
 Asia-Pacific Sustainable Home Decor Market | 2026-2036
Asia-Pacific Sustainable Home Decor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sustainable Home Decor Market Analytics
Digital twin modeling and AI-powered material lifecycle assessment is reconfiguring how sustainable home decor manufacturers prototype, source, and certify products across the Asia-Pacific region. Inter IKEA Holding B.V. leverages its captive supply of FSC-certified timber to control cost and traceability from forest to showroom. Nitori Holdings Co., Ltd. anchors its competitive position through vertical manufacturing scale across Japan and Southeast Asian assembly plants. Godrej Interio differentiates by specializing in bamboo-composite furniture engineered for humidity resistance in tropical Indian climates.
Sustainable home decor comprises furnishings, textiles, lighting, and accessories manufactured from renewable, recycled, or low-impact materials such as bamboo, organic cotton, hemp, and post-consumer recycled polymers, with certification thresholds typically requiring minimum recycled content of 30 percent or carbon footprint documentation per unit. These products serve residential and commercial interiors where environmental performance claims must withstand third-party audit for LEED, BREEAM, or equivalent green building compliance. Furniture commands the largest revenue pool in the product type dimension, while textiles from organic cotton and hemp represent the fastest-expanding material segment as dyeing processes shift to closed-loop water systems. Online retail channels are displacing department stores as the primary growth vector, though artisan markets sustain margin premiums through handcrafted provenance and direct maker relationships.
China's MEE enforces dual carbon goals that mandate embodied carbon disclosure for building materials entering commercial projects, while India's BIS develops standards for bamboo structural composites under its PLI scheme for sustainable manufacturing. Australia's Green Building Council and Japan's METI both incorporate interior material sourcing into broader green building certification frameworks, creating compliance pull-through for certified decor. Stakeholders must monitor how rapidly these regulatory regimes harmonize or fragment, as divergence in certification requirements between Beijing, New Delhi, and Tokyo will determine which suppliers can scale across borders without duplicative testing burden.
Market Dynamics
China's dual carbon goals and Australia's Green Building Council standards are tightening material compliance requirements across the Asia-Pacific sustainable home decor sector, forcing manufacturers to reconfigure sourcing and certification workflows.
Growth Catalysts
- Urban millennial purchasing power:Homeowners in Seoul and Sydney are expanding acquisitions of certified sustainable furnishings, creating concentrated demand pools in premium metropolitan markets.
- Bamboo structural composites:India's BIS standards development under the PLI scheme for sustainable manufacturing is accelerating domestic production capacity for humidity-resistant tropical furniture.
- Closed-loop water systems:Textile producers across the region are retrofitting dyeing facilities to meet organic cotton and hemp processing standards demanded by eco-conscious tier-one city consumers.
Market Restraints
- FSC-certified timber supply concentration:Captive forest-to-showroom supply chains limit independent manufacturer access to cost-competitive certified raw materials.
- Regulatory fragmentation:Divergence between China's MEE embodied carbon disclosure mandates, India's BIS bamboo standards, and Japan's METI green building frameworks creates duplicative testing burdens for cross-border suppliers.
- Petroleum-based polymer price volatility:Post-consumer recycled polymer feedstock costs fluctuate with crude oil benchmarks, compressing margins on certified recycled-content products.
Strategic Opportunities
- Tier-two Indian urbanization:Eco-conscious consumers in emerging metropolitan centers beyond Mumbai and Delhi represent underpenetrated demand for premium bamboo and organic cotton furnishings.
- Digital twin certification:AI-powered material lifecycle assessment tools are converging with blockchain traceability to create automated compliance documentation for LEED and BREEAM projects.
- Artisan market channel expansion:Direct maker relationships through curated online platforms are capturing margin premiums unavailable through conventional retail distribution.
Industry Challenges
- Third-party audit capacity constraints:Qualified auditors for FSC, LEED, and BREEAM certification are concentrated in major metropolitan hubs, creating bottlenecks for regional manufacturers.
- Humidity-resistant adhesive formulation:Tropical climate furniture engineering requires specialized R&D investment that exceeds standard furniture manufacturing capex thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sustainable Home Decor Market |
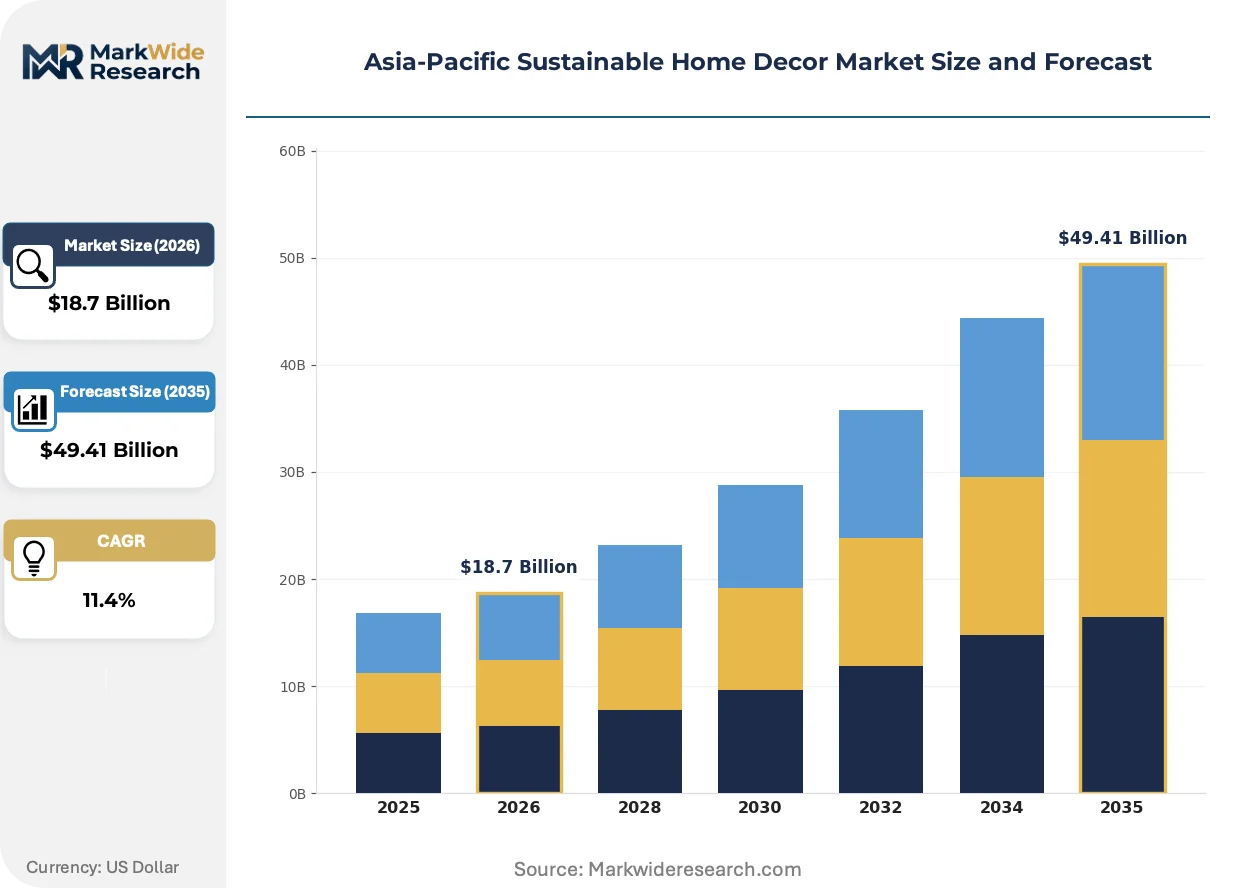
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furniture, Textiles, Lighting, Accessories Material: Bamboo, Recycled Plastic, Organic Cotton, Hemp Distribution Channel: Online Retail, Specialty Stores, Artisan Markets, Department Stores End User: Homeowners, Renters, Interior Designers, Eco-conscious Consumers |
| Companies Covered | Inter IKEA Holding B.V., Nitori Holdings Co., Ltd., Ashley Furniture Industries, Godrej Interio, Kuka Home, Shunde Kinwai Furniture Co., Ltd., Zuoyou Furniture Co., Ltd., Moso International, Okamura Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sustainable Home Decor Market Evolving Landscape
Digital infrastructure and material science advances are compressing product development cycles while fragmenting traditional retail channels across the Asia-Pacific sustainable home decor market.
AI-powered material lifecycle assessment platforms are rendering obsolete manual carbon footprint documentation for bamboo-composite and organic cotton products. Japanese and Australian furniture manufacturers are adopting these tools at accelerating rates to pre-certify prototypes before physical production. This capability is compressing time-to-market for climate-responsive furnishings while reducing compliance engineering headcount.
Australia's Green Building Council has incorporated interior material sourcing into broader certification frameworks, creating mandatory pull-through demand for documented sustainable decor in commercial projects. Property developers in Sydney and Melbourne now specify certified furnishings to secure green building ratings. This regulatory architecture is shifting procurement authority from interior designers to sustainability compliance officers.
Millennial homeowners are bypassing department stores in favor of curated online platforms that combine product visualization with maker provenance storytelling. Artisan markets in Seoul and tier-one Indian cities are sustaining premium pricing through direct consumer relationships that conventional retail cannot replicate. This channel disintermediation is most visible in textile categories where dyeing process transparency commands measurable price premiums.
Asia-Pacific Sustainable Home Decor Market Segmentation
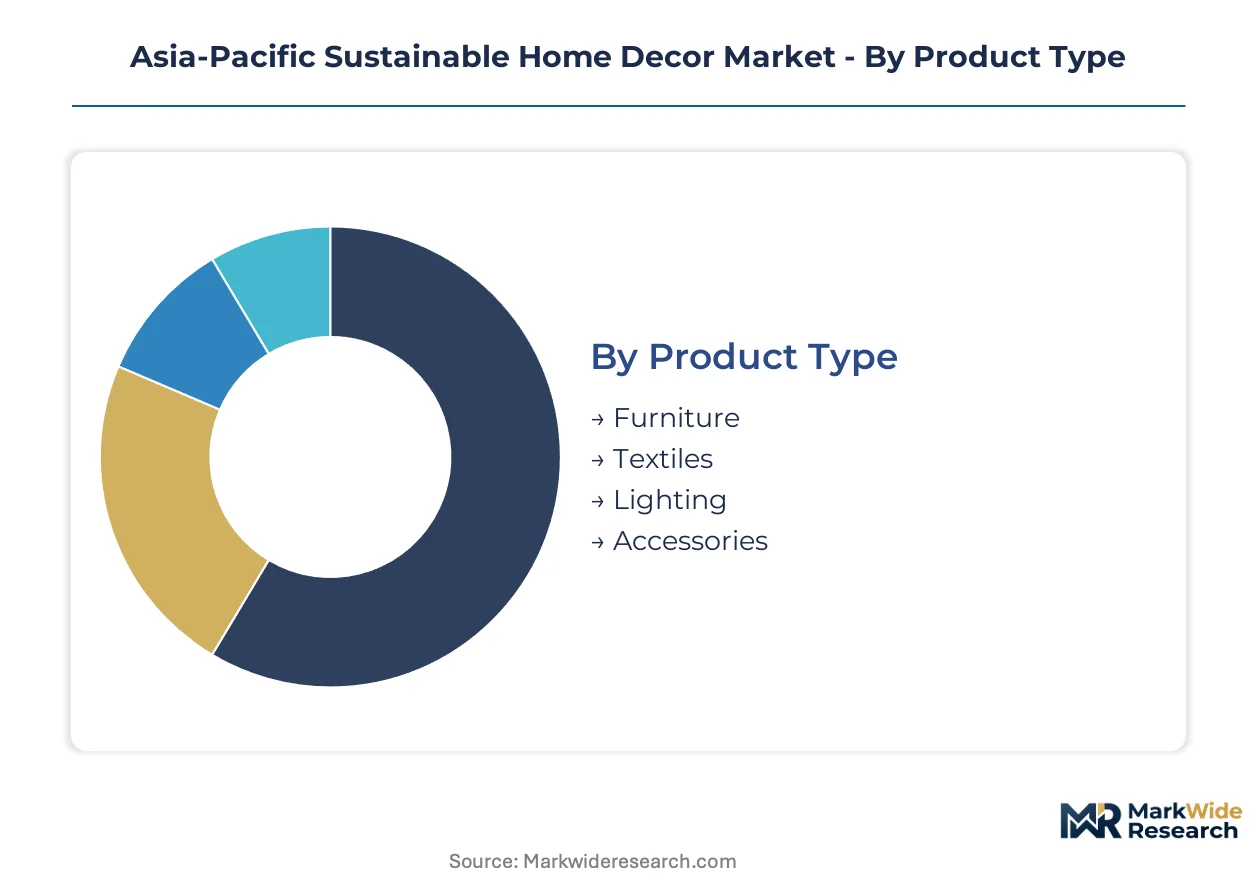
Segmentation in Asia-Pacific sustainable home decor reveals distinct service and support requirements across product categories. Furniture and textiles demand intensive installation and certification documentation, while accessories and lighting require minimal post-purchase engagement.
Product Type:
After-sales service intensity varies dramatically across product categories, with furniture requiring assembly coordination and textile producers managing dye-process certification queries.
- Furniture:Bamboo-composite and certified timber pieces require humidity-resistant engineering validation and FSC chain-of-custody documentation. Seoul and Sydney homeowners drive concentrated demand for modular systems with carbon footprint disclosure. Installation complexity and warranty claims consume disproportionate customer service resources relative to unit value.
- Textiles:Organic cotton and hemp fabrics demand closed-loop water system certification and third-party dye safety verification. Tier-one Indian cities exhibit the steepest adoption curve as eco-conscious consumers scrutinize chemical-free processing claims. Returns management centers on texture expectations versus actual hand-feel discrepancies.
- Lighting:LED fixtures with recycled polymer housings require minimal post-sale support beyond electrical safety compliance.
- Accessories:Decorative objects from post-consumer materials carry straightforward replacement policies with limited technical consultation needs.
Furniture holds the largest share; momentum sits with textiles expanding most quickly.
Material:
Cost tier stratification separates premium certified inputs from economy-grade alternatives, with bamboo and organic cotton commanding price premiums over recycled polymers.
- Bamboo:Structural composites engineered for tropical humidity resistance require specialized adhesive R&D investment. India's BIS standards development under the PLI scheme accelerates domestic production capacity for climate-responsive furniture. Godrej Interio anchors its competitive position through proprietary composite formulations.
- Organic Cotton:Closed-loop water system processing demands capital-intensive facility retrofits that smaller textile producers struggle to finance. Australia's Green Building Council standards create mandatory specification pull-through in commercial Sydney and Melbourne projects. Certification audit costs compress margins for mid-scale weavers.
- Recycled Plastic:Post-consumer polymer feedstock costs fluctuate with crude oil benchmarks, creating margin volatility for certified-content products.
- Hemp:Processing infrastructure scarcity limits regional supply scale despite favorable carbon sequestration credentials.
Bamboo holds the largest share; organic cotton is climbing the fastest.
Distribution Channel:
Volume concentration shifts toward direct-to-consumer platforms as department store foot traffic declines across metropolitan Asia-Pacific markets.
- Online Retail:Curated platforms combining product visualization with maker provenance storytelling capture millennial homeowners bypassing conventional retail. Seoul and tier-one Indian cities sustain premium pricing through transparency features unavailable in physical channels. Returns logistics complexity increases with furniture category penetration.
- Artisan Markets:Direct maker relationships in curated physical and digital venues command margin premiums through handcrafted provenance documentation. Sydney and Melbourne consumers pay measurable premiums for dyeing process transparency in textile categories. Scale limitations constrain national brand emergence.
- Specialty Stores:Certified sustainable showrooms in premium mall locations face rent pressure from online channel displacement.
- Department Stores:Legacy retail footprints in Japan and Australia retrench as sustainability compliance documentation requirements exceed their procurement capabilities.
Online retail holds the largest share; artisan markets are gaining share fastest.
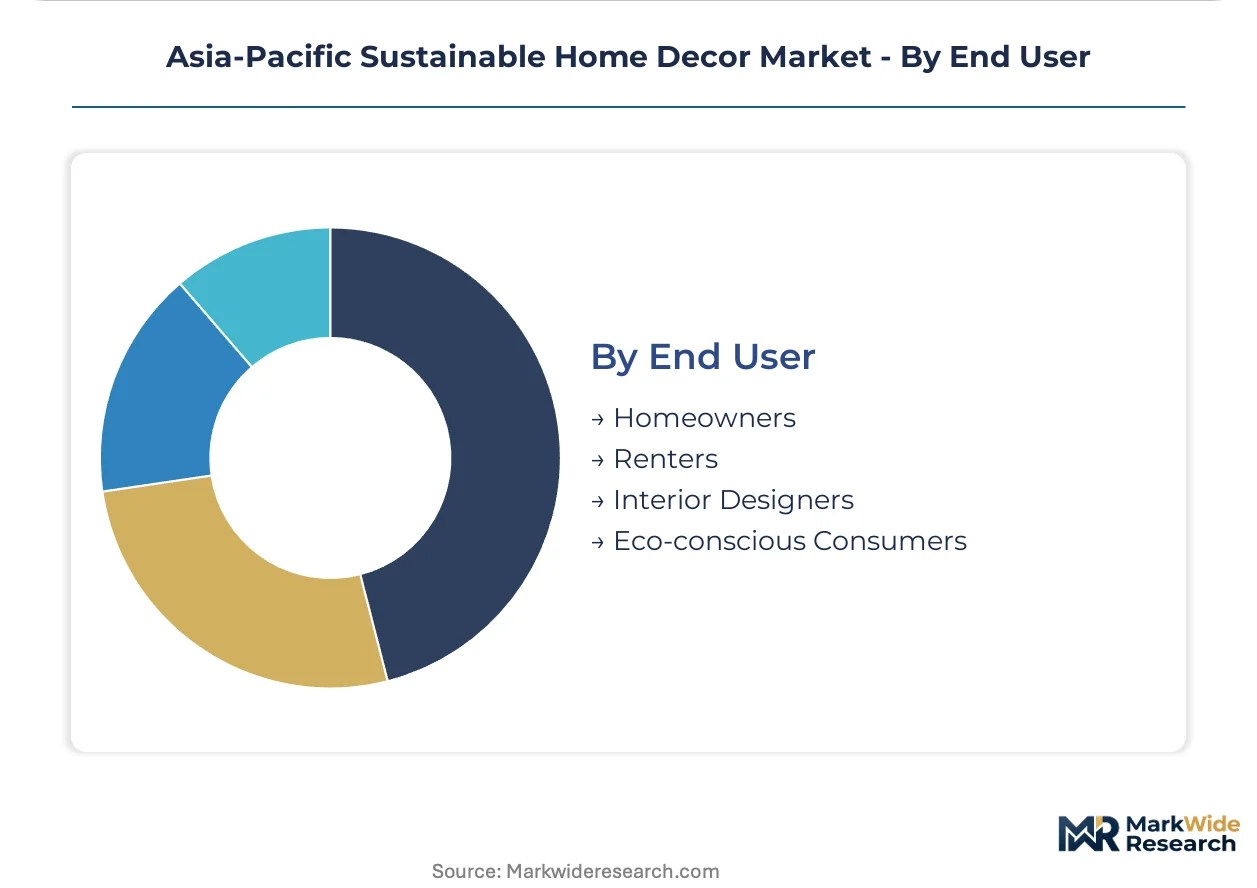
End User:
Customer type determines specification authority and price sensitivity, with interior designers and eco-conscious consumers driving premium segment growth.
- Eco-conscious Consumers:Tier-one city residents in India and Australia demand carbon footprint documentation and third-party audit trails for all purchase categories. LEED and BREEAM compliance requirements in commercial projects extend to residential specification behavior. Price elasticity remains low for verified sustainable claims.
- Interior Designers:Procurement authority in Sydney and Melbourne commercial projects now rests with sustainability compliance officers rather than aesthetic specialists. Australia's Green Building Council standards mandate documented interior material sourcing for green building ratings. Specification liability drives preference for pre-certified product lines.
- Homeowners:Seoul's urban millennial demographic expands certified sustainable furnishing acquisitions with concentrated metropolitan demand.
- Renters:Temporary residence patterns favor lower-investment accessories and textiles over permanent furniture commitments.
Homeowners hold the largest share; eco-conscious consumers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports bamboo-composite components to Indian furniture assemblers under the PLI scheme for sustainable manufacturing, while Australian developers import certified timber furnishings to satisfy Green Building Council interior material mandates.
China
Urban millennial homeowners in Shanghai and Beijing drive concentrated demand for modular certified timber systems. The MEE enforces dual carbon goals mandating embodied carbon disclosure for building materials entering commercial projects. The Yangtze River Delta hosts the densest cluster of FSC-certified timber processing facilities supplying showroom-ready furnishings.
India
Eco-conscious consumers in Mumbai and Delhi propel premium bamboo and organic cotton adoption at measurable rates. BIS develops standards for bamboo structural composites under the PLI scheme for sustainable manufacturing. Godrej Interio anchors proprietary humidity-resistant composite production in Maharashtra for tropical climate deployment.
Australia
Sydney and Melbourne property developers specify certified sustainable furnishings to secure green building ratings. The Green Building Council incorporates interior material sourcing into mandatory certification frameworks. Sustainability compliance officers now hold procurement authority over interior designers in commercial projects across New South Wales and Victoria.
Japan
METI integrates interior material sourcing into broader green building certification frameworks. Nitori Holdings Co., Ltd. controls vertical manufacturing scale across domestic and Southeast Asian assembly plants. The Kansai region concentrates humidity-resistant furniture engineering R&D for tropical export markets.
South Korea
Seoul's urban millennial demographic expands certified sustainable furnishing acquisitions with metropolitan concentration. The MFDS regulates chemical safety in textile processing facilities serving home decor supply chains. Gyeonggi Province clusters closed-loop water system retrofits for organic cotton and hemp dyeing operations.
Asia-Pacific Sustainable Home Decor Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base spans captive forest-to-showroom supply chains, vertical manufacturing scale operators, and proprietary composite formulators. Three strategic archetypes dominate: timber-integrated multinationals, bamboo-composite regional specialists, and curated artisan platform operators. Competitive moves concentrate on geographic expansion through Southeast Asian assembly plants and certification pre-engineering through digital twin adoption.
Among timber-integrated multinationals, Inter IKEA Holding B.V. and Nitori Holdings Co., Ltd. exemplify channel control through captive raw material sourcing. Godrej Interio occupies a position within the bamboo-composite specialist tier, anchoring proprietary formulations for tropical climate resistance. These three entities represent distinct competitive vectors: multinational scale, regional manufacturing depth, and material science specialization.
| Leading Market Players |
|---|
| Inter IKEA Holding B.V. |
| Nitori Holdings Co., Ltd. |
| Ashley Furniture Industries |
| Godrej Interio |
| Kuka Home |
| Shunde Kinwai Furniture Co., Ltd. |
| Zuoyou Furniture Co., Ltd. |
| Moso International |
| Okamura Corporation |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor cost dynamics concentrate FSC-certified timber supply advantages among captive forest-to-showroom operators while forcing independent manufacturers toward price differentiation through certification tiering. This logistics concentration amplifies margin pressure on non-integrated players sourcing certified raw materials from dispersed Southeast Asian assembly nodes.
Pricing Analysis
Digital twin-enabled certification pricing gaps separate current-generation AI-validated products from prior-generation manual audit documentation and emerging blockchain-traceability next-generation offerings. Three-tier pricing structure across premium certified-timber, standard bamboo-composite, and economy recycled-polymer levels stratifies the market. Price differentiation rests on FSC chain-of-custody grade and geographic delivery cost from Yangtze Delta processing hubs. Cost compression in the recycled-polymer tier intensifies because petroleum feedstock volatility tracks crude benchmarks. Eco-conscious consumers in Seoul and Sydney exhibit lowest price sensitivity; tier-two Indian renters show highest elasticity.
Supply Chain Analysis
Export-control regime restrictions on advanced adhesive formulation technology limit humidity-resistant composite flows from Japanese R&D centers to Indian assembly plants under BIS PLI scheme compliance requirements. Geographic supply concentration centers on China for FSC-certified timber processing, India for bamboo structural composite manufacturing, and Vietnam for textile dyeing facility retrofits. Raw material dependencies draw from Indonesian bamboo plantations, Australian certified hardwood estates, and post-consumer polymer collection networks across Japan. Single-source vulnerability in FSC-certified timber auditing capacity creates bottleneck risk. Distribution runs through curated online platforms displacing department store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as urban millennial household formation in Seoul, Sydney, and tier-one Indian cities rebounds from post-pandemic housing affordability constraints. The recovery trajectory hinges on mortgage rate stabilization and green building certification mandate expansion.
For Market Incumbents: Insulate captive timber supply advantages through backward integration into Indonesian and Australian plantation assets before independent competitors secure alternative FSC-certified feedstock. Accelerate digital twin certification pre-engineering investment to compress compliance documentation timelines below competitor reach. Threat of AI-powered lifecycle assessment platform commoditization demands proprietary data moat construction around tropical climate engineering parameters.
For New Entrants and Emerging Players: Tier-two Indian urbanization beyond Mumbai and Delhi represents the most penetrable white-space geography for premium bamboo-composite furnishings. Artisan market channel fragmentation in curated online platforms offers accessible entry with lower capital requirements than conventional retail distribution. Target direct-to-consumer provenance storytelling as the primary go-to-market angle, leveraging dye-process transparency premiums unavailable through legacy procurement relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bamboo-composite regional specialists with proprietary humidity-resistant formulations over timber-integrated multinationals facing raw material cost volatility. Long-term viability over the projection horizon centers on certification automation capabilities and Southeast Asian assembly plant network density. Acquisition target archetype: mid-scale operators with BIS standards compliance progress and underutilized closed-loop water system infrastructure. The signal to watch is harmonization velocity between China's MEE embodied carbon mandates and Australia's Green Building Council interior material frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Certification Deployment | AI-powered lifecycle assessment compresses LEED documentation timelines for Sydney commercial developers. |
| Backward Integration into Plantations | Captive FSC-certified timber supply secures cost stability against Yangtze Delta logistics volatility. |
| Artisan Platform Channel Expansion | Curated online provenance storytelling captures margin premiums from Seoul millennial homeowners. |
| Closed-Loop Water System Retrofit | Organic cotton dyeing compliance meets Australia's Green Building Council textile specifications. |
| Bamboo Composite R&D Investment | Humidity-resistant adhesive formulations address tropical climate demand from Mumbai and Delhi. |
Research Methodology
Cross-validation between primary interviews with sustainable furniture manufacturing executives, textile processing facility managers, green building certification auditors, and online retail platform operators anchors the qualitative findings against secondary validation from customs trade records, BIS standards development filings, and Green Building Council certification databases. Bottom-up demand modeling across product type, material, distribution channel, and end user dimensions converges with top-down macroeconomic anchoring.
Calibration against historical certification adoption curves and regulatory mandate implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include furniture versus textile versus lighting product categories, bamboo versus organic cotton versus recycled polymer material tiers, online retail versus artisan market versus specialty store channels, and eco-conscious consumer versus interior designer versus homeowner end user archetypes. CAGRs derive from regression analysis against green building certification penetration rates and urban millennial household formation data.
Macroeconomic conditions sit as an overlay; deviation in residential construction permitting velocity and mortgage rate trajectories would shift the trajectory. Forecasts reflect assumptions regarding regulatory harmonization pace between Beijing, New Delhi, and Tokyo. Material shifts in FSC-certified timber supply concentration or abrupt petroleum feedstock price dislocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Global Homeware Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
United Arab Emirates Interior Design Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
US Bamboos Market
Homecare and Decor
Middle East Revolving Doors Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Builders and Cabinet Hardware Market
Homecare and Decor
Asia-Pacific Wall Covering Market
Homecare and Decor
North America Sustainable Home Decor Market
Homecare and Decor
India Interior Design Market
Homecare and Decor
United Kingdom Resilient Floor Covering Market
Homecare and Decor
Interior Design Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
Balcony Accessories Market
Homecare and Decor
India Wallpapers Market