
 UK Sustainable Office Furniture Market | 2026-2036
UK Sustainable Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
UK Sustainable Office Furniture Market Analytics
Capital-intensity divergence between large-scale manufacturers and boutique craft producers is collapsing as modular fabrication systems democratize precision manufacturing. Lee & Plumpton leverages its Midlands production base to control lead times on reclaimed timber collections. Flexiform Business Furniture anchors its position through NHS and government framework contracts requiring full chain-of-custody documentation. Verve Workspace differentiates via circular-economy leasing models that retain material ownership.
UK sustainable office furniture comprises workstation, seating, and storage systems manufactured with recycled, rapidly renewable, or cradle-to-cradle certified materials meeting BSI EN standards for commercial durability. Products typically incorporate minimum 70% recycled content, low-VOC finishes, and disassembly-ready joinery to support end-of-life material recovery. Chairs and desks dominate current procurement volumes, while modular systems capture the fastest expansion as hybrid-work reconfigurations accelerate refresh cycles. Reclaimed wood and recycled metal command premium positioning against biodegradable plastics, where cost-performance gaps limit corporate adoption at scale.
BSI Kitemark and FSC chain-of-custody certification operate as baseline market-access requirements, while UK Building Regulations Part L and proposed embodied-carbon reporting rules tighten material disclosure obligations. The Environment Agency's waste hierarchy enforcement and extended producer responsibility consultations further pressure suppliers to redesign for disassembly. Stakeholders must monitor whether upcoming UK Timber Procurement Policy amendments will restrict tropical hardwood alternatives and redirect specification toward domestic reclaimed sources.
Market Dynamics
Modular fabrication systems are collapsing the historical capital-intensity gap between large-scale manufacturers and boutique craft producers, redistributing competitive advantage toward supply-chain control and circular-economy infrastructure.
Growth Catalysts
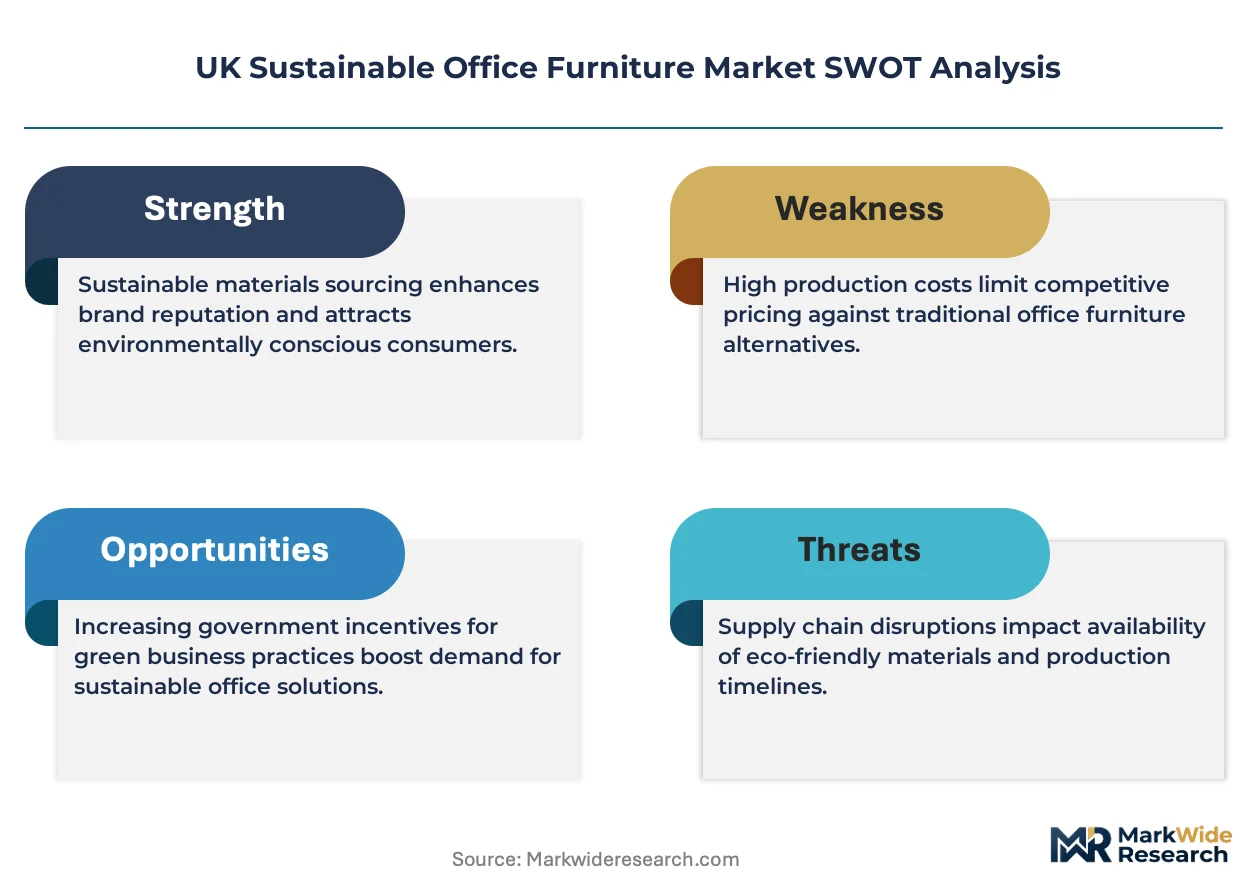
- BSI Kitemark Certification:Mandatory baseline for NHS and government framework contracts, forcing suppliers to upgrade material traceability systems. Public procurement now routes exclusively through certified vendors.
- Corporate B Corp Certification:Certified corporations in London and Manchester now mandate sustainable furniture fit-outs, creating concentrated demand clusters in England's commercial hubs.
- Reclaimed Timber Processing:Midlands-based production facilities leverage domestic reclaimed wood streams, compressing lead times against imported virgin materials.
Market Restraints
- Biodegradable Plastic Cost-Performance Gap:Corporate procurement teams reject biodegradable alternatives due to durability failures in high-use commercial environments, limiting material substitution.
- Extended Producer Responsibility Consultations:Pending Environment Agency rules on end-of-life furniture recovery impose unresolved compliance costs on design and logistics.
- Tropical Hardwood Supply Uncertainty:Anticipated UK Timber Procurement Policy amendments threaten to disqualify non-domestic reclaimed sources, constricting material options.
Strategic Opportunities
- Circular-Economy Leasing Models:Retained material ownership contracts allow suppliers to capture multiple lifecycle revenues while meeting corporate ESG reporting requirements.
- Hybrid-Work Reconfiguration Cycles:Accelerated refresh demand for modular workstation systems creates recurring revenue streams distinct from traditional capital purchase cycles.
- Embodied-Carbon Reporting Rules:Proposed Building Regulations amendments will mandate material disclosure, advantaging early movers with established chain-of-custody documentation.
Industry Challenges
- FSC Chain-of-Custody Documentation:Full documentation requirements for government contracts strain supplier administrative capacity and audit readiness.
- Disassembly-Ready Joinery Engineering:Design-for-recovery specifications demand retooling of production lines and retraining of craft labor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Sustainable Office Furniture Market |
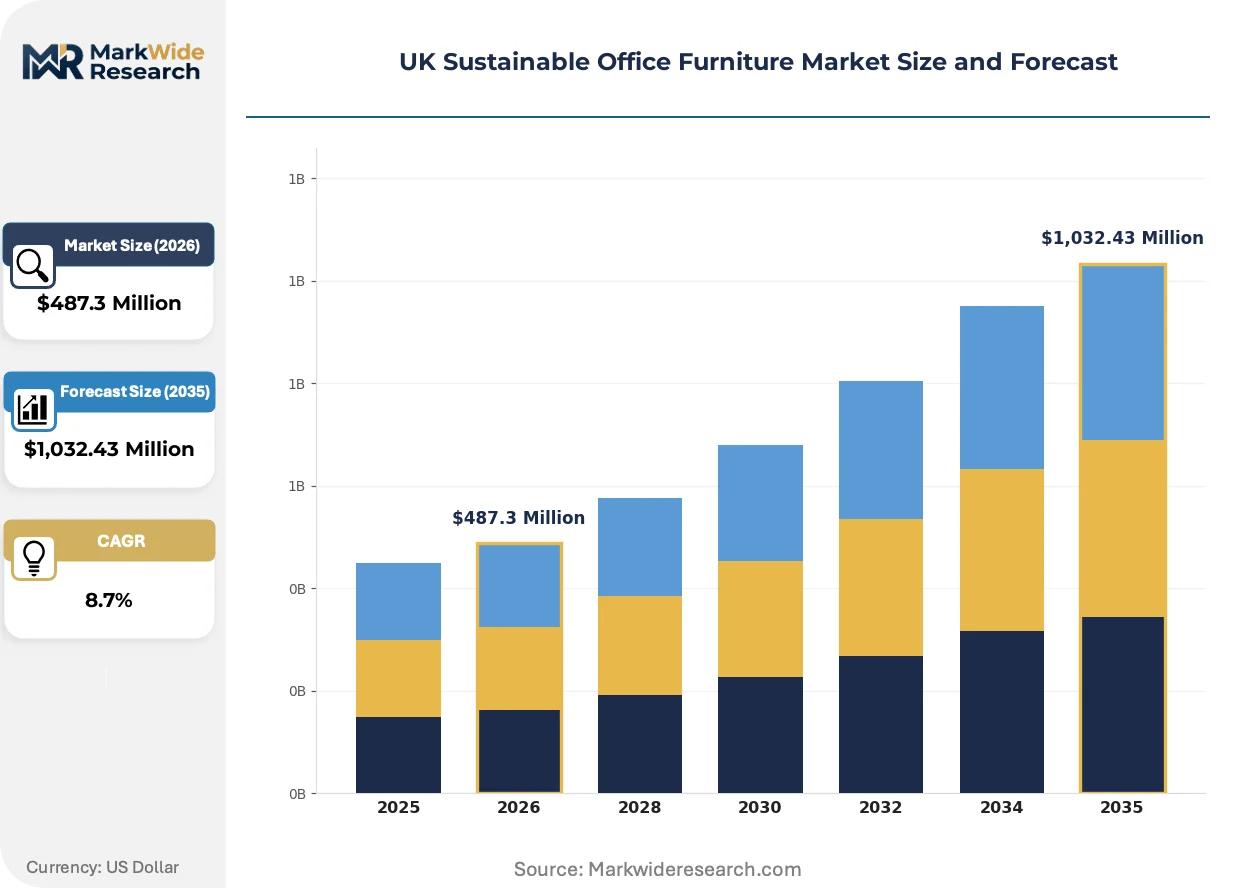
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Tables, Storage Units Material: Recycled Metal, Bamboo, Reclaimed Wood, Biodegradable Plastics Design Style: Minimalist, Ergonomic, Modular, Vintage End User: Corporations, Startups, Educational Institutions, Nonprofits |
| Companies Covered | Lee & Plumpton, Office Reality, Flexiform Business Furniture, Diamond Business Interiors, Hunts Office, Verve Workspace, Metric Office Furniture, Tangent Furniture, Frem, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Sustainable Office Furniture Market Evolving Landscape
Three distinct vectors are restructuring how sustainable office furniture is specified, financed, and recovered: fabrication technology convergence, tightening material disclosure mandates, and procurement model evolution toward material-as-a-service.
Digital twin-enabled modular systems are decomposing traditional fixed-floorplate office configurations. Corporate real estate teams in Manchester and Birmingham deploy sensor-integrated workstation pods that reconfigure without tools. This technology is decomposing the five-to-seven-year refresh cycle into continuous incremental adaptation, compressing capital planning horizons and shifting supplier relationships toward ongoing service partnerships.
UK Building Regulations Part L amendments are tightening energy efficiency and embodied-carbon thresholds for commercial fit-outs. Suppliers must now submit verified material origin documentation to qualify for planning permission in London and major regional centers. NHS procurement frameworks have responded by elevating chain-of-custody certification from preferred to mandatory status, disqualifying vendors without FSC or PEFC documentation.
Corporate buyers are consolidating vendor relationships around circular-economy service contracts that retain supplier ownership of materials. Facilities management teams in England's B Corp-certified corporations now specify performance-based agreements covering furniture provision, maintenance, and end-of-life recovery. This model is most visible in London's financial and professional services sectors, where ESG reporting requirements drive preference for verified material circularity over upfront capital expenditure minimization.
UK Sustainable Office Furniture Market Segmentation
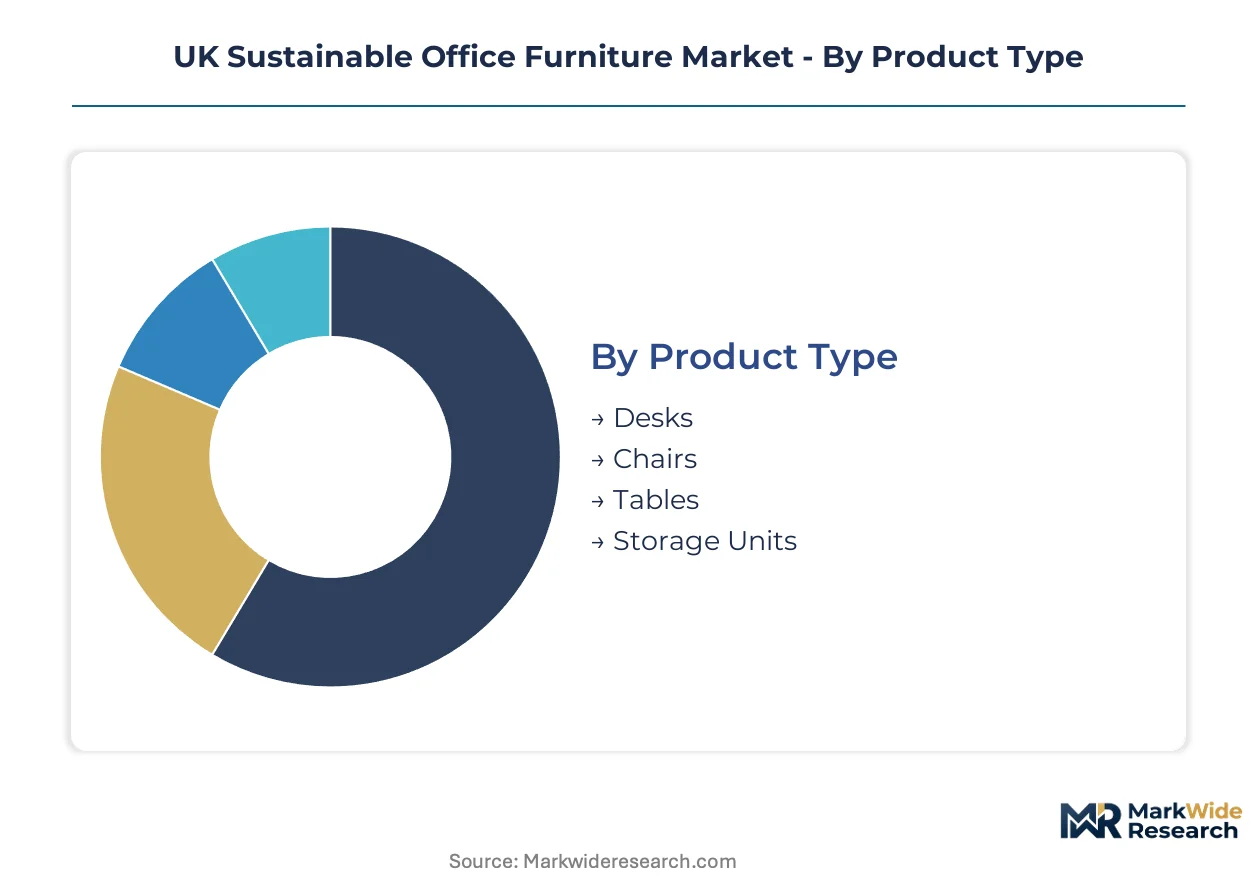
Procurement teams in England's commercial hubs route distinct product categories through framework contracts, direct manufacturer relationships, and circular-economy leasing channels. Understanding these channel-segment pairings clarifies where BSI Kitemark certification and FSC documentation create mandatory access gates versus discretionary positioning advantages.
Product Type:
Desks and chairs flow predominantly through NHS and government framework contracts requiring full chain-of-custody documentation, while tables and storage units see heavier direct procurement by corporate real estate teams in London and Manchester.
- Desks:Workstation systems incorporating minimum 70% recycled content and disassembly-ready joinery dominate public sector procurement volumes. NHS frameworks in England mandate BSI EN durability standards and low-VOC finishes, compressing supplier qualification to certified vendors exclusively.
- Chairs:Ergonomic seating with cradle-to-cradle certified materials captures concentrated demand from B Corp-certified corporations in London's financial district. Hybrid-work reconfigurations accelerate refresh cycles beyond traditional five-to-seven-year replacement horizons.
- Tables:Conference and collaborative surfaces manufactured from reclaimed timber collections serve boutique craft producers and mid-scale manufacturers equally through modular fabrication systems.
- Storage Units:Filing and archival systems with recycled metal frames face slower adoption due to extended replacement cycles in legacy office estates.
By volume, desks lead procurement through public frameworks. By growth pace, chairs are climbing the fastest on corporate ESG mandates.
Material:
Cost tier stratification separates premium reclaimed sources from standard recycled streams, with biodegradable alternatives stranded in experimental positioning due to durability failures.
- Recycled Metal:Steel and aluminum frames with verified post-consumer content anchor durability specifications for high-use commercial environments. Midlands-based production facilities compress lead times against imported virgin materials through domestic supply chain control.
- Reclaimed Wood:Timber recovered from demolished industrial structures commands premium positioning in London fit-outs where embodied-carbon reporting rules tighten material disclosure obligations. Lee & Plumpton leverages regional processing capacity to outpace tropical hardwood alternatives facing UK Timber Procurement Policy uncertainty.
- Bamboo:Rapidly renewable grass-based materials serve sustainability-focused startups seeking rapid scalability without FSC documentation burdens.
- Biodegradable Plastics:Experimental polymers derived from agricultural waste struggle with cost-performance gaps that limit corporate adoption at commercial scale.
Reclaimed wood and recycled metal together dominate value capture, while bamboo gains share fastest among venture-backed startups prioritizing speed over certification depth.
Design Style:
Application context determines specification: modular systems serve hybrid-work reconfiguration demands, while vintage styling targets nonprofit budgets and heritage-sensitive public sector fit-outs.
- Modular:Sensor-integrated workstation pods reconfigure without tools, decomposing fixed-floorplate offices into adaptive environments. Corporate real estate teams in Manchester and Birmingham deploy these systems for continuous incremental adaptation rather than cyclical capital refresh.
- Ergonomic:Biomechanically optimized seating and height-adjustable surfaces address occupational health requirements in NHS and government contracts. Flexiform Business Furniture anchors market position through framework penetration here.
- Minimalist:Reduced-material aesthetic specifications appeal to B Corp-certified corporations seeking visible sustainability signaling for ESG reporting.
- Vintage:Refurbished and reclaimed aesthetic pieces serve nonprofit budgets and heritage-sensitive public sector fit-outs where capital constraints outweigh performance optimization.
Modular systems command the steepest expansion trajectory on hybrid-work normalization, while ergonomic specifications hold the largest installed base through mandatory procurement frameworks.
End User:
Customer type determines contract structure: corporations consolidate around circular-economy leasing, while educational institutions remain tethered to capital purchase cycles with extended depreciation horizons.
- Corporations:B Corp-certified entities in London and Manchester mandate sustainable furniture fit-outs through performance-based service contracts. Verve Workspace's retained material ownership model captures multiple lifecycle revenues while meeting verified material circularity requirements.
- Educational Institutions:Universities and colleges in England's major commercial hubs specify durable, low-maintenance systems with 15-20 year replacement horizons, slowing refresh cycle velocity.
- Startups:Venture-backed firms prioritize speed-to-occupancy over certification depth, routing procurement through direct manufacturer relationships rather than framework compliance.
- Nonprofits:Budget-constrained organizations favor vintage and refurbished sourcing, accepting aesthetic inconsistency for cost minimization.
Corporations generate the highest revenue per square foot through service contract structures. Startups are expanding most quickly as venture funding concentrates in London's fintech and climate-tech clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the UK diverge sharply between England's commercial hubs and the devolved nations, with procurement frameworks and certification requirements driving distinct specification behaviors.
London and Southeast England
B Corp-certified financial and professional services firms concentrate demand for cradle-to-cradle certified seating and modular workstation systems. UK Building Regulations Part L enforcement tightens embodied-carbon disclosure for commercial fit-outs. The City of London and Canary Wharf clusters anchor circular-economy leasing adoption through performance-based service contracts.
Midlands
Reclaimed timber processing facilities leverage domestic supply chains to compress lead times against imported virgin materials. BSI Kitemark certification operates as mandatory baseline for NHS procurement frameworks routing through Birmingham and Nottingham. Lee & Plumpton anchors regional production capacity for certified sustainable collections.
North England
Manchester's corporate real estate teams deploy sensor-integrated modular pods for hybrid-work reconfigurations. Extended producer responsibility consultations from the Environment Agency pressure suppliers to redesign for disassembly. The Greater Manchester commercial hub drives fastest growth in circular-economy service contracts outside London.
Scotland
Public sector frameworks in Edinburgh and Glasgow mandate FSC chain-of-custody documentation for government fit-outs. Scottish procurement regulations align with UK Timber Procurement Policy uncertainty, redirecting specification toward domestic reclaimed sources. Highlands timber recovery operations feed low-carbon material streams to central belt manufacturing.
Wales
Smaller-scale commercial fit-outs in Cardiff and Swansea prioritize cost-conscious sustainable sourcing over premium certification depth. Welsh government procurement frameworks adopt BSI EN durability standards with lagged timing versus English counterparts. Regional craft producers exploit modular fabrication convergence to compete on lead times.
UK Sustainable Office Furniture Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with competitive advantage redistributing toward supply-chain control and circular-economy infrastructure rather than scale alone. The market structure reflects capital-intensity collapse from modular fabrication systems, enabling mid-scale producers to match precision manufacturing capabilities. Three archetypes dominate: framework-anchored public sector suppliers, circular-economy service providers, and reclaimed material specialists. Dominant competitive moves include circular-economy leasing model expansion and Midlands-based production capacity consolidation.
Among framework-anchored suppliers, Flexiform Business Furniture exemplifies the public sector penetration archetype through NHS and government contract concentration. Verve Workspace occupies a position within the circular-economy service tier, retaining material ownership through leasing structures. Lee & Plumpton represents the reclaimed material specialist archetype, leveraging regional processing capacity for certified timber collections.
| Leading Market Players |
|---|
| Lee & Plumpton |
| Office Reality |
| Flexiform Business Furniture |
| Diamond Business Interiors |
| Hunts Office |
| Verve Workspace |
| Metric Office Furniture |
| Tangent Furniture |
| Frem |
| Others |
Value Network & Pricing Analysis
Four-to-six-week lead-time compression for BSI Kitemark-certified collections redistributes pricing power toward Midlands-based producers with captive reclaimed timber streams, while spot-market buyers absorb volatility from tropical hardwood supply uncertainty.
Pricing Analysis
Long-term framework contracts dominate public sector procurement, locking in volume commitments across 3-5 year horizons with price escalation clauses tied to FSC-certified material indices. Three-tier pricing structure across premium reclaimed, standard recycled-content, and economy-grade alternatives separates certified vendors from uncertified competitors. Pricing pressure stems from biodegradable plastic durability failures that force procurement teams back to higher-cost metal and timber specifications. Educational institutions exhibit highest price sensitivity due to extended 15-20 year depreciation cycles, while B Corp-certified corporations absorb premium positioning for ESG reporting compliance.
Supply Chain Analysis
The UK and Ireland anchor reclaimed timber processing through Midlands-based facilities that compress lead times against imported virgin alternatives. Steel and aluminum feedstock draws from domestic scrap recovery networks and European mill supply, while bamboo sourcing rests on Southeast Asian plantation streams facing UK Timber Procurement Policy uncertainty. Single-source vulnerability concentrates in FSC chain-of-custody documentation providers, where audit capacity constraints create qualification bottlenecks. Distribution runs through NHS and government framework contracts for institutional buyers, direct manufacturer relationships for corporate real estate teams, and circular-economy leasing channels for ESG-mandated fit-outs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent suppliers face substitution pressure from modular fabrication systems that collapse capital barriers for boutique craft producers, eroding scale-based competitive moats.
For Market Incumbents: Compound framework contract penetration by embedding circular-economy leasing clauses into NHS and government procurement vehicles before pending Environment Agency extended producer responsibility rules reshape compliance costs. Deepen backward integration into Midlands reclaimed timber processing to outpace tropical hardwood alternatives facing UK Timber Procurement Policy restriction. For New Entrants and Emerging Players: Circular-economy service-layer gaps in Wales and smaller English regional centers offer white-space entry points where incumbent coverage remains thin. Target Cardiff and Swansea commercial fit-outs with cost-optimized sustainable sourcing that lags premium certification depth. Deploy direct manufacturer relationships bypassing framework compliance burdens to accelerate speed-to-occupancy for venture-backed startups. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified furniture conglomerates with under-monetized sustainable product lines and dormant FSC certification assets. Five-to-ten year viability hinges on circular-economy infrastructure ownership rather than manufacturing scale alone. Monitor UK Timber Procurement Policy amendment timing as inflection indicator for reclaimed timber valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Circular-Economy Leasing Model Expansion | Retained material ownership captures multiple lifecycle revenues while satisfying B Corp ESG reporting mandates. |
| Midlands Reclaimed Timber Capacity Consolidation | Regional processing control compresses lead times against tropical hardwood alternatives facing procurement policy uncertainty. |
| BSI Kitemark Certification Investment | Mandatory baseline qualification unlocks NHS and government framework contract access. |
| Modular Fabrication System Deployment | Precision manufacturing democratization enables mid-scale producers to match large-scale capabilities. |
| Disassembly-Ready Joinery Engineering | Design-for-recovery specifications preempt Environment Agency extended producer responsibility compliance requirements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with procurement directors at B Corp-certified corporations, NHS framework contract managers, facilities management leads, and reclaimed timber processors; and secondary validation against BSI certification databases, UK Building Regulations Part L documentation, Environment Agency consultation records, and trade flow data from HM Revenue and Customs. Bottom-up volume estimates from product-category shipment analysis triangulated against top-down market sizing from framework contract value disclosures.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, material certification tier, end-user segment, and regional procurement hub. CAGRs derived from historical framework contract renewal patterns and corporate real estate refresh cycle compression. Industry-specific inputs incorporated B Corp certification growth curves, hybrid-work reconfiguration frequency, and embodied-carbon reporting rule implementation timelines.
Forecasts assume regulatory continuity in UK Building Regulations Part L and Environment Agency extended producer responsibility consultations; material policy shifts would require re-modeling. Recalibration cycles align with UK Timber Procurement Policy amendments and BSI Kitemark standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
North America Smart Furniture Market
Furniture
India Upholstered Furniture Market
Furniture
GCC Smart Furniture Market
Furniture
Europe School Furniture Market
Furniture
Europe Sustainable Mattress Market
Furniture
Kids and Nursery Furniture Market
Furniture
School Furniture Market
Furniture
India Furniture Market
Furniture
North America Home Furniture Market
Furniture
Europe Upholstered Furniture Market
Furniture
China Home Furniture Market
Furniture
Entryway Furniture Market
Furniture
Laminated Door Market
Furniture
Eco-Friendly Furniture Market
Furniture
Russia Home Furniture Market
Furniture
GCC Multifunctional Furniture Market