
 North America RTA Furniture Market | 2026-2036
North America RTA Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
North America RTA Furniture Market Insights
Buyer concentration among millennial and Gen Z first-time homeowners is restructuring how RTA furniture reaches end consumers, with digital-native purchasers favoring direct-to-door delivery over traditional showroom visits. IKEA leverages its global supply network to dominate price-accessible Scandinavian design across the continent. Sauder Woodworking anchors American manufacturing heritage through its Ohio-based production complex. BESTAR specializes in Canadian-engineered office and bedroom systems for North American commercial clients.
Ready-to-assemble furniture comprises flat-packed components shipped with hardware and instructions for consumer-level construction, typically using engineered wood panels with cam-lock fasteners, dowel joints, or slide-together metal brackets designed to reduce shipping volume and last-mile logistics cost. The product category serves residential, commercial, and institutional buyers seeking affordable, modular furnishings with minimal professional installation. Bedroom and office furniture segments lead volume, reflecting work-from-home permanence and urban space constraints, while metal and wood material splits reveal divergent margin pools with metal frames commanding durability premiums and engineered wood sustaining mass-market penetration. Online retail channels capture accelerating share as augmented reality tools reduce purchase uncertainty for spatially sensitive categories.
The EPA oversees composite wood formaldehyde emissions under TSCA Title VI, directly constraining panel sourcing and finishing processes for manufacturers serving the United States market. Health Canada and the Canadian Standards Association maintain parallel indoor air quality benchmarks that shape cross-border product compliance strategies. Stakeholders must monitor evolving extended producer responsibility frameworks in California and Ontario that threaten to impose end-of-life collection obligations on RTA brands.
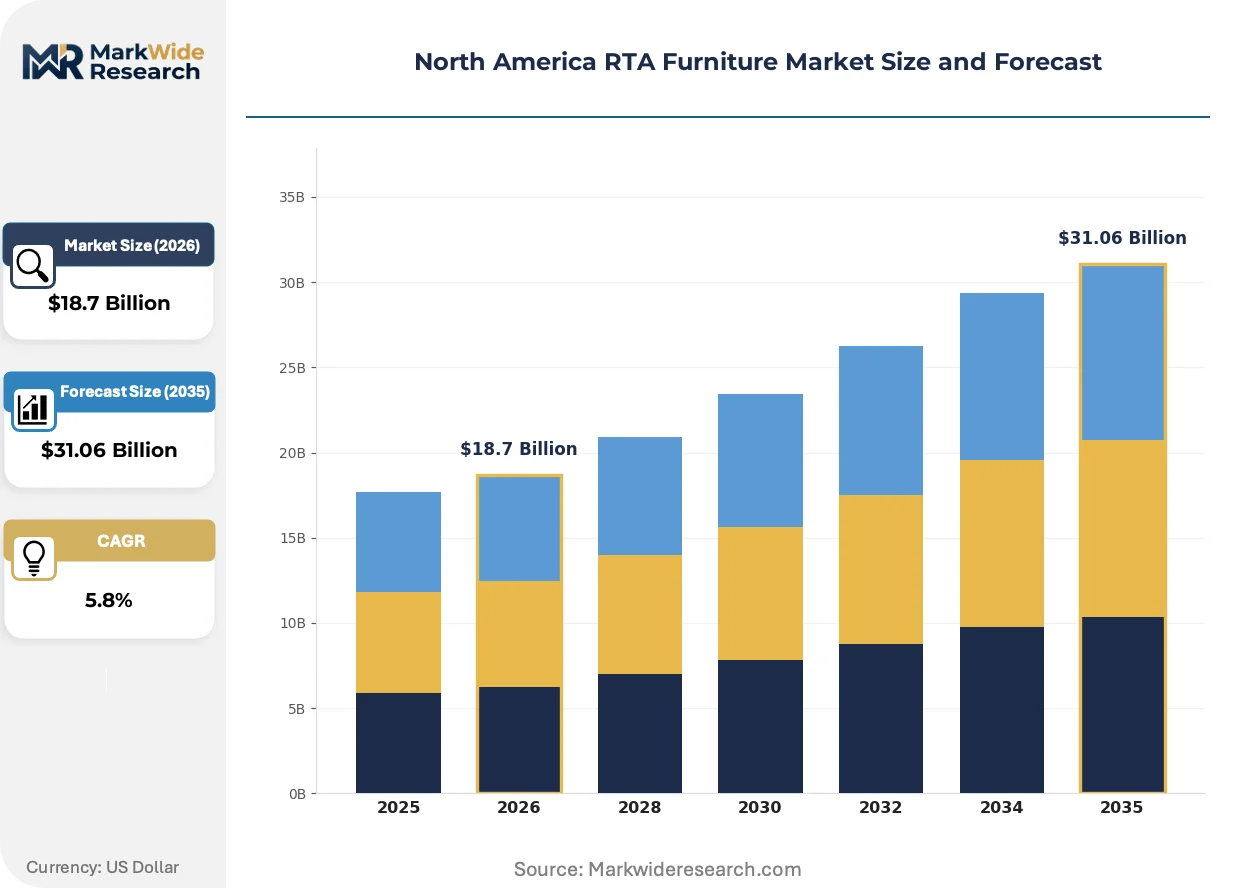
Market Dynamics
Flat-pack logistics economics and EPA formaldehyde emission enforcement are compressing manufacturer margins while simultaneously rewarding supply chain consolidation among integrated panel producers.
Growth Catalysts
- Apartment household formation:Urban density constraints in Texas and Florida are accelerating demand for space-efficient bedroom and storage systems that ship via standard parcel networks.
- California Title 20:Energy efficiency standards for lighting-integrated furniture are creating compliance-driven product refresh cycles across the southwestern United States.
- Work-from-home permanence:Commercial office furniture buyers are redirecting procurement toward residential-scale RTA desk systems for distributed employee stipends.
Market Restraints
- Resin and adhesive input volatility:Urea-formaldehyde binder costs fluctuate with natural gas pricing, compressing engineered wood panel margins unpredictably.
- Cross-border panel concentration:Canadian softwood lumber tariffs and Ontario-based particleboard supply bottlenecks expose US assemblers to duty-related cost spikes.
- Particleboard density limitations:Structural RTA shelving above 150-pound load ratings requires medium-density fiberboard substitution, raising material cost 18-22 percent.
Strategic Opportunities
- Mexico nearshoring corridors:Nuevo León and Baja California manufacturing zones offer tariff-advantaged export platforms for US-bound RTA fulfillment.
- Extended producer responsibility frameworks:California and Ontario end-of-life collection mandates will favor brands with pre-positioned reverse logistics infrastructure.
- Augmented reality spatial validation:AR-enabled mobile applications are reducing return rates for dimensionally sensitive categories by letting buyers visualize fit pre-purchase.
Industry Challenges
- CAD-to-CNC translation talent scarcity:Flat-pack engineering requires specialized nesting software expertise that furniture design programs rarely emphasize.
- TSCA Title VI certification timelines:EPA third-party certification for composite wood products adds 90-120 days to new supplier onboarding.
- Last-mile damage rates:Parcel carrier handling of 48-inch+ flat packs produces 8-12 percent corner crush incidence, eroding brand equity and driving replacement costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America RTA Furniture Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedroom Furniture, Living Room Furniture, Kitchen Furniture, Office Furniture Material: Wood, Metal, Plastic, Glass Distribution Channel: Online Retail, Brick-and-Mortar Stores, Wholesalers, Distributors Customer Type: Residential, Commercial, Institutional, Corporate |
| Companies Covered | IKEA, Ashley Furniture Industries, Sauder Woodworking, Dorel Industries, Bush Industries, South Shore Furniture, Whalen Furniture Manufacturing, BESTAR, Tvilum, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America RTA Furniture Market Trends and Innovations
Digital tools and material science advances are compressing product development cycles while regulatory pressure on indoor air quality is forcing finishing process reinvention across the value chain.
Cam-lock fastener systems with tool-free assembly are modularizing consumer expectations for furniture construction. First-time homebuyers in the southern United States are adopting these interfaces at accelerating rates, rejecting traditional hex-key dependency. This shift is modularizing supplier R&D roadmaps toward snap-fit engineering that eliminates hardware kits entirely.
EPA TSCA Title VI third-party certification requirements for formaldehyde emissions are tightening panel sourcing constraints. Manufacturers must now maintain chain-of-custody documentation from resin supplier through finished goods, adding administrative overhead. Bedroom furniture segments with extended indoor exposure profiles are responding fastest, with some assemblers switching to NAF (no added formaldehyde) substrates despite 15-20 percent cost premiums.
Direct-to-consumer channel capture is displacing traditional furniture retail intermediation. Millennial and Gen Z buyers are completing entire room configurations via mobile-optimized configurators, bypassing showroom visits entirely. This pattern concentrates most visibly in coastal metropolitan markets where apartment turnover rates sustain repeat purchase velocity.
North America RTA Furniture Market Segmentation
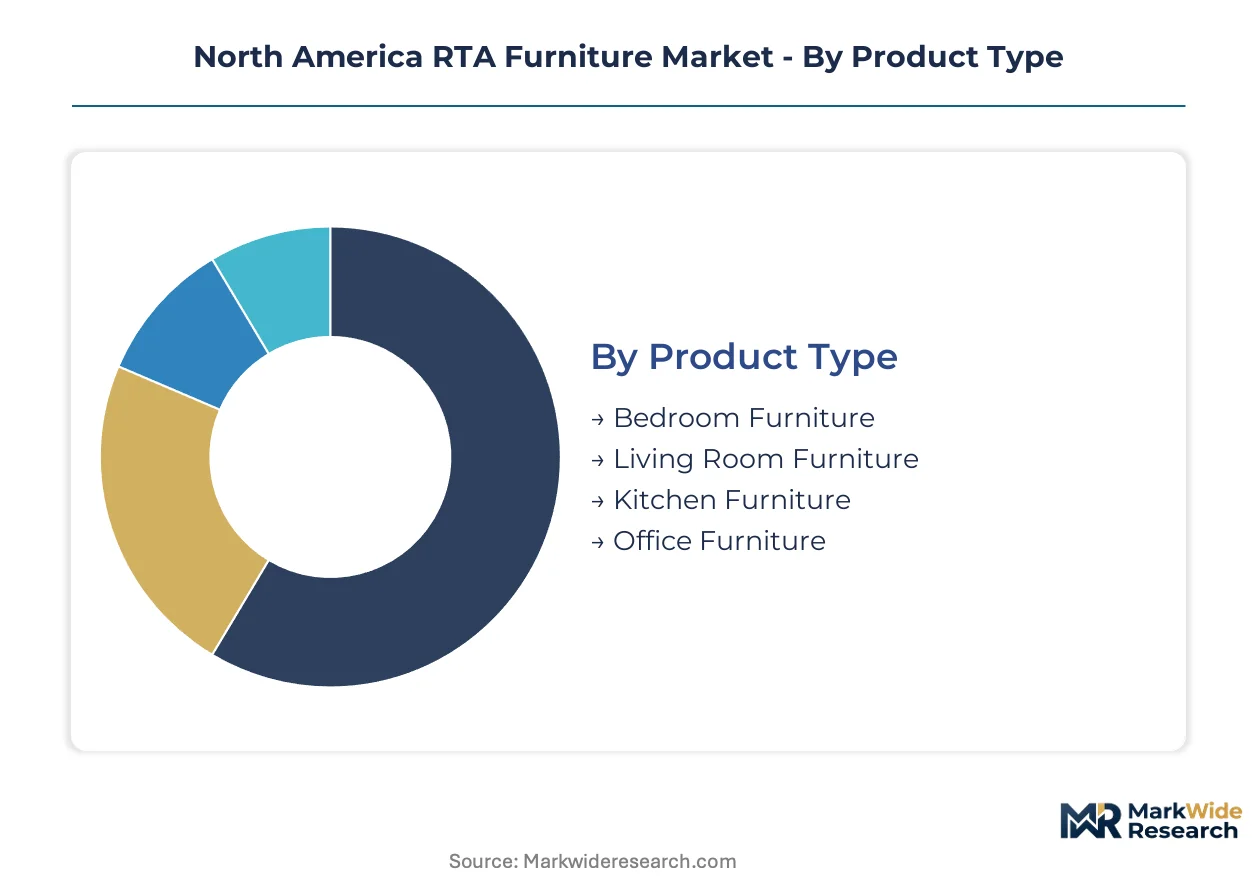
RTA furniture segmentation reveals divergent margin architectures across material and channel choices. Volume concentration in engineered wood bedroom systems contrasts with premium capture in metal-frame office configurations, while digital channel migration is fragmenting traditional retail intermediation.
Product Type:
Bedroom and office furniture dominate unit economics through divergent paths: bedroom systems leverage parcel-scale shipping for mass-market penetration, while office furniture commands durability premiums through structural reinforcement.
- Bedroom Furniture:Flat-packed bed frames, wardrobes, and nightstands utilize cam-lock fasteners and dowel joints for tool-minimal assembly. Demand clusters in Texas and Florida apartment markets where household formation rates outpace national averages and space-efficient storage commands priority.
- Office Furniture:RTA desks, shelving units, and filing systems incorporate metal reinforcement brackets for load-bearing capacity. Work-from-home permanence has redirected commercial procurement toward residential-scale systems for distributed employee stipends across southern United States metros.
- Living Room Furniture:Sofas, entertainment centers, and coffee tables with modular sectional designs.
- Kitchen Furniture:Pantry units, islands, and storage cabinets requiring moisture-resistant finishes.
Today's leader: Bedroom Furniture. Tomorrow's challenger: Office Furniture.
Material:
Engineered wood sustains mass-market penetration through TSCA Title VI compliance pathways, while metal frames extract durability premiums from commercial buyers.
- Wood:Particleboard and medium-density fiberboard panels with laminate or veneer surfacing dominate cost-engineered production. EPA formaldehyde emission enforcement is accelerating NAF substrate adoption despite cost premiums in bedroom furniture with extended indoor exposure profiles.
- Metal:Steel and aluminum framing systems with powder-coated finishes deliver structural integrity above 150-pound load ratings. Commercial buyers in corporate and institutional segments absorb 18-22 percent material cost premiums for durability assurance.
- Plastic:Polypropylene and ABS components for lightweight storage and outdoor applications.
- Glass:Tempered glass tabletops and shelving accents requiring specialized packaging for last-mile damage prevention.
Wood retains volume leadership. Metal gains share fastest in commercial procurement.
Distribution Channel:
Digital-native purchase patterns are compressing traditional retail intermediation, with augmented reality tools reducing spatial uncertainty for dimensionally sensitive categories.
- Online Retail:Direct-to-consumer platforms with mobile-optimized configurators and parcel delivery networks. Millennial and Gen Z first-time homebuyers in coastal metropolitan markets complete entire room configurations without showroom visits, sustaining repeat purchase velocity through subscription-style refresh cycles.
- Brick-and-Mortar Stores:Big-box furniture retailers and specialty chains with in-person assembly consultation. Physical presence defends market position in markets where tactile material evaluation influences purchase decisions.
- Wholesalers:Volume procurement intermediaries serving multi-unit residential developers and property management firms.
- Distributors:Regional logistics networks managing inventory positioning for rapid fulfillment.
Online Retail captures accelerating share. Brick-and-Mortar defends in tactile-dependent segments.
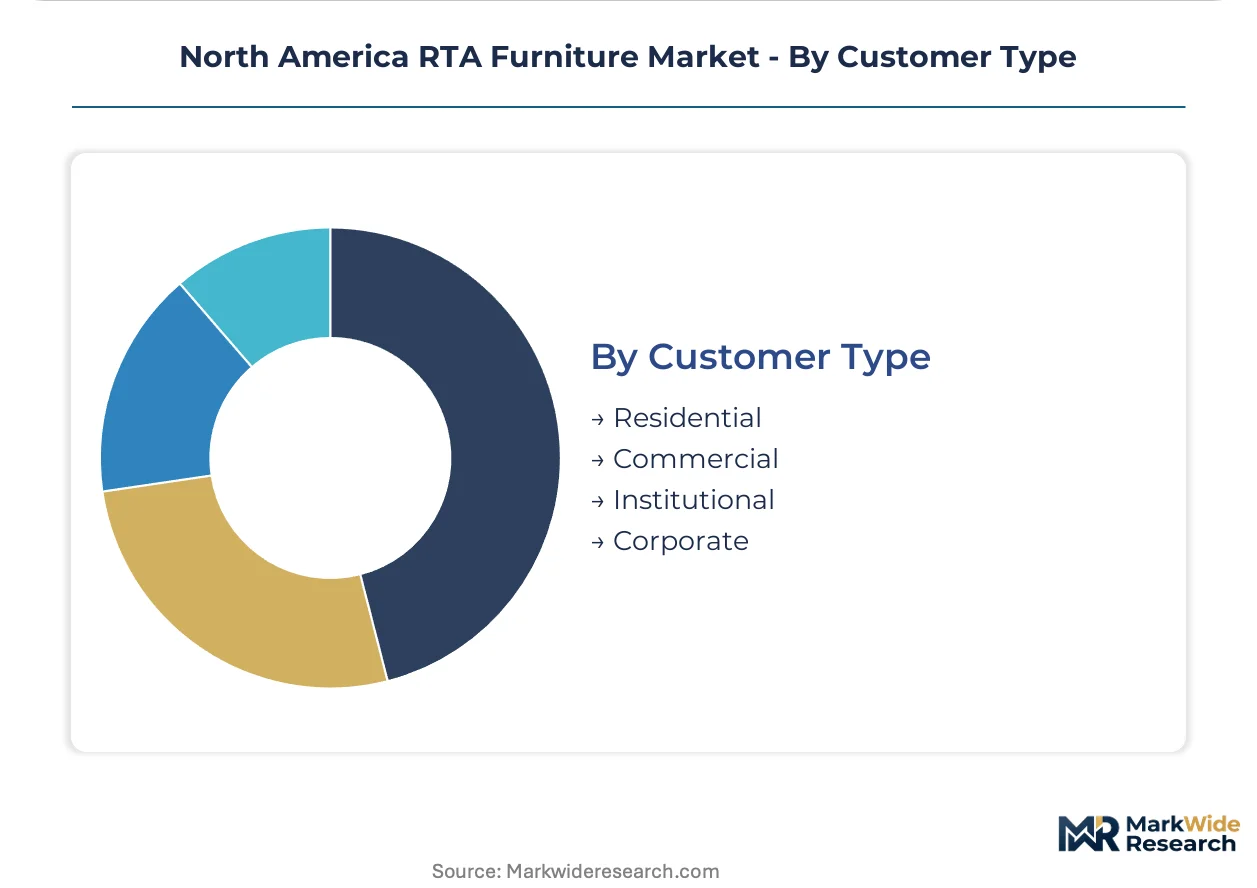
Customer Type:
Residential volume concentration contrasts with commercial margin extraction, as institutional procurement formalizes compliance documentation requirements.
- Residential:Individual households and apartment dwellers purchasing space-efficient systems for primary and secondary residences. First-time homebuyer concentration in southern United States states drives adoption of tool-free assembly interfaces and direct-to-door delivery preferences.
- Commercial:Small businesses and professional service firms procuring reception and workstation furniture. Extended producer responsibility frameworks in California and Ontario are imposing end-of-life collection documentation requirements on procurement specifications.
- Institutional:Educational facilities, healthcare clinics, and government offices with formal bidding processes.
- Corporate:Large enterprises with centralized procurement and distributed employee stipend programs.
Residential anchors volume. Commercial expands most quickly through compliance-driven refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States absorbs the dominant share of North American RTA furniture consumption, while Canadian manufacturing clusters supply cross-border panel demand and Mexican assembly zones capture nearshoring investment.
United States
Texas and Florida apartment markets drive bedroom and storage system demand through elevated household formation rates. EPA TSCA Title VI enforcement constrains composite wood sourcing from resin supplier through finished goods. Southern California's Inland Empire hosts distribution clusters where last-mile parcel networks position inventory for direct-to-door fulfillment.
Canada
Ontario and Quebec engineered wood panel producers serve US assemblers despite softwood lumber tariff exposure. Health Canada and CSA indoor air quality benchmarks shape cross-border compliance documentation requirements. Toronto-Waterloo corridor manufacturers specialize in office systems for North American commercial procurement.
Mexico
Nuevo León and Baja California assembly zones attract tariff-advantaged production for US-bound RTA fulfillment. Mexican federal environmental standards for industrial emissions align with US EPA benchmarks to maintain export eligibility. Monterrey manufacturing parks concentrate flat-pack engineering talent for cam-lock and dowel joint systems.
North America RTA Furniture Market Competitive Landscape
United States producers anchor the mass-market tier; Canadian specialists hold engineered wood supply advantages. The vendor base organizes around three strategic archetypes: integrated panel manufacturers with captive resin supply, direct-to-consumer platforms with augmented reality configurators, and commercial-grade metal fabricators serving corporate procurement. Competitive moves concentrate on Mexico nearshoring corridor establishment and extended producer responsibility infrastructure pre-positioning.
Within the Scandinavian-design mass-market tier, IKEA exemplifies global supply network leverage for price-accessible positioning. Sauder Woodworking represents American manufacturing heritage through Ohio-based production concentration. BESTAR occupies a position as Canadian-engineered office and bedroom system specialists for North American commercial clients.
| Leading Market Players |
|---|
| IKEA |
| Ashley Furniture Industries |
| Sauder Woodworking |
| Dorel Industries |
| Bush Industries |
| South Shore Furniture |
| Whalen Furniture Manufacturing |
| BESTAR |
| Tvilum |
| Others |
Pricing and Supply Chain Analysis
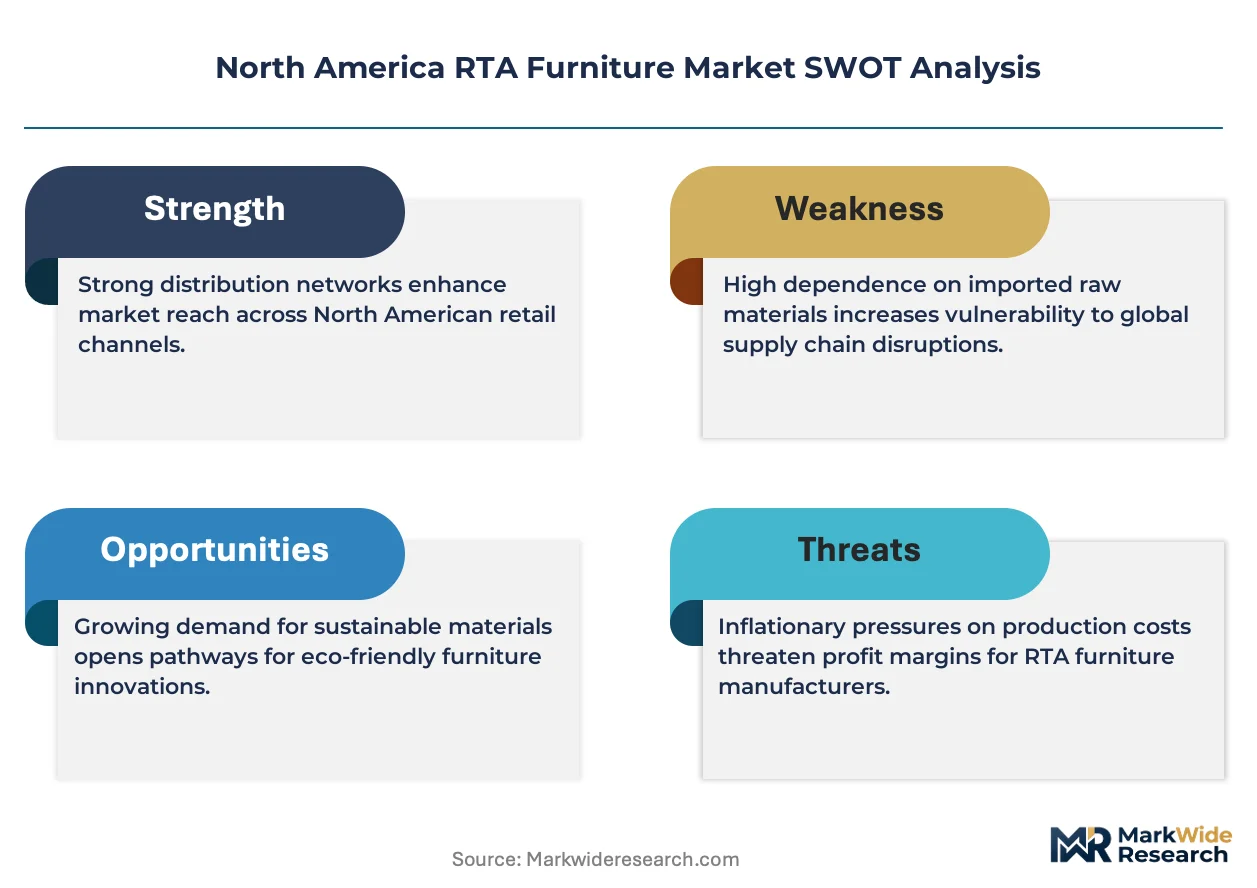
Natural gas price benchmarks governing urea-formaldehyde resin costs cascade through engineered wood panel production into three-tier pricing structures across premium, standard, and economy levels. Panel producers with captive chemical supply command margin insulation unavailable to merchant purchasers, compressing competitive differentiation to certification tier and logistics proximity.
Pricing Analysis
Capacity additions in Nuevo León are reshaping price floors for US-bound RTA fulfillment. Pricing stratifies across premium, standard, and economy tiers based on TSCA Title VI certification status and after-sales assembly support bundling. Cost compression in the standard tier is intensifying because Ontario particleboard supply bottlenecks expose assemblers to duty-related cost spikes. First-time homebuyers in Texas apartment markets exhibit highest price sensitivity, while corporate procurement through employee stipend programs absorbs durability premiums.
Supply Chain Analysis
EPA TSCA Title VI third-party certification gates supplier onboarding with 90-120 day documentation timelines. Manufacturing concentrates in Canada, Mexico, and the United States, with Ontario panel producers feeding US assemblers despite softwood lumber tariff exposure. The chain draws from urea-formaldehyde binders, Canadian softwood fiber, and Asian laminate surfacing. Single-source vulnerability concentrates in Ontario particleboard supply. Distribution runs through Southern California Inland Empire parcel hubs for last-mile positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America RTA furniture market functions as a geographic-arbitrage play where Mexico nearshoring corridors capture tariff advantages against Canadian duty exposure.
For Market Incumbents: Anchor compliance infrastructure around pre-positioned reverse logistics networks before California and Ontario extended producer responsibility mandates activate. Integrate backward into resin supply or captive panel production to offset urea-formaldehyde cost volatility. Defend against direct-to-consumer platforms by controlling last-mile parcel hub positioning in Texas and Florida. For New Entrants and Emerging Players: Begin with augmented reality-enabled configurators targeting coastal metropolitan apartment markets where showroom bypass is already normalized. Exploit white-space in metal-frame office systems for distributed employee stipend programs. Pursue commercial procurement channels where compliance documentation requirements filter out unqualified competitors. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated panel manufacturers with captive resin supply and established EPA certification pathways. Long-term viability favors operators with Mexico manufacturing footprints and pre-built reverse logistics infrastructure. Monitor Ontario softwood lumber tariff negotiations as inflection indicator for cross-border supply economics.| Strategic Initiative | Industry Significance |
|---|---|
| Mexico Nearshoring Establishment | Nuevo León assembly zones capture tariff advantages against Canadian duty exposure for US fulfillment. |
| Reverse Logistics Infrastructure | Pre-positioned collection networks satisfy California and Ontario extended producer responsibility mandates. |
| NAF Substrate Transition | No-added-formaldehyde panel adoption commands bedroom furniture premiums despite input cost elevation. |
| Augmented Reality Configurator Launch | Spatial validation tools reduce return rates for dimensionally sensitive categories in coastal metros. |
| Cam-Lock Engineering Talent Acquisition | Flat-pack nesting software expertise scarcity constrains product development velocity for competitors. |
Research Methodology
Direct dialogue with flat-pack engineering directors, EPA compliance officers at panel manufacturers, procurement leads at multi-unit residential developers, and parcel carrier operations managers grounded qualitative assessment. Secondary validation drew from EPA TSCA Title VI certification databases, Health Canada indoor air quality filings, US Census household formation statistics, and cross-border customs records. Bottom-up unit economics triangulated against top-down regional demand aggregation.
Bottom-up modeling of bedroom, office, living room, and kitchen furniture unit shipments across wood, metal, plastic, and glass material splits combined with top-down regional consumption pattern analysis. Segmentation dimensions included product type, material composition, distribution channel, and customer archetype across the analysis window. CAGRs derived from trend extrapolation of apartment household formation rates, work-from-home permanence indicators, and regulatory compliance-driven refresh cycles.
Caveats apply where Ontario softwood lumber tariff renegotiations or EPA formaldehyde emission threshold revisions could materially shift the outlook. Forecasts reflect assumptions around parcel network capacity expansion and Mexico manufacturing zone stability. A model refresh is warranted upon material change in extended producer responsibility implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Unfinished Wood Furniture Market
Furniture
HORECA Furniture Market
Furniture
North America Secondary Wood Products Market
Furniture
Europe Upholstered Furniture Market
Furniture
Wooden Furniture Market
Furniture
Rattan Furniture Market
Furniture
United Kingdom Home Furniture Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
Germany Home Furniture Market
Furniture
GCC Multifunctional Furniture Market
Furniture
United Arab Emirates Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
Kids Furniture Market
Furniture
GCC Home Furniture Market
Furniture
Global Multifunctional Furniture Market
Furniture
Laminated Door Market