
 Europe Smart Furniture Market | 2026-2036
Europe Smart Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Furniture Market Foresight
Subscription-based furniture leasing and asset-light operating models is narrowing the competitive field to firms with balance-sheet capacity or fintech partnerships. Inter IKEA Systems B.V. leverages its flat-pack logistics network to lower total cost of ownership for smart product lines. Steelcase Inc. anchors its position through deep ergonomic research partnerships with European workplace consultants. MillerKnoll Inc. competes by integrating wellness sensors directly into premium seating collections.
Europe Smart Furniture comprises furnishings embedded with microprocessors, sensors, and connectivity modules that enable automated adjustment, usage tracking, and environmental responsiveness, typically incorporating IoT protocols such as Zigbee or Matter and drawing power through wireless charging pads or low-voltage USB-C interfaces. These systems serve commercial and residential environments by optimizing occupant comfort, energy efficiency, and space utilization through real-time data feedback. Smart beds currently occupy the largest margin pool as biometric sleep monitoring commands premium pricing, while smart desks represent the fastest structural expansion as hybrid work policies normalize sensor-equipped workstations across corporate real estate portfolios. Voice control technology leads adoption in hospitality settings where hands-free operation enhances guest experience, though touch controls sustain stronger penetration in educational institutions due to durability and lower maintenance requirements.
CE marking under the EU Radio Equipment Directive governs wireless connectivity compliance, while REACH restricts hazardous substances in embedded electronics and sensor housings. The EU Green Deal's embodied carbon thresholds are forcing redesigns of composite materials and supply chain sourcing patterns. Stakeholders must monitor how the EU AI Act classifies autonomous adjustment algorithms before committing to multi-year product roadmaps.
Market Dynamics
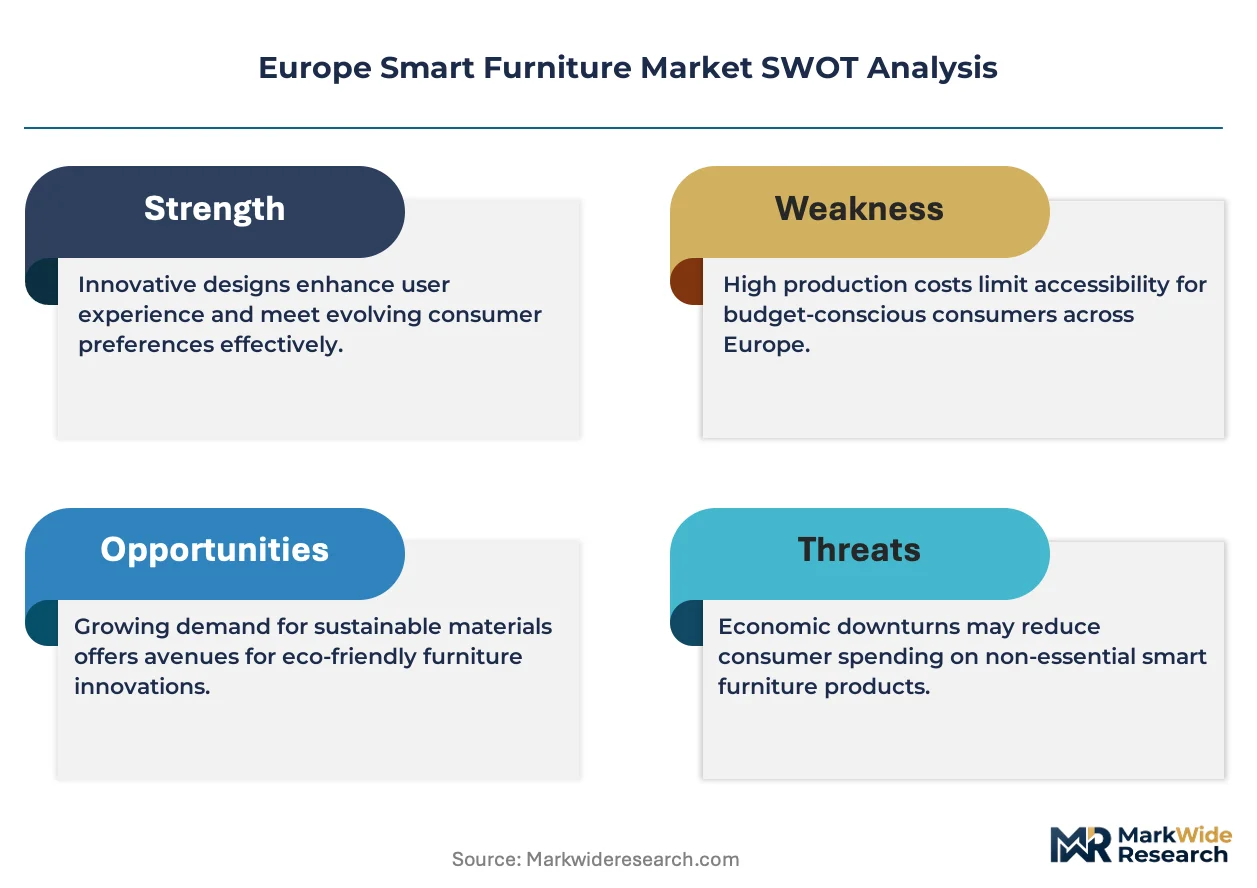
EU Green Deal embodied carbon thresholds are forcing manufacturers to redesign composite materials and reconfigure supply chain sourcing patterns across the European smart furniture value chain. This regulatory pressure is compressing product development cycles while elevating modular design architectures as competitive necessities.
Growth Catalysts
- REACH compliance mandates:Hazardous substance restrictions in embedded electronics are accelerating replacement cycles for legacy sensor housings across German and French manufacturing facilities.
- Commercial office retrofit demand:Employers across the United Kingdom are deploying sensor-embedded desks and chairs to optimize hybrid workspace utilization and energy efficiency.
- IoT protocol standardization:Matter and Zigbee interoperability is reducing integration friction for hospitality and educational procurement teams evaluating multi-vendor deployments.
Market Restraints
- Semiconductor supply concentration:Microprocessor sourcing bottlenecks from East Asian foundries are extending lead times for biometric sleep monitoring modules in premium smart bed production.
- CE marking complexity:EU Radio Equipment Directive wireless compliance testing is adding six-to-nine month certification delays for connectivity-enabled furniture launches.
- Skilled firmware talent scarcity:Embedded systems engineering capacity constraints in Central and Eastern Europe are inflating R&D payroll costs for autonomous adjustment algorithm development.
Strategic Opportunities
- Polish manufacturing expansion:Underpenetrated production capacity in Lower Silesia offers cost-competitive assembly locations for modular smart desk platforms serving Western European distribution.
- EU AI Act algorithm classification:Early clarity on autonomous furniture adjustment regulatory treatment will reward first-movers with compliant product roadmaps before 2025 implementation deadlines.
- Furniture-as-a-Service channel emergence:Asset-light leasing models through fintech partnerships are opening corporate real estate procurement channels previously blocked by capex approval cycles.
Industry Challenges
- Legacy building management system integration:BACnet and Modbus protocol mismatches with Matter-enabled furniture are requiring custom middleware development for commercial deployments.
- CSRD supply chain disclosure:Corporate Sustainability Reporting Directive Scope 3 emissions tracking is forcing tier-two component suppliers to adopt traceability systems they lack capital to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Furniture Market |
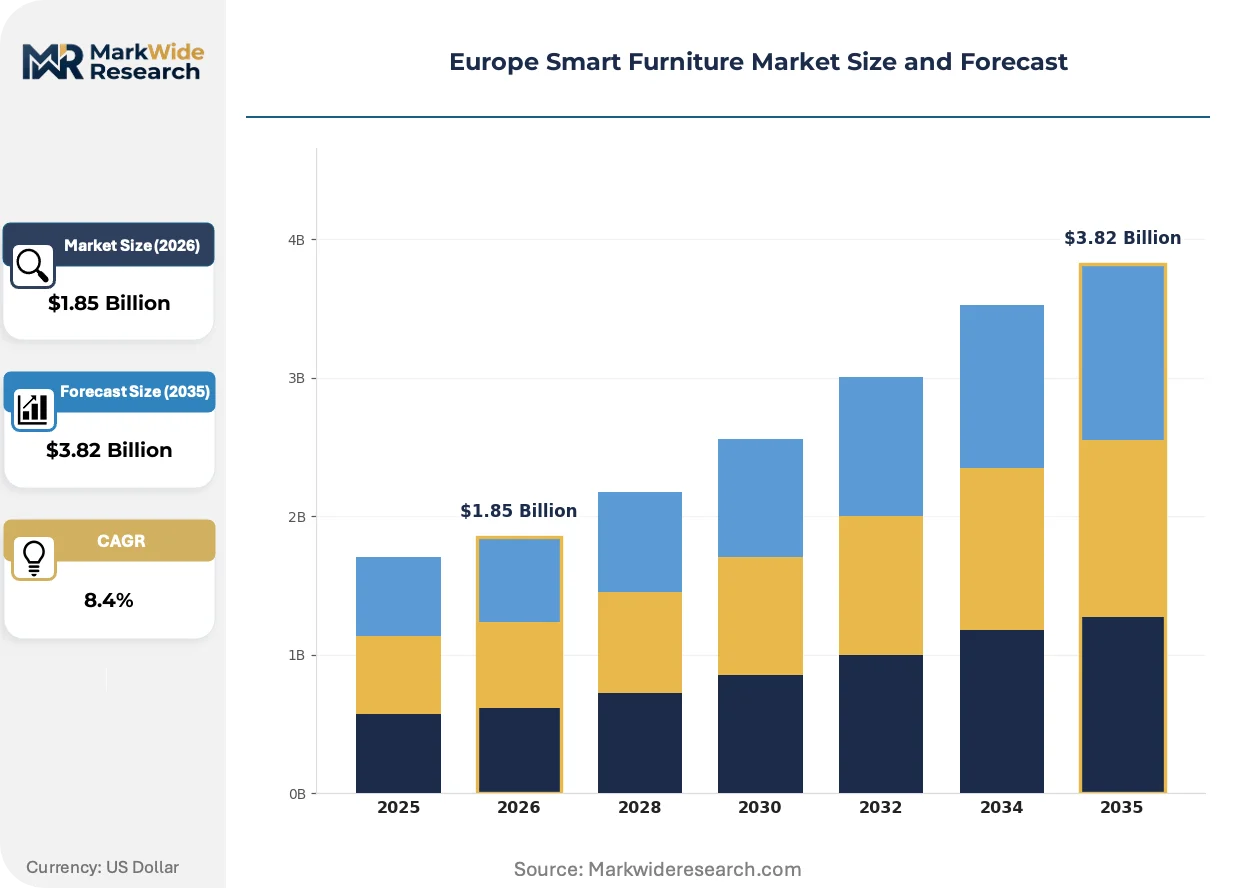
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Desks, Smart Chairs, Smart Beds, Smart Cabinets Technology: IoT, Wireless Charging, Voice Control, Touch Controls End User: Residential, Commercial, Educational, Hospitality Material: Wood, Metal, Plastic, Composite |
| Companies Covered | Sleep Number Corporation, Eight Sleep, Inter IKEA Systems B.V., MillerKnoll Inc., Teknion Corporation, Herman Miller, Sobro, Nowy Styl, Steelcase Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Furniture Market Shifts & Advancements
Sensor fusion architectures and wireless power delivery systems are actively restructuring how European manufacturers differentiate premium smart furniture lines from commodity alternatives. These technical trajectories are compressing traditional hardware refresh cycles while elevating software-defined feature roadmaps.
Biometric monitoring arrays embedded in sleep surfaces are hybridizing pressure-sensitive textiles with photoplethysmography sensors to capture heart rate variability and respiratory patterns without wearable devices. Hospitality operators in Spain and Italy are piloting these systems for wellness-focused guest room tiers. This convergence is hybridizing furniture and medical device regulatory pathways, forcing manufacturers to navigate both CE marking and emerging health claim substantiation requirements.
The EU AI Act's risk classification framework for autonomous decision-making systems is compelling furniture engineers to document algorithmic transparency for self-adjusting ergonomic mechanisms. German workplace safety regulators are already interpreting these provisions in employer liability contexts. Premium seating manufacturers with established ergonomic research partnerships are responding fastest by pre-positioning human-in-the-loop override features.
Corporate real estate teams are consolidating vendor relationships around integrated workspace platforms that bundle furniture, sensors, and analytics software into single-contract arrangements. This behavior is displacing traditional bid-based procurement for individual furniture categories. The United Kingdom and Netherlands are exhibiting the most concentrated demand for these consolidated service models as lease structures shift toward flexible, short-term arrangements.
Europe Smart Furniture Market Segmentation
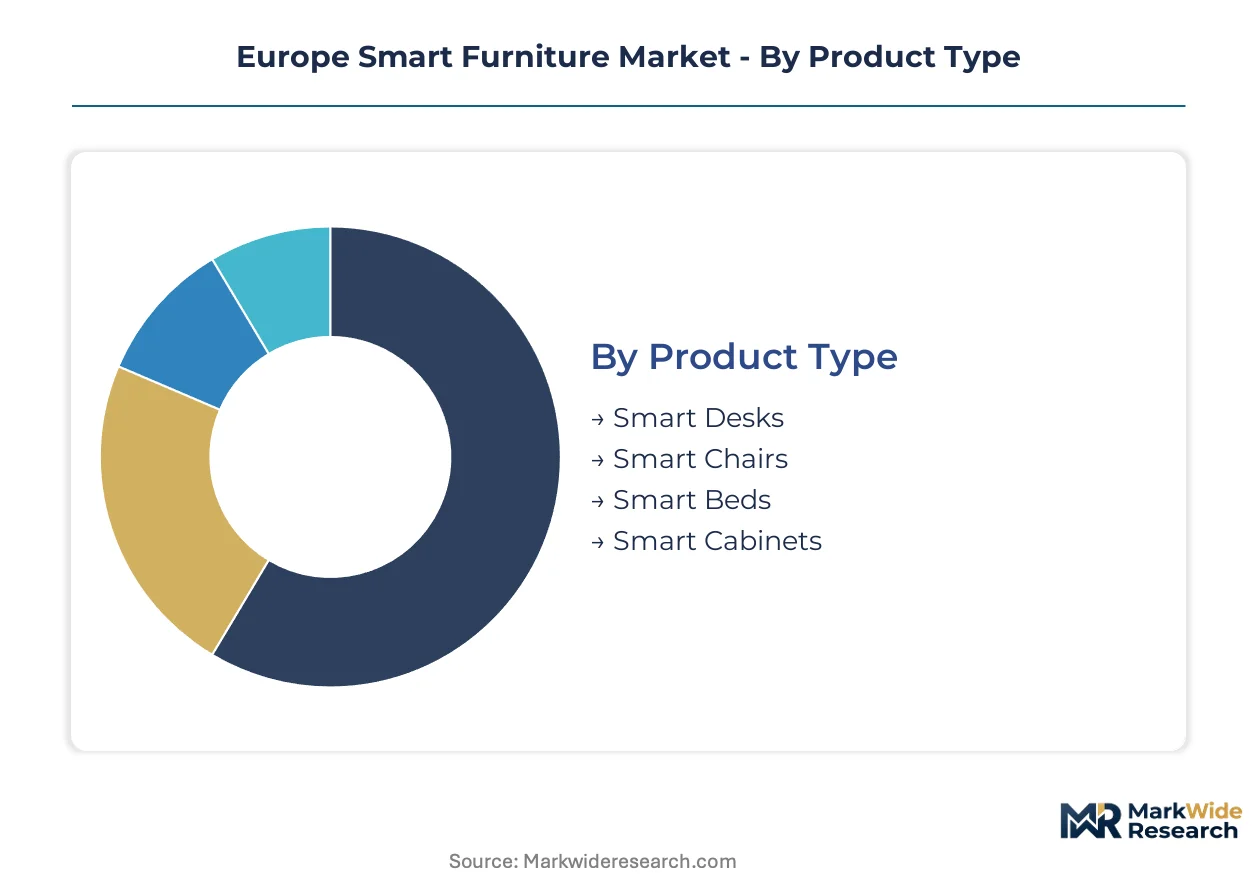
Smart furniture segmentation in Europe reveals divergent maturity curves across product categories, with biometric-enabled sleep systems commanding premium positioning while sensor-embedded workstations penetrate corporate real estate at volume scale. Material compliance under EU Green Deal thresholds and technology interoperability under Matter protocol are reshaping how procurement teams evaluate vendor portfolios across residential, commercial, and institutional channels.
Product Type:
Mature ergonomic seating and emerging biometric sleep surfaces anchor opposite ends of the product maturity spectrum, with desk automation occupying the high-growth middle ground as hybrid work policies stabilize.
- Smart Desks:Height-adjustable surfaces with embedded occupancy sensors, environmental monitors, and wireless charging pads. Demand concentrates in United Kingdom and German corporate retrofit projects where facility managers track space utilization metrics for lease optimization decisions.
- Smart Beds:Sleep surfaces integrating pressure-sensitive textiles with photoplethysmography arrays for heart rate variability tracking without wearable devices. Hospitality operators in Spain and Italy pilot these for wellness-tier guest rooms, navigating both CE marking and emerging health claim substantiation pathways.
- Smart Chairs:Ergonomic seating with posture sensors and autonomous lumbar adjustment algorithms.
- Smart Cabinets:Storage units with inventory tracking, climate control, and access authentication modules.
Smart beds handle the majority of margin extraction; smart desks are expanding most quickly on procurement volume.
Technology:
Cost tier stratification separates premium biometric architectures from standardized connectivity modules, with voice interfaces commanding hospitality premiums while touch controls dominate education procurement.
- IoT:Zigbee and Matter protocol stacks enabling cross-vendor interoperability and centralized building management integration. French and Dutch commercial real estate teams prioritize these for multi-tenant flexible workspace platforms requiring seamless sensor federation.
- Voice Control:Hands-free operation architectures leveraging natural language processing for adjustment commands. Hotels in Barcelona and Milan deploy these for accessibility compliance and guest experience differentiation in premium room categories.
- Wireless Charging:Qi-standard and proprietary inductive power delivery embedded in work surfaces and bedside units.
- Touch Controls:Durable capacitive interfaces with physical override switches for institutional durability requirements.
IoT-enabled systems carry the heaviest R&D allocation; voice control is gaining share fastest in hospitality specification.
End User:
Application context determines technology bundling, with residential buyers prioritizing wellness telemetry while commercial procurement emphasizes space analytics and energy integration.
- Commercial:Sensor-embedded workstations and collaborative furniture for corporate real estate optimization. United Kingdom employers lead deployment density as lease structures shift toward short-term flexible arrangements requiring granular utilization data.
- Residential:Biometric sleep monitoring and automated ergonomic adjustment for home office and bedroom environments. German consumers show highest willingness-to-pay for certified sustainable materials under Blue Angel and EU Ecolabel schemes.
- Educational:Touch-control desks and chairs with durability specifications for K-12 and university procurement cycles.
- Hospitality:Wellness-integrated guest room furniture with voice control and sleep tracking for premium tier positioning.
Commercial channels dominate current shipment volumes; hospitality is climbing the fastest on post-pandemic wellness investment.
Material:
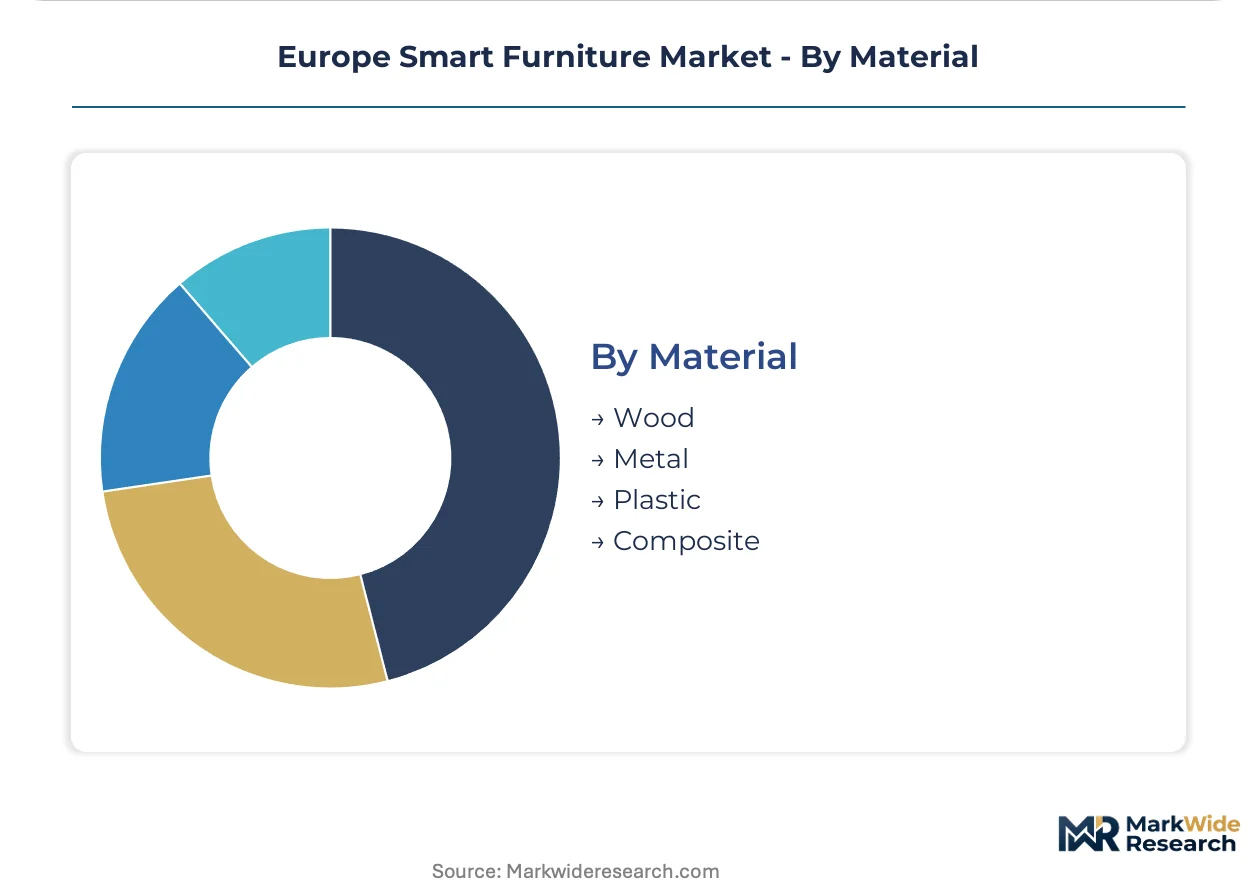
Supply concentration and embodied carbon compliance separate premium certified inputs from cost-optimized alternatives, with composite innovation accelerating under EU Green Deal pressure.
- Composite:Engineered materials combining recycled content with structural polymers for weight reduction and sensor integration. Manufacturers in Lower Silesia, Poland, are scaling production to serve Western European distribution with REACH-compliant formulations meeting embodied carbon thresholds.
- Wood:FSC-certified hardwoods and engineered timber with embedded sensor housings. Swedish and Finnish suppliers anchor premium positioning through traceable Nordic sourcing that satisfies CSRD Scope 3 disclosure requirements for corporate buyers.
- Metal:Aluminum and steel frameworks with powder-coated finishes for commercial durability specifications.
- Plastic:Recycled polymer housings and structural components for cost-sensitive educational and mass-market residential segments.
Wood carries the premium pricing tier; composite materials are expanding fastest on manufacturing scalability and regulatory compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows from Polish and Czech manufacturing clusters outweigh intra-European exports, creating a net import position for Western European markets dependent on lower-cost assembly capacity. German and Dutch distributors dominate cross-border wholesale channels, while French and Italian buyers concentrate procurement through domestic specification houses. REACH compliance costs and CE marking timelines are reshaping sourcing patterns toward integrated regional supply chains.
Germany
Corporate real estate retrofit demand concentrates in Berlin and Munich, where facility managers deploy sensor-embedded workstations for hybrid workspace optimization. Blue Angel certification requirements under the EU Ecolabel framework elevate procurement specifications for sustainable materials. North Rhine-Westphalia hosts the densest manufacturing cluster, with Düsseldorf-based distributors coordinating pan-European logistics for modular smart desk platforms.
United Kingdom
Flexible lease structures in London and Manchester are accelerating furniture-as-a-service adoption among employers seeking to bypass capital expenditure approval cycles. The Building Safety Act 2022's product traceability provisions intersect with CSRD disclosure mandates for corporate tenants. The Midlands manufacturing corridor around Birmingham is scaling composite material production to serve domestic and Irish distribution networks.
France
Hospitality operators in Paris and Lyon are piloting biometric sleep surfaces for wellness-tier guest room positioning, navigating both CE marking and emerging health claim substantiation pathways. The EU AI Act's algorithmic transparency requirements are compelling French workplace safety regulators to interpret autonomous adjustment provisions in employer liability contexts. Auvergne-Rhône-Alpes hosts a growing cluster of sensor integration specialists serving Lyon-based furniture fabricators.
Poland
Lower Silesia's underpenetrated production capacity offers cost-competitive assembly locations for modular smart desk platforms serving Western European distribution. REACH-compliant composite material formulations from Polish suppliers are capturing share from German and Swedish incumbents under EU Green Deal embodied carbon pressure. Wrocław-based logistics hubs are consolidating cross-border fulfillment for Dutch and Belgian wholesale channels.
Italy
Hospitality procurement in Milan and Rome prioritizes voice-controlled guest room furniture for accessibility compliance and premium positioning. The country's furniture design heritage intersects with Matter protocol standardization efforts, with Milan-based specification houses coordinating multi-vendor IoT deployments. Northern Italian manufacturing districts around Brianza are adapting artisan woodcraft techniques to embedded sensor housing production for luxury residential segments.
Europe Smart Furniture Market Competitive Landscape
On the supply side, the industry is bifurcating between capital-intensive platform operators and specialized component suppliers. Tier-one vendors consolidate procurement relationships through integrated workspace analytics bundles, while mid-scale fabricators compete on modular customization and regional fulfillment velocity. Two strategic archetypes dominate: ergonomic research partnerships anchoring premium seating positioning, and flat-pack logistics networks enabling total cost of ownership compression. Competitive moves center on fintech-enabled leasing channel development and algorithmic transparency pre-positioning ahead of EU AI Act implementation.
Within the platform-operator tier, Inter IKEA Systems B.V. and Steelcase Inc. exemplify divergent scale strategies, with the former leveraging captive logistics infrastructure and the latter anchoring positioning through workplace consultancy ecosystems. MillerKnoll Inc. occupies a position bridging premium residential and corporate segments. Specialists in biometric sleep integration include Sleep Number Corporation and Eight Sleep, both representing the convergence of furniture and medical device regulatory pathways. Among European-based fabricators, Nowy Styl exemplifies the mid-scale modular specialist archetype competing on regional responsiveness rather than integrated platform breadth.
| Leading Market Players |
|---|
| Sleep Number Corporation |
| Eight Sleep |
| Inter IKEA Systems B.V. |
| MillerKnoll Inc. |
| Teknion Corporation |
| Herman Miller |
| Sobro |
| Nowy Styl |
| Steelcase Inc. |
| Others |
Supply & Pricing Matrix
Semiconductor sourcing bottlenecks from East Asian foundries determine both pricing tier spreads and supply chain shape across the European smart furniture value chain. This single-source dependency for biometric sleep monitoring modules and autonomous adjustment microprocessors compresses margins at the premium tier while forcing manufacturers toward modular architectures that accommodate component substitution.
Pricing Analysis
Corporate real estate buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the European smart furniture market. Price differentiation rests on CE certification tier and volume scale, with hospitality operators least sensitive due to wellness-tier positioning requirements while educational procurement teams face strict budget caps. Pricing pressure stems from REACH compliance costs for sensor housing materials, intensifying cost compression in the mid-market desk segment where German and French facility managers dominate volume.
Supply Chain Analysis
Export-control restrictions on advanced microprocessors and sensor fusion chipsets limit component flows from Taiwanese and South Korean foundries into European assembly operations. Manufacturing gravity centers on Poland, Germany, and Sweden for final assembly, with raw material dependencies spanning FSC-certified Nordic timber, REACH-compliant composite polymers from Lower Silesia, and photoplethysmography sensor arrays from East Asian suppliers. Single-source vulnerability for biometric modules creates inventory risk, while distribution runs through Düsseldorf and Wrocław logistics hubs serving Western European wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European smart furniture market sits at a platform-economics inflection where Matter protocol interoperability determines ecosystem lock-in. This shift rewards vendors with integrated software-analytics bundles over pure hardware fabricators.
For Market Incumbents: Harden algorithmic transparency documentation ahead of EU AI Act implementation deadlines, pre-positioning human-in-the-loop override features for autonomous ergonomic mechanisms. Deepen captive supply of sensor fusion chipsets through direct foundry relationships to offset East Asian concentration risk. Anchor positioning through exclusive workplace consultancy partnerships that bundle furniture, sensors, and utilization analytics into single-contract arrangements. For New Entrants and Emerging Players: Mid-market commercial buildings in Poland and the Czech Republic represent the most penetrable entry point for modular smart desk platforms, where underpenetrated production capacity meets Western European distribution demand. Hospitality voice-control furniture for accessibility compliance in Spanish and Italian wellness-tier guest rooms offers secondary white-space. Pursue fintech-enabled furniture-as-a-service channel partnerships to bypass corporate capex approval cycles. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform operators with integrated workspace analytics capabilities over pure manufacturing specialists. Five-to-ten year viability hinges on regulatory compliance infrastructure and software-defined feature roadmaps. Target acquisition archetypes include biometric sleep integration specialists navigating medical device pathways and regional modular fabricators with REACH-compliant composite material expertise. Monitor EU AI Act algorithm classification clarity as the critical inflection signal for compliant product roadmap valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-vendor interoperability unlocks multi-tenant flexible workspace procurement in the Netherlands and France. |
| Biometric Sleep Module Development | Photoplethysmography integration commands hospitality wellness-tier premiums in Barcelona and Milan. |
| Polish Manufacturing Footprint Expansion | Lower Silesia assembly capacity reduces embodied carbon exposure under EU Green Deal thresholds. |
| Furniture-as-a-Service Platform Launch | Asset-light leasing bypasses UK corporate real estate capex approval cycles. |
| Algorithmic Transparency Documentation | EU AI Act compliance pre-positioning defends against German workplace safety liability exposure. |
Research Methodology
Initial hypotheses were tested against primary input from corporate real estate facility managers, hospitality procurement directors, embedded systems engineers, and EU regulatory affairs specialists, then refined through secondary validation. Primary fieldwork encompassed workplace consultancy partnerships, sensor integration specialists, and composite material suppliers across Germany, Poland, and Sweden. Secondary sources included CE marking documentation under the EU Radio Equipment Directive, REACH substance restriction databases, EU Green Deal embodied carbon threshold disclosures, and corporate sustainability reporting under CSRD Scope 3 requirements. Bottom-up shipment data triangulated against top-down procurement spend estimates across commercial, residential, hospitality, and educational channels.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation dimensions spanning product type, technology protocol, end-use application, material certification tier, and regional production cluster. CAGRs derived from fitted growth curves incorporating hybrid work policy stabilization rates, IoT protocol adoption velocity, and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs included biometric sensor cost decline trajectories and Matter certification pipeline visibility.
Practitioners should monitor semiconductor export-control expansion, EU AI Act implementation guidance, and REACH substance list revisions for early signals requiring forecast reassessment. Material shifts in autonomous furniture algorithm classification or embodied carbon threshold stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
United Kingdom Kitchen Furniture Market
Furniture
China Furniture Market
Furniture
Laminated Door Market
Furniture
Middle East and Africa Wood Based Panel Market
Furniture
North America Secondary Wood Products Market
Furniture
Children Furniture Market
Furniture
Ergonomic Chair Market
Furniture
Global Furniture Fittings Market
Furniture
Global Multifunctional Furniture Market
Furniture
HORECA Furniture Market
Furniture
Back Mount Frames Market
Furniture
Bean Bag Chairs Market
Furniture
Wooden Furniture Market
Furniture
Metal Furniture Market
Furniture
Pool Tables Market
Furniture
Cabinet Market