
 Bar Stools Market | 2026-2036
Bar Stools Market Size, Share, and Industry Trends Forecast 2026-2036
Bar Stools Market Analytics
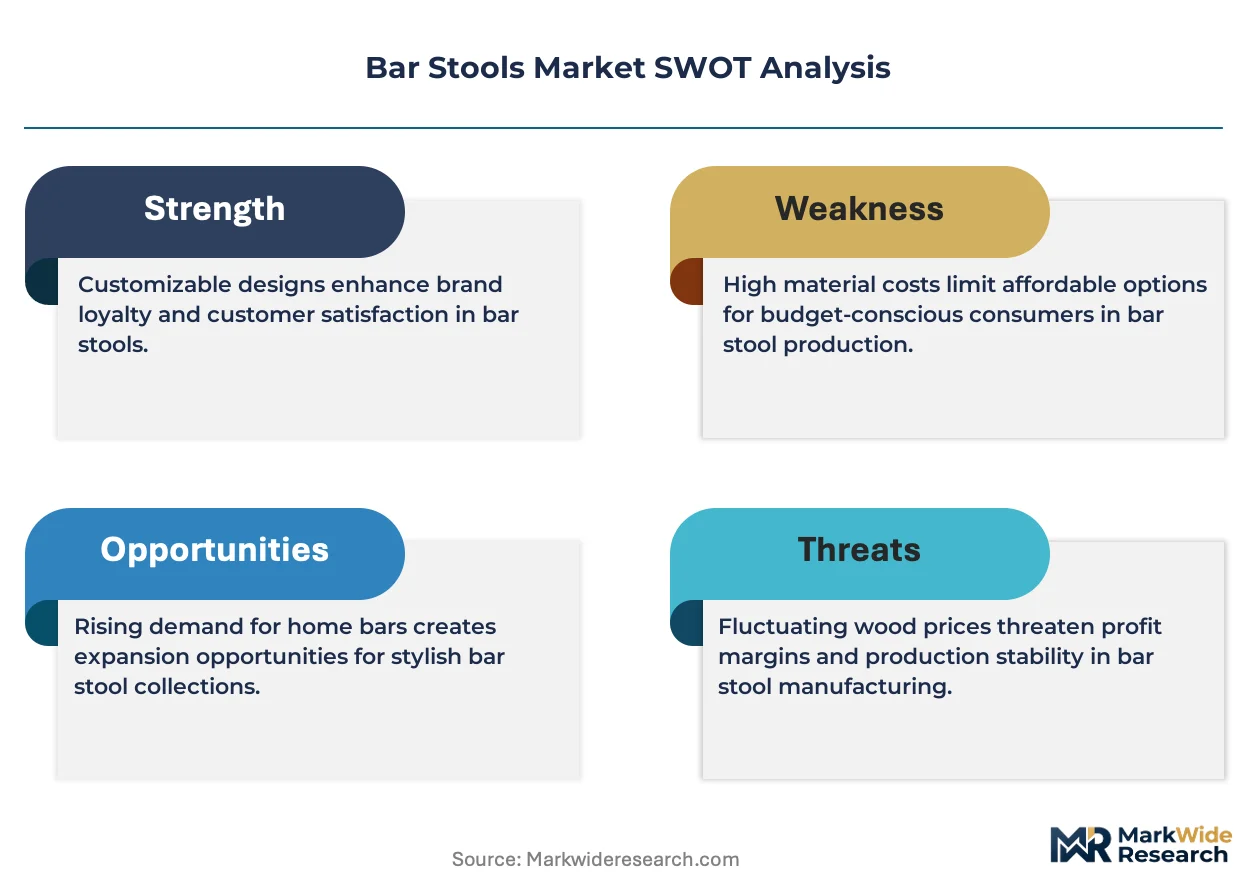
Direct-to-consumer furniture channels is narrowing as legacy retailers consolidate online presence and specialty makers bypass wholesale layers. IKEA leverages its flat-pack logistics network to dominate entry-level residential volumes. Holland Bar Stool anchors its position through captive manufacturing of licensed sports and commercial seating. Williams-Sonoma differentiates via curated artisan partnerships that command premium positioning in kitchen and bar environments.
Bar stools are elevated seating fixtures typically constructed with hardwood frames, steel bases, or molded polymer shells, designed for counter-height or bar-height surfaces in residential kitchens, commercial hospitality venues, and recreational spaces. Metal-framed industrial stools with welded steel construction and powder-coated finishes withstand high-traffic restaurant environments where durability governs procurement decisions. Upholstered variants in leather and performance fabric command margin concentration in residential channels where aesthetic customization drives replacement cycles, while swivel mechanisms represent the fastest-growing functional category as consumers prioritize ergonomic adaptability in multipurpose kitchen islands.
California Air Resources Board composite wood regulations and EPA formaldehyde emissions standards constrain material selection for domestic manufacturers, pushing supply chains toward certified low-emission substrates and water-based finishes. The Consumer Product Safety Commission stability testing requirements for tip-over prevention add engineering costs that disproportionately burden smaller import-dependent distributors. Stakeholders must monitor evolving state-level chemical disclosure mandates and assess whether regional compliance investments justify captive production versus outsourced manufacturing partnerships.
Market Dynamics
Residential renovation spending and open-plan kitchen trends are restructuring demand patterns across the Bar Stools Market, while California's Title 20 energy efficiency standards force manufacturers toward certified low-emission substrates and water-based finishes.
Growth Catalysts
- Residential Kitchen Renovation:Homeowners in the United States are replacing fixed seating with counter-height stools as kitchen islands become primary gathering spaces, driving replacement cycles in metropolitan installations.
- EPA Formaldehyde Emissions Standards:Stricter composite wood regulations push domestic manufacturers toward certified substrates, creating competitive differentiation for compliant producers against import-dependent distributors.
- Swivel Mechanism Adoption:Ergonomic adaptability in multipurpose kitchen islands accelerates functional category expansion as consumers prioritize seating mobility over static designs.
Market Restraints
- Steel Input Cost Volatility:Welded steel construction and powder-coated finishes for commercial hospitality venues face margin pressure from fluctuating raw material indices and energy-intensive coating processes.
- Import Concentration Risk:Smaller distributors dependent on Asian manufacturing face disproportionate engineering cost burdens from CPSC stability testing requirements for tip-over prevention.
- Performance Fabric Substitution:Leather upholstery variants in residential channels compete with synthetic alternatives that mimic aesthetic properties at lower price points, compressing premium positioning.
Strategic Opportunities
- Direct-to-Consumer Channel Innovation:Specialty makers bypassing wholesale layers capture margin previously allocated to legacy retail intermediaries through owned digital storefronts and configurable product platforms.
- Artisan Partnership Models:Curated collaborations with regional woodworkers and metal fabricators enable premium kitchen and bar positioning that commands price separation from mass-market flat-pack alternatives.
- State-Level Chemical Disclosure Mandates:Early compliance investments in California's evolving transparency requirements create barrier-to-entry advantages against late-adopting competitors in domestic manufacturing.
Industry Challenges
- Water-Based Finish Certification Timeline:Manufacturers transitioning from solvent-based coatings face extended validation periods for durability and colorfastness testing under CARB composite wood regulations.
- Legacy ERP Integration Complexity:Custom furniture producers adopting mass-customization software encounter friction synchronizing artisan production workflows with automated inventory and fulfillment systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bar Stools Market |
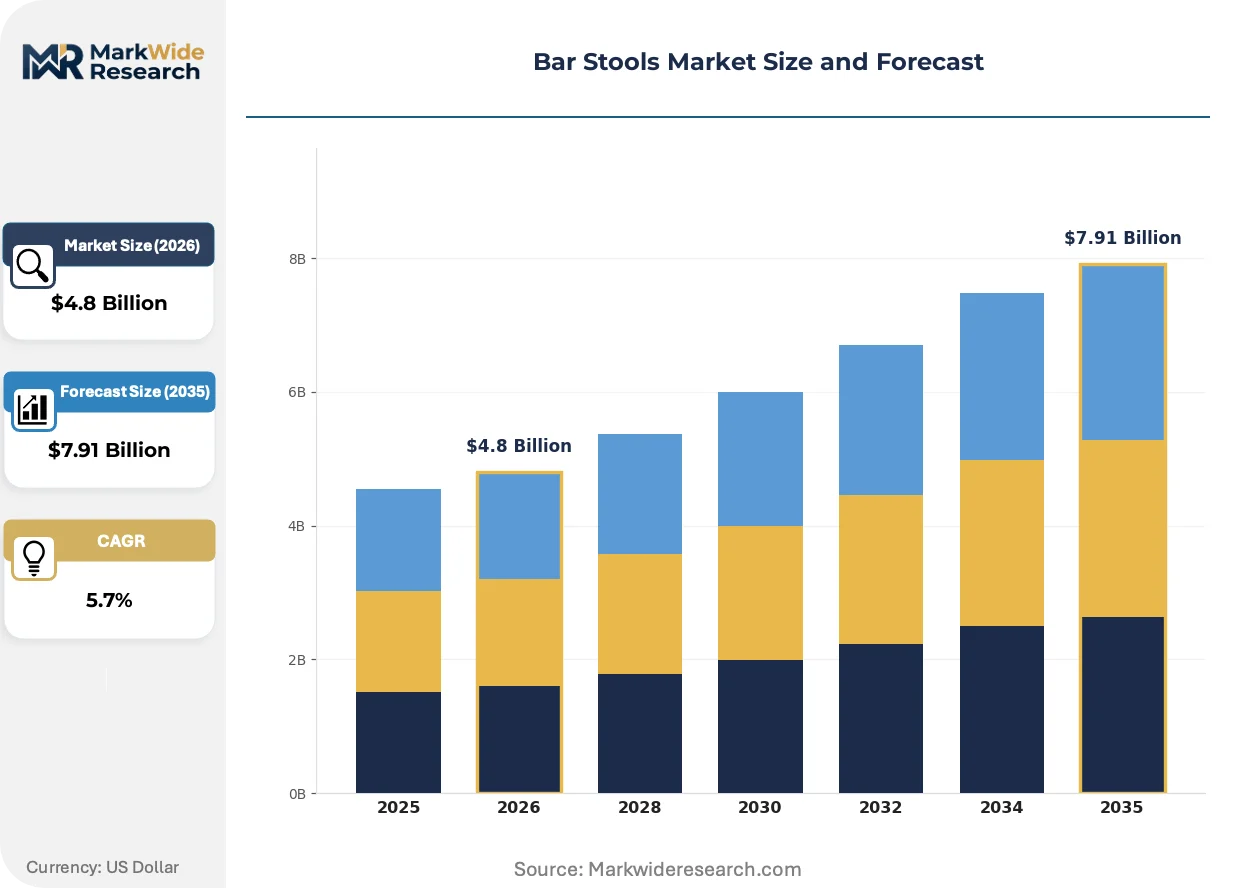
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Modern, Swivel, Adjustable Material: Wood, Metal, Plastic, Upholstered Style: Industrial, Contemporary, Rustic, Coastal End User: Commercial, Residential, Restaurants, Bars |
| Companies Covered | IKEA, Holland Bar Stool, Richardson Seating, Williams-Sonoma, Ashley Furniture Industries, Steelcase, Regal Seating, Trendler, My Bar Stools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bar Stools Market Evolving Landscape
Molded polymer shells and adjustable-height mechanisms are redefining material and functional expectations across residential and commercial segments, compressing traditional category boundaries between fixed and adaptive seating.
Pneumatic lift technology is migrating from office furniture into residential bar stool designs, enabling seated height adjustment across counter and bar surfaces from a single unit. Urban apartment dwellers and downsizing homeowners are adopting these dual-purpose fixtures at accelerating rates. This convergence is collapsing the historical separation between kitchen and home office seating categories, forcing retailers to reorganize merchandising and inventory allocation.
REACH chemical restrictions in Europe and parallel state-level mandates in California are eliminating certain flame retardants and plasticizers from upholstered components, compelling reformulation of foam cushioning and synthetic leather alternatives. Manufacturers serving hospitality clients must maintain dual specification streams for domestic and export compliance. The commercial seating segment bears the heaviest adaptation burden, as contract furniture faces the most stringent durability and safety testing protocols.
Buyers are consolidating vendor relationships around full-service seating suppliers capable of delivering coordinated kitchen, dining, and bar collections from single purchase orders. Independent interior designers and multi-unit residential developers are displacing fragmented sourcing across specialty stool, chair, and table manufacturers. This concentration is most visible in United States metropolitan markets where renovation contractors prioritize schedule certainty and single-point accountability over price optimization.
Bar Stools Market Segmentation
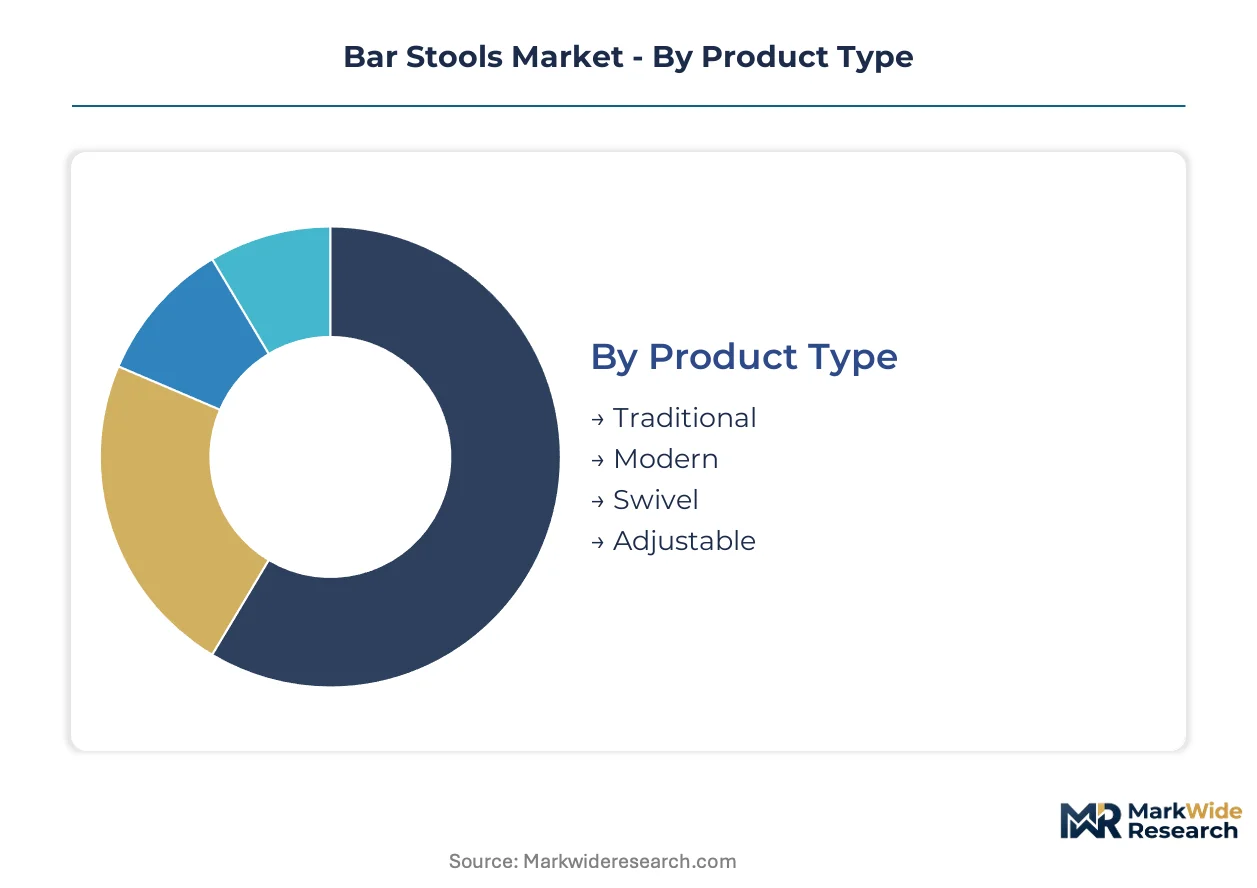
Bar stool purchasing decisions fragment across functional requirements, aesthetic preferences, and compliance obligations that reshape vendor selection criteria. Understanding these segment boundaries clarifies where margin concentrates and which specification streams demand dedicated supply chain investment.
Product Type:
After-sales service intensity varies sharply across mechanism complexity, with adjustable and swivel variants requiring component replacement networks that static designs rarely need.
- Traditional:Fixed-height designs with four-legged hardwood or metal construction dominate replacement cycles in established residential kitchens where homeowners prioritize longevity over adaptability. Demand clusters in United States metropolitan renovation markets where matching existing dining furniture governs procurement.
- Modern:Clean-lined profiles with minimal ornamentation command premium positioning in urban condominium developments and open-plan kitchen installations. Coastal California and Pacific Northwest metropolitan areas drive specification volume for matte finishes and geometric silhouettes.
- Swivel:Rotational bearing mechanisms enable ergonomic adaptability in multipurpose kitchen islands, accelerating functional category expansion as consumers prioritize seating mobility.
- Adjustable:Pneumatic or threaded-column height modification supports counter-to-bar surface flexibility, collapsing historical category boundaries between fixed-height segments.
Traditional designs hold the largest share; momentum sits with Swivel as ergonomic priorities reshape residential specification.
Material:
Cost tier stratification separates premium hardwood and leather upholstery from mass-market metal and polymer alternatives, with compliance certification adding margin layers to certified substrates.
- Wood:Solid hardwood frames in oak, walnut, and maple anchor artisan positioning and command price separation from engineered alternatives. California CARB composite wood regulations and EPA formaldehyde emissions standards constrain domestic manufacturer sourcing toward certified low-emission substrates.
- Metal:Welded steel construction with powder-coated finishes withstands high-traffic restaurant environments where durability governs commercial procurement decisions.
- Plastic:Molded polymer shells reduce unit costs and shipping weight, enabling flat-pack distribution models that dominate entry-level residential volume.
- Upholstered:Leather and performance fabric variants concentrate margin in residential channels where aesthetic customization drives replacement cycles.
Metal commands commercial volume leadership; Upholstered variants are climbing the fastest as residential customization priorities intensify.
Style:
Application context dictates style selection, with contract hospitality favoring Industrial durability while residential channels fragment across aesthetic movements.
- Industrial:Exposed steel frames, riveted joints, and distressed finishes align with brewery and loft-conversion aesthetics in urban United States markets. Chicago, Detroit, and Pittsburgh metropolitan restaurant openings sustain specification volume for welded construction and weathered patina treatments.
- Contemporary:Streamlined profiles with mixed material combinations—wood seats on metal bases, acrylic backs on steel frames—capture renovation spending in high-end residential kitchens.
- Rustic:Reclaimed wood elements and hand-forged metal accents target vacation property and farmhouse-style installations in Mountain West and Northeast markets.
- Coastal:Whitewashed finishes, rope-wrapped bases, and weather-resistant materials dominate Florida and Carolinas beach house renovations where humidity tolerance shapes material selection.
Industrial styling leads commercial share; Contemporary designs are gaining share fastest as metropolitan kitchen renovations accelerate.
End User:
Customer type determines specification rigor, with contract hospitality demanding fire-rated materials and stability certification that residential channels rarely require.
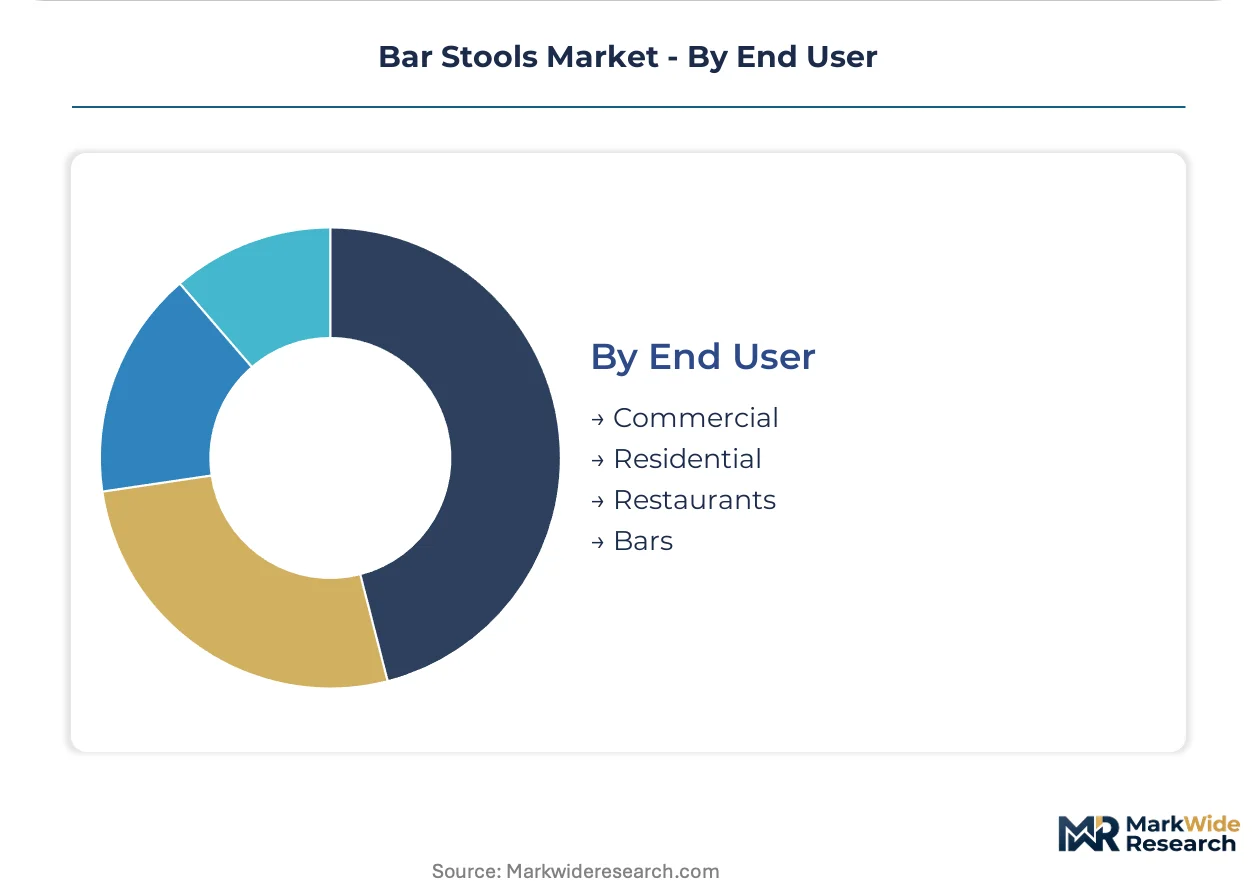
- Commercial:Multi-unit hospitality and corporate foodservice operations prioritize durability warranties, stackability, and uniform replacement part availability across property portfolios.
- Residential:Single-family homeowners and apartment dwellers drive volume through kitchen island installations, with aesthetic coordination to existing cabinetry governing purchase timing.
- Restaurants:Independent and chain dining establishments specify for daily high-cycle use, with CPSC stability testing requirements for tip-over prevention adding engineering costs that burden smaller import-dependent distributors.
- Bars:Nightlife venues emphasize foot rail integration, backless profiles for crowd flow, and spill-resistant finishes that withstand aggressive cleaning protocols.
Residential channels hold the largest share; Restaurants are expanding most quickly as United States dining establishment openings accelerate post-pandemic renovation backlogs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States residential channels command price premiums against Mexican manufacturing cost baselines, creating margin capture asymmetries across North American supply chains. European REACH chemical restrictions and Asian flat-pack logistics networks add regulatory and operational complexity to cross-border sourcing decisions.
United States
Metropolitan kitchen renovations in California, Texas, and New York Metro drive counter-height stool replacement cycles as open-plan islands replace formal dining rooms. EPA formaldehyde emissions standards and CPSC stability testing requirements constrain import-dependent distributors toward certified domestic substrates. Chicago anchors industrial-style specification volume for brewery and loft-conversion hospitality projects.
Germany
High-end residential construction in Bavaria and North Rhine-Westphalia sustains artisan hardwood frame demand for kitchen and bar environments. ECHA REACH restrictions on flame retardants and plasticizers compel foam cushioning reformulation for upholstered variants. Berlin-Brandenburg clusters specialist metal fabricators serving contract hospitality across Central European markets.
China
Flat-pack polymer shell production concentrates in Guangdong and Zhejiang provinces for cost-driven residential export volume. GB standards for furniture safety and MIIT industrial policy shape manufacturing upgrade timelines toward automated welding and powder-coating lines. Yangtze River Delta ports handle consolidated container shipments to North American and European distribution networks.
India
Maharashtra and Gujarat furniture clusters supply metal-framed commercial seating for domestic hospitality and Middle East export contracts. BIS certification requirements for structural stability and material safety add compliance layers to manufacturing investments. Bangalore residential developers specify contemporary bar stools for urban apartment kitchen islands.
Canada
Ontario and Quebec renovation contractors source cross-border from United States distributors while maintaining specifications for Health Canada product safety guidelines. Vancouver and Toronto metropolitan markets concentrate contemporary and coastal-style demand for condominium and single-family installations. Prairie Provinces drive rustic-style volume for vacation property and farmhouse aesthetic projects.
Bar Stools Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with captive manufacturing and licensed fabrication relationships. The vendor base separates between mass-market flat-pack distributors, artisan-curated premium retailers, and contract hospitality specialists. Three archetypes dominate: logistics-scale platform operators, licensed sports and commercial seating fabricators, and configurable direct-to-consumer specialists. Competitive moves concentrate on wholesale layer bypass through owned digital channels and regional artisan partnership networks for premium positioning.
Among logistics-scale platform operators, IKEA anchors entry-level residential volume through flat-pack distribution density. Holland Bar Stool exemplifies the licensed commercial seating archetype with captive manufacturing of sports and hospitality contracts. Williams-Sonoma occupies the premium curated tier through artisan partnerships commanding price separation in kitchen and bar environments.
| Leading Market Players |
|---|
| IKEA |
| Holland Bar Stool |
| Richardson Seating |
| Williams-Sonoma |
| Ashley Furniture Industries |
| Steelcase |
| Regal Seating |
| Trendler |
| My Bar Stools |
| Others |
Value Network & Pricing Analysis
Guangdong and Zhejiang province flat-pack polymer shell production anchors entry-level cost baselines, compressing margin capture for distributors dependent on Asian manufacturing while premium hardwood fabricators in North Carolina and Bavaria command price separation through certified substrate sourcing.
Pricing Analysis
The configured-to-order premium spreads 40-60 percent above standard SKUs, with artisan hardwood frames and performance fabric upholstery driving differentiation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and customization depth. Price erosion runs through metal-framed commercial tiers as steel input volatility and powder-coating energy costs squeeze fabricator margins. Residential renovation contractors exhibit highest price sensitivity, while hospitality procurement officers prioritize durability warranties over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate supplier-financing arrangements for import-dependent distributors, stretching working capital cycles. Manufacturing concentrates in China, Vietnam, and Mexico, with hardwood lumber drawing from Appalachian and European sustainable forestry programs. Single-source vulnerability concentrates in pneumatic lift mechanism suppliers serving adjustable-height variants. Distribution runs through wholesale furniture marts, direct-to-consumer digital storefronts, and contract hospitality specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around CARB composite wood certification and CPSC stability testing creates defensive moats for compliant domestic manufacturers, as import-dependent distributors face disproportionate compliance cost burdens.
For Market Incumbents: Pre-empt margin compression in metal-framed commercial tiers by securing captive powder-coating capacity in energy-stable geographies. Invest in water-based finish certification ahead of California chemical disclosure mandate expansion. Channel control through owned digital storefronts protects against wholesale layer consolidation. For New Entrants and Emerging Players: Build out artisan partnership networks targeting Pacific Northwest and coastal California metropolitan renovation markets where curated hardwood positioning commands premium separation. Direct-to-consumer configurators with 3D visualization tools represent the most penetrable white-space, bypassing legacy furniture mart intermediaries. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with certified substrate sourcing and established hospitality contract relationships. Long-term viability hinges on regulatory compliance infrastructure rather than pure cost position. Watch California Title 20 expansion patterns as inflection indicator for compliance investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Owned digital storefronts capture margin previously allocated to wholesale furniture mart intermediaries. |
| Artisan Partnership Network Expansion | Curated regional woodworker collaborations enable premium positioning in kitchen and bar environments. |
| Water-Based Finish Certification Investment | Early compliance with CARB regulations creates barrier-to-entry against import-dependent competitors. |
| Captive Pneumatic Mechanism Sourcing | Backward integration into adjustable-height component supply reduces single-source vulnerability. |
| Commercial Hospitality Contract Consolidation | Full-service seating collections displace fragmented sourcing across specialty stool manufacturers. |
Research Methodology
Cross-validation between primary fieldwork and secondary trade data anchors the qualitative findings. Interviews with furniture manufacturing executives, hospitality procurement officers, residential renovation contractors, and specialty retail buyers were synthesized with customs records, EPA regulatory filings, and industry association shipment data. Bottom-up segment sizing and top-down market triangulation were reconciled through iterative validation rounds.
Calibration against historical replacement cycle patterns and renovation spending indices shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade, end-use channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation and driver elasticity analysis, with steel price indices and residential construction permit data serving as key forecast inputs.
Stress conditions across raw material cost bands, regulatory enforcement intensity, and import tariff scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about compliance timeline adherence and renovation spending continuity. Macroeconomic contraction, accelerated chemical disclosure mandates, or technological substitution in seating mechanisms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
GCC Luxury Furniture Market
Furniture
Canada Home Furniture Market
Furniture
Europe Smart Furniture Market
Furniture
Pedicure Chair Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
United States Upholstered Furniture Market
Furniture
Luxury Furniture Market
Furniture
US Multifunctional Furniture Market
Furniture
Armchairs with Footrest Market
Furniture
Global Multifunctional Furniture Market
Furniture
Brazil Furniture Market
Furniture
UK Multifunctional Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
UAE Luxury Furniture Market
Furniture
Spain Furniture Market
Furniture
Russia Home Furniture Market