
 Asia-Pacific Virtual Desktop Infrastructure Market | 2026-2036
Asia-Pacific Virtual Desktop Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Virtual Desktop Infrastructure Market Insights
Multi-source procurement for virtualization licenses is consolidating as enterprises seek fewer vendors with broader platform capabilities. VMware, Inc. sustains technology leadership in desktop virtualization through deep protocol optimization. Huawei Technologies Co., Ltd. anchors its position with integrated infrastructure solutions tailored to state-owned enterprise requirements. Microsoft Corporation leverages Azure Virtual Desktop to compete across hybrid deployment scenarios.
Virtual Desktop Infrastructure delivers centralized desktop environments through server-hosted virtualization, typically operating over protocols such as HDX, PCoIP, or RDP with latency thresholds below 150 milliseconds for acceptable user experience. The architecture pools compute, storage, and network resources to stream desktop images to endpoint devices, eliminating local data retention and simplifying patch management. Cloud-based deployment now captures the fastest expansion as organizations migrate persistent workloads away from capital-intensive on-premises data centers. Managed services within the service type dimension command premium margins by absorbing operational complexity from BFSI and healthcare end users with limited internal virtualization expertise.
India's Ministry of Electronics and Information Technology enforces data localization through the Digital Personal Data Protection Act, compelling VDI providers to maintain domestic hosting infrastructure. China's SAMR and MIIT coordinate GB standards for cloud service security assessment, creating certification barriers for foreign platform vendors. Australia's TGA and the country's financial regulator impose sector-specific record-keeping rules that drive healthcare and BFSI demand for auditable virtual desktop trails. Stakeholders must weigh sovereign hosting requirements against platform interoperability when architecting multi-country deployments.
Market Dynamics
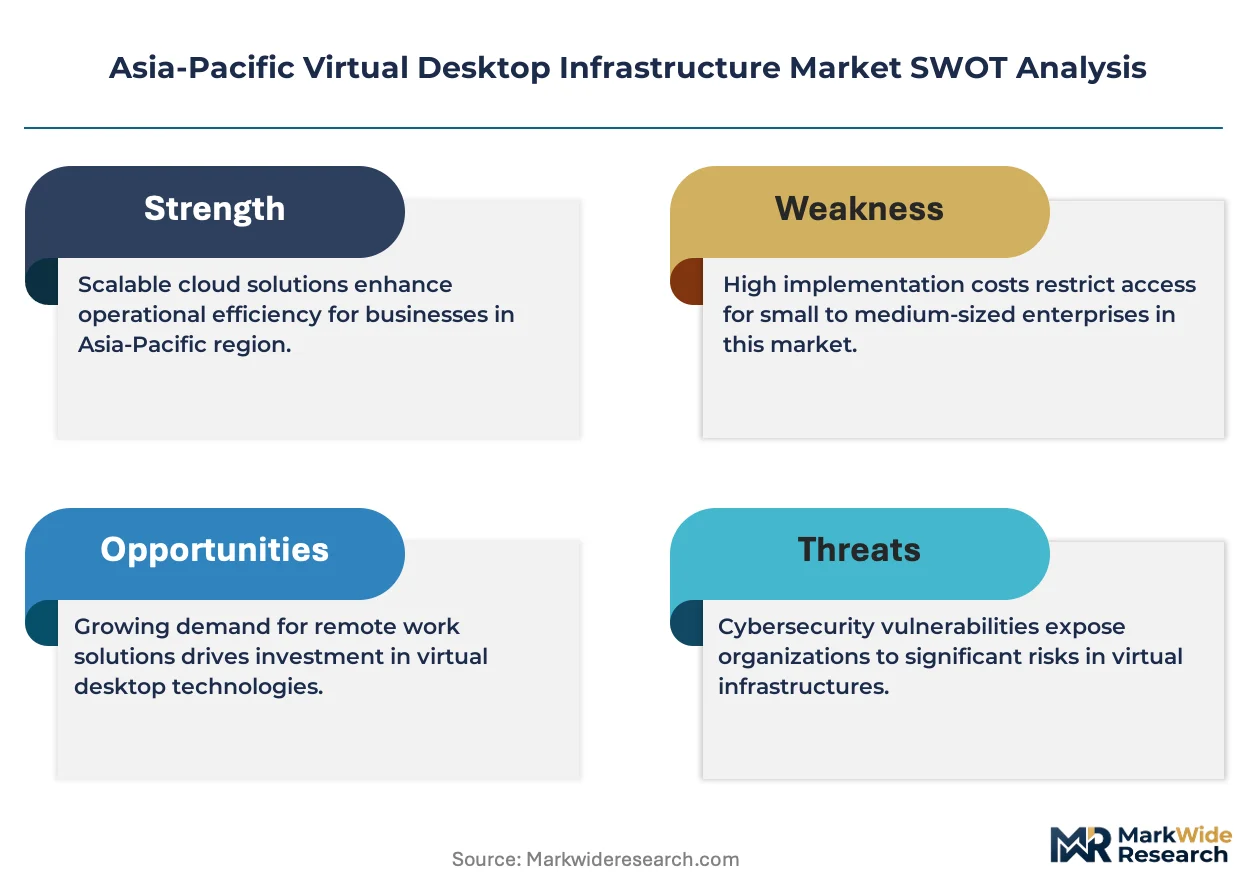
Cross-border data sovereignty mandates are fragmenting VDI architecture decisions across Asia-Pacific, forcing providers to replicate infrastructure stacks in multiple jurisdictions rather than consolidating on regional cloud hubs.
Growth Catalysts
- India's Digital Personal Data Protection Act:The data localization mandate compels healthcare and BFSI enterprises to deploy domestic-hosted virtual desktops, creating captive demand for certified local operators.
- Remote diagnostics in Southeast Asian healthcare:Teleradiology networks across Thailand, Vietnam, and Indonesia require secure endpoint isolation that VDI protocols deliver for HIPAA-equivalent patient data protection.
- GPU virtualization advances:NVIDIA vGPU and AMD MxGPU technologies enable graphics-intensive workloads on thin clients, expanding VDI from office productivity into engineering and media production segments.
Market Restraints
- Latency sensitivity:Sub-150 millisecond protocol thresholds limit viable deployment radii, constraining centralized hosting models across Australia's vast interior and Indonesia's archipelago geography.
- State-affiliated infrastructure concentration:China's state-owned enterprise procurement preferences favor domestic stack integration, creating certification barriers for foreign protocol vendors seeking SAMR cloud security assessment clearance.
- Perpetual license substitution:Browser-based workspace alternatives from SaaS-native vendors capture lightweight use cases, compressing addressable volume for full-stack VDI in sub-50 seat deployments.
Strategic Opportunities
- Philippines BPO sector expansion:Call center and back-office outsourcing clusters in Manila and Cebu present greenfield demand for multi-tenant managed desktop services with strict PCI-DSS isolation.
- Japan's METI digital workplace initiative:Post-pandemic hybrid work standardization drives public sector and manufacturing adoption of zero-trust architecture integrated with virtual desktop access.
- Edge-VDI convergence:5G MEC node deployment enables sub-20 millisecond desktop streaming for field engineering and construction management in Australia's mining and energy corridors.
Industry Challenges
- Certification timeline compression:Australia's TGA and financial sector auditors demand auditable session logging and data residency documentation that extends sales cycles by 4-6 months for foreign platform vendors.
- Legacy application virtualization:Windows-dependent line-of-business systems in India's public sector and China's industrial base resist containerization, requiring costly per-application compatibility engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Virtual Desktop Infrastructure Market |
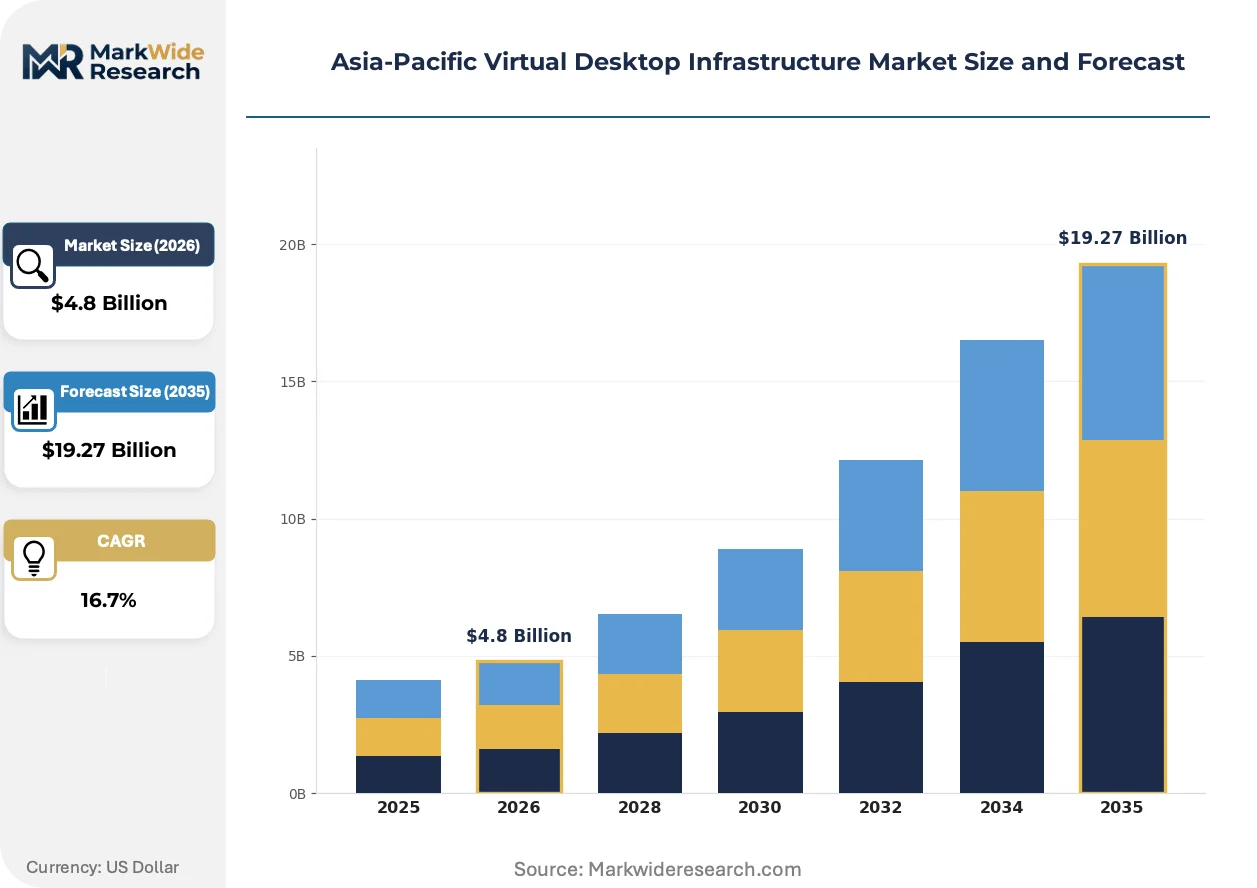
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Healthcare, Education, BFSI, Manufacturing Solution Type: Infrastructure Solutions, Desktop Virtualization, Application Virtualization, Security Solutions Service Type: Managed Services, Consulting, Support Services, Integration Services |
| Companies Covered | Microsoft Corporation, VMware, Inc., Citrix Systems, Inc., Cisco Systems, Inc., Dell Technologies, Inc., Hewlett Packard Enterprise Company, Amazon.com, Inc., IBM Corporation, Huawei Technologies Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Virtual Desktop Infrastructure Market Trends and Innovations
Protocol optimization and sovereign cloud architecture are converging to redefine competitive differentiation in Asia-Pacific VDI delivery, with latency engineering and compliance automation emerging as primary value levers.
GPU-accelerated desktop virtualization is absorbing graphics-intensive workloads previously tethered to physical workstations. Engineering firms in South Korea and Australia's resources sector deploy virtualized CAD and seismic analysis environments at scale. This technology compression is absorbing high-margin workstation hardware revenue into software-defined infrastructure contracts.
China's GB standards for cloud service security assessment establish mandatory third-party evaluation for all government and critical infrastructure VDI deployments. Foreign vendors face extended certification queues through MIIT and SAMR coordination. Healthcare and state-owned enterprise segments are responding by pre-qualifying domestic-integrated stack providers before tender issuance.
Subscription-based managed desktop services displace perpetual license procurement across mid-market BFSI and professional services segments. Channel partners in Singapore and Hong Kong consolidate deployment and support under single-vendor accountability. This behavioral pivot concentrates procurement authority with systems integrators possessing sovereign hosting credentials rather than traditional software resellers.
Asia-Pacific Virtual Desktop Infrastructure Market Segmentation
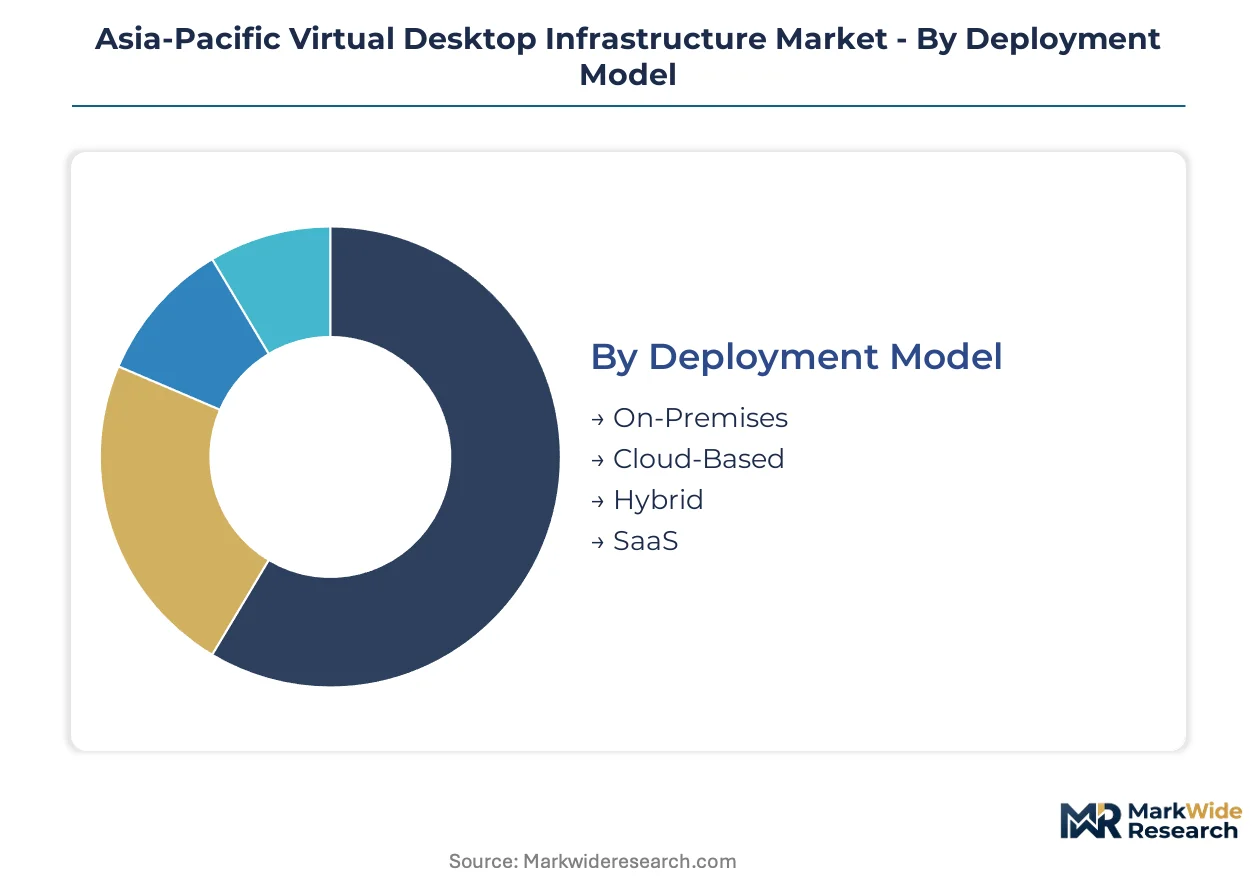
VDI procurement patterns across Asia-Pacific diverge sharply by control requirements and data sovereignty exposure. Deployment architecture choices determine compliance posture against India's localization mandates and China's GB certification regimes. End-user verticals impose distinct latency, graphics, and audit trail specifications that reshape solution packaging.
Deployment Model:
Standardization dominates at the infrastructure layer while customization proliferates at the policy and integration layers across this category.
- On-Premises:Enterprises retain full hardware ownership with dedicated server clusters in domestic data centers. India's BFSI sector and China's state-owned enterprises favor this model to satisfy RBI and SAMR data residency audits.
- Cloud-Based:Third-party hosted virtual desktops eliminate capital expenditure and shift operational burden to providers. Healthcare networks in Thailand and Vietnam deploy cloud-based VDI for rapid teleradiology scaling without facility construction.
- Hybrid:Workload portability between private infrastructure and public cloud accommodates burst capacity and disaster recovery. Australian mining operators use hybrid deployments to maintain core operations on-premises while leveraging cloud for remote site expansion.
- SaaS:Fully managed desktop-as-a-service abstracts all infrastructure decisions behind per-user subscriptions. Mid-market professional services firms in Singapore and Hong Kong adopt SaaS delivery to bypass internal virtualization expertise gaps.
Leading the category by volume: On-Premises. Expanding most quickly: Cloud-Based.
End User:
Regulatory intensity and endpoint sensitivity sort vertical demand into discrete procurement tiers with specialized certification requirements.
- Healthcare:Diagnostic imaging and electronic health record access demand GPU-accelerated protocols and session-level encryption. Southeast Asian hospital networks prioritize VDI for radiologist remote access with HIPAA-equivalent audit trails.
- Education:Seasonal enrollment spikes and device heterogeneity drive consumption-based licensing. Indian universities deploy virtual labs to standardize software access across fragmented student device populations.
- BFSI:PCI-DSS isolation and trader surveillance requirements mandate dedicated infrastructure segments. Manila and Cebu BPO clusters represent concentrated demand for multi-tenant managed desktops with strict data compartmentalization.
- Manufacturing:Shop floor thin clients and engineering workstation virtualization coexist within unified architectures. South Korean automotive and electronics producers integrate VDI with MES systems for real-time production monitoring.
Dominant by revenue: BFSI. Climbing the fastest: Healthcare.
Solution Type:
Technology stack depth separates turnkey platform providers from component specialists with narrow integration scope.
- Infrastructure Solutions:Server, storage, and networking hardware bundled with hypervisor licensing. Huawei anchors this segment with integrated stacks pre-certified for Chinese government procurement.
- Desktop Virtualization:Core broker and protocol software enabling persistent and non-persistent desktop pools. VMware's protocol optimization maintains technology leadership for latency-sensitive financial trading floors.
- Application Virtualization:Streamed application delivery without full desktop encapsulation. Legacy Windows-dependent systems in India's public sector resist containerization, sustaining demand for per-application compatibility engineering.
- Security Solutions:Zero-trust access controls, session recording, and data loss prevention overlays. Japan's METI digital workplace initiative accelerates security-integrated VDI adoption across public sector and manufacturing.
Highest margin concentration: Security Solutions. Broadest addressable base: Desktop Virtualization.
Service Type:
Operational complexity absorption determines whether procurement centers on software licensing or outcome-based accountability.
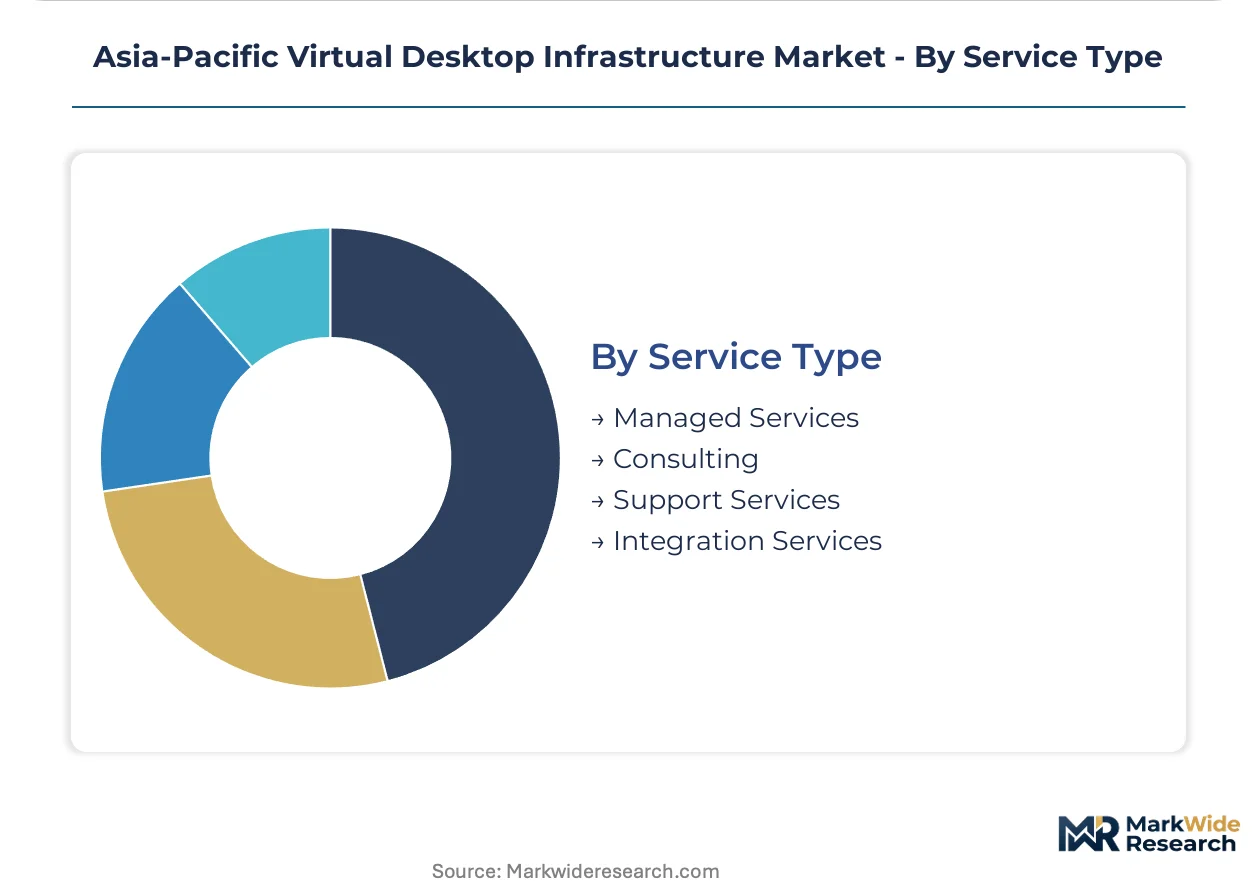
- Managed Services:End-to-end desktop lifecycle management including patching, capacity planning, and help desk. Australian healthcare and BFSI organizations with limited internal virtualization expertise pay premium margins for single-vendor accountability.
- Consulting:Architecture design and compliance mapping for multi-jurisdiction deployments. Foreign vendors navigating China's GB certification queues engage local consultants to compress SAMR and MIIT evaluation timelines.
- Support Services:Break-fix and technical assistance for self-managed implementations. Mid-market manufacturing in Indonesia and Malaysia consumes support services to maintain on-premises VDI without full outsourcing.
- Integration Services:Custom connector development and legacy system bridging. Channel partners in Singapore consolidate deployment and support under integration-led contracts with sovereign hosting credentials.
Fastest value capture: Managed Services. Most price-pressured: Support Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center infrastructure across the Asia-Pacific region anchors VDI deployment decisions, with submarine cable landing points and domestic cloud regions determining latency engineering requirements for virtual desktop delivery.
China
State-owned enterprises in Beijing and Shanghai drive demand for integrated infrastructure stacks with domestic certification. MIIT and SAMR coordinate GB standards for cloud service security assessment, creating mandatory third-party evaluation queues for government VDI deployments. Yangtze River Delta manufacturing clusters deploy virtualized engineering workstations for automotive and electronics design.
India
IT hub cities Mumbai, Bangalore, and Hyderabad concentrate BFSI and healthcare demand for data-localized virtual desktops. The Digital Personal Data Protection Act enforces strict data localization, compelling providers to maintain domestic hosting infrastructure. Indian universities in Delhi-NCR and Chennai deploy virtual labs to standardize software access across fragmented student device populations.
Australia
Financial centers Sydney and Melbourne generate premium demand for auditable virtual desktop trails with sub-150 millisecond protocol thresholds. TGA and financial sector auditors impose sector-specific record-keeping rules that extend sales cycles for foreign platform vendors. Western Australia mining corridors explore edge-VDI convergence over 5G MEC nodes for field engineering applications.
Japan
Tokyo and Osaka manufacturing conglomerates integrate VDI with MES systems for real-time production monitoring. METI's digital workplace initiative accelerates zero-trust architecture adoption across public sector and automotive supply chains. Kansai region engineering firms deploy GPU-accelerated virtualized CAD environments at scale.
Singapore
Channel partners and systems integrators in the city-state consolidate deployment and support under single-vendor accountability with sovereign hosting credentials. Mid-market professional services firms adopt SaaS desktop delivery to bypass internal virtualization expertise gaps. Singapore serves as regional coordination hub for multi-country compliance architecture across Southeast Asian deployments.
Asia-Pacific Virtual Desktop Infrastructure Market Competitive Landscape
Global majors compete with regional champions across protocol optimization and sovereign hosting credentials, producing a tiered structure where technology depth separates platform providers from component specialists. Consolidation pressure favors vendors with integrated infrastructure stacks capable of satisfying multi-jurisdiction compliance requirements. Three archetypes dominate: full-stack platform providers, specialized protocol optimizers, and sovereign-integrated domestic champions. Competitive moves center on strategic partnerships with local systems integrators and geographic expansion through certification queue navigation.
Within the full-stack platform tier, Microsoft Corporation and VMware, Inc. occupy positions defined by hybrid cloud and protocol engineering capabilities respectively. Huawei Technologies Co., Ltd. anchors the sovereign-integrated archetype with domestic certification advantages in state-affiliated procurement channels. These three entities exemplify the competitive tension between global technology breadth and regional compliance depth that shapes procurement decisions across Asia-Pacific enterprise segments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| VMware, Inc. |
| Citrix Systems, Inc. |
| Cisco Systems, Inc. |
| Dell Technologies, Inc. |
| Hewlett Packard Enterprise Company |
| Amazon.com, Inc. |
| IBM Corporation |
| Huawei Technologies Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Captive hosting infrastructure in China, India, and Australia anchors supply positioning while simultaneously constraining pricing flexibility for foreign platform vendors facing certification queues. Domestic-integrated stack providers leverage this vertical control to command premium positioning in state-affiliated procurement channels, whereas global vendors absorb margin compression to secure sovereign hosting partnerships.
Pricing Analysis
Managed service bundling dominates Asia-Pacific VDI procurement, with subscription tiers separating basic protocol access from comprehensive lifecycle management including patching, capacity planning, and compliance documentation. Price differentiation hinges on certification grade—GB assessment clearance for China, DPDP Act compliance for India—and volume scale across seat deployments. Cost compression in mid-market SaaS tiers intensifies as browser-based workspace alternatives capture lightweight use cases. Healthcare and BFSI segments demonstrate lowest price sensitivity due to audit trail mandates, while education and sub-50 seat manufacturing deployments exhibit highest sensitivity to per-user subscription costs.
Supply Chain Analysis
Submarine cable latency costs and domestic data center construction expenses concentrate supply chain decisions in China, India, and Singapore, where sovereign hosting infrastructure determines viable deployment radii. Hardware components draw from Taiwan for server silicon, South Korea for memory modules, and domestic Chinese manufacturers for integrated stack assembly. Single-source vulnerability persists in GPU virtualization accelerators from NVIDIA and AMD, creating procurement bottlenecks for graphics-intensive workloads. Distribution runs through systems integrators possessing multi-jurisdiction compliance credentials rather than traditional software resellers, concentrating channel power in Singapore and Hong Kong coordination hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified domestic hosting capacity functions as the binding constraint propping pricing power across Asia-Pacific VDI markets, with queue lengths for GB assessment and DPDP Act compliance extending sales cycles and limiting vendor contestability.
For Market Incumbents: To counter emerging domestic champions in China and India, VMware and Microsoft must accelerate sovereign cloud partnership investments in Mumbai, Bangalore, and Shanghai data center zones. Certification queue navigation capabilities represent the critical defensive lever, requiring dedicated local regulatory affairs teams to compress MIIT, SAMR, and MeitY evaluation timelines. Channel control consolidation through exclusive systems integrator arrangements in Singapore and Hong Kong protects multi-country deployment margins. For New Entrants and Emerging Players: Mid-market professional services firms in Singapore and Hong Kong present the most penetrable buyer archetype, with virtualization expertise gaps driving demand for fully managed desktop-as-a-service. Philippine BPO clusters in Manila and Cebu offer greenfield expansion opportunity given PCI-DSS isolation requirements and limited incumbent saturation. Go-to-market execution should prioritize sovereign hosting credentials over protocol optimization depth, partnering with established domestic data center operators to bypass certification barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by global platform vendors seeking sovereign hosting capabilities and regional certification expertise. Long-term viability hinges on five-to-ten year regulatory trajectory alignment, with data localization mandates across India, China, and Australia structurally favoring domestic-integrated providers. The signal to watch is queue length compression at MIIT and SAMR, which would indicate regulatory opening for foreign vendor re-entry and corresponding valuation pressure on domestic champions.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Domestic data center alliances in Mumbai and Shanghai bypass DPDP Act and GB certification queues for foreign vendors. |
| Protocol Optimization Investment | Sub-20 millisecond latency engineering for 5G MEC nodes captures Australian mining and energy corridor demand. |
| Managed Service Consolidation | Single-vendor accountability models absorb operational complexity from BFSI and healthcare buyers with limited virtualization expertise. |
| GPU Virtualization Integration | NVIDIA vGPU and AMD MxGPU enablement expands addressable market from office productivity into engineering and media production segments. |
| Systems Integrator Acquisition | Singapore and Hong Kong channel partners with sovereign hosting credentials concentrate procurement authority and multi-country deployment control. |
Research Methodology
Regulatory filings, hyperscaler capex disclosures, and hospital procurement databases formed the secondary backbone of this analysis, supplemented by customs records tracking server and networking hardware imports across Asia-Pacific markets. Primary interviews with CTOs, IT procurement officers at BFSI and healthcare enterprises, channel partners, and integration specialists validated deployment architecture preferences and compliance cost structures. Bottom-up triangulation across these sources anchored segmentation-level estimates, while top-down cross-checks against aggregate virtualization software revenue disclosures ensured consistency.
Historical trendline analysis of virtualization license procurement patterns, cloud migration trajectories, and managed services adoption rates informed the projection framework across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user vertical, solution stack depth, and service type accountability. CAGRs derived from curve-fitting observed adoption velocities against regulatory milestone timelines, with GPU virtualization penetration and sovereign hosting capacity buildout serving as key industry-specific forecast inputs.
Revisions become necessary when data localization mandates expand to additional Asia-Pacific jurisdictions, when GB certification queues compress dramatically altering vendor contestability, or when 5G MEC deployment accelerates faster than anticipated enabling edge-VDI convergence. Stakeholders should weight assumptions against their own operating context, particularly regarding internal virtualization expertise depth and multi-country compliance architecture requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Colocation Edge Data Center Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
Ireland Data Center Physical Security Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Australia Data Center Construction Market
Data Center Infrastructure
Canada Data Center Power Market
Data Center Infrastructure
United Arab Emirates Data Center Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Norway Data Center Server Market