
 Global Datacenter Deployment Spending Market | 2026-2036
Global Datacenter Deployment Spending Market Size, Share, and Industry Trends Forecast 2026-2036
Global Datacenter Deployment Spending Market Foresight
The capital-intensity divergence between hyperscale builders and regional colocation providers is collapsing as both classes pursue identical power-dense, liquid-cooled footprints. Microsoft leverages its vertical integration across fiber, land, and generation capacity to compress deployment timelines. Equinix anchors its interconnection density strategy in metro-adjacent campuses where cross-connect revenue sustains premium economics. NTT Communications Corporation competes through modular build-to-suit contracts that reduce customer capital commitment.
Datacenter deployment spending encompasses capital and operational outlays for facility construction, mechanical and electrical infrastructure, IT equipment installation, and ongoing systems integration required to bring compute environments into production service. These investments typically specify power densities exceeding 50 kilowatts per rack, direct liquid cooling loops, and redundant electrical topologies to sustain availability above 99.999 percent for enterprise and cloud workloads. Hyperscale deployment models now absorb the dominant share of annual investment as single-campus capacities exceed one gigawatt, while edge configurations represent the fastest-growing structural segment driven by latency-sensitive applications in manufacturing and autonomous systems. Solution offerings cluster around Infrastructure as a Service and managed hosting where margin pools remain deepest, though disaster recovery services are gaining share among financial institutions facing operational resilience mandates.
The EPA ENERGY STAR program and the EU Energy Efficiency Directive shape facility design standards, with both frameworks pushing measurable power usage effectiveness thresholds and embodied carbon disclosure. The IRA production tax credits in the United States and the EU Green Deal taxonomy are redirecting deployment capital toward on-site solar, battery storage, and grid-interactive designs. Stakeholders must monitor evolving grid interconnection queues and utility tariff structures as these become the binding constraint on deployment velocity in every major cluster market.
Market Dynamics
Power density thresholds above 50 kilowatts per rack are compressing mechanical infrastructure refresh cycles from seven years to under four, forcing simultaneous capital redeployment across cooling, electrical, and compute layers.
Growth Catalysts
- EU Energy Efficiency Directive:Mandated power usage effectiveness disclosure is accelerating facility redesigns toward liquid cooling and renewable power sourcing across European deployments.
- Autonomous systems manufacturing:Latency requirements below 10 milliseconds are pulling edge datacenter investment into industrial zones around Stuttgart, Detroit, and Shenzhen.
- Northern Virginia cluster concentration:Pre-approved substations and fiber rights-of-way are compressing utility interconnection timelines relative to secondary markets.
Market Restraints
- Copper and electrical steel input volatility:Transformer and busbar lead times now extend 18-24 months, freezing project schedules for facilities lacking advance procurement positions.
- Taiwan semiconductor equipment concentration:Lithography and advanced packaging tool availability constrains server supply elasticity, creating deployment bottlenecks independent of facility readiness.
- Grid interconnection queue depth:FERC Order 2023 compliance delays across US independent system operators are extending energization timelines 12-36 months beyond construction completion.
Strategic Opportunities
- Brazil underpenetration:São Paulo metro latency to Miami exceeds 120 milliseconds, creating arbitrage for Portuguese-speaking Latin American cloud delivery without US data residency exposure.
- Grid-interactive battery storage:IRA production tax credits are enabling revenue-stacking models where datacenter batteries participate in frequency regulation markets during off-peak compute periods.
- Modular build-to-suit contracts:Japanese manufacturing conglomerates are accepting operational lease structures that transfer construction risk to facility operators while preserving balance sheet capacity.
Industry Challenges
- Medium-voltage electrical commissioning:Utilities face acute shortages of relay technicians and protection engineers capable of synchronizing multi-megawatt datacenter loads with transmission stability requirements.
- CSRD embodied carbon disclosure:Scope 3 supply chain documentation demands are extending equipment procurement cycles as vendors lack verified Environmental Product Declarations for legacy product lines.
- Direct liquid cooling integration:Retrofit of existing air-cooled facilities requires simultaneous redesign of fire suppression, structural loading, and facility water treatment systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Datacenter Deployment Spending Market |
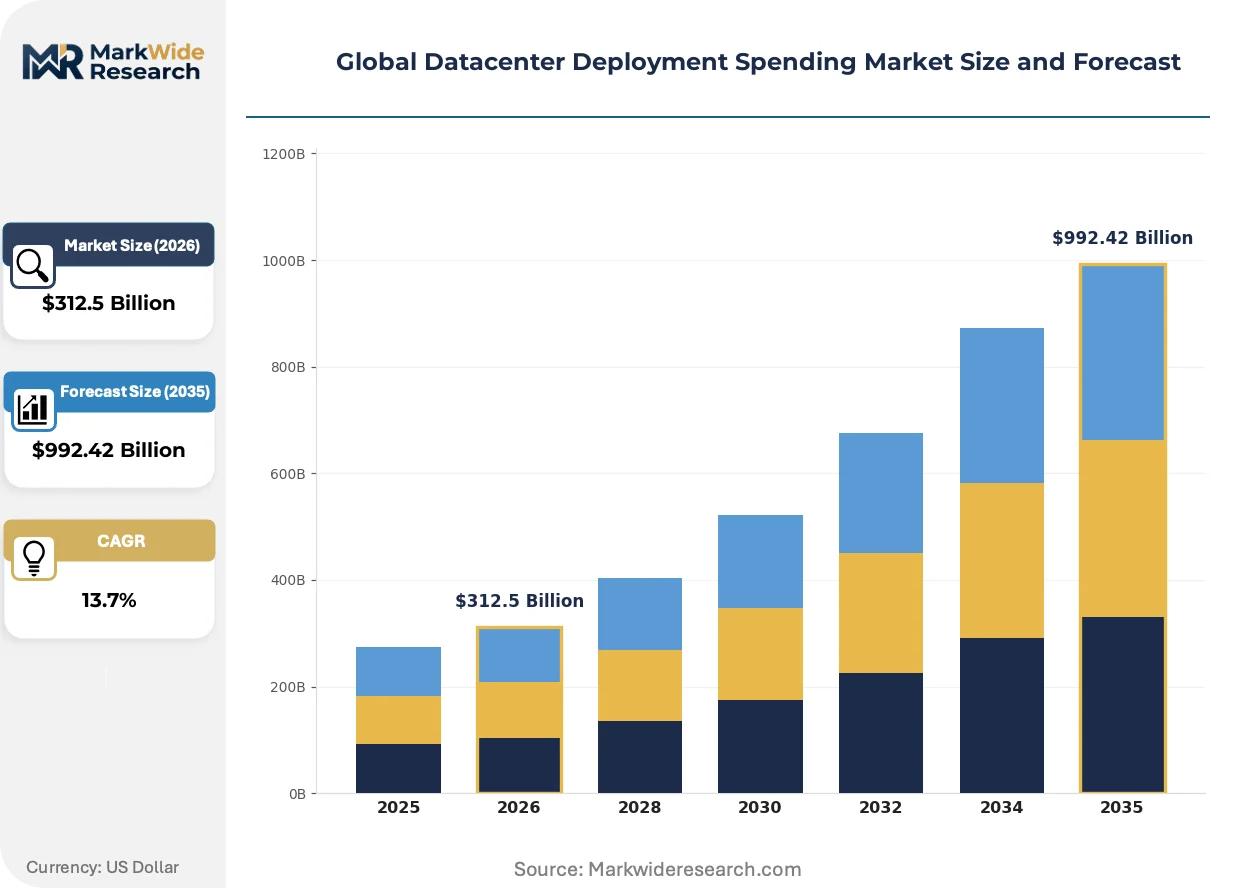
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $992.42 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Colocation, Hyperscale, Edge, Enterprise, Modular Solution Offering: Infrastructure as a Service, Managed Hosting, Dedicated Hosting, Cloud Migration, Disaster Recovery Use Case: Cloud Storage, High Performance Computing, Content Delivery, Virtual Desktop Infrastructure, Big Data Analytics End User Type: Telecom Operators, Financial Institutions, E-commerce Firms, Media Companies, Government Agencies |
| Companies Covered | Microsoft, IBM, Google Cloud, Digital Realty, Equinix, NTT Communications Corporation, Cisco Systems, Amazon Web Services, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Datacenter Deployment Spending Market Shifts & Advancements
Deployment architectures are fragmenting into three distinct models—hyperscale campuses, modular edge nodes, and retrofit brownfield conversions—each demanding incompatible supply chain and skill configurations.
Immersion cooling using synthetic dielectric fluids is decomposing the traditional separation between IT and facilities engineering. Hyperscale operators in Singapore and Frankfurt are adopting single-phase immersion for GPU-intensive training clusters, collapsing the mechanical infrastructure footprint by 40 percent and enabling rack densities exceeding 100 kilowatts. This compression is decomposing the vendor landscape as traditional chiller manufacturers lose specification control to fluid chemistry and tank fabrication specialists.
REACH restriction proposals on per- and polyfluoroalkyl substances are forcing refrigerant transitions in European mechanical systems. The F-Gas Regulation phasedown is accelerating adoption of ammonia and CO2 chillers in Nordic facilities, while southern European operators face higher capital costs for low-global-warming-potential alternatives. German and French facility operators are responding by relocating compute-intensive workloads to Nordic campuses with ambient cooling availability.
Enterprise buyers are consolidating procurement authority into centralized infrastructure teams with direct hyperscale contracting relationships. Traditional systems integrators and value-added resellers are losing specification influence as FinOps platforms enable real-time workload placement across owned, colocation, and public cloud assets. This consolidation is most visible among North American financial services institutions subject to operational resilience mandates from the SEC and Federal Reserve.
Global Datacenter Deployment Spending Market Segmentation
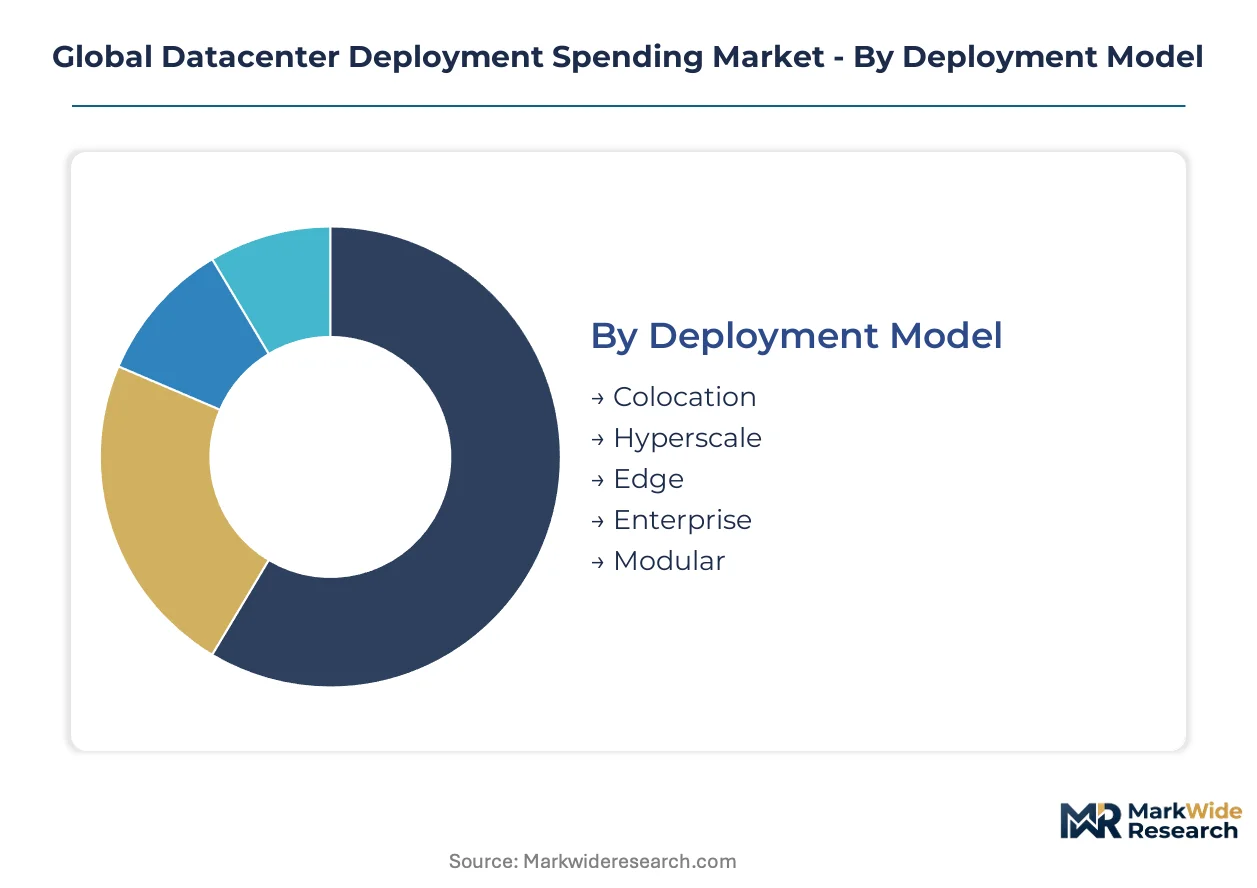
Deployment spending patterns diverge sharply across facility architectures and service delivery models. Capital allocation strategies differ fundamentally between wholesale hyperscale builds and distributed edge configurations. Procurement authority is consolidating around workload-specific requirements rather than traditional infrastructure categories.
Deployment Model:
Geographic concentration varies by scale tier, with hyperscale campuses clustering in Northern Virginia and Dallas-Fort Worth while edge nodes distribute across industrial zones in Germany, China, and the United States.
- Hyperscale:Single-campus capacities now exceed one gigawatt, requiring synchronized procurement across land, power, and fiber rights-of-way. Demand concentrates in United States cluster zones where pre-approved substations compress utility interconnection timelines relative to secondary markets.
- Edge:Latency requirements below 10 milliseconds are pulling investment into manufacturing corridors around Stuttgart, Detroit, and Shenzhen. GPU-intensive inference workloads are driving rack densities above 50 kilowatts in these distributed configurations.
- Colocation:Metro-adjacent campuses sustain premium economics through cross-connect density and interlocking carrier relationships.
- Enterprise:On-premise builds persist among financial institutions facing operational resilience mandates from the SEC and Federal Reserve.
- Modular:Japanese manufacturing conglomerates are accepting operational lease structures that transfer construction risk to facility operators while preserving customer balance sheet capacity.
Hyperscale holds the largest share; momentum sits with Edge.
Solution Offering:
Margin pools concentrate where operational complexity transfers from customer to provider, with infrastructure abstraction commanding premium pricing over raw capacity.
- Infrastructure as a Service:Abstracted compute and storage resources delivered through API-driven provisioning. Financial institutions in the United States are consolidating procurement authority into centralized infrastructure teams with direct hyperscale contracting relationships for this delivery model.
- Disaster Recovery:Synchronous replication and failover orchestration for operational resilience compliance. European banks facing CSRD mandates are extending procurement cycles to secure verified Environmental Product Declarations for underlying infrastructure.
- Managed Hosting:Facility operations and hardware lifecycle management bundled with physical security and network operations.
- Dedicated Hosting:Single-tenant environments with customized power and cooling specifications.
- Cloud Migration:Workload assessment, replatforming, and cutover services for enterprise transformation programs.
Infrastructure as a Service generates the deepest margin pools; Disaster Recovery is climbing the fastest.
Use Case:
Compute intensity and latency tolerance determine facility selection, with training workloads seeking Nordic ambient cooling and inference workloads distributing toward population centers.
- High Performance Computing:GPU clusters for scientific simulation and generative AI training. Singapore and Frankfurt operators are adopting single-phase immersion cooling, collapsing mechanical infrastructure footprints by 40 percent and enabling rack densities exceeding 100 kilowatts.
- Content Delivery:Caching and streaming optimization for sub-50 millisecond response times. Media companies are driving edge node placement in Brazil where São Paulo metro latency to Miami exceeds 120 milliseconds.
- Cloud Storage:Durable object and block storage with multi-region replication.
- Virtual Desktop Infrastructure:Centralized workstation virtualization for secure remote access.
- Big Data Analytics:Distributed processing frameworks for enterprise data warehouse modernization.
High Performance Computing commands the highest capital intensity per rack; Content Delivery is gaining share fastest.
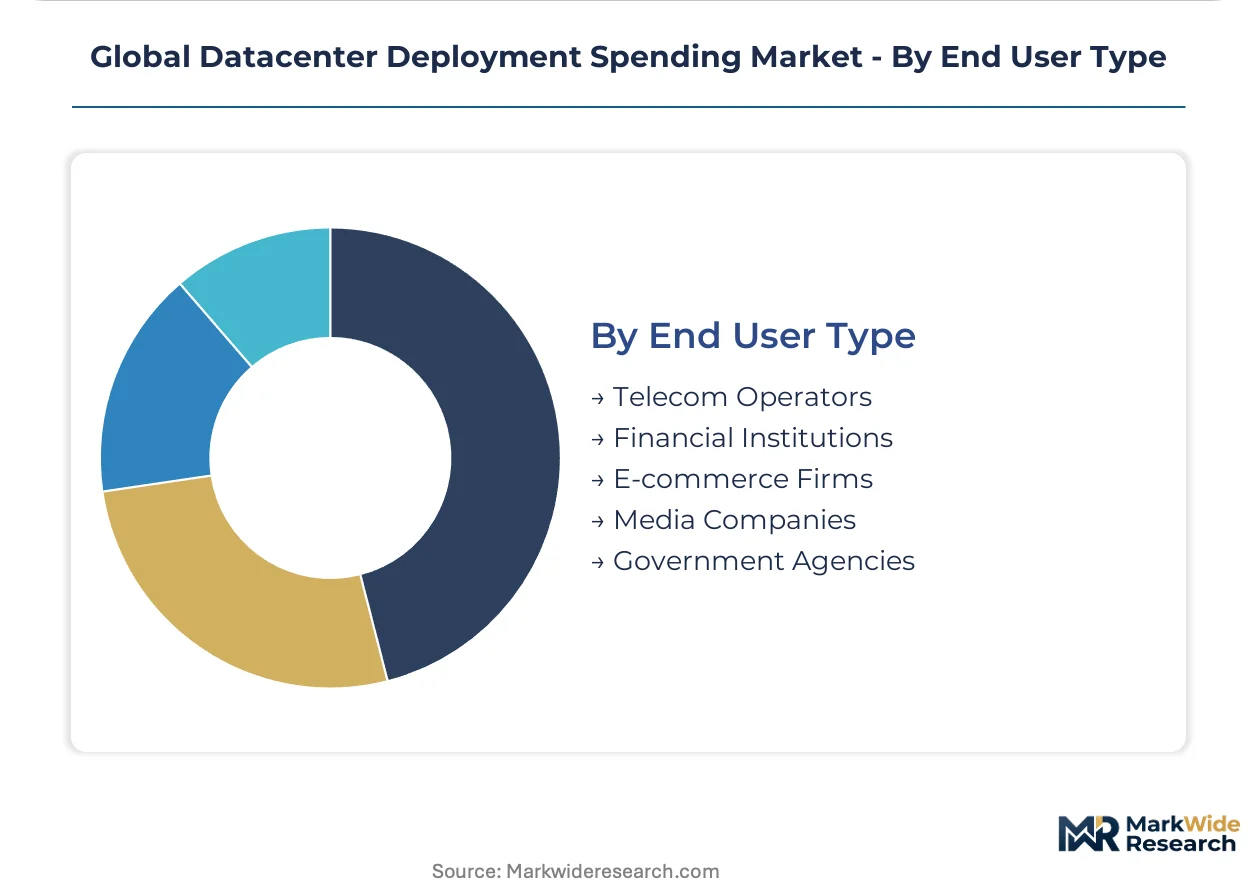
End User Type:
Regulatory exposure and latency sensitivity segment procurement behavior, with financial services prioritizing resilience certification and media companies optimizing for geographic distribution.
- Financial Institutions:Operational resilience mandates from the SEC and Federal Reserve are driving synchronous replication architectures and dedicated facility requirements. These buyers are consolidating procurement authority into centralized infrastructure teams with direct hyperscale relationships.
- E-commerce Firms:Seasonal demand volatility and global customer bases require elastic capacity with local data residency compliance.
- Telecom Operators:Edge infrastructure for 5G network function virtualization and multi-access edge computing.
- Media Companies:Content delivery optimization and live streaming infrastructure with geographic redundancy.
- Government Agencies:FedRAMP and comparable national security certifications for sovereign cloud deployments.
Financial Institutions anchor premium pricing; E-commerce Firms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Brazil exhibit the highest price elasticity for colocation services, while financial institutions in the United States and Germany absorb substantial premiums for resilience certification and sub-millisecond latency guarantees.
United States
Hyperscale operators command deployment timelines measured in months rather than years through pre-approved substations and fiber rights-of-way. FERC Order 2023 compliance delays across independent system operators are extending energization timelines 12-36 months beyond construction completion. Northern Virginia and Dallas-Fort Worth cluster zones concentrate over half of domestic capacity additions.
Germany
Industrial automation and automotive AI training are pulling GPU-intensive workloads into manufacturing corridors around Stuttgart. The EU Energy Efficiency Directive mandates power usage effectiveness disclosure, accelerating facility redesigns toward liquid cooling. Frankfurt operators are adopting single-phase immersion cooling for densities exceeding 100 kilowatts per rack.
Singapore
Tropical ambient conditions and land scarcity are forcing mechanical innovation as operators deploy synthetic dielectric fluid immersion systems. The country's national environmental regulator enforces strict cooling efficiency standards under tropical data center guidelines. Marina Bay and Changi Business Park campuses anchor Southeast Asian cloud delivery.
Brazil
São Paulo metro latency to Miami exceeds 120 milliseconds, creating arbitrage for Portuguese-speaking Latin American cloud delivery without United States data residency exposure. ANVISA and central bank data localization rules are compelling domestic facility investment. Campinas and São Paulo state industrial zones are absorbing modular edge deployments for manufacturing AI inference.
Japan
Manufacturing conglomerates are accepting operational lease structures that transfer construction risk to facility operators while preserving balance sheet capacity. METI efficiency standards and grid stability requirements are shaping facility electrical topology specifications. Osaka and Tokyo metro campuses sustain premium interconnection economics through submarine cable landing density.
Global Datacenter Deployment Spending Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Hyperscale cloud operators absorb the dominant share of annual investment through vertical control across land, power, and fiber assets. Regional colocation providers and telecommunications infrastructure specialists constitute the remaining competitive tiers. Capacity expansion and strategic partnerships with utility operators represent the dominant competitive moves as grid interconnection queues become the binding constraint on deployment velocity.
Among hyperscale cloud operators, Microsoft and Amazon Web Services exemplify the integrated infrastructure archetype through captive control of deployment timelines. Equinix occupies a position within the interconnection-centric tier, anchoring metro-adjacent campus strategies where cross-connect density sustains premium economics. NTT Communications Corporation represents the modular build-to-suit specialist archetype, accepting operational lease structures that reduce customer capital commitment.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Google Cloud |
| Digital Realty |
| Equinix |
| NTT Communications Corporation |
| Cisco Systems |
| Amazon Web Services |
| Hewlett Packard Enterprise |
| Others |
Supply & Pricing Matrix
Long-term power purchase agreements with take-or-pay structures dominate hyperscale contracting, locking in renewable energy supply visibility while capping exposure to utility tariff volatility across United States cluster markets. These arrangements transfer interconnection queue risk to offtakers while preserving developer margin through capacity reservation fees.
Pricing Analysis
Service revenue from liquid cooling infrastructure lifecycle management now drives lifetime value for facility operators. Three-tier pricing structure across premium, standard, and economy levels separates Tier III+ certified campuses with sub-millisecond latency guarantees from modular edge configurations with basic redundancy. Cost compression in standard-tier colocation is intensifying because hyperscale self-build programs are absorbing anchor-tenant demand. Financial institutions exhibit the lowest price sensitivity, while e-commerce firms and media companies negotiate aggressively on per-kilowatt rates.
Supply Chain Analysis
Transformer and switchgear lead times stretching beyond eighteen months are freezing project schedules for operators lacking advance procurement positions. Manufacturing concentrates in China, Germany, and the United States for electrical infrastructure, while Taiwan and South Korea dominate semiconductor equipment supply. Copper busbar and electrical steel dependencies create vulnerability to commodity price swings. Single-source concentration for lithography tools from Dutch and Japanese suppliers presents regulatory restriction exposure. Distribution runs through EPC contractors with utility relationships rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as financial institutions and hyperscale cloud operators consolidate procurement authority into centralized infrastructure teams, fragmenting the vendor base across incompatible technical specifications.
For Market Incumbents: Secure pre-approved substation positions in Northern Virginia and Dallas-Fort Worth before FERC Order 2023 compliance delays deepen interconnection queue backlogs. Anchor interconnection density in metro-adjacent campuses where cross-connect revenue sustains premium economics against modular build-to-suit competitors. Vertical integration into captive renewable generation preserves margin against utility tariff volatility. For New Entrants and Emerging Players: EPA ENERGY STAR fast-track certification offers entry into United States federal contracting channels with reduced compliance friction. Target Brazil's underpenetrated Portuguese-speaking Latin American cloud delivery market where São Paulo metro latency exceeds 120 milliseconds to Miami. Pursue grid-interactive battery storage revenue-stacking models enabled by IRA production tax credits as a differentiated service layer. For Investors and Strategic Acquirers: The market sits at a capital-intensity consolidation phase that favors facility operators with synchronized land, power, and fiber control. Long-term viability hinges on exposure to cluster markets with pre-approved utility infrastructure rather than secondary locations facing interconnection delays. Acquisition targets should demonstrate operational lease structures preserving customer balance sheet capacity. Monitor FERC Order 2023 implementation pace as the signal for deployment velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-approved Substation Acquisition | Compresses utility interconnection timelines in Northern Virginia cluster zones relative to secondary markets. |
| Liquid Cooling Infrastructure Deployment | Enables rack densities exceeding 100 kilowatts for GPU-intensive training clusters in Singapore and Frankfurt. |
| Grid-Interactive Battery Storage Integration | Stacks IRA production tax credits with frequency regulation market participation during off-peak compute periods. |
| Modular Build-to-Suit Contracting | Transfers construction risk to operators while preserving Japanese manufacturing conglomerate balance sheet capacity. |
| Cross-Connect Density Expansion | Sustains premium economics in metro-adjacent campuses through interlocking carrier relationships. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with datacenter facility engineers, utility interconnection planners, hyperscale procurement executives, and EPC project managers. Secondary validation drew from FERC interconnection queue filings, EPA ENERGY STAR certification databases, EU Energy Efficiency Directive implementation reports, and hyperscaler capital expenditure disclosures. Bottom-up facility-level capacity builds were triangulated against top-down regional demand projections.
Across the projection horizon, the analytical framework modeled deployment spending across facility architecture tiers, solution delivery models, compute intensity use cases, and regulatory compliance segments. CAGRs were derived from facility pipeline tracking and utility interconnection approval velocity. Key inputs included power density evolution curves, liquid cooling adoption rates, and renewable energy procurement contract structures.
Underlying assumptions cover sustained hyperscale expansion, stable utility tariff structures, and semiconductor equipment supply normalization, with deviation risk concentrated in FERC Order 2023 implementation delays and Taiwan semiconductor equipment availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
Data Center Power Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
Data Center IT Asset Disposition Market
Data Center Infrastructure
Blade Server Market
Data Center Infrastructure
Middle East and Africa Containerized Data Center Market
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
Austria Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
New Zealand Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
Asia-Pacific Data Center Market