
 Data Center As a Service Market | 2026-2036
Data Center As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center As a Service Market Intelligence
Asset-light leasing and project finance structures is fragmenting competitive dynamics in data center infrastructure, allowing non-traditional operators to scale without balance-sheet intensity. Microsoft Corporation leverages its Azure stack to anchor enterprise hybrid deployments across multiple geographies. Equinix, Inc. controls premium interconnection real estate in strategic metro markets. Huawei Technologies Co., Ltd. competes on integrated hardware-software stacks in select regional markets where vendor diversification matters.
Data Center As a Service denotes the provisioning of compute, storage, and networking infrastructure through third-party facilities with guaranteed uptime parameters, typically expressed in tier classifications from I through IV, serving enterprises that prefer operational expenditure models over capital-intensive facility ownership. Public Cloud and Hybrid Cloud service types dominate current revenue pools, while Managed Hosting retains margin strength in regulated verticals requiring dedicated environments. Colocation deployments sustain physical proximity advantages for latency-sensitive workloads, whereas Serverless models are gaining traction among developers seeking abstracted infrastructure management.
The EU AI Act and CSRD impose algorithmic transparency and sustainability reporting obligations that reshape procurement criteria for European enterprise buyers, while the SEC's climate disclosure rules and HIPAA security standards extend compliance complexity for US-based healthcare and publicly traded adopters. China's MIIT and GB standards govern data localization requirements that constrain cross-border architecture choices for multinational operators. Stakeholders must weigh regulatory divergence against the operational simplicity of standardized global platforms.
Market Dynamics
Hyperscaler buildouts in the United States and enterprise migration to operational expenditure models are compressing traditional data center ownership economics, forcing facility operators to restructure lease terms and energy procurement to retain enterprise tenants.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises facing algorithmic transparency requirements are outsourcing infrastructure to specialized providers with pre-certified environmental controls and audit trails, accelerating procurement of tier III and IV facilities.
- Financial services capital reallocation:Banks and insurance carriers are shedding owned data center assets to free balance-sheet capacity for core lending activities, converting fixed infrastructure into subscription-based operational expenditure.
- Liquid cooling adoption:High-density GPU clusters for generative AI training are forcing retrofits of legacy air-cooled facilities, creating replacement demand for purpose-built liquid-cooled environments.
Market Restraints
- Power grid interconnection queues:Utility interconnection delays in Northern Virginia, Frankfurt, and Singapore are extending facility commissioning timelines by 18-36 months, constraining supply response to immediate demand.
- Land scarcity in primary metros:Zoning restrictions and community opposition in Loudoun County, Amsterdam, and Tokyo are limiting greenfield expansion and inflating site acquisition premiums.
- Generator set supply concentration:Diesel and natural gas backup power systems rely on a consolidated supplier base in the United States and Germany, exposing operators to engine block allocation constraints during demand surges.
Strategic Opportunities
- India's data localization regime:The country's requirement for domestic storage of financial and government data is creating demand for indigenous facility capacity that multinational operators can address through joint ventures with local real estate developers.
- Carbon-free energy matching:Corporate renewable energy procurement mandates are enabling power purchase agreement structures that lock in long-term offtake and differentiate facility offerings.
- Edge computing convergence:Integration of 5G radio access networks with micro data centers is opening distributed infrastructure deployments for autonomous vehicle telemetry and industrial IoT processing.
Industry Challenges
- Electrical trades labor scarcity:Specialized high-voltage technicians and commissioning engineers are in chronic undersupply across North America and Western Europe, delaying critical infrastructure energization.
- Legacy mainframe coexistence:Financial institutions maintaining IBM zSeries environments face integration complexity when attempting unified management across on-premise owned assets and outsourced cloud infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center As a Service Market |
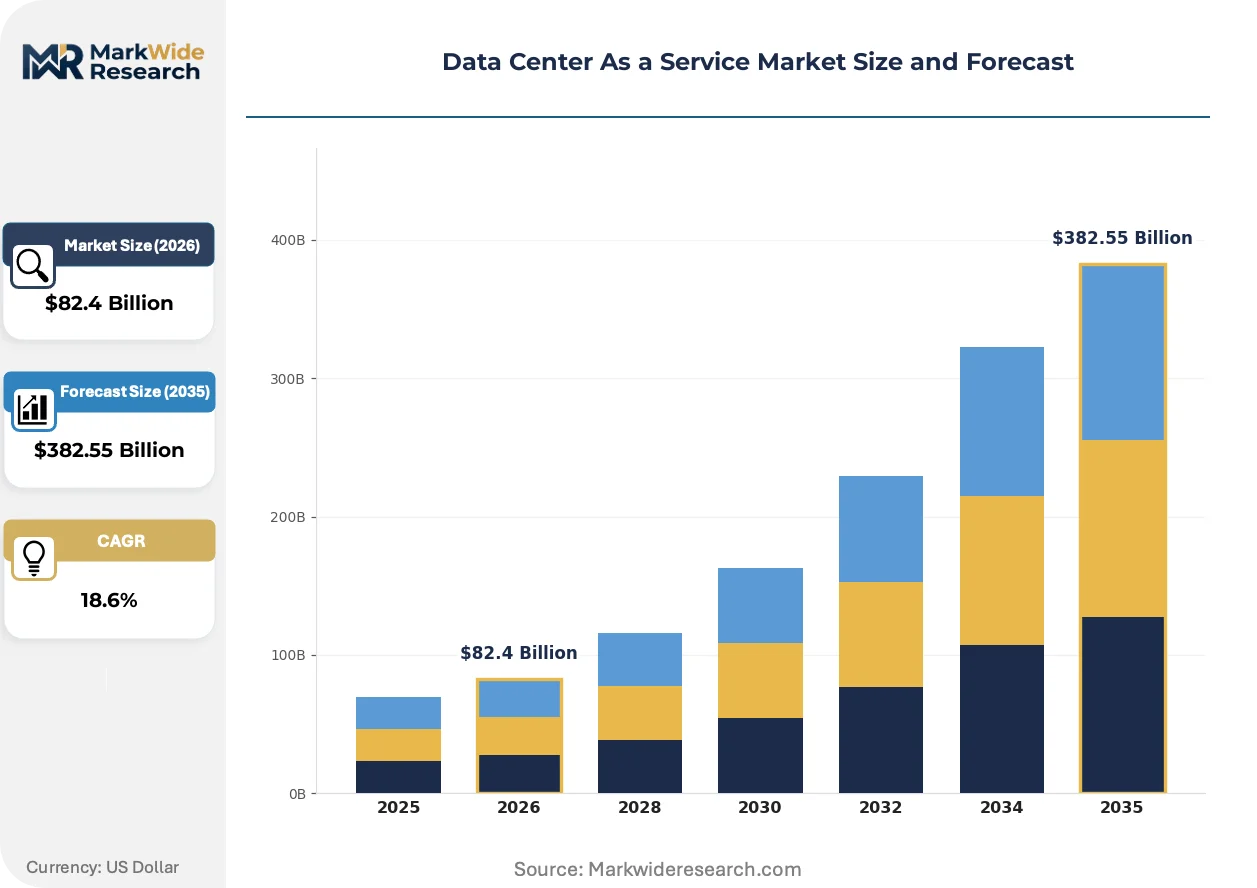
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $382.55 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Public Cloud, Private Cloud, Hybrid Cloud, Managed Hosting Deployment Model: On-Premises, Off-Premises, Colocation, Serverless End User Type: SMEs, Large Enterprises, Government, Educational Institutions Pricing Model: Pay-As-You-Go, Subscription-Based, Tiered Pricing, Fixed-Rate |
| Companies Covered | Amazon.com, Inc., Microsoft Corporation, IBM Corporation, Hewlett Packard Enterprise Development LP, Equinix, Inc., Dell Technologies, Inc., Alibaba, DigitalOcean, LLC, Huawei Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center As a Service Market Strategic Shifts & Innovations
Operational technology convergence with information technology platforms is dissolving traditional boundaries between facility engineering and software-defined infrastructure management, reshaping vendor capability requirements and buyer evaluation criteria.
Immersion cooling systems using dielectric fluids are hybridizing thermal management architectures, enabling power densities above 50 kilowatts per rack that air-cooled designs cannot sustain. Hyperscale operators in the United States and Nordic countries are deploying these systems at scale for AI training clusters, compressing facility footprints and reducing mechanical energy overhead by eliminating compressor-based refrigeration cycles.
The EU CSRD and SEC climate disclosure rules are mandating granular Scope 1, 2, and 3 emissions reporting for data center operators with revenue thresholds above defined limits. These frameworks are forcing infrastructure providers to implement continuous carbon accounting and procure documented renewable energy certificates, with European enterprises now requiring supplier sustainability attestations as standard contract terms.
Consumption-based billing models are replacing fixed colocation contracts as the dominant commercial structure for enterprise buyers. Retail and e-commerce segments in the United States are driving this transition, preferring metered compute and storage with automatic scaling provisions over committed capacity agreements that leave stranded assets during demand troughs.
Data Center As a Service Market Segmentation
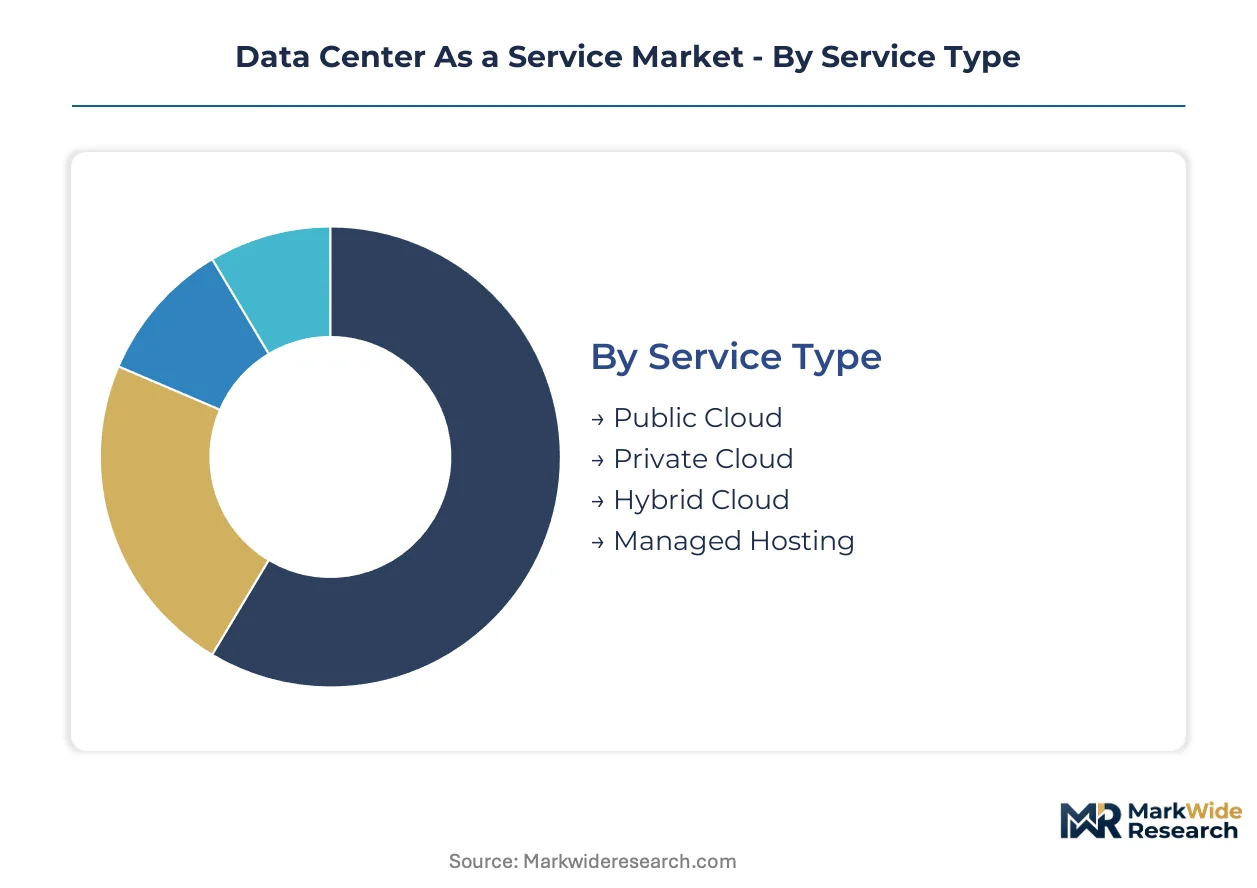
Segmentation in the Data Center As a Service market reveals how procurement cycles, compliance burdens, and workload characteristics fragment demand across distinct operational models. Buyers select service tiers based on latency tolerance, data sovereignty requirements, and capital structure preferences rather than homogeneous technical specifications.
Service Type:
Public Cloud contracts refresh fastest at 12-18 month cycles, while Managed Hosting engagements extend 36-60 months due to dedicated infrastructure lock-in and regulatory certification overhead.
- Public Cloud:Shared infrastructure pools deliver compute and storage through multi-tenant architectures with API-driven provisioning. Financial services firms in the United States are consolidating discretionary workloads here to convert fixed data center spend into variable operational expenditure aligned with trading volume fluctuations.
- Hybrid Cloud:Orchestration layers unify on-premise owned assets with off-premise elastic capacity, enabling workload portability across security boundaries. German automotive manufacturers deploy this model to keep proprietary design data on-premise while bursting simulation workloads to external facilities during peak development cycles.
- Private Cloud:Single-tenant dedicated environments with cloud-style automation but physically isolated infrastructure. Healthcare systems subject to HIPAA security standards in the United States favor this architecture for patient record repositories requiring audit trail isolation from multi-tenant neighbors.
- Managed Hosting:Provider-operated dedicated servers within leased facility space, bundling hardware lifecycle management with physical security and network operations. European banks facing EU AI Act algorithmic transparency mandates are migrating legacy core banking platforms here to access pre-certified environmental controls without building captive facilities.
Public Cloud anchors the volume base while Hybrid Cloud gains share at the steepest rate as enterprises seek to unify fragmented infrastructure estates without full migration.
Deployment Model:
Cost tier differentiation separates capital-intensive owned facilities from operational expenditure alternatives, with physical proximity premiums commanding measurable price spreads.
- Colocation:Enterprise-owned equipment housed in third-party facilities with shared power, cooling, and physical security infrastructure. Latency-sensitive electronic trading systems in the United States concentrate in Northern Virginia and Chicago metro facilities to minimize round-trip times to exchange matching engines.
- Serverless:Abstracted compute layer where developers deploy code without managing underlying server infrastructure, with automatic scaling triggered by event volume. Indian e-commerce platforms adopt this model to handle festival-season traffic spikes without provisioning standby capacity that remains idle eleven months annually.
- On-Premises:Enterprise-owned and operated facilities with full control over hardware selection, facility design, and operational procedures. Defense contractors in the United States maintain classified processing environments here to satisfy government security clearance requirements prohibiting third-party physical access.
- Off-Premises:Fully outsourced infrastructure with no enterprise ownership of physical assets, encompassing both dedicated and shared resource models. Japanese pharmaceutical companies utilize this architecture for non-proprietary research computing to avoid capital allocation debates during pipeline restructuring periods.
Colocation retains the largest installed footprint while Serverless expands most quickly among developer-centric organizations prioritizing deployment velocity over infrastructure control.
End User Type:
Customer type determines contract structure complexity, with government procurement cycles extending 18-24 months longer than commercial equivalents due to security clearance and budget appropriation requirements.
- Large Enterprises:Multinational organizations with dedicated procurement functions negotiating master service agreements spanning multiple geographies and business units. These buyers in the United States are consolidating fragmented data center contracts into global frameworks with standardized security and sustainability clauses.
- SMEs:Mid-market organizations lacking internal infrastructure expertise, purchasing through channel partners or direct self-service portals with minimal customization. German manufacturing SMEs are adopting standardized cloud bundles to replace aging on-premise servers without hiring specialized operations staff.
- Government:Public sector agencies with mandatory data localization, security certification, and domestic ownership requirements constraining supplier selection. India's financial data localization regime requires indigenous facility capacity for tax and payment system records.
- Educational Institutions:Universities and research organizations with episodic high-performance computing demand and grant-funded procurement cycles. Nordic research consortia leverage these structures for climate modeling workloads requiring intermittent access to GPU clusters.
Large Enterprises anchor contract value concentration while SMEs represent the fastest-expanding customer acquisition target for standardized platform offerings.
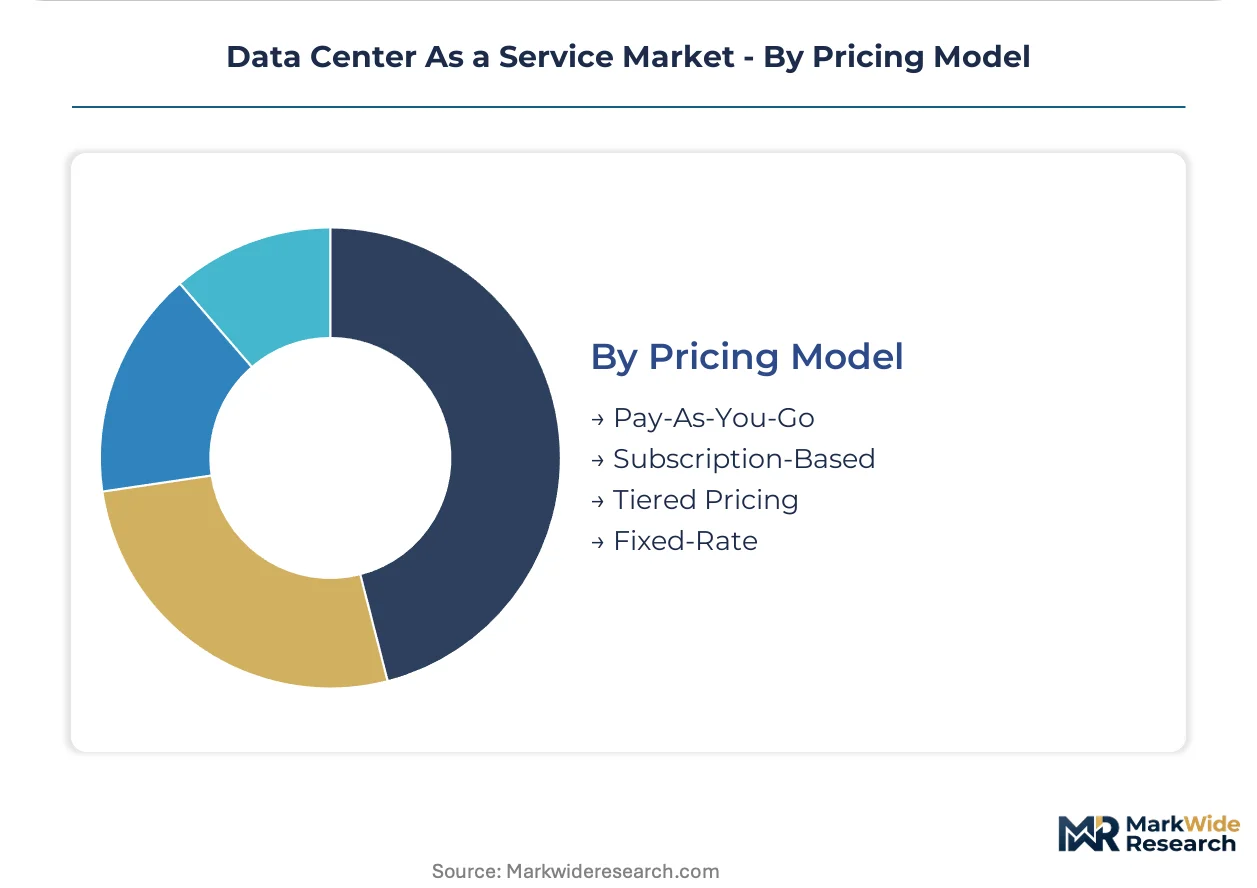
Pricing Model:
Margin profiles diverge sharply between consumption-based structures with operational risk transfer and fixed-rate agreements with predictable revenue streams for facility operators.
- Pay-As-You-Go:Metered billing based on actual resource consumption with no minimum commitment, enabling immediate cost elasticity. United States retail and e-commerce segments drive this transition, preferring automatic scaling provisions over committed capacity agreements that strand assets during demand troughs.
- Subscription-Based:Fixed recurring fees for defined resource bundles with predictable monthly expenditure and simplified budgeting. European enterprises subject to CSRD sustainability reporting obligations favor this structure for multi-year carbon accounting and renewable energy certificate documentation.
- Tiered Pricing:Volume-discounted rate schedules with price breaks at predefined consumption thresholds, rewarding scale with marginal cost reductions. Japanese automotive suppliers negotiate these structures for connected vehicle data processing with production volume-linked infrastructure scaling.
- Fixed-Rate:Uniform pricing regardless of utilization, common in regulated colocation contracts with dedicated physical space and power allocation. United States healthcare systems under HIPAA security standards select this model to lock in audit-compliant environments with guaranteed capacity availability.
Subscription-Based contracts dominate committed revenue pipelines while Pay-As-You-Go climbs fastest as finance organizations prioritize operational expenditure flexibility over capital budget certainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax incentives for data center construction are reshaping facility investment patterns across major economies. Sovereign data localization mandates are forcing multinational operators to establish domestic capacity. Energy procurement regulations now determine site selection feasibility in key markets.
United States
Virginia's Data Center Sales and Use Tax Exemption Program has anchored hyperscaler expansion in Loudoun County. The SEC's climate disclosure rules require Scope 1 and 2 emissions reporting from publicly traded operators. Northern Virginia hosts the world's densest concentration of cloud infrastructure with over 35 percent of global internet traffic passing through its fiber corridors.
Germany
Industrial digitization initiatives under the Gaia-X federated data infrastructure program are stimulating domestic cloud capacity demand. The EU AI Act imposes algorithmic transparency requirements that favor certified facility providers. Frankfurt's Rhine-Main metro has emerged as Europe's primary interconnection hub with over 60 data centers operating within 30 kilometers of the city center.
India
The Digital India program and data localization requirements for financial and government data are accelerating indigenous facility construction. RBI mandates require domestic storage of payment system records. Mumbai and Chennai are attracting joint ventures between global operators and local real estate developers to satisfy surging enterprise demand.
China
MIIT's "East Data West Computing" initiative is redirecting facility investment toward western provinces with abundant renewable energy. GB standards govern cross-border data flows and constrain foreign operator market access. Inner Mongolia and Guizhou provinces are developing hyperscale campuses leveraging cooler climates and hydroelectric power for AI training clusters.
Singapore
The government's moratorium on new data center construction has lifted with revised sustainability criteria requiring carbon-neutral operations. IMDA's Green Mark certification now governs facility approvals. The Jurong and Tanjong Kling industrial estates are absorbing limited new capacity as operators deploy liquid-cooled designs to meet 1.3 PUE requirements.
Data Center As a Service Market Key Industry Players
Channel-controlling players compete with product-specialist players for enterprise workload placement. Hyperscale cloud operators dominate volume-based public cloud segments through direct sales relationships. Interconnection specialists and managed hosting providers retain premium positioning in regulated verticals requiring physical proximity and compliance certification. Competitive dynamics center on energy procurement scale, geographic footprint expansion, and sustainability credential differentiation.
Within the hyperscale tier, Amazon.com, Inc. and Microsoft Corporation exemplify platform-scale competition through vertically integrated infrastructure stacks. Equinix, Inc. occupies a distinct position as an interconnection-focused operator with premium metro real estate. Huawei Technologies Co., Ltd. represents the integrated hardware-software archetype in markets where vendor diversification carries strategic weight.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Microsoft Corporation |
| IBM Corporation |
| Hewlett Packard Enterprise Development LP |
| Equinix, Inc. |
| Dell Technologies, Inc. |
| Alibaba |
| DigitalOcean, LLC |
| Huawei Technologies Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Tight utilization in Northern Virginia's hyperscale corridor is compressing lease terms and forcing facility operators into longer-term power purchase agreements to lock in supply visibility. This capacity constraint simultaneously elevates pricing power for incumbent landlords with energized space and pressures new entrants to absorb interconnection delay costs or accept secondary metro locations.
Pricing Analysis
Tier certification level creates the primary spread between facility offerings, with Tier IV uptime guarantees commanding substantial premiums over Tier II equivalents in financial services procurement. Subscription-based contracts with renewable energy matching dominate enterprise agreements, while consumption-based billing gains share among retail and e-commerce buyers seeking demand elasticity. Pricing pressure stems from hyperscaler self-build programs bypassing third-party leasing, compressing margins for wholesale providers. SMEs exhibit highest price sensitivity, prioritizing standardized bundles over customized environments, whereas regulated healthcare and defense buyers accept fixed-rate premiums for audit-compliant isolation.
Supply Chain Analysis
Upstream electrical equipment manufacturing concentrates in the United States, Germany, and China, with medium-voltage switchgear and generator sets drawing from a consolidated supplier base. Diesel engine blocks, power distribution units, and precision cooling systems represent critical component dependencies with extended lead times. Single-source vulnerability in backup generator engine manufacturing exposes operators to allocation constraints during demand surges. Distribution runs through direct OEM relationships for hyperscale builds and regional systems integrators for enterprise colocation deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Data Center As a Service market is undergoing high-growth disruption as generative AI training clusters force liquid cooling retrofits and reshape facility design standards. The EU AI Act's algorithmic transparency mandates are accelerating procurement of pre-certified Tier III and IV environments.
For Market Incumbents: Harden interconnection relationships with utilities in constrained metros like Northern Virginia and Frankfurt to secure queue priority against new entrants. Expand captive renewable energy procurement through power purchase agreements to meet CSRD disclosure requirements and differentiate sustainability credentials. Vertical integration into electrical trades training programs addresses chronic technician scarcity threatening energization timelines.
For New Entrants and Emerging Players: Establish a beachhead in India's data localization market through joint ventures with domestic real estate developers to satisfy RBI financial data storage mandates. Target edge computing convergence opportunities in 5G radio access network micro data centers for autonomous vehicle telemetry processing. Pursue carbon-free energy matching as a go-to-market angle to capture corporate renewable procurement mandates.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among interconnection-focused operators with premium metro real estate and long-term enterprise tenancy. Long-term viability centers on facilities with secured power interconnection and liquid cooling retrofit capability for AI workload accommodation. Watch hyperscaler self-build announcements as a signal for third-party leasing demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Retrofit | Enables power densities above 50 kilowatts per rack for AI training clusters. |
| Renewable Energy Matching | Locks in long-term offtake through power purchase agreements meeting CSRD requirements. |
| Edge Computing Convergence | Integrates 5G radio access networks with micro data centers for industrial IoT processing. |
| Data Localization Joint Venture | Addresses India's RBI mandates through partnerships with domestic real estate developers. |
| Interconnection Capacity Expansion | Secures utility queue priority in constrained metros like Northern Virginia and Frankfurt. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with data center facility managers, enterprise IT procurement officers, hyperscaler infrastructure planners, electrical contractors, and utility interconnection specialists. Secondary validation drew from SEC filings of publicly traded operators, FERC interconnection queue data, EIA electricity market reports, and EU regulatory disclosure databases. Bottom-up capacity buildout tracking and top-down enterprise spend analysis were triangulated to reconcile supply and demand estimates.
Calibration against historical facility commissioning timelines and power density evolution informed projection parameters across the analysis window. Segmentation dimensions modeled include service type, deployment model, end user category, and pricing structure. CAGRs were derived from fitted growth curves anchored to disclosed hyperscaler capex trajectories and enterprise cloud migration survey data. Renewable energy procurement velocity and liquid cooling adoption curves served as industry-specific forecast inputs.
Stress conditions across utility interconnection delays, generator set supply constraints, and electrical trades labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hyperscaler self-build rates and regulatory enforcement timelines. Cross-checking against disclosed hyperscaler facility energization schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Colocation Edge Data Center Market
Data Center Infrastructure
Australia Data Center Construction Market
Data Center Infrastructure
Long Term Data Retention Solutions Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Spain Data Center Physical Security Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
Europe Data Center Power Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
Brazil Data Center Power Market