
 Global Virtual Desktop Market | 2026-2036
Global Virtual Desktop Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Desktop Market Intelligence
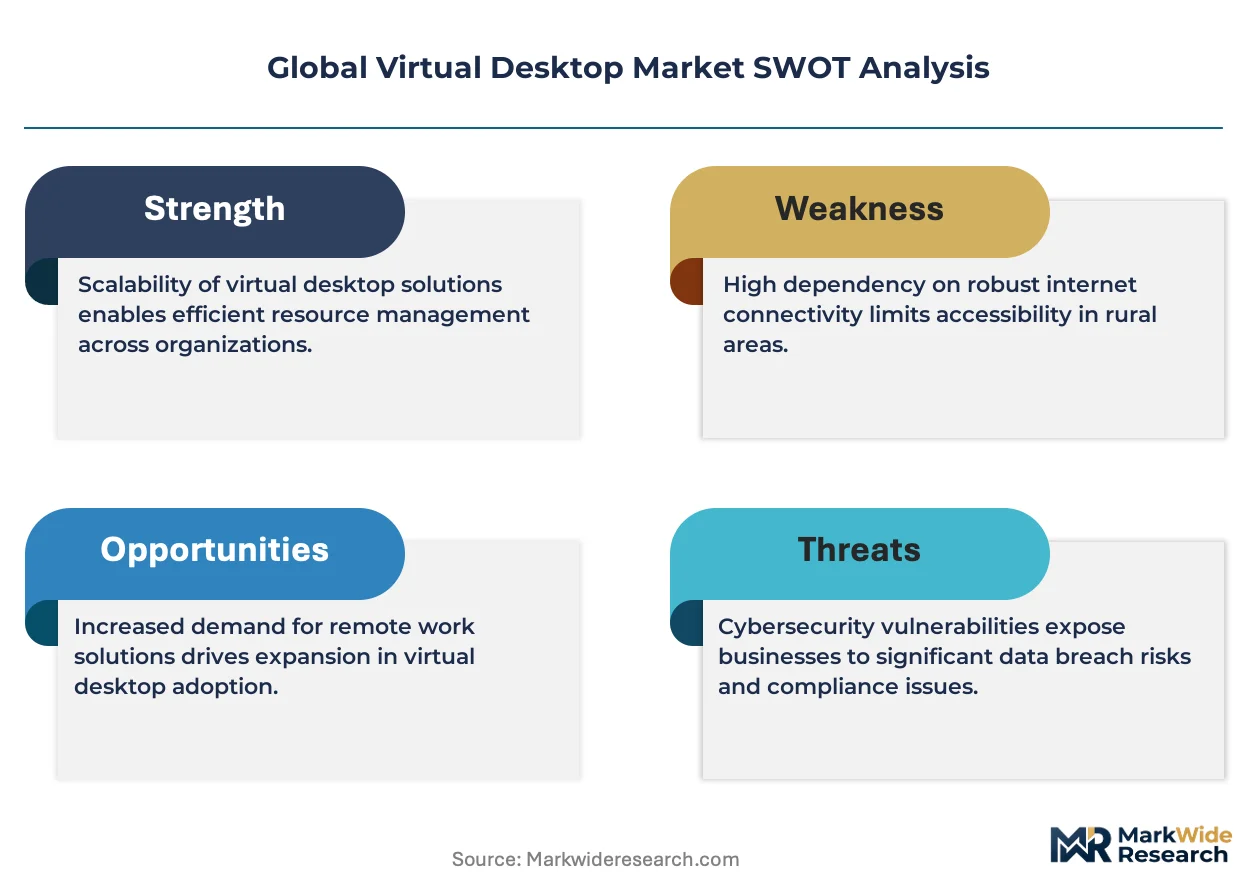
The gap between premium managed Desktop as a Service offerings and commodity remote desktop tools is repositioning how enterprises evaluate total cost of ownership versus security certification depth. VMware leverages its hypervisor heritage to sustain pricing power in regulated verticals. Citrix Systems anchors its competitive stance through specialized application virtualization layering. Microsoft competes by extending Azure Virtual Desktop into hybrid deployment architectures that span on-premise and cloud footprints.
Virtual desktop technology delivers centralized operating system and application hosting from a data center or cloud environment to endpoint devices, typically employing GPU acceleration protocols and thin-client rendering to maintain sub-50 millisecond latency thresholds for interactive workloads. The technology's primary commercial purpose is to decouple compute processing from physical hardware, enabling IT departments to patch, secure, and scale desktop environments without touching distributed endpoint machines. Cloud-Based Virtual Desktop deployments are capturing the fastest expansion as banking institutions and government agencies migrate away from capital-intensive on-premise Virtual Desktop Infrastructure. Desktop as a Service solutions concentrate margin pools where multi-tenant automation and sovereign data residency capabilities differentiate vendor offerings.
FDA's 21 CFR Part 11 electronic records requirements for pharmaceutical research, HIPAA security rule mandates for healthcare data access, and the EU AI Act's risk classification framework for automated decision systems collectively shape product development priorities and market access conditions for virtual desktop vendors serving regulated industries. GDPR's cross-border data transfer restrictions and BSI's IT-Grundschutz baseline protection standards further segment competitive positioning between regional cloud providers and multinational platforms. Stakeholders must monitor evolving encryption-in-transit requirements and sovereignty certifications as procurement criteria harden across defense, healthcare, and financial services verticals.
Market Dynamics
The EU AI Act's risk classification framework for automated decision systems is forcing virtual desktop vendors to architect sovereign data residency capabilities as a prerequisite for regulated industry procurement across Europe.
Growth Catalysts
- GDPR cross-border transfer restrictions:Pharmaceutical manufacturers in Germany require localized virtual desktop infrastructure to maintain patient data sovereignty during multi-site clinical trials.
- GPU acceleration protocol maturation:Healthcare diagnostic imaging workloads now achieve sub-30 millisecond latency thresholds, enabling radiologist adoption of cloud-hosted workstations.
- FDA 21 CFR Part 11 mandates:Electronic records requirements for pharmaceutical research create mandatory audit trails that virtual desktop centralized logging satisfies.
Market Restraints
- Hyperscaler concentration risk:Three cloud providers control over 80% of sovereign-certified data center capacity in Western Europe, creating single-source vulnerability.
- Legacy application virtualization debt:Financial services institutions maintain 15-20 year-old application stacks incompatible with modern GPU-accelerated protocols without expensive re-architecture.
- BSI IT-Grundschutz certification timelines:Baseline protection certification requires 12-18 month audit cycles that delay German public sector deployment schedules.
Strategic Opportunities
- India's CDSCO regulatory digitization:Pharmaceutical contract research organizations require compliant virtual desktop infrastructure for international trial data management.
- Edge-to-cloud protocol convergence:5G network slicing combined with containerized desktop delivery creates sub-10 millisecond latency for manufacturing floor applications.
- Japan METI data free flow with trust initiative:Cross-border certification reciprocity opens Japanese pharmaceutical demand to European sovereign cloud providers.
Industry Challenges
- Zero-trust architecture skill scarcity:Enterprise IT departments lack sufficient identity and access management engineers to implement continuous verification protocols.
- Multi-cloud orchestration complexity:Hybrid deployments spanning on-premise VMware, Azure Virtual Desktop, and AWS WorkSpaces require specialized platform engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Desktop Market |
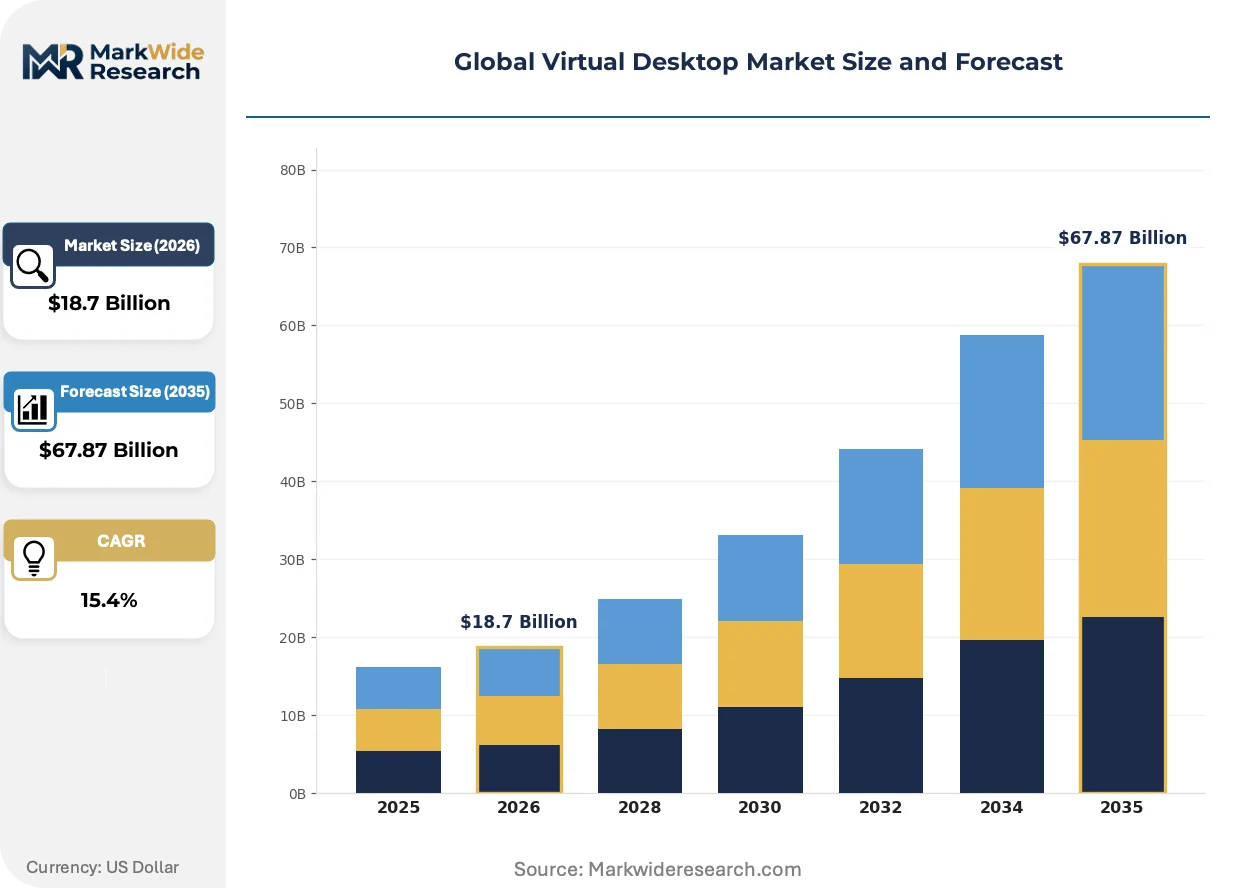
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $67.87 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Hosted Virtual Desktop, On-Premise Virtual Desktop, Cloud-Based Virtual Desktop, Hybrid Deployment Solution Type: Desktop as a Service, Virtual Desktop Infrastructure, Application Virtualization, Remote Desktop Services, Client Virtualization Use Case: Remote Work, Training & Development, IT Management, Disaster Recovery, Secure Access End User Industry: Banking Institutions, Government Agencies, Telecommunication Firms, Education Providers, Manufacturing Entities |
| Companies Covered | VMware, Citrix Systems, Microsoft, Amazon Web Services, Nutanix, Dell Technologies, Cisco Systems, Hewlett Packard Enterprise, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Desktop Market Strategic Shifts & Innovations
Containerized desktop delivery protocols are fragmenting traditional hypervisor-centric architectures, enabling workload portability across sovereign cloud boundaries while compressing vendor lock-in duration.
WebRTC-based display protocols are decentralizing GPU rendering workloads from centralized data centers to edge points of presence. Banking institutions in Singapore and Switzerland now deploy branch-level desktop containers that synchronize encrypted session states across distributed nodes. This topology reduces cross-border data transfer volumes while complicating centralized security policy enforcement.
The EU AI Act's high-risk system registration requirements are mandating algorithmic decision logging within virtual desktop session recordings. Healthcare providers deploying diagnostic AI tools must now maintain immutable audit trails of clinician interactions with automated systems. German university hospitals are piloting blockchain-anchored session records to satisfy both EMA pharmacovigilance and GDPR accountability obligations.
Consumption-based licensing models are displacing traditional per-seat subscriptions in enterprise procurement. Managed service providers in France and the Netherlands now offer hourly-billed virtual desktop capacity for seasonal pharmaceutical research teams. This flexibility attracts mid-market contract research organizations previously priced out of dedicated infrastructure, though it compresses vendor margin predictability.
Global Virtual Desktop Market Segmentation
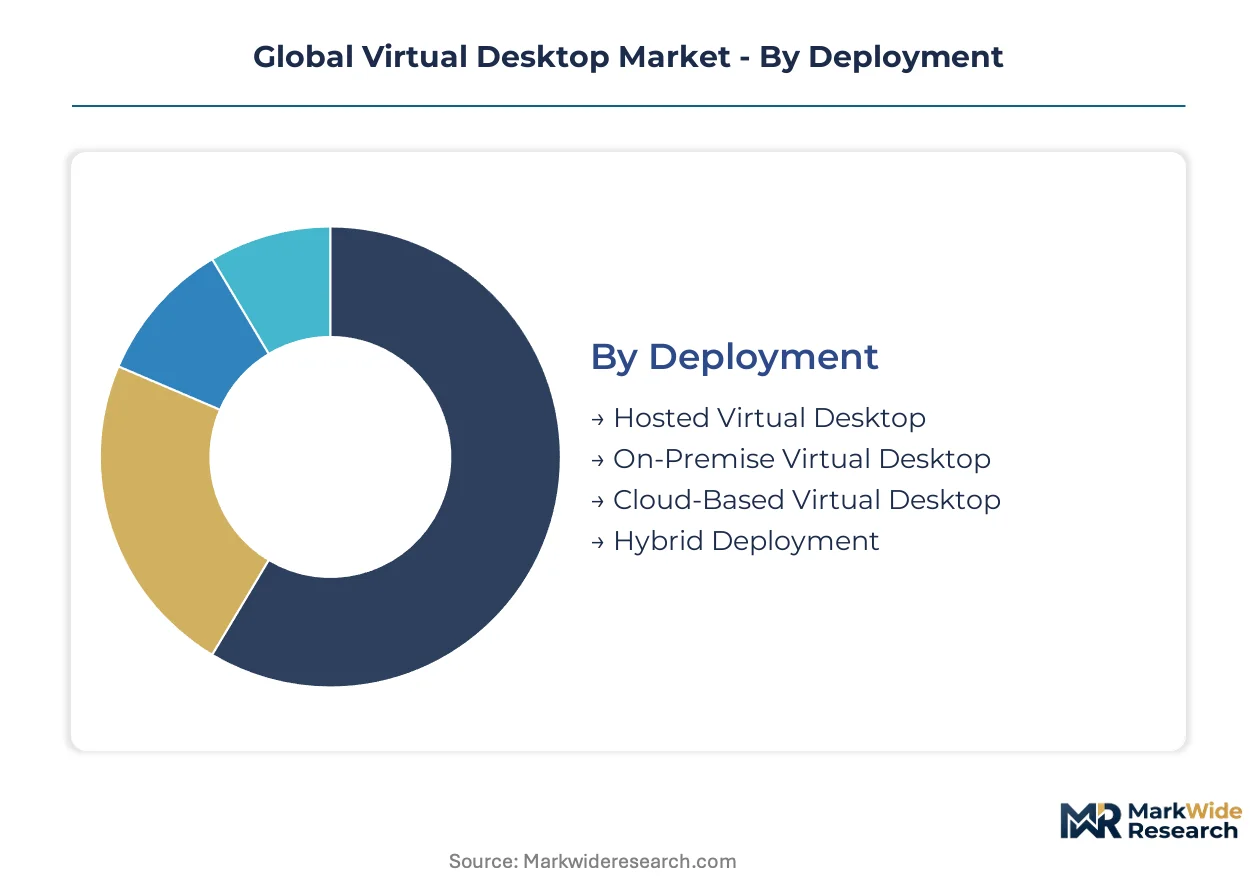
Virtual desktop procurement patterns diverge sharply across deployment architectures and regulatory contexts. Enterprise upgrade cycles from legacy terminal services to GPU-accelerated cloud instances reshape vendor competitive positioning within each segment cluster.
Deployment:
Migration timelines from capital-intensive on-premise estates to consumption-based cloud models determine replacement-cycle velocity across enterprise accounts.
- Cloud-Based Virtual Desktop:Multi-tenant infrastructure delivers centralized patching and elastic scaling without endpoint hardware refresh. German pharmaceutical manufacturers prioritize sovereign-certified instances for EMA-compliant clinical data hosting.
- Hybrid Deployment:Workload orchestration spans on-premise VMware estates and Azure/AWS cloud footprints, preserving legacy application compatibility. Financial services institutions in Switzerland and Singapore deploy this architecture to satisfy data residency mandates while accessing cloud burst capacity.
- On-Premise Virtual Desktop:Dedicated infrastructure maintained within enterprise data centers for maximum control over encryption keys and physical access.
- Hosted Virtual Desktop:Single-tenant managed service where a provider operates dedicated infrastructure on customer-specified premises.
Volume placements concentrate in Cloud-Based Virtual Desktop; the faster expansion belongs to Hybrid Deployment.
Solution Type:
Margin structures stratify between commodity remote access tools and sovereign-certified managed service tiers.
- Desktop as a Service:Fully managed subscription offering bundles compute, storage, and security operations into per-seat pricing. Healthcare providers in France and the Netherlands adopt hourly-billed variants for seasonal research teams.
- Virtual Desktop Infrastructure:Enterprise-operated stack of hypervisor, connection broker, and profile management components. Defense contractors in Germany maintain on-premise VDI to satisfy BSI IT-Grundschutz baseline protection requirements.
- Application Virtualization:Streaming individual applications without full desktop hosting reduces resource overhead for legacy Windows dependencies.
- Remote Desktop Services:Session-based sharing of server operating systems for task worker populations with minimal personalization needs.
- Client Virtualization:Type-1 or Type-2 hypervisors executing locally on endpoint hardware for offline capability.
Revenue concentrates in Desktop as a Service; Virtual Desktop Infrastructure claims the steepest expansion trajectory among self-managed alternatives.
Use Case:
Functional requirements vary by workforce mobility patterns and data sensitivity classifications.
- Remote Work:Persistent desktop sessions accessible from unmanaged home devices. Japanese pharmaceutical firms deploy these for METI-certified cross-border collaboration.
- Secure Access:Zero-trust architectures verifying identity and device posture before session initiation. Government agencies in Germany mandate this configuration for classified network access.
- Disaster Recovery:Warm standby desktops activated during primary site failures to maintain business continuity.
- IT Management:Centralized imaging and patch distribution eliminating endpoint visit requirements.
- Training & Development:Non-persistent pools provisioned for temporary contractor and student populations.
Procurement volume clusters around Remote Work; Secure Access is climbing the fastest as zero-trust mandates harden.
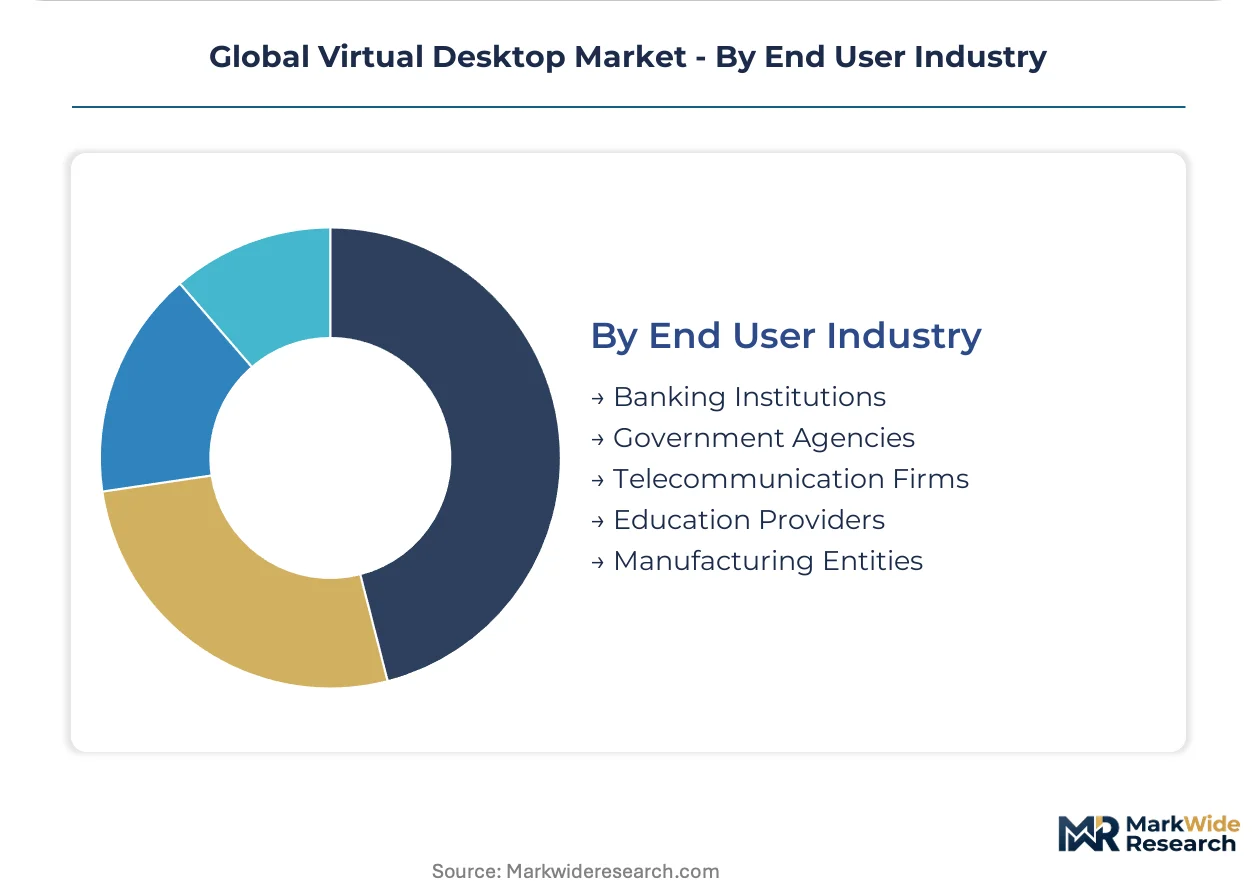
End User Industry:
Compliance certification depth determines vendor selection criteria across regulated verticals.
- Banking Institutions:GPU-accelerated workstations for quantitative analysts combined with locked-down teller sessions. Singaporean banks deploy WebRTC-based branch containers to minimize cross-border data transfer.
- Government Agencies:Immutable session logging and sovereign data residency for classified and citizen service delivery. German public sector procurement requires BSI certification cycles spanning 12-18 months.
- Healthcare Providers:Diagnostic imaging workstations demanding sub-30 millisecond latency for radiologist acceptance.
- Telecommunication Firms:Customer service agent pools scaling elastically with call volume patterns.
- Education Providers:Lab and library access for student populations with high churn and minimal personalization.
- Manufacturing Entities:Shop floor thin clients resisting dust, vibration, and temperature extremes.
Deployment scale concentrates in Banking Institutions; Government Agencies are gaining share fastest as sovereign cloud procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's sovereign cloud corridor anchors European virtual desktop procurement as pharmaceutical manufacturers consolidate compliant infrastructure within the Rhine-Main metropolitan zone.
United States
FDA's 21 CFR Part 11 electronic records mandates drive pharmaceutical and clinical research demand for centralized logging capabilities. Healthcare providers in Boston and San Francisco deploy GPU-accelerated diagnostic imaging workstations to satisfy HIPAA security rule requirements. The FDA's risk-based enforcement framework shapes vendor certification priorities across the life sciences corridor.
Germany
EMA pharmacovigilance obligations and BSI IT-Grundschutz baseline protection standards create mandatory 12-18 month certification timelines for public sector deployments. Munich and Berlin university hospitals pilot blockchain-anchored session records to satisfy GDPR accountability obligations for AI-assisted diagnostic tools. Sovereign data residency capabilities determine procurement outcomes in pharmaceutical manufacturing clusters.
Switzerland
Swissmedic regulatory requirements and banking secrecy frameworks concentrate demand in Zurich and Geneva financial centers. WebRTC-based branch containers minimize cross-border data transfer volumes while maintaining sub-10 millisecond latency for quantitative trading workstations. The country's data protection authority enforces encryption-in-transit standards that exceed baseline EU requirements.
Japan
METI's Data Free Flow with Trust initiative establishes cross-border certification reciprocity for pharmaceutical research collaboration. Tokyo and Osaka pharmaceutical firms deploy METI-certified virtual desktops for international trial data management with European partners. PMDA's digitization roadmap accelerates cloud migration timelines for contract research organizations.
Singapore
Monetary Authority of Singapore cybersecurity guidelines and banking secrecy requirements drive financial sector adoption of edge-to-cloud architectures. Marina Bay financial institutions deploy containerized desktop delivery across 5G network slices to achieve sub-10 millisecond latency for trading floors. The country's data localization policies reinforce demand for sovereign-certified infrastructure.
Global Virtual Desktop Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and managed service automation capabilities. The market stratifies between hypervisor-heritage vendors sustaining pricing power in regulated verticals and cloud-native challengers compressing delivery costs through multi-tenant automation. Three strategic archetypes dominate: sovereign-certified specialists, hybrid orchestration platforms, and consumption-based managed service providers. Competitive moves concentrate on M&A for compliance certifications and strategic partnerships for edge infrastructure.
Within the hypervisor-heritage tier, VMware and Citrix Systems exemplify premium positioning through specialized application virtualization layering and regulated vertical focus. Microsoft anchors the cloud-native vector by extending Azure Virtual Desktop into hybrid deployment architectures. Amazon Web Services occupies a position at the scale-driven end of sovereign-certified infrastructure, competing on elastic capacity and geographic footprint rather than legacy compatibility depth.
| Leading Market Players |
|---|
| VMware |
| Citrix Systems |
| Microsoft |
| Amazon Web Services |
| Nutanix |
| Dell Technologies |
| Cisco Systems |
| Hewlett Packard Enterprise |
| IBM |
| Others |
Cost & Logistics Intelligence
GPU accelerator chip costs cascade through sovereign-certified cloud infrastructure tiers, compressing margins at the commodity remote-access layer while preserving premium pricing for BSI IT-Grundschutz validated deployments in German pharmaceutical manufacturing clusters.
Pricing Analysis
Uptime guarantees anchor value-based pricing for mission-critical healthcare and financial services workloads. Subscription tiers stratify across premium sovereign-certified, standard multi-tenant, and economy remote-session offerings, with EMA pharmacovigilance compliance commanding substantial premiums over uncertified alternatives. Cost compression in the standard tier intensifies as hyperscaler automation reduces delivery overhead, while pharmaceutical contract research organizations exhibit highest price sensitivity among regulated buyers.
Supply Chain Analysis
Cross-border data transfer costs shape cloud region selection for European deployments. Taiwan and South Korea supply advanced GPU silicon, Germany and Switzerland host sovereign-certified data center capacity, and Ireland anchors EU-West compute availability. The supply chain rests on specialized networking hardware from Chinese and American vendors, creating tariff exposure for edge infrastructure components. Distribution runs through hyperscaler marketplaces and specialized managed service providers serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerized desktop delivery protocols are displacing legacy hypervisor-centric architectures, compressing vendor lock-in duration and reshaping procurement evaluation criteria across enterprise accounts.
For Market Incumbents: Deepen vertical integration into sovereign data center operations to defend margin position against cloud-native challengers. VMware and Citrix Systems should accelerate BSI IT-Grundschutz pre-certification investments, as German public sector procurement delays threaten revenue recognition timelines. Capacity expansion into Frankfurt's cloud corridor preserves geographic proximity to pharmaceutical manufacturing demand clusters.
For New Entrants and Emerging Players: Managed service providers in France and the Netherlands represent the most penetrable channel partner type for hourly-billed consumption models. Target mid-market contract research organizations previously priced out of dedicated infrastructure, deploying sovereign-certified edge nodes to satisfy GDPR cross-border restrictions without hyperscaler dependency.
For Investors and Strategic Acquirers: Blockchain-anchored session record pilots at Munich university hospitals are the leading indicator that immutable audit trail capabilities will become mandatory procurement criteria. Sovereign-certified specialists with existing EMA validation pathways represent the optimal acquisition archetype. Watch for CDSCO regulatory digitization announcements in India as inflection signals for international trial data management demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Certification Investment | BSI IT-Grundschutz pre-certification unlocks German public sector procurement pipelines. |
| Containerized Protocol Migration | WebRTC-based delivery reduces cross-border data transfer volumes for Swiss banking clients. |
| Edge Infrastructure Partnership | 5G network slicing partnerships enable sub-10 millisecond latency for Singapore trading floors. |
| Hourly Billing Model Launch | Consumption-based licensing attracts seasonal pharmaceutical research teams in the Netherlands. |
| Blockchain Audit Trail Integration | Immutable session records satisfy EU AI Act high-risk system registration requirements. |
Research Approach
Document review covered hyperscaler capex disclosures, EMA pharmacovigilance guidelines, and BSI certification databases, complemented by interviews with cloud infrastructure architects, healthcare IT procurement officers, and regulatory compliance leads across German, Swiss, and Japanese pharmaceutical clusters. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EU AI Act implementation texts, and METI Data Free Flow with Trust framework materials. Bottom-up deployment sizing and top-down market aggregation were cross-referenced for triangulation.
Historical adoption curves were cross-referenced against panel input from platform engineering directors to construct projections across the analysis window. Segmentation dimensions modeled include deployment architecture, solution type, end-user industry vertical, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted replacement cycle analysis, incorporating GPU protocol maturation timelines and sovereign certification backlog estimates as industry-specific inputs.
Caveats apply where EU AI Act enforcement intensity or BSI audit cycle duration could materially shift the outlook for European procurement velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Workforce Management Software Market
Software & Services
Course Authoring Software Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Test Automation Market
Software & Services
Vehicle Embedded Software Market
Software & Services
Train Reservation Software Market
Software & Services
Enterprise Capture Software Market
Software & Services
3D CAD Software Market
Software & Services
Yacht Management Software Market
Software & Services
Taxi Booking Software Market
Software & Services
Live Software Market
Software & Services
Geomechanics Software and Service Market
Software & Services
Multivariate Testing Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Lab Automation Software Market