
 GCC Data Center Market | 2026-2036
GCC Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Data Center Market Intelligence
The UAE's dual carbon goals is pivoting hyperscale developers toward liquid-cooled facility designs across Dubai and Abu Dhabi. Khazna Data Centers anchors capacity expansion in Abu Dhabi with sovereign-grade certifications. Equinix leverages its global interconnection fabric to capture multinational enterprise demand. Gulf Data Hub specializes in carrier-neutral colocation, sustaining connectivity density that attracts financial services tenants.
A data center constitutes a dedicated facility housing computing infrastructure—servers, storage systems, networking equipment, and power distribution units—engineered to maintain 99.999% uptime through redundant cooling, uninterruptible power supplies, and fire suppression systems, serving as the physical backbone for enterprise IT operations, cloud delivery, and digital service propagation. Colocation services command the largest revenue share as enterprises shed owned assets for operational flexibility, while edge computing infrastructure represents the fastest-expanding technology segment driven by latency-sensitive applications in autonomous systems and industrial IoT. Managed services capture premium margins through cybersecurity integration and workload optimization, though hybrid deployment models now dominate procurement patterns as organizations balance sovereignty requirements against cloud scalability.
Saudi Arabia's Communications, Space and Technology Commission enforces data localization rules that restrict cross-border transfers of citizen information, compelling foreign cloud providers to establish in-kingdom facilities. The UAE's Telecommunications and Digital Government Regulatory Authority certifies facilities against tiered reliability standards that determine eligibility for government contracts. Stakeholders must monitor evolving national cybersecurity frameworks across Kuwait, Oman, and Qatar, where regulatory maturation will determine market access timelines and certification burdens for new entrants.
Market Dynamics
Sovereign cloud mandates across Gulf Cooperation Council member states are forcing hyperscale providers to localize infrastructure, creating a structural pull toward in-kingdom facility construction and certified colocation partnerships.
Growth Catalysts
- Saudi Arabia's Data Localization Framework:The Communications, Space and Technology Commission restricts cross-border citizen data transfers, compelling foreign cloud operators to establish domestic facilities and driving colocation demand among banking and telecom sectors.
- Liquid Cooling Adoption:Direct-to-chip and immersion cooling systems address power density constraints in Dubai and Abu Dhabi facilities where ambient temperatures strain traditional HVAC architectures.
- Smart City Edge Deployments:Autonomous transport and industrial IoT networks across Riyadh and Dubai concentrate low-latency compute requirements in metropolitan hyperscale clusters.
Market Restraints
- Power Infrastructure Bottlenecks:Grid interconnection delays in secondary GCC cities extend facility commissioning timelines beyond 18 months.
- Skilled Technician Scarcity:The region produces fewer than 400 certified data center engineers annually, constraining operational scaling for new entrants.
- Desalination-Dependent Cooling:Water scarcity elevates operational costs for evaporative cooling systems in Kuwait, Oman, and Qatar facilities.
Strategic Opportunities
- Oman and Kuwait Regulatory Maturation:Nascent data protection frameworks in these markets offer first-mover positioning before certification requirements formalize.
- AI Training Cluster Demand:GPU-intensive workloads from regional petroleum and logistics sectors seek sovereign-hosted infrastructure outside Western cloud jurisdictions.
- Green Hydrogen Power Purchase Agreements:Renewable energy offtake contracts in Saudi Arabia and UAE enable carbon-neutral facility claims for ESG-sensitive multinationals.
Industry Challenges
- Tier Certification Timelines:Uptime Institute and TIA-942 assessments require 9-14 months, delaying revenue recognition for speculative builds.
- Legacy Enterprise Migration Complexity:Mainframe-dependent banks and government agencies face 24-36 month workload refactoring cycles before colocation adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Data Center Market |
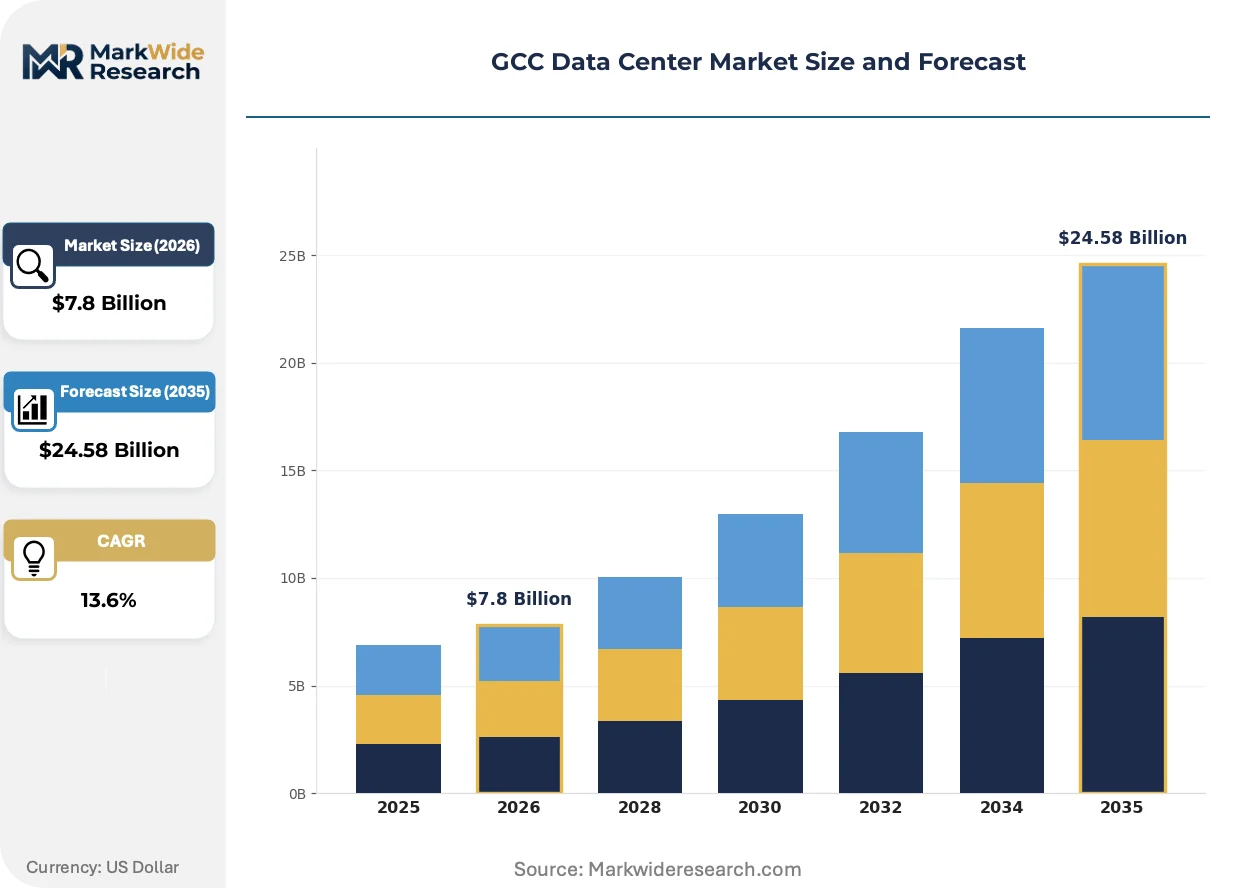
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $24.58 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Services, Cloud Services, Disaster Recovery Deployment Model: On-Premise, Hybrid, Multi-Cloud, Private Cloud End User: Telecommunications, BFSI, Government, E-Commerce Technology: Virtualization, Edge Computing, AI Integration, SDN |
| Companies Covered | Edgnex Data Centres by DAMAC, Quantum Switch Tamasuk, Equinix, Ooredoo, stc, Gulf Data Hub, Moro Hub, Mobily, Khazna Data Centers, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Data Center Market Strategic Shifts & Innovations
Computational density requirements and sovereignty compliance are converging to reshape facility architecture across Arabian Peninsula markets, with cooling innovation and certification standards commanding disproportionate capital allocation.
Direct liquid cooling is rewriting thermal management economics in Gulf facilities. Saudi Aramco and Emirates NBD deploy immersion-cooled racks for AI inference workloads. This compression of power usage effectiveness ratios enables 40kW-per-rack densities previously unattainable in desert climates.
The UAE's Telecommunications and Digital Government Regulatory Authority mandates tiered reliability certifications for government contract eligibility. Facility operators now pre-certify to Tier III standards before breaking ground. Banking and healthcare tenants prioritize TDRA-compliant sites over uncertified alternatives regardless of price positioning.
Consumption-based infrastructure provisioning is displacing traditional capacity reservations among regional enterprises. Saudi fintechs and Qatari logistics operators now procure compute through flexible rack-unit subscriptions rather than multi-year cage commitments. This pattern concentrates in Riyadh and Dubai where venture-backed scale-ups dominate demand growth.
GCC Data Center Market Segmentation
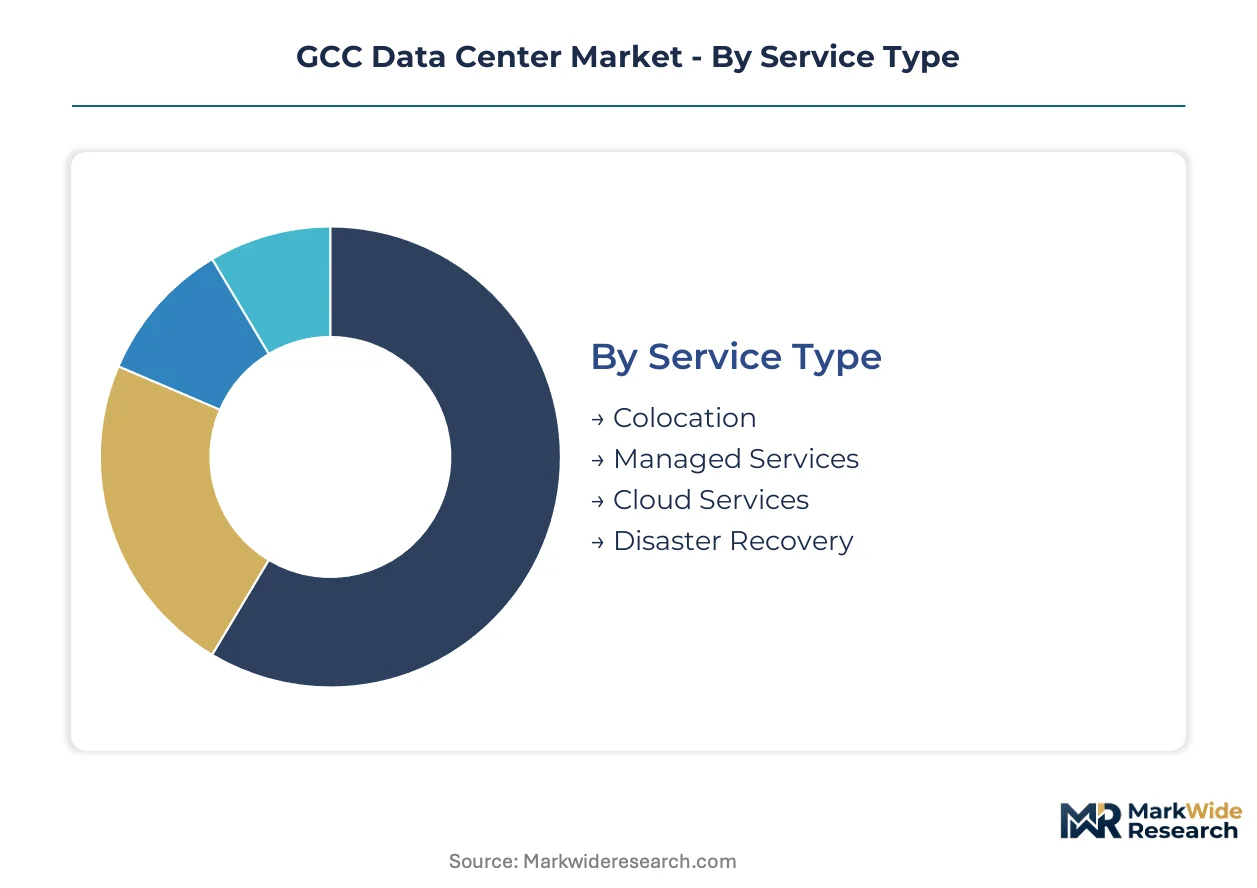
Facility operators across Saudi Arabia and the UAE structure service portfolios around sovereignty mandates and thermal constraints. Deployment patterns reveal how latency requirements and data localization rules partition capital allocation across the Arabian Peninsula.
Service Type:
Supply concentration in colocation reflects enterprise preference for asset-light infrastructure amid regulatory pressure for in-kingdom data hosting.
- Colocation:Rack, cage, and suite leasing arrangements dominate procurement as Saudi banks and UAE government entities shed owned facilities. Riyadh and Dubai hyperscale campuses absorb the majority of new capacity commitments driven by CSTC localization mandates.
- Managed Services:Remote hands, network operations, and cybersecurity monitoring command premium pricing. Saudi Aramco and Emirates NBD outsource infrastructure management to focus internal engineering on core applications.
- Cloud Services:Public and sovereign cloud delivery through localized regions satisfies TDRA and CSTC compliance requirements.
- Disaster Recovery:Secondary site replication and business continuity planning address seismic and geopolitical risk profiles across Kuwait and Oman.
Colocation absorbs the bulk of installed capacity; managed services is expanding most quickly as skills scarcity drives outsourcing intensity.
Deployment Model:
Cost tier differentiation separates speculative builds from certified facilities, with hybrid architectures commanding intermediate price positioning between captive on-premise and multi-tenant alternatives.
- On-Premise:Dedicated facilities retain favor among Saudi defense and UAE sovereign wealth entities with classified workload requirements. Khazna and STC build captive campuses for single-tenant government contracts.
- Hybrid:Integrated on-premise and cloud orchestration dominates banking procurement patterns. Emirates NBD and Riyad Bank balance core ledger systems in owned cages with customer-facing applications on hyperscale cloud.
- Multi-Cloud:Workload distribution across AWS, Azure, and GCP local regions mitigates vendor concentration risk.
- Private Cloud:Single-tenant virtualized infrastructure serves healthcare and aviation tenants with strict data residency requirements.
Hybrid deployments absorb the bulk of enterprise commitments; multi-cloud configurations are climbing the fastest as fintech scale-ups avoid vendor lock-in.
End User:
Application-specific reliability requirements partition the customer base, with financial services and government contracts demanding Tier III certification that general commercial tenants bypass.
- Telecommunications:STC, Etisalat, and Zain anchor demand for network-dense facilities with sub-millisecond latency to mobile switching centers. 5G core network virtualization concentrates compute requirements in Jeddah and Dubai metro clusters.
- BFSI:Banking, financial services, and insurance institutions drive sovereign-grade facility construction. SAMA and UAE Central Bank cybersecurity frameworks mandate certified colocation for payment infrastructure.
- Government:Federal and municipal entities procure through TDRA and CSTC pre-qualified facility lists.
- E-Commerce:Last-mile logistics platforms and payment gateways seek edge proximity in Riyadh and Dubai retail corridors.
BFSI absorbs the bulk of premium-tier capacity; e-commerce is gaining share fastest as digital retail penetration accelerates across secondary GCC cities.
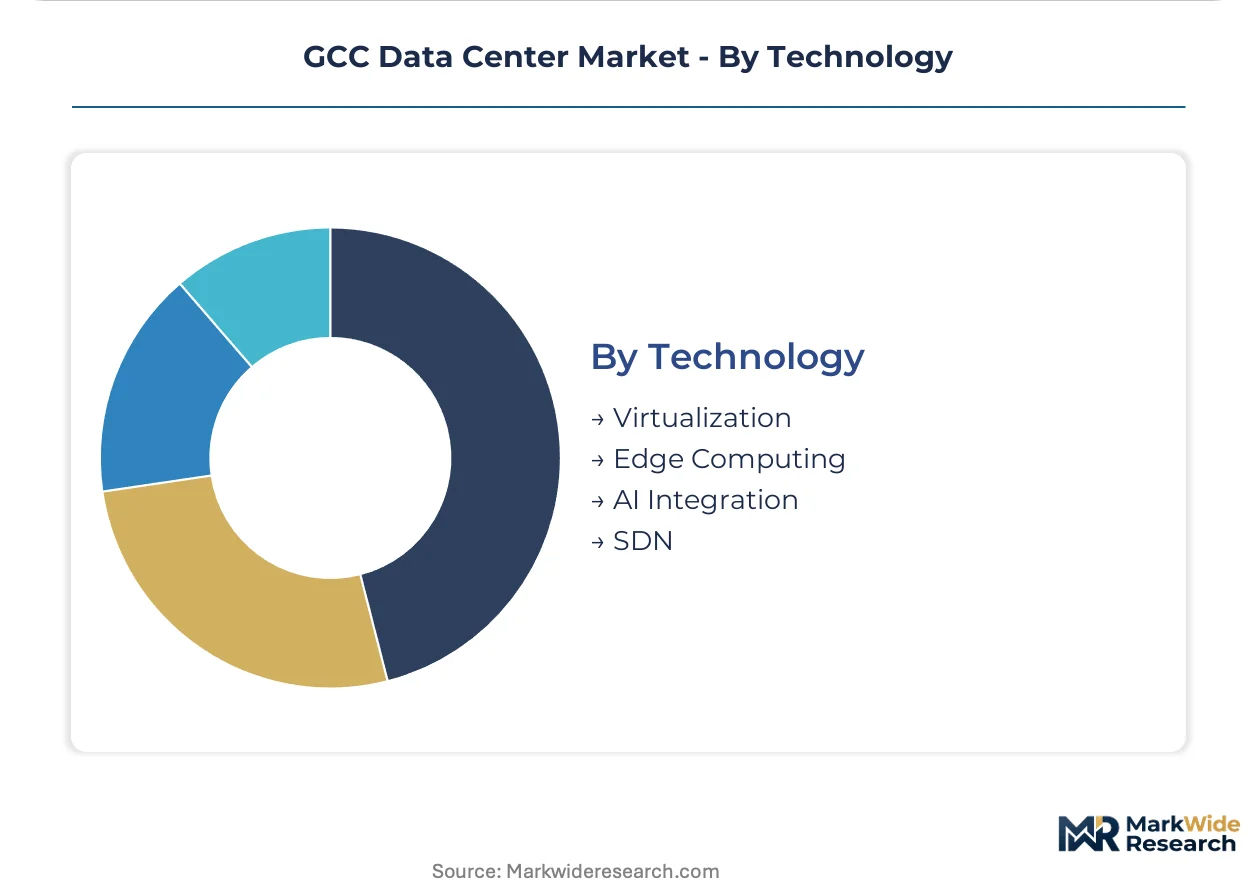
Technology:
Margin structures favor software-defined architectures over hardware-centric legacy designs, with AI integration capturing development resources previously allocated to basic virtualization layers.
- Virtualization:Server consolidation and workload abstraction remain foundational across enterprise migrations. VMware and Hyper-V deployments dominate legacy refactoring projects in Kuwaiti and Qatari banks.
- Edge Computing:Distributed micro-facilities address autonomous vehicle and industrial sensor latency requirements. NEOM and Dubai South smart city deployments concentrate edge nodes within 10 kilometers of data generation points.
- AI Integration:GPU clusters and inference-optimized silicon attract petroleum and logistics sector investment.
- SDN:Software-defined networking enables programmable traffic management across multi-tenant environments.
Virtualization retains the bulk of installed base; edge computing is climbing the fastest as smart city infrastructure scales across Saudi giga-projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai Internet City and Dubai South anchor hyperscale construction across the Arabian Peninsula, with sovereign mandates and smart city deployments concentrating capacity in metropolitan clusters.
Saudi Arabia
Riyadh and Jeddah absorb the majority of new facility commitments as the Communications, Space and Technology Commission enforces data localization for citizen information. SAMA cybersecurity frameworks mandate certified colocation for payment infrastructure. NEOM's smart city deployment concentrates edge nodes within 10 kilometers of data generation points.
United Arab Emirates
Abu Dhabi and Dubai campuses capture multinational enterprise demand through sovereign-grade certifications. The Telecommunications and Digital Government Regulatory Authority mandates tiered reliability standards for government contract eligibility. Khazna Data Centers anchors capacity expansion with pre-certified Tier III designs.
Qatar
Doha facilities serve liquefied natural gas trading platforms and aviation logistics with low-latency requirements. The national communications regulator is maturing data protection frameworks that will determine certification burdens for new entrants. Lusail smart city infrastructure concentrates edge computing demand in metropolitan corridors.
Kuwait
Kuwait City financial institutions seek disaster recovery sites to address seismic risk profiles. The central bank is developing cybersecurity guidelines that will shape procurement patterns for banking infrastructure. Water scarcity elevates operational costs for evaporative cooling systems in planned facilities.
Oman
Muscat and Salalah attract submarine cable landing stations that anchor regional connectivity hubs. Nascent data protection frameworks offer first-mover positioning before certification requirements formalize. Duqm special economic zone provides land and power incentives for speculative builds targeting Indian Ocean traffic.
GCC Data Center Market Key Industry Players
The competitive structure tilts toward sovereign-certified specialists and global interconnection platforms. Facility operators differentiate through certification grade rather than price positioning. Three archetypes dominate: telecommunications incumbents with captive fiber assets, hyperscale developers with government partnerships, and carrier-neutral colocation specialists with dense connectivity fabrics. Capacity expansion and strategic partnerships constitute the dominant competitive moves as operators secure land and power ahead of regulatory maturation.
Within the telecommunications incumbent tier, stc and Ooredoo exemplify vertically integrated providers leveraging captive network infrastructure. Among carrier-neutral specialists, Gulf Data Hub and Equinix occupy positions emphasizing interconnection density and multinational enterprise access. Khazna Data Centers represents the sovereign-grade archetype with government-linked capacity expansion in Abu Dhabi.
| Leading Market Players |
|---|
| Edgnex Data Centres by DAMAC |
| Quantum Switch Tamasuk |
| Equinix |
| Ooredoo |
| stc |
| Gulf Data Hub |
| Moro Hub |
| Mobily |
| Khazna Data Centers |
| Others |
Cost & Logistics Intelligence
Saudi banking consortiums and UAE sovereign wealth procurement programs anchor demand for certified colocation, compressing price negotiation leverage toward long-term contract structures with embedded uptime guarantees.
Pricing Analysis
Uptime-based SLA anchoring governs facility economics across Riyadh and Dubai campuses. Tier III certification premiums separate Khazna and Gulf Data Hub offerings from uncertified speculative builds, while power density surcharges for liquid-cooled racks capture thermal management value. Cost compression in secondary GCC markets intensifies as Oman and Kuwait entrants compete on land and power incentives. Fintech scale-ups exhibit highest price sensitivity, prioritizing flexible rack-unit subscriptions over cage commitments; government entities accept premium positioning for sovereign-grade assurance.
Supply Chain Analysis
TDRA and CSTC facility pre-certification requirements gate component sourcing for critical infrastructure deployments. Server and networking hardware concentrates in Taiwan, South Korea, and USA manufacturing bases; diesel generators and precision cooling systems draw from European and Japanese specialist suppliers. Single-source vulnerability runs through semiconductor foundry concentration for GPU clusters. Distribution feeds from direct OEM relationships into EPC contractors managing hyperscale construction timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where CSTC localization mandates erect structural barriers that reward early certification investment and punish speculative builds lacking sovereign-grade pre-approval.
For Market Incumbents: Acquire land and power capacity reservations in Duqm and Salalah before regulatory maturation formalizes. Strengthen captive fiber assets through submarine cable landing station partnerships to defend against carrier-neutral specialists eroding connectivity density premiums. Pre-certify speculative builds to Tier III standards to compress revenue recognition delays from Uptime Institute assessment timelines. For New Entrants and Emerging Players: Capture edge computing deployment slots within NEOM and Dubai South smart city corridors where latency requirements outpace hyperscale campus construction. Target Omani and Kuwaiti markets where nascent data protection frameworks offer first-mover positioning ahead of certification formalization. Lead with consumption-based infrastructure provisioning to align with venture-backed fintech procurement preferences. For Investors and Strategic Acquirers: The window for entry favors sovereign-certified specialists with government-linked capacity pipelines over generic colocation operators lacking TDRA or CSTC pre-qualification. Long-term viability hinges on differentiation through certification grade rather than price positioning. Watch for AI training cluster demand inflection from Saudi Aramco and regional logistics operators seeking GPU-intensive sovereign-hosted infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Tier III Pre-Certification Investment | Compresses Uptime Institute assessment delays and accelerates government contract eligibility for Khazna-scale facilities. |
| Liquid Cooling Infrastructure Deployment | Enables 40kW-per-rack densities for Saudi Aramco AI inference workloads in desert climate constraints. |
| Submarine Cable Landing Partnership | Anchors Muscat and Salalah connectivity hubs for Indian Ocean traffic routing to Ooredoo and stc networks. |
| Green Hydrogen PPA Execution | Supports carbon-neutral facility claims for ESG-sensitive multinationals procuring through Equinix and Gulf Data Hub. |
| Edge Node Micro-Facility Construction | Addresses NEOM autonomous vehicle latency requirements within 10-kilometer proximity mandates. |
Research Approach
Regulatory filings from CSTC and TDRA, hyperscaler capex disclosures, and facility certification databases formed the secondary backbone for this analysis. Primary interviews with data center engineering directors, cloud procurement officers at Saudi banks, EPC contractors managing hyperscale builds, and connectivity specialists at submarine cable operators triangulated against secondary validation. Bottom-up capacity aggregation across Riyadh, Dubai, and Doha facilities combined with top-down cloud revenue attribution to derive market sizing.
Historical trendline analysis of colocation commitments and managed services penetration established baseline growth patterns across the projection horizon. Segmentation modeling incorporated service type, deployment model, end-user vertical, and technology tier dimensions. CAGRs derived from regression analysis of certified capacity additions against localization mandate enforcement timelines. Forecast inputs included smart city edge deployment schedules and AI training cluster procurement intentions from petroleum and logistics sectors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory maturation trajectories in Oman and Kuwait, grid interconnection delays in secondary cities, and skilled technician production rates constraining operational scaling. A model refresh is warranted upon material change in CSTC cross-border data transfer enforcement or TDRA tier certification requirement expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
Taiwan Data Center Physical Security Market
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
Vietnam Data Center Power Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
Jakarta Data Center Market
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
China Data Center Physical Security Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Denmark Data Center Power Market
Data Center Infrastructure
Los Angeles Data Center Market