
 Data Center Support Infrastructure Market | 2026-2036
Data Center Support Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Support Infrastructure Market Intelligence
AI-driven rack density is tilting thermal management toward liquid cooling architectures. Schneider Electric leverages its integrated power and cooling portfolio to anchor hyperscale contracts across multiple continents. Vertiv Holdings Co sustains engineering intensity in edge power systems, while Eaton Corporation plc differentiates through intelligent power distribution software that competes with legacy hardware-centric vendors.
Data center support infrastructure encompasses the physical systems that sustain continuous IT operations, including precision cooling equipment rated for densities exceeding 50 kW per rack, uninterruptible power supplies with modular scalability, and fire suppression engineered for occupied electronic environments. Cooling Systems and Power Distribution Units command the largest installed base, though Liquid Cooling and Intelligent Power Management represent the fastest-expanding margin pools as thermal loads intensify. Cloud Data Centers and Hyperscale Data Centers absorb the dominant share of capital deployment, while Edge Data Facilities emerge as a distinct application requiring compact, hardened support equipment.
The EPA enforces ENERGY STAR server specifications that cascade into cooling and power efficiency requirements, while the EU F-Gas Regulation phases down refrigerants used in precision air conditioning units. OSHA electrical safety standards and NFPA fire codes further constrain equipment design and installation protocols across US facilities. Stakeholders must weigh liquid cooling retrofit economics against new-build deployments as rack densities climb beyond air-cooling thresholds.
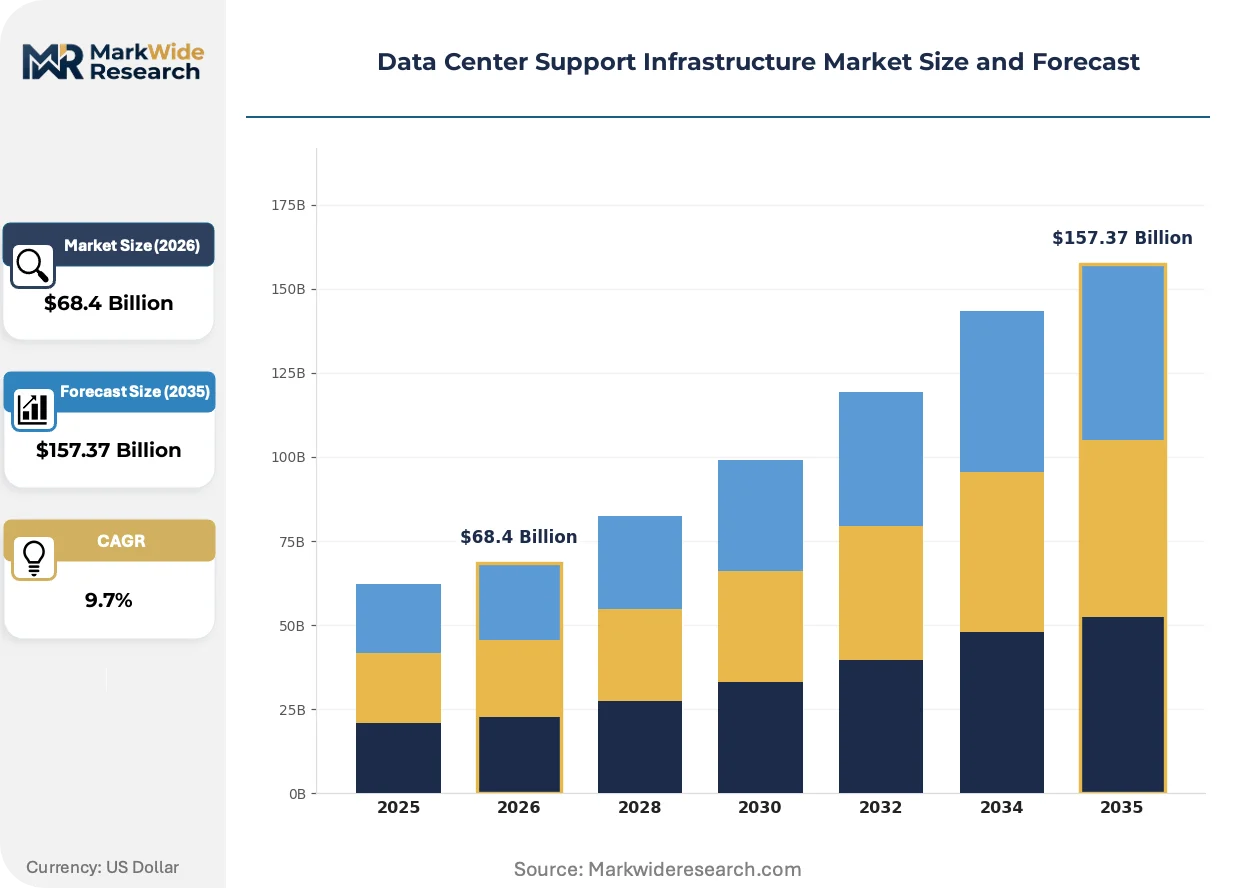
Market Dynamics
AI rack densities exceeding 50 kW per rack are compressing thermal design cycles and forcing infrastructure refresh decisions years ahead of depreciation schedules. This density inflection is redrawing supplier relationships and procurement criteria across hyperscale and enterprise facilities.
Growth Catalysts
- ENERGY STAR Certification:The EPA's server efficiency specifications cascade into cooling and power procurement mandates, pulling upgrade cycles forward across US enterprise data centers.
- Liquid Cooling Technology:Direct-to-chip and immersion architectures unlock compute densities impossible under air-cooling physics, enabling AI training clusters in previously space-constrained facilities.
- Hyperscale Expansion:Cloud operators in India, Germany, and the United States are deploying regional capacity to satisfy data sovereignty requirements and latency-sensitive workloads.
Market Restraints
- Copper and Rare Earth Volatility:Power distribution busbars and high-efficiency motor windings expose infrastructure OEMs to commodity swings without contractual pass-through mechanisms.
- Refrigerant Phase-Down:The EU F-Gas Regulation constrains hydrofluorocarbon supply for precision air conditioning units, compressing service margins and retrofit economics.
- Skilled Technician Scarcity:Liquid cooling system commissioning and maintenance require specialized fluid dynamics expertise that outpaces vocational training pipeline output.
Strategic Opportunities
- Edge Facility Hardening:Compact, thermally resilient support equipment for telecom shelters and manufacturing floors remains undersupplied relative to projected distributed compute deployment.
- Intelligent Power Convergence:Integration of power distribution software with building management systems creates new value pools beyond hardware-centric legacy vendor offerings.
- India Manufacturing Incentives:The PLI scheme for electronics and component production supports domestic assembly of modular UPS and cooling units for regional hyperscale demand.
Industry Challenges
- NFPA Fire Code Compliance:Suppression system design for occupied electronic environments requires extensive third-party validation, extending certification timelines for new liquid cooling architectures.
- Legacy Air-Cooling Stranded Assets:Facilities with recent precision air investments face accelerated obsolescence as rack densities breach 30 kW thresholds, complicating capital recovery planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Support Infrastructure Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $157.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Systems, Power Distribution Units, Rack Cabinets, Fire Suppression Systems, Cable Management Technology: Liquid Cooling, Air Cooling, Modular UPS, Static Transfer Switch, Intelligent Power Management Application: Cloud Data Centers, Colocation Facilities, Edge Data Facilities, Hyperscale Data Centers, Managed Hosting End User: IT Service Providers, Telecommunication Operators, Financial Institutions, Government Agencies, Research Organizations |
| Companies Covered | Schneider Electric, Vertiv Holdings Co, Eaton Corporation plc, ABB Ltd, Emerson Electric Co, Delta Electronics, Inc., Siemens AG, Johnson Controls International plc, Rittal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Support Infrastructure Market Strategic Shifts & Innovations
Thermal management architectures are bifurcating between liquid-cooled high-performance zones and optimized air-cooled legacy footprints. This technical schism is fragmenting supplier portfolios and reshaping facility engineering standards.
Immersion cooling using dielectric fluids is rendering obsolete conventional raised-floor air distribution in AI training halls. Hyperscale operators in the United States and Germany are deploying tank-based systems at multi-megawatt scale. The technology is rendering obsolete the mechanical infrastructure layer that consumed 35-40% of facility capital in previous build cycles.
The EU F-Gas Regulation is accelerating refrigerant transitions in precision cooling equipment. Manufacturers must reformulate heat transfer fluids and redesign compressor architectures to maintain efficiency under lower-global-warming-potential constraints. European hyperscale procurement now mandates reclaimed or natural refrigerant compatibility as a baseline qualification.
Buyers are consolidating infrastructure procurement under integrated platform contracts rather than discrete component sourcing. Hyperscale operators in India are awarding single-vendor power and cooling packages that bundle engineering, commissioning, and long-term service. This concentration is compressing margins for standalone equipment suppliers while rewarding system integrators with software-defined control layers.
Data Center Support Infrastructure Market Segmentation
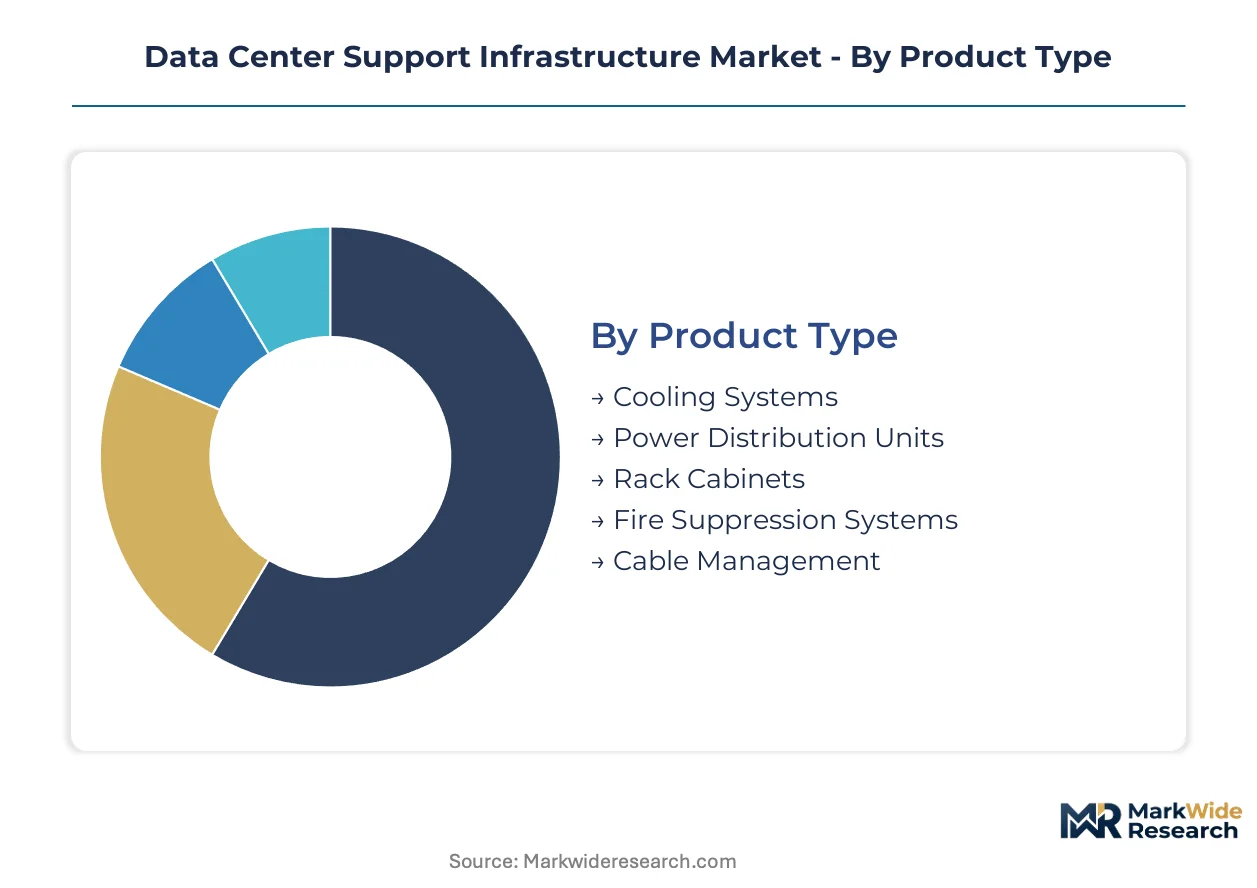
Segmentation reveals divergent engineering requirements across deployment scales. Procurement patterns for hyperscale liquid cooling bear little resemblance to edge facility power distribution, forcing suppliers to maintain parallel product architectures.
Product Type:
After-sales service intensity varies sharply across physical infrastructure categories, with cooling systems demanding continuous refrigerant monitoring and power units requiring battery replacement cycles.
- Cooling Systems:Precision air conditioning and liquid cooling architectures manage thermal loads exceeding 50 kW per rack. Demand concentrates in Germany and United States hyperscale halls where AI training clusters drive direct-to-chip and immersion deployments against F-Gas regulatory constraints.
- Power Distribution Units:Modular busbar systems and intelligent rack PDUs distribute electricity with remote monitoring capabilities. Financial institutions in Frankfurt and Singapore prioritize these units for uptime guarantees under Basel operational risk frameworks.
- Rack Cabinets:Enclosures with integrated cable management and thermal containment features. Colocation providers specify these for multi-tenant density optimization.
- Fire Suppression Systems:Clean agent and water mist systems engineered for occupied electronic environments. NFPA validation requirements extend certification timelines for new liquid cooling architectures.
- Cable Management:Overhead and underfloor routing systems supporting fiber and power density. Edge deployments in India favor compact configurations for telecom shelter constraints.
Cooling Systems holds the largest share; momentum sits with Power Distribution Units.
Technology:
Technology selection determines capital recovery horizons, with liquid cooling compressing depreciation schedules against legacy air-cooled assets.
- Liquid Cooling:Direct-to-chip cold plates and immersion tanks using dielectric fluids transfer heat beyond air-cooling physics limits. Hyperscale operators in United States and Germany deploy tank-based systems at multi-megawatt scale for AI training clusters.
- Air Cooling:Raised-floor precision air conditioning with hot aisle containment. Enterprise facilities in India retain these systems for densities below 30 kW per rack.
- Modular UPS:Scalable uninterruptible power supply units with N+1 redundancy. Cloud data centers specify these for incremental capacity expansion.
- Static Transfer Switch:Sub-cycle switching between power sources for critical loads. Financial institutions mandate these for trading floor continuity.
- Intelligent Power Management:Software-defined control layers integrating with building management systems. This segment is expanding most quickly as procurement shifts toward integrated platform contracts.
Liquid Cooling commands premium pricing; Intelligent Power Management is climbing the fastest.
Application:
Application scale dictates supplier engagement models, from single-vendor hyperscale packages to fragmented enterprise component sourcing.
- Hyperscale Data Centers:Single-tenant facilities exceeding 50 MW with customized infrastructure stacks. Operators in India award integrated power and cooling contracts bundling engineering and long-term service.
- Cloud Data Centers:Multi-tenant facilities serving public cloud workloads. United States and Germany host the dominant share of regional capacity for data sovereignty compliance.
- Colocation Facilities:Third-party data centers leasing space to multiple enterprises. These operators balance legacy air cooling against liquid cooling retrofit economics.
- Edge Data Facilities:Distributed compute nodes in telecom shelters and manufacturing floors. Compact, thermally resilient equipment remains undersupplied relative to projected deployment.
- Managed Hosting:Service providers operating dedicated infrastructure for single clients. These facilities lag hyperscale technology adoption by two to three upgrade cycles.
Hyperscale Data Centers absorb the dominant capital deployment; Edge Data Facilities show the steepest expansion trajectory.
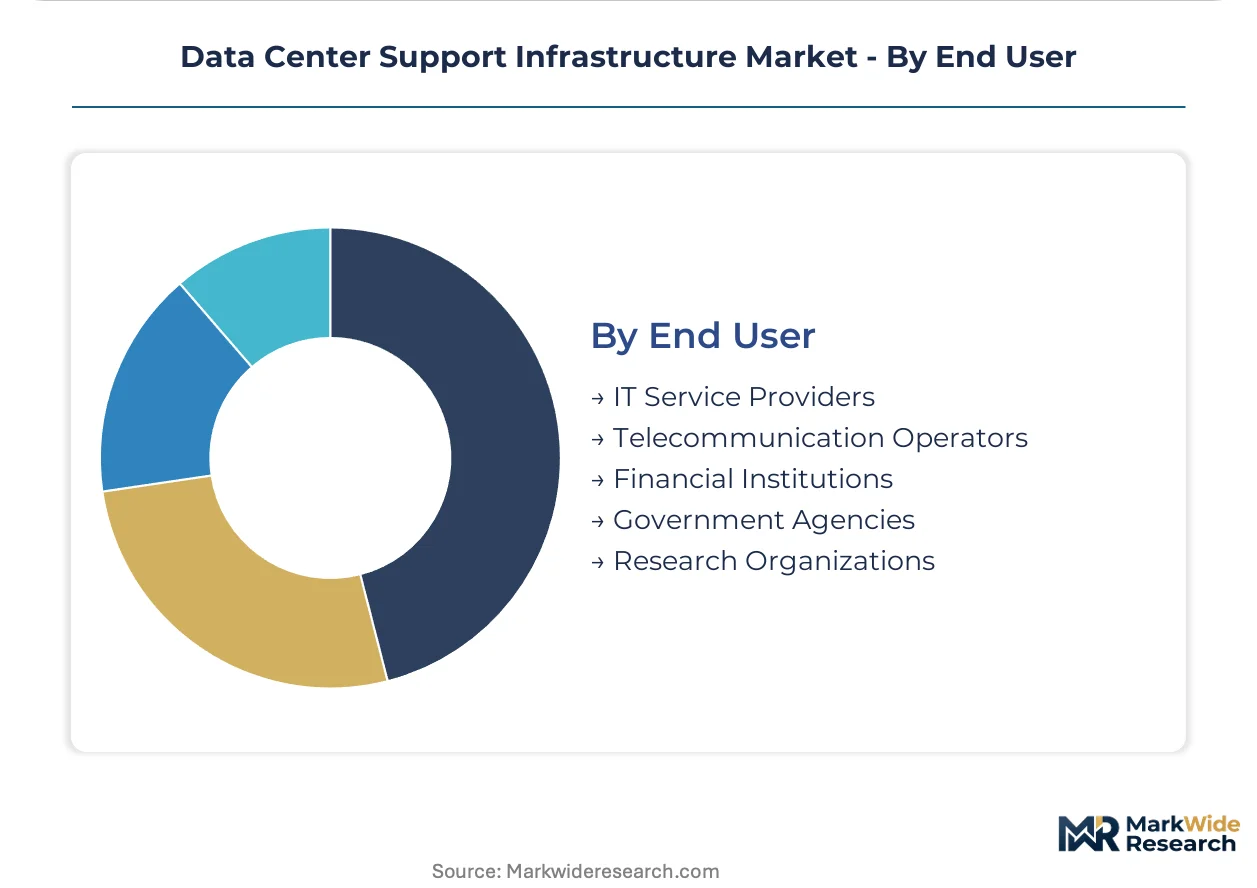
End User:
End user risk tolerance shapes specification stringency, with financial and government mandates exceeding commercial thresholds.
- IT Service Providers:Cloud and managed service operators building owned or leased capacity. These buyers consolidate procurement under platform contracts favoring integrated vendors.
- Telecommunication Operators:Carriers deploying edge infrastructure for 5G and low-latency services. Indian operators leverage PLI scheme incentives for domestic modular UPS assembly.
- Financial Institutions:Banks and exchanges with zero-downtime requirements. Frankfurt and Singapore facilities specify intelligent power distribution under operational risk regulations.
- Government Agencies:Sovereign data centers with security and data localization mandates. Indian government cloud drives regional hyperscale expansion.
- Research Organizations:Academic and national laboratory HPC installations. These users pioneer immersion cooling at densities exceeding commercial norms.
IT Service Providers represent the largest demand pool; Research Organizations pioneer technology transitions earliest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering exports liquid cooling systems to hyperscale operators across the United States and India, establishing the primary trade corridor for high-density thermal infrastructure.
United States
Hyperscale operators in Northern Virginia and Phoenix deploy multi-megawatt liquid cooling clusters for AI training workloads. EPA ENERGY STAR server specifications cascade into cooling procurement mandates across enterprise facilities. Dallas-Fort Worth and Atlanta emerge as secondary concentration zones for modular UPS assembly serving regional cloud capacity.
Germany
Frankfurt's financial district drives intelligent power distribution demand under Basel operational risk frameworks. EU F-Gas Regulation accelerates refrigerant transitions in precision cooling equipment manufactured in Bavaria. Berlin-Brandenburg hosts immersion cooling pilot installations for research organization HPC clusters exceeding commercial density norms.
India
Cloud providers expand Mumbai and Chennai capacity to satisfy data sovereignty requirements under proposed data protection legislation. PLI scheme incentives support domestic assembly of modular UPS and cooling units for regional hyperscale demand. Telangana's Hyderabad cluster attracts integrated infrastructure contracts bundling engineering and long-term service.
China
Beijing-Tianjin-Hebei corridor concentrates domestic cloud operator procurement of air-cooled systems for densities below 30 kW per rack. MIIT efficiency standards constrain power usage effectiveness ratios in state-owned data center portfolios. Yangtze River Delta manufacturers supply busbar systems to Southeast Asian hyperscale expansion.
Singapore
Financial institutions mandate intelligent rack PDUs for trading floor continuity under Monetary Authority operational resilience guidelines. Tropical climate conditions compress cooling system replacement cycles versus temperate geographies. The city-state functions as procurement hub for Southeast Asian edge facility hardening requirements.
Data Center Support Infrastructure Market Key Industry Players
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated platform vendors bundle power, cooling, and software layers under single-vendor contracts that compress margins for standalone equipment suppliers. Product specialists retain position in edge facility segments where compact form factors outweigh system integration value. Dominant competitive moves include geographic expansion into India manufacturing zones and technology licensing partnerships for liquid cooling architectures.
Among France-based conglomerates, Schneider Electric exemplifies the integrated platform archetype spanning multiple continents. Vertiv Holdings Co and Eaton Corporation plc occupy positions within the North American tier, with the former representing engineering intensity in edge power systems and the latter anchoring intelligent power distribution software capabilities. These three entities collectively illustrate the competitive tension between hardware-centric legacy positioning and software-defined control layer convergence.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv Holdings Co |
| Eaton Corporation plc |
| ABB Ltd |
| Emerson Electric Co |
| Delta Electronics, Inc. |
| Siemens AG |
| Johnson Controls International plc |
| Rittal |
| Others |
Cost & Logistics Intelligence
Bavaria's precision cooling manufacturing cluster shapes downstream pricing power across European hyperscale procurement, with EU F-Gas Regulation compliance costs cascading into contract premiums for refrigerant-compatible systems. This geographic concentration of engineering-intensive production creates asymmetric negotiating leverage against buyers in India and the United States seeking liquid cooling retrofits.
Pricing Analysis
Next-generation liquid cooling architectures command substantial premiums over legacy air-cooled systems and transitional direct-to-chip configurations. Three-tier pricing structure across premium immersion tanks, standard cold-plate assemblies, and economy-grade precision air units reflects certification grade differentiation under EPA ENERGY STAR and EU F-Gas mandates. Cost compression in standard-tier power distribution units is intensifying because Indian PLI scheme incentives are expanding domestic modular UPS assembly capacity. Cloud hyperscalers exhibit lowest price sensitivity given bundled single-vendor procurement contracts, while colocation operators face acute margin pressure from stranded air-cooling assets.
Supply Chain Analysis
US export controls on advanced thermal interface materials and high-performance compressor technologies constrain flows to Chinese data center OEMs, fragmenting supplier relationships across geopolitical lines. Manufacturing concentrates in Germany, the United States, and China, with rare earth magnet supply for high-efficiency motor windings drawing from concentrated Chinese processing capacity. Single-source vulnerability sits with Taiwanese semiconductor content in intelligent power management controllers. Distribution runs through direct hyperscale platform contracts in India and Germany, bypassing traditional channel intermediaries for integrated power-cooling bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as AI rack densities breach air-cooling physics limits, forcing infrastructure refresh decisions ahead of traditional depreciation schedules. Liquid cooling penetration remains below saturation thresholds across enterprise facilities, creating runway for technology-transition plays.
For Market Incumbents: Entrench integrated platform positioning by bundling power, cooling, and software layers under single-vendor contracts that compress standalone equipment supplier margins. Deepen backward integration into dielectric fluid formulation to secure supply continuity against EU F-Gas regulatory constraints. Channel control through long-term service agreements anchors hyperscale relationships against emerging liquid cooling specialists.
For New Entrants and Emerging Players: Edge facility hardening in Indian telecom shelters and Southeast Asian manufacturing floors represents the most penetrable entry point, with compact thermally resilient equipment remaining undersupplied relative to projected distributed compute deployment. Immersion cooling component supply for research organization HPC clusters offers technology validation pathways before commercial scale. Go-to-market through specialized fluid dynamics commissioning partnerships bypasses incumbent service network advantages.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with dormant precision cooling divisions lacking AI-density product roadmaps. Long-term viability centers on software-defined control layer convergence rather than hardware-centric legacy positioning. The signal to watch is hyperscale procurement consolidation toward integrated platform contracts versus discrete component sourcing, indicating which supplier archetypes capture margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Technology Licensing | Dielectric fluid partnerships with German chemical specialists accelerate EU F-Gas-compliant product pipelines. |
| Intelligent Power Management Acquisition | Software-defined control layer targets compete with Eaton's building management system integration capabilities. |
| India Manufacturing Joint Venture | PLI scheme incentives support domestic modular UPS assembly for regional hyperscale demand concentration. |
| Edge Facility Hardening Product Launch | Compact thermally resilient designs address undersupplied telecom shelter and manufacturing floor deployments. |
| Hyperscale Platform Integration Partnership | Single-vendor power-cooling-service bundles mirror Schneider Electric's multi-continent contract structures. |
Research Approach
A standing panel of data center engineering directors, hyperscale procurement officers, thermal systems specialists, and facility operations managers provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews engaged infrastructure OEM product managers, refrigerant compliance consultants, and edge deployment architects at telecommunications operators. Secondary sources encompassed EPA ENERGY STAR certification databases, EU F-Gas Regulation implementation reports, hyperscaler capital expenditure disclosures, and NFPA fire code validation records. Bottom-up segment sizing triangulated against top-down market aggregation across product type, technology, application, and end user dimensions.
Scenario-bracketing framed analytical projections across the analysis window, with segmentation modeling spanning cooling architecture generation, deployment scale tier, geographic regulatory cluster, and buyer consolidation pattern. CAGRs derived from unit economics modeling of liquid cooling retrofit versus new-build capital deployment cycles. Forecast inputs incorporated AI training cluster density trajectories, refrigerant phase-down compliance cost curves, and skilled technician availability constraints.
Practitioners should monitor hyperscale procurement contract structures, EU F-Gas refrigerant price volatility, and liquid cooling commissioning technician pipeline output for early signals of forecast deviation. Forecasts reflect assumptions on technology transition velocity and regulatory enforcement intensity. Material shifts in AI workload density trajectories or export control scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Norway Data Center Power Market
Data Center Infrastructure
Ireland Data Center Power Market
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Jakarta Data Center Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
US Multi-Tenant (Colocation) Data Center Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
Japan Data Center Construction Market