
 Composable Infrastructure Market | 2026-2036
Composable Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Composable Infrastructure Market Intelligence
Software-defined resource pooling is expanding the capabilities of traditional data centers by replacing fixed, siloed hardware configurations. This fundamental shift toward fluid infrastructure allows for the dynamic allocation of compute and storage resources on demand. Hewlett Packard Enterprise leverages its established presence in enterprise IT to deliver integrated systems. Dell Technologies competes through its broad portfolio of servers and storage, while Cisco Systems anchors its strategy in advanced network fabric solutions.
Composable infrastructure is an architectural framework that disaggregates compute, storage, and network fabric into fluid resource pools managed entirely by software. Its core function relies on unified API-driven commands to dynamically provision physical resources for specific workloads, maximizing hardware utilization. Software-Defined Infrastructure represents the foundational technology layer, capturing a significant share of market investment. Hybrid Cloud deployments are becoming the dominant model as enterprises seek to balance on-premises security with public cloud scalability.
Data governance regulations like Europe's GDPR and the United States' HIPAA influence infrastructure design, requiring flexible data placement and auditable security controls. Concurrently, energy efficiency standards from bodies such as China's MEE and frameworks like the EU Green Deal impact hardware procurement and data center operations. These regulatory pressures directly shape both hardware and software development priorities. Enterprises must therefore decide on the optimal balance between achieving operational agility and managing long-term compliance risk.
Market Dynamics
The primary force shaping the market is the decoupling of hardware from its management software. This shift enables the fluid pooling of compute, storage, and networking resources to meet the demands of AI-driven analytics and hybrid cloud models.
Growth Catalysts
- AI and ML Workloads:The proliferation of Artificial Intelligence applications requires highly elastic and scalable infrastructure that can be dynamically reconfigured, a core competency of composable systems.
- Hybrid Cloud Integration:Enterprises are deploying composable infrastructure to create a consistent operational plane, enabling seamless workload mobility between on-premises data centers and public cloud environments.
- Data Sovereignty Regulations:Mandates like Europe's GDPR require precise control over data residency, which composable APIs facilitate by directing workloads to specific physical hardware within a jurisdiction.
Market Restraints
- High Initial Investment:The upfront capital expenditure for disaggregated hardware components and sophisticated management software presents a significant adoption barrier for many mid-sized enterprises.
- Vendor-Specific Ecosystems:Proprietary management APIs and hardware interconnects can lead to vendor lock-in, limiting interoperability and increasing long-term total cost of ownership for customers.
- Legacy System Complexity:Integrating a fluid, API-driven composable framework with existing siloed IT infrastructure poses significant technical and operational hurdles, slowing down modernization projects.
Strategic Opportunities
- Edge Computing Deployments:Extending composable principles to edge locations offers a way to manage distributed infrastructure for IoT and real-time processing in manufacturing and retail sectors.
- Green Data Center Initiatives:The ability to maximize hardware utilization and power down idle resources directly supports energy efficiency goals under frameworks like the EU Green Deal.
- Open Source Management Platforms:Development of open standards like Redfish by the DMTF creates opportunities for third-party software vendors to offer cross-platform management and orchestration tools.
Industry Challenges
- Specialized Skills Gap:A shortage of IT professionals with deep expertise in software-defined infrastructure, automation scripting, and API integration hinders effective deployment and operational management.
- Integration with Legacy Security:Adapting traditional, perimeter-based security tools and policies to a dynamic, software-defined environment where resources are constantly provisioned and de-provisioned is a major challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composable Infrastructure Market |
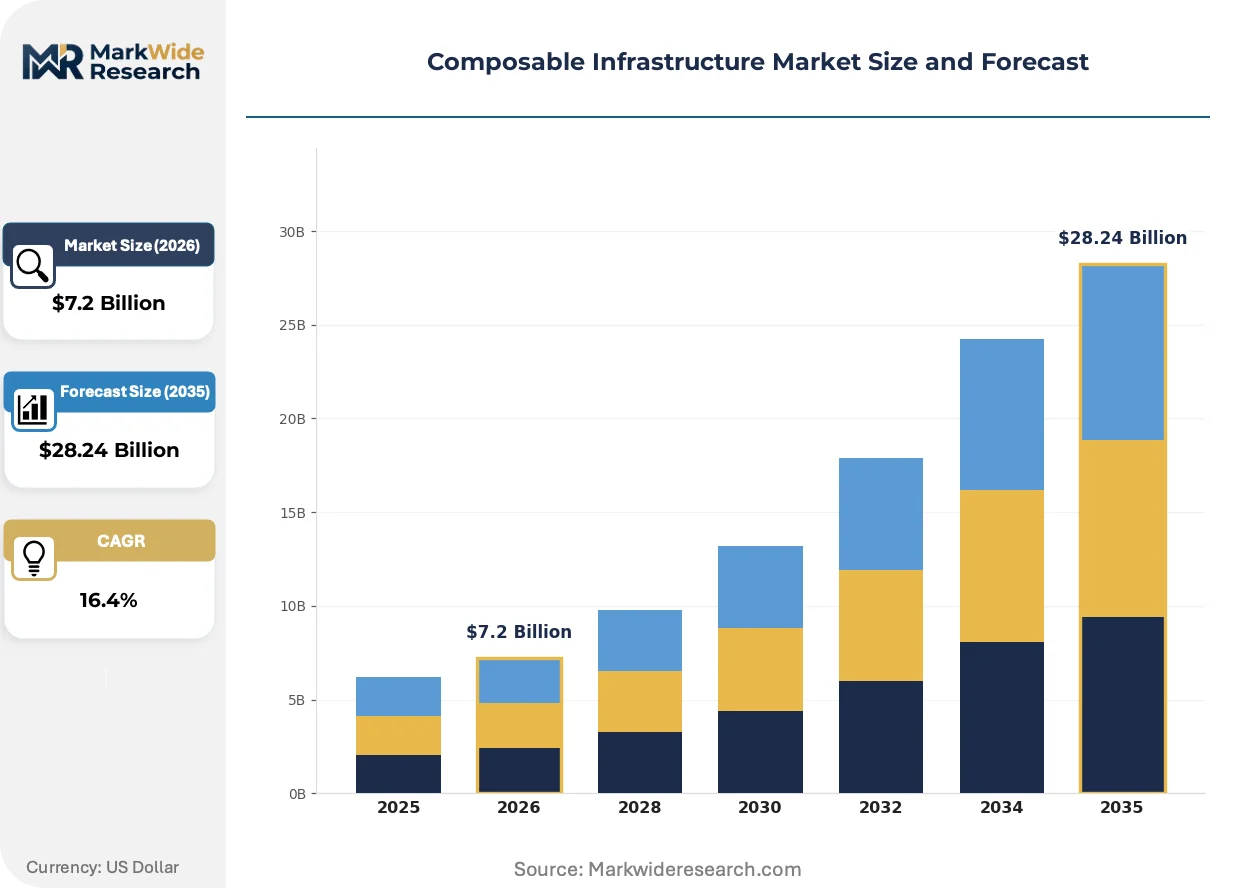
| Market Size in 2026 | $7.2 Billion |
| Market Size in 2035 | $28.24 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software-Defined Infrastructure, Hardware Composability, Management Tools, Network Fabric, Storage Systems Deployment: Private Cloud, Hybrid Cloud, On-Premises, Multi-Cloud, Edge Data Centers Use Case: High Performance Computing, Big Data Analytics, Artificial Intelligence, DevOps, Virtual Desktop Infrastructure End User: Telecommunication Providers, IT Service Providers, Financial Institutions, Government Agencies, Research Laboratories |
| Companies Covered | Hewlett Packard Enterprise, Dell Technologies, Cisco Systems, Lenovo Group, Nutanix, NetApp, Juniper Networks, Liqid, DriveScale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composable Infrastructure Market Strategic Shifts & Innovations
Maturation of composable architecture beyond the hyperscale data center is becoming a core tenet of enterprise IT modernization. Software intelligence now defines infrastructure capability, enabling automated management of increasingly complex and distributed application environments.
Composable Disaggregated Infrastructure (CDI) separates server components like CPUs, memory, and accelerators into independent, network-attached pools. Financial services and high-performance computing sectors are adopting CDI for workload-specific system composition. This technology is expanding into enterprise data centers to provide a more granular and efficient foundation for containerized applications.
China's Ministry of Ecology and Environment (MEE) is implementing stringent energy efficiency regulations for new and existing data centers. This compels operators to improve Power Usage Effectiveness (PUE) by retiring inefficient hardware. The data center hardware segment is most affected, accelerating the adoption of liquid cooling and power-aware composable systems.
A shift toward consumption-based procurement for infrastructure management software is gaining traction. This model disrupts the traditional perpetual license sale, replacing it with recurring subscription revenue tied to resource usage. The transition is most pronounced in North American and European enterprises seeking to align IT spending with actual workload demand.
Composable Infrastructure Market Segmentation
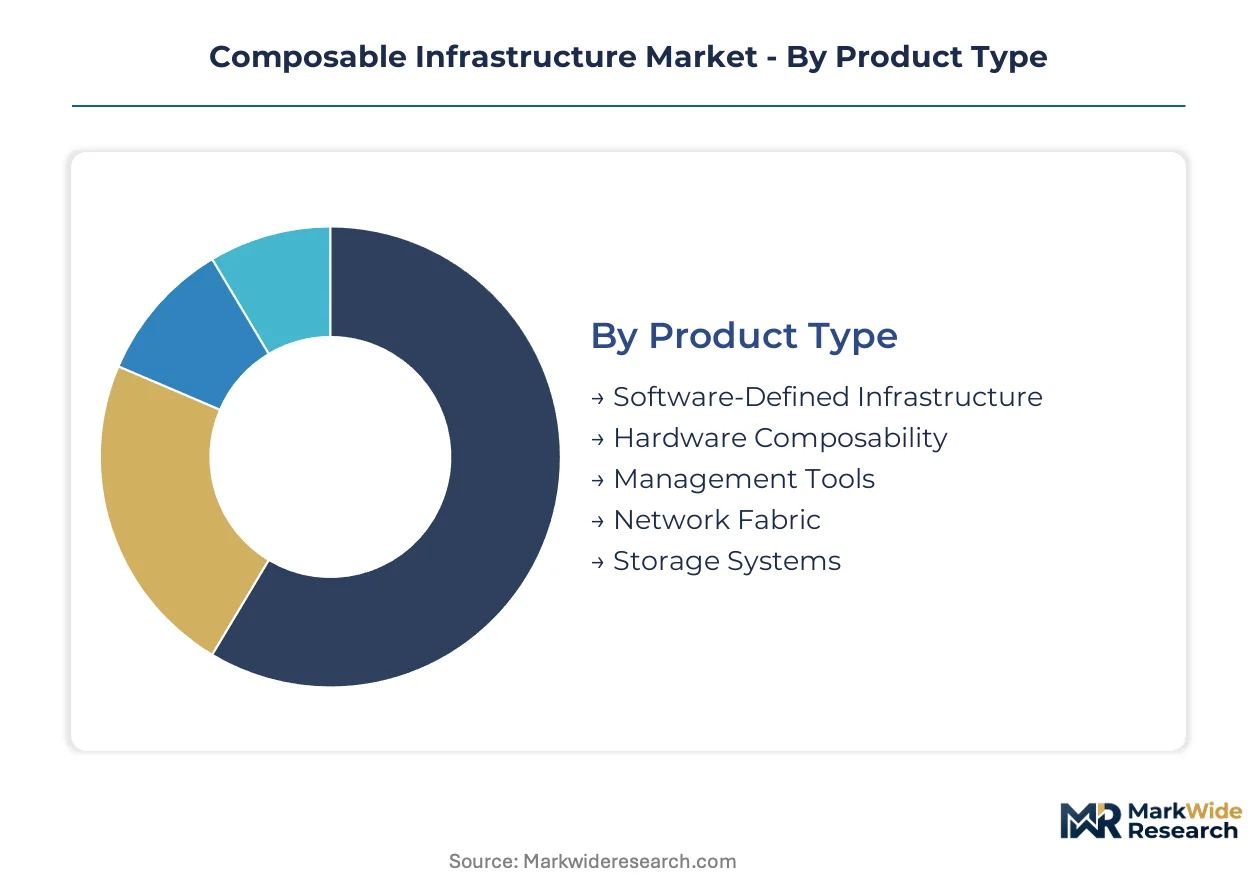
The Composable Infrastructure market segmentation offers a granular view into the technologies and applications driving its expansion. This analysis details the market's structure across product types, deployment models, use cases, and end-user verticals.
Product Type:
Composable infrastructure demand stems from continuous upgrade and replacement cycles for traditional IT hardware. Enterprises migrate to software-managed, disaggregated resource pools.
- Software-Defined Infrastructure:This segment encompasses foundational software layers managing compute, storage, and networking resources. It enables dynamic provisioning, crucial for hybrid cloud and AI workloads.
- Hardware Composability:This involves physical infrastructure designed for disaggregation, pooling components like CPUs and memory via high-speed fabrics. Financial services and HPC adopt this for workload-specific composition.
- Management Tools:These software platforms provide unified control, automation, and monitoring across composable infrastructure environments, simplifying orchestration.
- Network Fabric:This segment includes high-speed, low-latency interconnects linking disaggregated hardware components and resource pools, ensuring efficient data transfer.
- Storage Systems:This comprises disaggregated storage solutions dynamically provisioned and scaled independently of compute resources, supporting diverse data types.
Volume placements concentrate in Software-Defined Infrastructure; the faster expansion belongs to Hardware Composability.
Deployment:
Deployment models reflect evolving enterprise strategies for workload placement and data residency. Organizations balance on-premises control with public cloud scalability.
- Hybrid Cloud:This model integrates on-premises private cloud with public cloud services, creating a unified environment for workload mobility. Enterprises balance security with scalability.
- Edge Data Centers:These deployments place composable infrastructure closer to data sources at the network edge. They support real-time processing for IoT and distributed applications, utilized by manufacturing.
- Private Cloud:Enterprises deploy composable infrastructure within their data centers, maintaining full control over data, security, and compliance for sensitive workloads.
- On-Premises:Traditional data center deployments provide dedicated composable resources for specific applications or departments, offering direct control over hardware and software.
- Multi-Cloud:This strategy involves using multiple public cloud providers alongside private cloud resources, avoiding vendor lock-in and optimizing costs while enhancing redundancy.
Enterprises prioritize Hybrid Cloud for strategic initiatives, while Edge Data Centers represent the fastest-growing segment for new deployments.
Use Case:
Composable infrastructure addresses diverse and demanding requirements of modern enterprise applications. Its flexibility supports workloads from intensive data processing to agile development.
- Artificial Intelligence:This use case involves dynamically allocating GPU and specialized compute resources for machine learning training and inference. AI proliferation directly necessitates agile infrastructure.
- High Performance Computing:Composable systems provision dedicated, high-bandwidth resources for complex scientific simulations and engineering analyses. Financial institutions leverage this for real-time analytics.
- Big Data Analytics:This involves processing massive datasets using elastic compute and storage resources. Composable infrastructure enables efficient scaling for data warehousing.
- DevOps:Composable infrastructure provides on-demand, consistent environments for software development, testing, and deployment, accelerating application delivery pipelines.
- Virtual Desktop Infrastructure:This use case leverages composable resources to host and manage virtual desktops for end-users, offering flexible access and centralized management.
Artificial Intelligence workloads drive significant resource consumption, while DevOps benefits from the agile provisioning capabilities of composable architecture.
End User:
End-user segments adopt composable infrastructure to address specific operational challenges and regulatory requirements. Each sector leverages the technology for distinct strategic advantages.
- Financial Institutions:This sector utilizes composable infrastructure for real-time analytics, high-frequency trading, and stringent compliance workloads (e.g., GDPR, HIPAA). They require robust security.
- Telecommunication Providers:These companies deploy composable systems to manage network functions virtualization (NFV), 5G infrastructure, and edge services. They require scalable, flexible platforms for delivery.
- IT Service Providers:These organizations leverage composable infrastructure to offer managed services, cloud hosting, and data center solutions, benefiting from efficient resource pooling.
- Government Agencies:Public sector entities adopt composable infrastructure for secure data processing, digital transformation, and managing sensitive citizen data, influenced by data sovereignty.
- Research Laboratories:These institutions use composable systems for scientific computing, data-intensive simulations, and collaborative research, demanding high-performance reconfigurable environments.
Financial Institutions and Telecommunication Providers are primary adopters, seeking operational agility and workload performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for composable infrastructure is notably high in regions with advanced digital economies and significant data center investments. The United States leads in adoption, driven by hyperscale operators and enterprise IT modernization efforts. European and Asian nations are also rapidly integrating these agile systems to meet evolving regulatory and operational demands.
United States
Large hyperscale data center operators and enterprise IT modernization projects drive significant demand for composable infrastructure in the United States. Data privacy regulations like HIPAA mandate flexible data placement and auditable security, which composable systems facilitate. Technology hubs such as Silicon Valley and major data center clusters in Texas are actively deploying these solutions for AI-driven analytics.
China
China's market for composable infrastructure is propelled by stringent energy efficiency regulations and the rapid growth of AI applications. The Ministry of Ecology and Environment (MEE) mandates improved Power Usage Effectiveness (PUE) in data centers, accelerating hardware upgrades. Major tech centers like Beijing and Shenzhen are at the forefront of implementing power-aware composable systems for scalable cloud services.
Germany
Hybrid cloud deployments and the need for robust data sovereignty solutions fuel composable infrastructure adoption across Germany. The EU's GDPR influences infrastructure design, requiring precise control over data residency within national borders. Industrial centers in Bavaria and financial hubs in Frankfurt are investing in these flexible architectures for secure, high-performance computing.
India
India’s digital transformation initiatives and the expansion of telecommunication providers are key drivers for composable infrastructure. Government policies supporting local manufacturing and data localization, such as the PLI scheme, encourage domestic infrastructure development. Major IT service hubs like Bangalore and Hyderabad are deploying composable systems to manage massive data processing and cloud services.
Japan
Japan's demand for composable infrastructure stems from high-performance computing requirements and continuous enterprise IT upgrades, particularly in manufacturing. Guidelines from the Ministry of Economy, Trade and Industry (METI) promote data center efficiency and resilience. Industrial zones in the Tokyo metropolitan area and Osaka are implementing disaggregated systems for advanced analytics and agile application environments.
Composable Infrastructure Market Key Industry Players
Portfolio diversification dominates the current landscape, as established technology companies expand their composable infrastructure offerings. The market exhibits a tiered structure, with a few large integrated IT vendors competing alongside specialized software and hardware innovators. Strategic partnerships and technology licensing are prevalent competitive moves, aimed at broadening solution ecosystems and market reach.
Established IT providers like Hewlett Packard Enterprise and Dell Technologies exemplify the integrated systems approach, leveraging their broad portfolios of servers and storage. Cisco Systems, Inc. occupies a position as a networking powerhouse, anchoring its strategy in advanced network fabric solutions. These companies represent the foundational layer of composable infrastructure, offering comprehensive solutions for enterprise and hyperscale clients globally.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Dell Technologies |
| Cisco Systems |
| Lenovo Group |
| Nutanix |
| NetApp |
| Juniper Networks |
| Liqid |
| DriveScale |
| Others |
Cost & Logistics Intelligence
The Semiconductor Industry Association's average selling price index influences the cost of disaggregated hardware components, cascading through the composable infrastructure supply chain into distinct pricing tiers for software and services.
Pricing Analysis
Volume deployments of composable infrastructure prioritize cost-efficiency, while specialized high-performance computing applications command higher margins. The dominant pricing model for software components is subscription-based, often tiered by resource usage, with hardware sales transactional. Price differentiation stems from performance tier, customization level, and bundled after-sales service. Pricing pressure stems from increasing competition among hardware vendors, making mid-sized enterprises highly price-sensitive, while financial institutions and hyperscale operators prioritize performance.
Supply Chain Analysis
The supply of high-performance server components for composable infrastructure largely rests on manufacturing capabilities in Taiwan, South Korea, and the United States. Key dependencies include advanced semiconductor chips, high-speed network interconnects, and specialized memory modules. Geopolitical tensions affecting chip production present a significant structural risk for component availability. Distribution runs through direct sales from OEMs to large enterprises and hyperscalers, complemented by IT service providers offering integrated solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The composable infrastructure market represents a pivotal technology-transition phase, with Software-Defined Infrastructure displacing legacy fixed hardware configurations. This shift enables dynamic resource allocation, crucial for modern workloads.
For Market Incumbents: Anchor existing enterprise client relationships by expanding integrated composable offerings. Develop specialized solutions for AI workloads to counter emerging pure-play vendors. Invest in R&D for next-generation network fabric solutions to maintain competitive differentiation against commoditization. Consolidate software management platforms to simplify adoption and mitigate vendor-specific ecosystem concerns.
For New Entrants and Emerging Players: Begin with niche segments like edge computing or specific high-performance computing applications where existing solutions are less optimized. Target mid-sized enterprises seeking cost-effective, flexible solutions without extensive legacy infrastructure. Focus on open source management platforms to reduce vendor lock-in concerns and accelerate adoption. Provide value through simplified integration services and consumption-based procurement models.
For Investors and Strategic Acquirers: The window for entry favors specialist software providers offering advanced orchestration and API management capabilities. Long-term viability over the next 5-10 years depends on interoperability standards and adoption of disaggregated hardware. Target acquisition archetypes include firms with strong intellectual property in network fabric and AI-specific resource management. A key signal to watch is the widespread adoption of open standards like Redfish across diverse vendor ecosystems.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Platform integration simplifies management for enterprise IT teams. |
| Strategic Partnership | Strategic partnerships broaden ecosystem compatibility with cloud providers. |
| Acquisition of Specialist Firm | Acquisition of specialist firms enhances AI workload optimization capabilities. |
| Geographic Expansion | Geographic expansion targets growing demand in Asian and European markets. |
| Product Launch | Product launch of new API-driven tools accelerates DevOps adoption. |
Research Approach
SEC 10-K filings, industry association reports, and technology journals formed the secondary backbone for this analysis. This was complemented by primary interviews with CTOs, IT procurement officers, platform engineers, and data center architects. Bottom-up data aggregation from company disclosures was validated against top-down market sizing estimates. This triangulated approach ensured robust data integrity and comprehensive market understanding.
A bottom-up analytical framework informed the market forecast across the analysis window. Segmentation dimensions modeled include product type, deployment model, use case, and end-user vertical, alongside regional adoption patterns. Compound Annual Growth Rates were derived from historical data trends and projected technology adoption curves. Key inputs included enterprise IT spending forecasts and AI workload growth projections.
Geopolitical instability, rapid technological shifts, and evolving regulatory landscapes are the dominant revision risks. Forecasts reflect assumptions regarding economic conditions and technology adoption rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
Data Center Rack Solutions Market
Data Center Infrastructure
Australia Data Center Construction Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Italy Data Center Construction Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Thailand Data Center Power Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market