
 Germany Dairy Market | 2026-2036
Germany Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Dairy Market Insights
Multi-source milk procurement is consolidating across northern German cooperatives as processors seek supply security amid volatile farmgate prices. DMK Deutsches Milchkontor GmbH leverages its cooperative structure to anchor procurement across Lower Saxony and Schleswig-Holstein. Müller Group competes through vertical control of yogurt and fresh dairy production. Arla Foods amba sustains cross-border sourcing from Danish member farms into German manufacturing plants.
Germany dairy encompasses fluid milk, fermented products, and fat-based derivatives standardized for protein content, fat percentage, and microbiological safety through pasteurization or ultra-high-temperature processing. Cheese production dominates value generation, with hard and semi-hard varieties occupying the largest margin pools due to aging requirements and export premiums. Yogurt segments are expanding fastest through functional and probiotic positioning in supermarket channels. Tetra Pak aseptic cartons lead packaging for UHT milk, while glass bottles retain share in premium fresh segments and organic distribution.
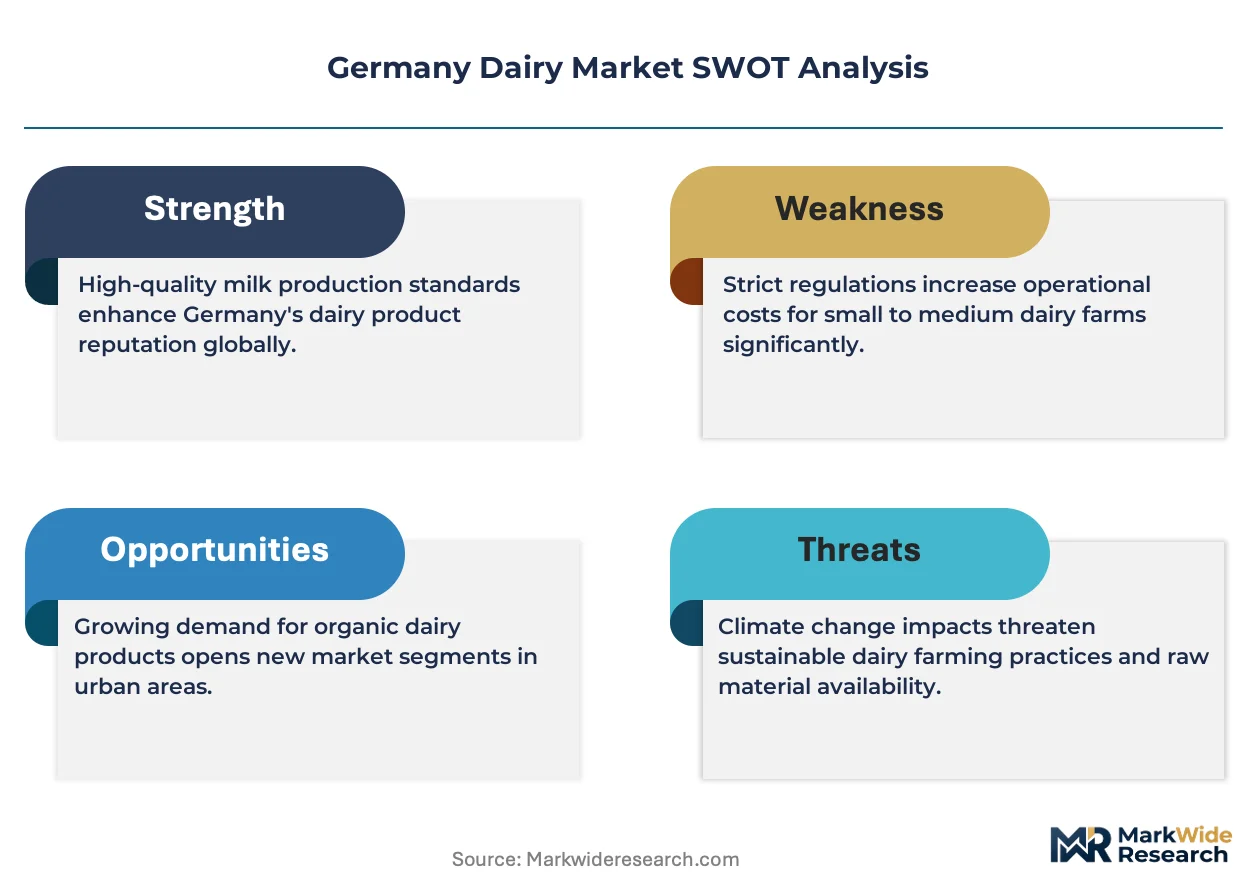
EMA food safety standards, EU Green Deal sustainability benchmarks, and Germany's national organic regulation (Bio-Siegel) shape product formulation, labeling claims, and cold-chain compliance obligations for all market participants. KBA emissions rules for refrigerated transport fleets add compliance costs that favor larger distributors with scale to retrofit logistics networks. Stakeholders must monitor how carbon accounting requirements for dairy farming reshape procurement premiums and cooperative membership terms.
Market Dynamics
The EU Green Deal's carbon accounting mandates are restructuring cooperative procurement premiums across Bavaria and northern Germany, forcing processors to renegotiate farmgate contracts based on methane-reduction compliance rather than volume alone.
Growth Catalysts
- F-Gas Regulation phase-down:Cold-chain operators in Lower Saxony are retrofitting milk storage facilities with natural refrigerants ahead of quota restrictions, accelerating equipment replacement cycles.
- Functional yogurt positioning:Probiotic and high-protein variants are capturing shelf space in REWE and Edeka channels as consumers substitute fermented products for supplements.
- Alpine milk zone clustering:Bavarian cooperatives are consolidating processing capacity near Allgäu supply basins to reduce collection transport emissions and capture organic premiums.
Market Restraints
- Feed input volatility:Soy and rapeseed meal prices swing with Black Sea supply disruptions, compressing farm margins and triggering volume hedging at DMK and Müller procurement desks.
- Schleswig-Holstein supply concentration:Northern Germany's cooperative dominance creates single-source vulnerability for fluid milk contracts when weather events hit the Elbe-Weser triangle.
- KBA fleet retrofit costs:Refrigerated transport operators face five-figure per-vehicle expenses to meet Euro VI-e emissions standards, favoring scale players with captive logistics.
Strategic Opportunities
- Bio-Siegel organic conversion:Conventional farms in Brandenburg are transitioning acreage to meet national organic regulation standards, unlocking 20-30% price premiums in Berlin retail channels.
- Precision fermentation convergence:Dairy proteins from biomass fermentation are nearing cost parity with traditional whey, enabling hybrid product lines for lactose-free positioning.
- Direct-to-foodservice channels:Bakeries and prepared-meal manufacturers in Munich and Hamburg are sourcing butter and cream outside wholesale markets, shortening payment cycles.
Industry Challenges
- Refrigeration technician scarcity:Natural refrigerant systems require ammonia and CO2 certification that fewer than 15% of existing cold-chain engineers hold, delaying retrofit timelines.
- EMA residue-testing backlog:Veterinary medicine clearance for export cheese lots now stretches 8-12 weeks, tying up working capital in aging inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Dairy Market |
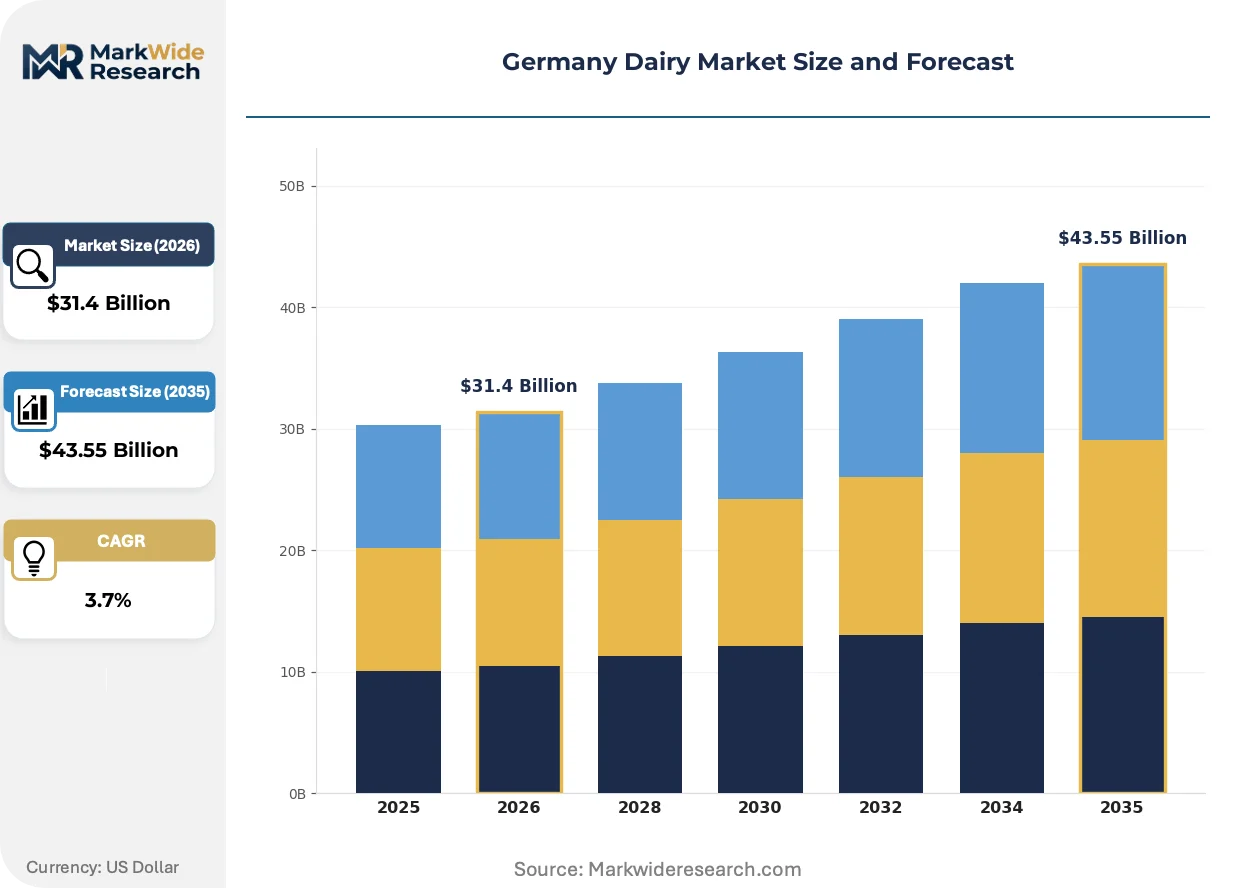
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $43.55 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter Packaging Type: Bottles, Tetra Packs, Cartons, Jars Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores End User: Household, Food Service, Retail, Industrial |
| Companies Covered | DMK Deutsches Milchkontor GmbH, Müller Group, Arla Foods amba, Groupe Lactalis, Danone SA, Molkerei Ammerland, FrieslandCampina Germany, Nordmilch, Hochwald Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Dairy Market Trends and Innovations
Aseptic processing advances and carbon-footprint labeling are compressing product development cycles while reshaping how German dairy manufacturers negotiate retail placement and export access.
Membrane filtration technology is unifying protein standardization across fluid milk, yogurt base, and whey powder production. Mid-sized processors in Bavaria are installing ceramic microfiltration systems to shift output between drinking milk and industrial ingredients within 48 hours. This flexibility is unifying what were previously separate production lines, reducing capital intensity for SKU proliferation.
Germany's KBA enforcement of Euro VI-e standards for refrigerated trucks is accelerating fleet turnover among distributors serving Aldi and Lidl networks. Operators running 50+ vehicles face compliance cliffs in 2027, pushing leasing consolidation toward larger logistics providers with retrofit capital. Cold-chain specialists are responding by pooling maintenance facilities across Lower Saxony to amortize technician training costs.
Foodservice buyers in Berlin and Hamburg are compressing supplier rosters from six dairy vendors to two or three, demanding consolidated invoicing and carbon-disclosure documentation. This concentration is displacing regional wholesalers who lack ESG reporting infrastructure. Bakery chains and contract caterers now specify cooperative-sourced butter with farm-level traceability, visible most sharply in Munich's premium retail corridor.
Germany Dairy Market Segmentation
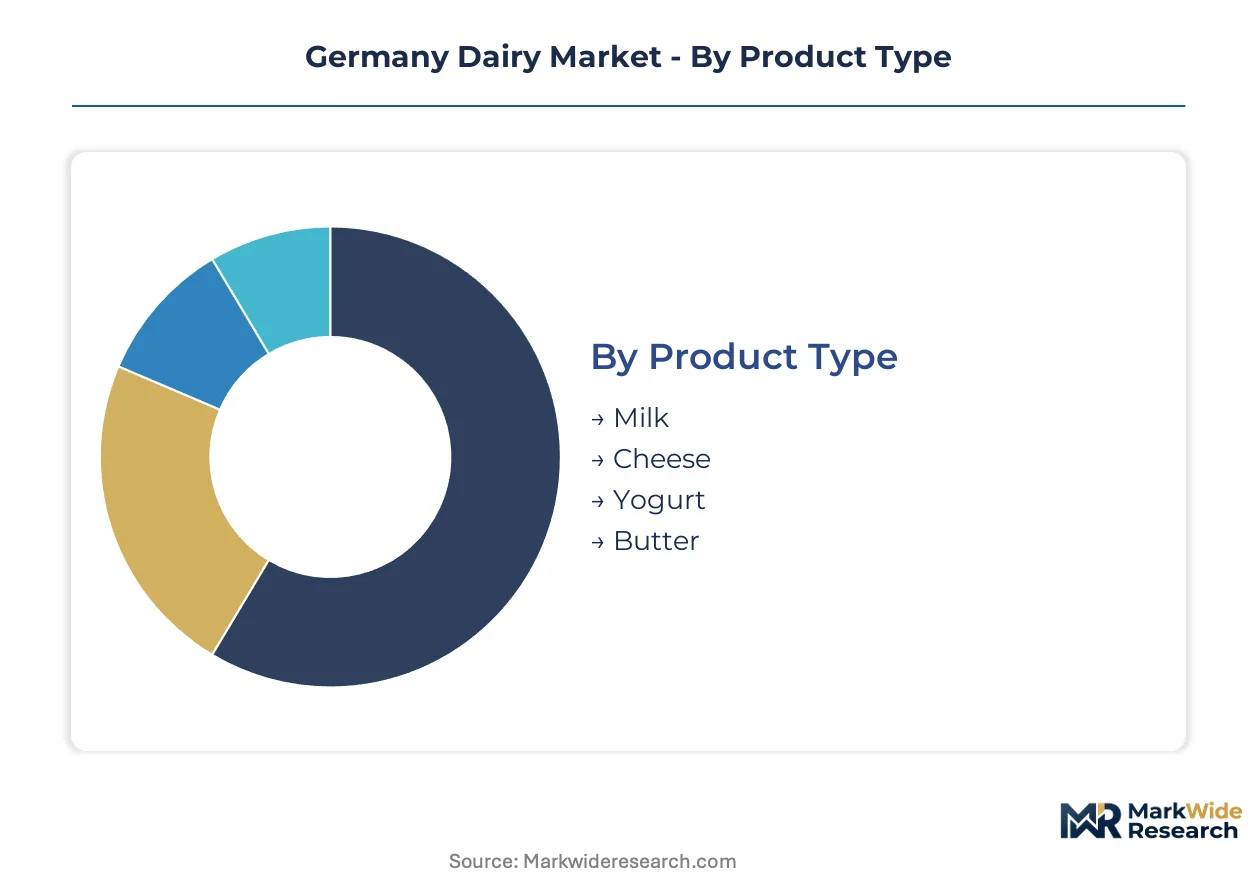
German dairy procurement patterns diverge sharply between retail and foodservice channels, with product specifications and packaging formats calibrated to distinct temperature requirements and shelf-life expectations. Segmentation clarity enables processors to allocate membrane filtration capacity and cold-chain investments across incompatible demand profiles.
Product Type:
Processing technology and aging protocols separate commodity fluid production from value-added derivatives, with protein standardization and fermentation control as the critical technical axes.
- Milk:Fluid milk undergoes pasteurization or UHT treatment to achieve microbiological safety standards, with protein content standardized through membrane filtration. Bavarian cooperatives concentrate procurement near Alpine supply zones to reduce collection transport emissions and capture organic premiums under Bio-Siegel regulation.
- Cheese:Hard and semi-hard varieties command the largest margin pools due to aging requirements and export premiums, with EMA residue-testing protocols creating 8-12 week clearance backlogs for export lots. DMK Deutsches Milchkontor GmbH anchors aging inventory across Lower Saxony facilities.
- Yogurt:Functional and probiotic positioning is expanding fastest through REWE and Edeka channels as consumers substitute fermented products for supplements.
- Butter:Fat-based derivatives serve bakery and prepared-meal manufacturers in Munich and Hamburg through direct sourcing outside wholesale markets.
Mature deployment sits with Cheese. Newer deployment is concentrated in Yogurt.
Packaging Type:
Barrier properties and aseptic capability determine shelf-life extension and cold-chain flexibility, with material selection driven by retail channel requirements and sustainability mandates.
- Tetra Packs:Aseptic carton systems enable UHT milk distribution without refrigeration, dominating volume throughput in Aldi and Lidl networks. Tetra Pak technology leads this segment with laminated barrier structures that block light and oxygen ingress.
- Bottles:Glass retains share in premium fresh segments and organic distribution, particularly in Berlin retail channels where farm-level traceability commands price premiums. Returnable bottle systems require dedicated logistics infrastructure that favors scale operators.
- Cartons:Gable-top fresh cartons serve short-shelf-life drinking milk in supermarket dairy cases.
- Jars:Glass jar formats concentrate in specialty yogurt and dessert applications through convenience store channels.
Volume leadership rests with Tetra Packs. Sustainability-driven substitution is accelerating fastest in Bottles.
Distribution Channel:
Footprint density and delivery frequency separate mass-market penetration from premium positioning, with ESG documentation requirements reshaping supplier consolidation.
- Supermarkets:REWE and Edeka networks compress supplier rosters from six vendors to two or three, demanding consolidated invoicing and carbon-disclosure documentation. This concentration displaces regional wholesalers lacking reporting infrastructure.
- Food Service:Bakeries and contract caterers in Munich specify cooperative-sourced butter with farm-level traceability, shortening payment cycles through direct procurement relationships.
- Convenience Stores:Urban density in Hamburg and Berlin drives refrigerated last-mile delivery requirements.
- Online Retail:Cold-chain integrity challenges limit fresh dairy penetration, with ambient UHT products dominating e-commerce volumes.
- Specialty Stores:Bio-Siegel certified organic products command 20-30% price premiums in dedicated retail formats.
Scale concentration is deepest in Supermarkets. Channel expansion is climbing the fastest in Food Service.
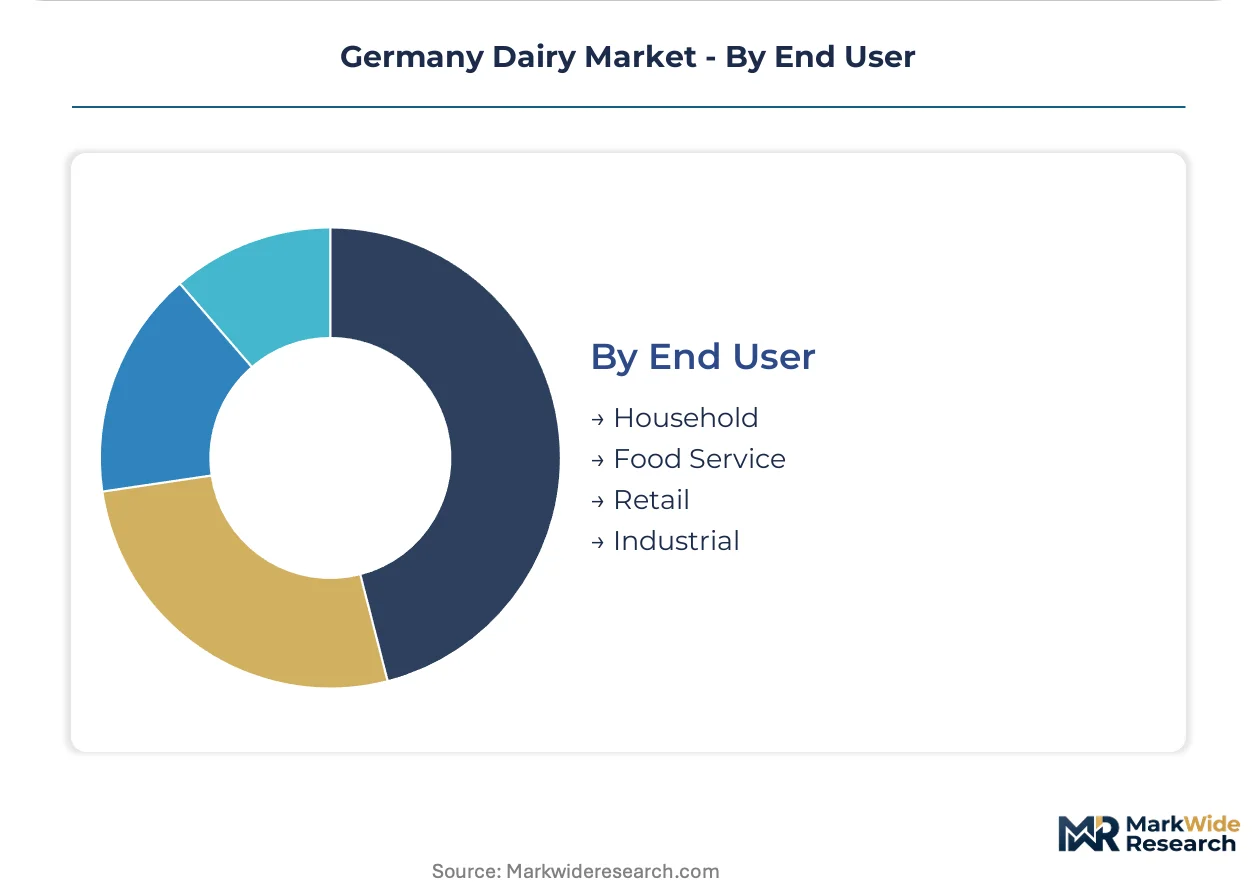
End User:
Volume predictability and specification rigor separate stable procurement relationships from spot-market volatility, with contract structures reflecting temperature sensitivity and shelf-life constraints.
- Household:Supermarket purchasing patterns drive standardized SKUs with consistent fat percentages and microbiological safety protocols through pasteurization.
- Industrial:Membrane filtration outputs shift between drinking milk and whey powder production based on ingredient demand, with ceramic microfiltration enabling 48-hour product line switches.
- Food Service:Prepared-meal manufacturers source cream and butter outside wholesale markets, demanding flexible delivery windows.
- Retail:Branded private-label positioning requires dedicated packaging lines and KBA-compliant refrigerated transport fleets.
Contract stability is strongest with Household. Specification complexity is expanding most quickly in Industrial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alpine pasture zones in southern Germany anchor raw milk supply quality, while northern grassland belts concentrate fluid milk volume. Regional procurement patterns diverge sharply between these feedstock geographies, shaping processor location decisions and cooperative membership structures.
Bavaria
Allgäu dairy cooperatives cluster near Alpine milk supply basins to reduce collection transport emissions. The EU Green Deal's carbon accounting mandates force processors to renegotiate farmgate contracts based on methane-reduction compliance. DMK Deutsches Milchkontor GmbH anchors aging inventory across regional facilities, capturing organic premiums under Bio-Siegel regulation.
Lower Saxony
Multi-source milk procurement consolidates across cooperatives as processors seek supply security amid volatile farmgate prices. F-Gas Regulation phase-down pressures cold-chain operators to retrofit milk storage facilities with natural refrigerants. DMK leverages its cooperative structure to anchor procurement across this northern belt.
Schleswig-Holstein
Single-source vulnerability for fluid milk contracts intensifies when weather events hit the Elbe-Weser triangle. Feed input volatility from Black Sea supply disruptions compresses farm margins and triggers volume hedging at procurement desks. Cooperative dominance here creates concentration risk for national fluid milk contracts.
Berlin-Brandenburg
Conventional farms transition acreage to meet Bio-Siegel national organic regulation standards, unlocking price premiums in urban retail channels. Foodservice buyers compress supplier rosters while demanding carbon-disclosure documentation. This concentration displaces regional wholesalers lacking ESG reporting infrastructure.
Hamburg
Prepared-meal manufacturers and bakeries source butter and cream outside wholesale markets, shortening payment cycles through direct procurement. KBA emissions rules for refrigerated transport fleets add compliance costs that favor larger distributors with scale to retrofit logistics networks. Urban density drives refrigerated last-mile delivery requirements.
Germany Dairy Market Competitive Landscape
Global majors compete with regional champions across procurement scale and cooperative structure. The vendor base organizes around three tiers: multinational dairy conglomerates with cross-border sourcing networks, German cooperative processors with captive farm supply, and specialized organic operators serving premium retail channels. Competitive moves center on backward integration into farm supply and portfolio diversification into functional fermented products.
Within the cooperative processor tier, DMK Deutsches Milchkontor GmbH and Molkerei Ammerland exemplify structures that anchor procurement across northern grassland belts. Among cross-border operators, Arla Foods amba occupies a position linking Danish member farms to German manufacturing plants. These three represent distinct archetypes: pure cooperative, hybrid cooperative-corporate, and transnational cooperative federation.
| Leading Market Players |
|---|
| DMK Deutsches Milchkontor GmbH |
| Müller Group |
| Arla Foods amba |
| Groupe Lactalis |
| Danone SA |
| Molkerei Ammerland |
| FrieslandCampina Germany |
| Nordmilch |
| Hochwald Foods |
| Others |
Pricing and Supply Chain Analysis
Cooperative-owned processors anchor supply discipline across northern Germany, translating captive farm membership into stable farmgate pricing that resists spot-market volatility. Their collective bargaining power compresses margin leakage while Bio-Siegel certification premiums reward organic conversion with 20-30% price uplifts in Berlin retail channels.
Pricing Analysis
Service bundling separates fluid milk contracts from cheese aging agreements, with processors offering cold-chain warranty extensions to secure multi-year offtake commitments. Three-tier pricing structure across premium, standard, and economy levels tracks fat content, organic certification, and traceability depth. Cost compression in commodity fluid tiers is intensifying because Black Sea feed input volatility squeezes farm margins. Industrial buyers exhibit highest price sensitivity, while foodservice operators in Munich absorb premiums for farm-level traceability documentation.
Supply Chain Analysis
Returnable bottle logistics create reverse-flow complexity, with glass container pooling requiring dedicated collection infrastructure that favors scale operators running 50-plus vehicle fleets. Raw milk supply concentrates in Bavaria's Alpine zones and northern grassland belts across Lower Saxony and Schleswig-Holstein. Feed inputs draw from Black Sea soy and rapeseed meal corridors. Single-source vulnerability intensifies when weather events disrupt the Elbe-Weser triangle. Distribution runs through cooperative-processor networks into REWE and Edeka retail systems, with direct-to-foodservice channels expanding for butter and cream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as processors pursue captive control over organic milk supply to secure Bio-Siegel premiums and deflect feed cost volatility.
For Market Incumbents: Cement procurement dominance by locking multi-year farmgate contracts tied to methane-reduction compliance under EU Green Deal carbon accounting. Expand ceramic microfiltration capacity across Bavarian facilities to enable 48-hour product line switching between fluid milk and whey powder. Precision fermentation entrants threaten whey protein margins; backward integration into organic feed production hedges input cost swings. For New Entrants and Emerging Players: Foodservice procurement officers at Munich bakery chains represent an underserved buyer archetype seeking consolidated invoicing and carbon-disclosure documentation outside incumbent cooperative networks. Target direct-to-manufacturer butter and cream supply relationships with prepared-meal producers in Hamburg. Penetrate through ESG reporting infrastructure that displaces regional wholesalers lacking farm-level traceability systems. For Investors and Strategic Acquirers: KBA fleet retrofit compliance cliffs in 2027 are the leading indicator that refrigerated transport consolidation will accelerate toward scale operators with captive logistics capital. Five-to-ten year viability favors processors controlling organic supply basins and membrane filtration flexibility. Monitor F-Gas Regulation natural refrigerant conversion timelines as equipment replacement cycle triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Alpine Supply Basin Consolidation | Bavarian cooperatives reduce collection emissions while capturing Bio-Siegel organic premiums near Allgäu milk zones. |
| Natural Refrigerant Retrofit | F-Gas Regulation phase-down forces cold-chain operators to adopt ammonia and CO2 systems ahead of quota restrictions. |
| Precision Fermentation Partnership | Biomass-derived dairy proteins nearing cost parity enable hybrid lactose-free product line expansion. |
| Foodservice Channel Direct Access | Bakeries and prepared-meal manufacturers in Munich and Hamburg shorten payment cycles outside wholesale markets. |
| Membrane Filtration Flexibility Investment | Ceramic microfiltration systems unify protein standardization across fluid milk, yogurt base, and whey powder production. |
Research Methodology
Document review covered EU regulatory filings, KBA transport emissions databases, and cooperative procurement records, complemented by interviews with dairy processing executives, farm cooperative managers, cold-chain logistics operators, and foodservice procurement directors. Secondary validation drew from EMA food safety protocols, Bio-Siegel certification registries, and F-Gas Regulation implementation trackers. Bottom-up farmgate volume estimates triangulated against top-down retail channel audits.
Output modeling produced segment-level volume and value trajectories across the projection horizon by calibrating protein standardization technology adoption, organic conversion rates, and refrigerated fleet compliance costs against historical procurement pattern shifts. CAGRs emerged from curve-fitting across membrane filtration deployment phases and functional yogurt shelf-space expansion. Feed input volatility indices and carbon accounting premium structures served as industry-specific forecast modifiers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal methane-reduction mandate enforcement and precision fermentation cost crossover timing. Practitioners should monitor Black Sea grain corridor stability and natural refrigerant technician certification rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Dairy Spreads Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Kefir Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
India Dairy Market
Dairy Products
Milk Protein Crisps Market
Dairy Products
GCC Casein Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Dairy Blends Market
Dairy Products
Global Milk Protein Market
Dairy Products
Indonesia Whey Protein Market
Dairy Products
North America Milk Powder Market
Dairy Products
Spoonable Yogurt Market