
 Lactose Monohydrate Market | 2026-2036
Lactose Monohydrate Market Size, Share, and Industry Trends Forecast 2026-2036
Lactose Monohydrate Market Foresight
USP-NF and Ph.Eur. certification cycles for lactose excipients is rotating supplier eligibility every three to five years, favoring manufacturers with dedicated pharmaceutical-grade streams. Arla Foods amba leverages its Scandinavian dairy network to sustain consistent raw whey supply for high-purity extraction. Hilmar Cheese Company anchors North American pharmaceutical demand through integrated whey processing in California. Meggle GmbH dominates European compendial-grade production with specialized milling and crystallization capabilities.
Lactose monohydrate is a crystalline disaccharide derived from whey, typically containing up to 5% water of crystallization, manufactured through controlled crystallization, refining, and spray-drying to achieve specified particle size distributions for direct compression tableting. It functions primarily as a diluent, binder, and flow aid in oral solid dosage forms, with secondary use as a nutritional carbohydrate in infant formulas and sports nutrition. Pharmaceutical Grade commands the deepest margin pool due to compendial compliance burdens and customer qualification requirements, while Food Grade sustains volume throughput through dairy and confectionery applications. Nutritional Supplements represents the fastest-growing application segment as protein fortification and clinical nutrition products expand formulation complexity.
FDA enforces ICH Q3D elemental impurity limits and USP <232> compliance for lactose excipients, while EMA through Ph.Eur. monographs 0187 and 1060 mandates microbial and endotoxin thresholds that determine market access for European pharmaceutical supply. India's CDSCO aligns with IP standards and requires import registration for excipient sourcing, shaping local procurement patterns for domestic generic manufacturers. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF, Ph.Eur., and JP standards, as divergence in particle size and moisture specifications will determine which suppliers retain multi-regional qualification status.
Market Dynamics
Pharmaceutical-grade certification cycles are compressing supplier eligibility windows, forcing capital-intensive purification upgrades that favor integrated whey processors over commodity traders. This structural filter is redrawing competitive boundaries across compendial supply chains.
Growth Catalysts
- Tablet formulation expansion:Oral solid dosage manufacturing in India and Southeast Asia is absorbing compendial-grade volumes as domestic generic production scales. CDSCO import registration requirements are locking in qualified supplier relationships.
- ICH Q3D compliance:FDA enforcement of elemental impurity limits is disqualifying legacy suppliers, creating qualification vacancies for processors with dedicated pharmaceutical streams and in-house testing capabilities.
- Spray-drying automation:Continuous crystallization and particle engineering systems are reducing batch-to-batch variability, enabling direct compression tableting without secondary granulation steps.
Market Restraints
- Whey supply concentration:Scandinavian and North American dairy cooperatives control raw material access, exposing processors to seasonal milk production swings and protein extraction competition.
- Ph.Eur. 1060 endotoxin thresholds:EMA microbial limits require dedicated cleanroom infrastructure that blocks food-grade manufacturers from pharmaceutical crossover without full facility reconstruction.
- Mannitol substitution:Excipient formulators in moisture-sensitive applications are pivoting to sugar alcohol diluents with superior stability profiles and lower hygroscopicity.
Strategic Opportunities
- Clinical nutrition fortification:Protein-sparing carbohydrate formulations in enteral feeding are creating specification demand for low-protein residual lactose grades in hospital and homecare channels.
- JP harmonization alignment:Convergence between USP-NF, Ph.Eur., and Japanese Pharmacopoeia particle size specifications would unlock multi-regional qualification for suppliers investing in unified testing protocols.
- Sports nutrition microencapsulation:Time-release carbohydrate systems in endurance products are opening formulation partnerships between excipient engineers and functional food developers.
Industry Challenges
- Analytical chemistry talent scarcity:ICP-MS and endotoxin testing expertise is concentrated among contract laboratories, extending qualification timelines for new manufacturing sites.
- Three-to-five-year certification cycles:USP-NF and Ph.Eur. requalification windows demand sustained documentation investment that strains mid-scale processors without dedicated regulatory affairs functions.
- Legacy spray-dryer retrofit costs:Pharmaceutical-grade containment and CIP/SIP integration require capital outlays that compress returns on decades-old production assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactose Monohydrate Market |
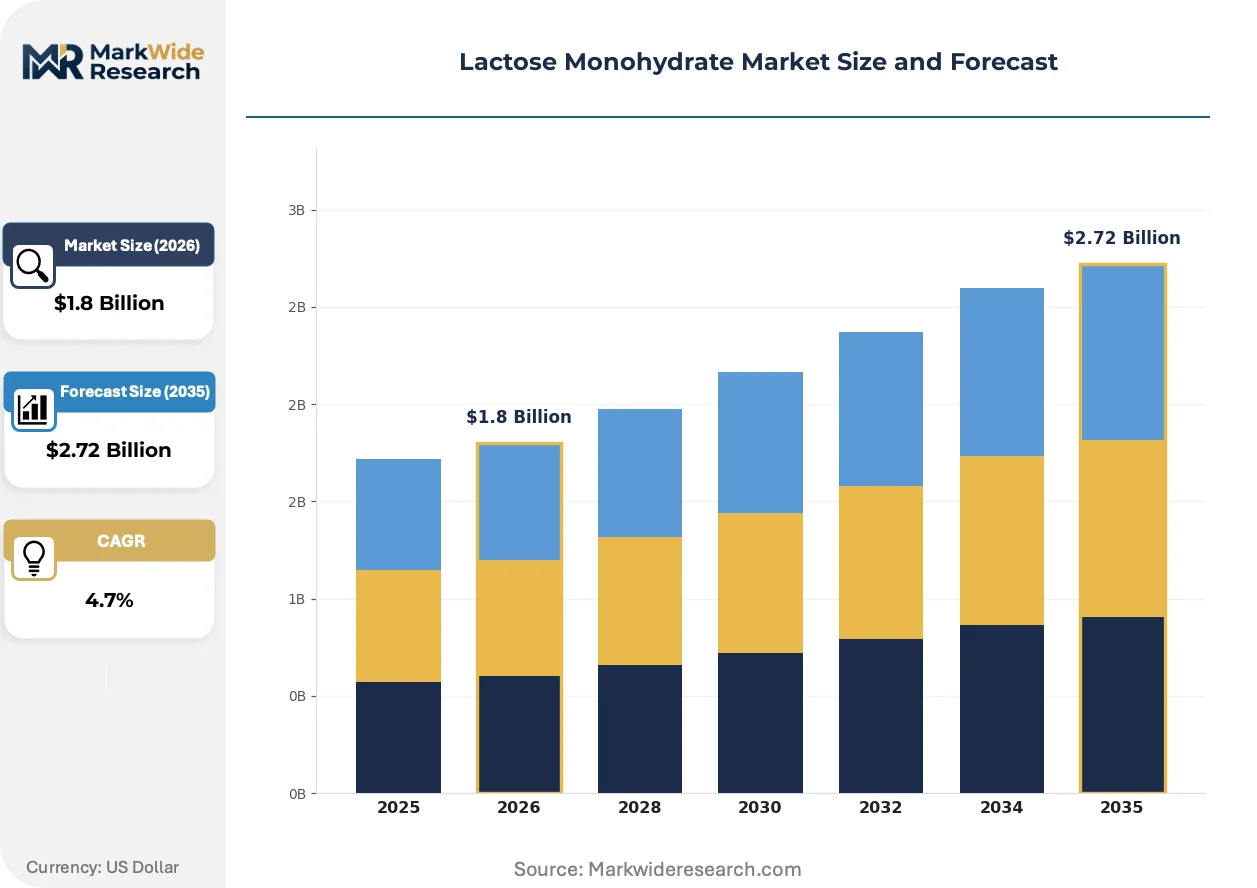
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Feed Grade, Industrial Grade Application: Dairy Products, Nutritional Supplements, Pharmaceuticals, Confectionery End User: Food Manufacturers, Pharmaceutical Companies, Animal Feed Producers, Research Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Arla Foods amba, Hilmar Cheese Company, LLC, Fonterra Co-operative Group Limited, Kerry Group, Meggle GmbH, DMK Deutsches Milchkontor GmbH, Glanbia plc, DFE Pharma, Koninklijke FrieslandCampina N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactose Monohydrate Market Shifts & Advancements
Continuous processing technologies and real-time release testing are displacing batch-oriented manufacturing, while pharmacopeial harmonization efforts are compressing regional specification divergence. These forces are converging to reward capital-heavy, quality-integrated supply structures.
Agitated thin-film evaporation with inline particle sizing is decomposing traditional batch crystallization sequences. Pharmaceutical contract manufacturers in India and Germany are adopting these systems to eliminate intermediate drying steps and reduce residence time variability. This technology is decomposing the historical advantage of large-scale batch processors by enabling right-sized, modular production with faster qualification cycles.
EMA's revised Ph.Eur. monograph 0187 tightening moisture and microbial specifications is forcing facility segregation investments. European compendial suppliers are constructing dedicated pharmaceutical streams with HVAC isolation from food-grade operations. The Nutritional Supplements segment faces the steepest compliance burden, as many historical suppliers lack infrastructure to meet endotoxin thresholds without complete facility redesign.
Direct material qualification by finished dosage manufacturers is replacing distributor-mediated procurement. Large Indian generic houses now audit lactose processors at whey intake through spray-dryer discharge, bypassing traditional trading intermediaries. This pattern is most visible in Mumbai and Hyderabad pharmaceutical clusters, where vertically integrated formulators are consolidating excipient supply bases to reduce batch variability liability.
Lactose Monohydrate Market Segmentation
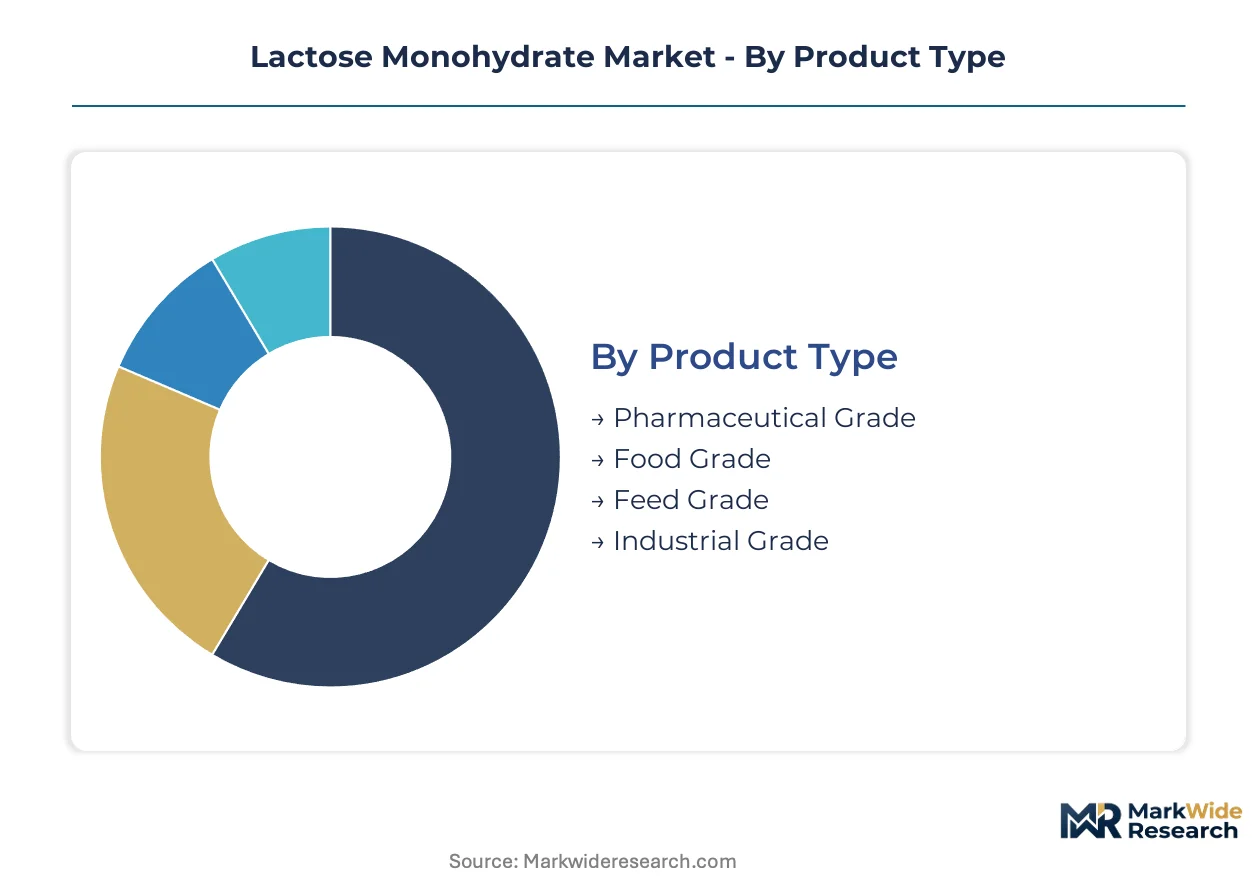
Segmentation in lactose monohydrate markets reveals how compendial compliance burdens and whey supply geography partition value capture. Pharmaceutical-grade streams command qualification premiums while food-grade volumes absorb commodity dairy economics.
Product Type:
Pharmaceutical Grade concentrates in European and North American export markets where FDA and EMA certification cycles filter supplier eligibility. Food Grade and Feed Grade serve domestic dairy processors with shorter supply chains and lower documentation thresholds.
- Pharmaceutical Grade:Crystalline disaccharide meeting USP-NF and Ph.Eur. monographs with controlled particle size distributions for direct compression tableting. Demand clusters in Mumbai and Hyderabad pharmaceutical clusters as CDSCO import registration locks in qualified supplier relationships. FDA enforcement of ICH Q3D elemental impurity limits is disqualifying legacy processors without dedicated pharmaceutical streams.
- Food Grade:Standard lactose monohydrate for dairy, confectionery, and bakery applications with less stringent microbial specifications. Domestic procurement dominates as regional dairy cooperatives supply local food manufacturers without cross-border documentation. Scandinavian and North American whey concentration shapes raw material access economics.
- Feed Grade:Lower-purity lactose for animal nutrition and calf milk replacers. Volume flows through agricultural supply cooperatives with minimal regulatory oversight.
- Industrial Grade:Technical lactose for fermentation substrates and chemical synthesis. Captive consumption by biotechnology processors limits merchant market development.
Pharmaceutical Grade commands the established base. The steepest expansion runs through Food Grade as protein fortification and sports nutrition formulations absorb compendial-surplus volumes.
Application:
Application segmentation tracks how formulation complexity and regulatory intensity allocate margin pools across end-use sectors. Direct material qualification by finished dosage manufacturers is replacing distributor-mediated procurement in high-specification segments.
- Pharmaceuticals:Oral solid dosage forms utilizing lactose as diluent, binder, and flow aid in tablets and capsules. EMA Ph.Eur. 1060 endotoxin thresholds require dedicated cleanroom infrastructure that blocks food-grade crossover. Spray-drying automation investments in India and Germany are reducing batch-to-batch variability for direct compression.
- Nutritional Supplements:Protein-sparing carbohydrate formulations in enteral feeding and clinical nutrition products. Hospital and homecare channels in India drive specification demand for low-protein residual grades. This segment faces the steepest compliance burden as historical suppliers lack infrastructure to meet microbial thresholds.
- Dairy Products:Standardized milk powders and infant formula carbohydrate fortification. Domestic dairy processors in India and Europe source through backward-integrated whey operations.
- Confectionery:Crystalline lactose for texture modification and sweetness control in chocolate and candy production. Regional dairy cooperatives supply local confectioners with minimal documentation.
Pharmaceuticals anchors revenue concentration. Nutritional Supplements is climbing the fastest as protein fortification and clinical nutrition products expand formulation complexity.
End User:
End user structure reflects procurement centralization patterns and qualification burden distribution. Large generic houses now audit processors at whey intake through spray-dryer discharge, bypassing traditional intermediaries.
- Pharmaceutical Companies:Finished dosage manufacturers with direct material qualification protocols and three-to-five-year supplier certification cycles. Mumbai and Hyderabad clusters consolidate excipient supply bases to reduce batch variability liability. ICP-MS and endotoxin testing expertise requirements extend qualification timelines.
- Food Manufacturers:Dairy, confectionery, and bakery processors sourcing through regional distributors. Shorter procurement cycles and lower documentation thresholds characterize this segment.
- Animal Feed Producers:Calf milk replacer and livestock nutrition formulators. Agricultural supply cooperatives dominate distribution with price-sensitive procurement.
- Research Institutions:Small-volume compendial-grade consumption for analytical standards and formulation development. Contract laboratory intermediaries manage sporadic procurement.
Pharmaceutical Companies concentrate value capture. Food Manufacturers provide volume throughput with compressed margins.
Distribution Channel:
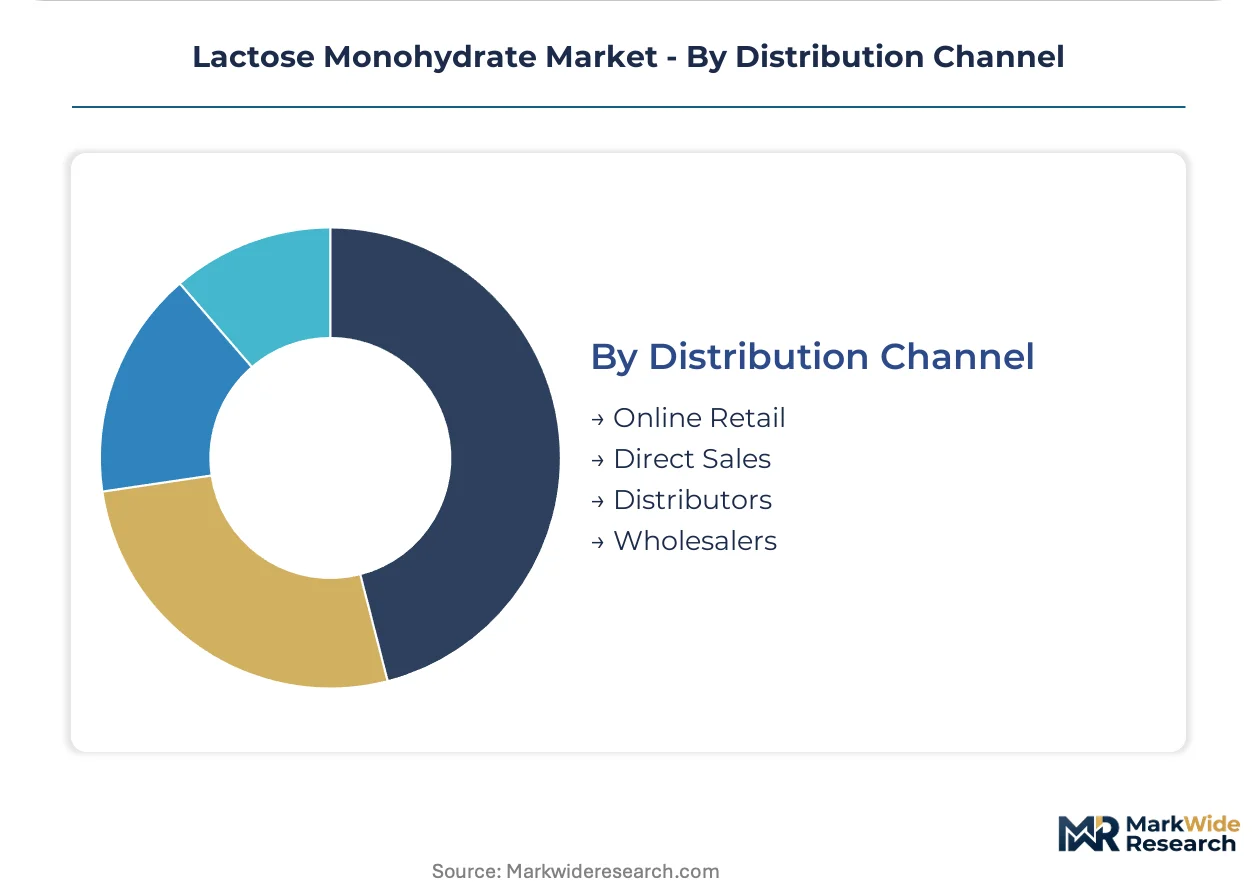
Channel structure is bifurcating as qualified pharmaceutical supply consolidates while food-grade distribution retains fragmentation. Direct qualification patterns reshape traditional trading economics.
- Direct Sales:Long-term supply agreements between lactose processors and finished dosage manufacturers. Large Indian generic houses audit facilities from whey intake through spray-dryer discharge. This channel absorbs the deepest margin pools through qualification-locked relationships.
- Distributors:Regional intermediaries serving food-grade and feed-grade segments with shorter sales cycles. Inventory pooling reduces working capital burdens for mid-scale processors.
- Wholesalers:Agricultural supply and commodity dairy traders handling bulk feed-grade volumes. Price transparency limits value-add capture.
- Online Retail:Small-package compendial-grade sales for research institutions and specialty food formulators. Limited penetration due to qualification documentation requirements.
Direct Sales commands the established base. Distributors retain the steepest expansion trajectory in food-grade segments as regional dairy processing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacopeial harmonization initiatives and domestic pharmaceutical manufacturing incentives are redrawing procurement geography across compendial-grade lactose supply chains. FDA, EMA, and CDSCO regulatory convergence pressures favor processors with multi-jurisdictional qualification infrastructure.
United States
Domestic generic tablet production and contract manufacturing expansion drive pharmaceutical-grade absorption. FDA enforcement of ICH Q3D elemental impurity limits through USP <232> compliance is disqualifying legacy suppliers without dedicated analytical capabilities. California's Central Valley dairy processors anchor North American whey supply chains for high-purity extraction.
Germany
EMA Ph.Eur. monograph revisions and endotoxin threshold tightening under monograph 1060 force facility segregation investments. Bavarian and North Rhine-Westphalia pharmaceutical clusters demand compendial-grade streams with HVAC-isolated production lines. Specialized milling and crystallization capabilities concentrate in southern industrial zones serving European export markets.
India
CDSCO import registration requirements and domestic pharmaceutical output scaling lock in qualified supplier relationships for Mumbai and Hyderabad generic houses. The country's national pharmaceutical regulator aligns excipient standards with IP pharmacopeia, shaping local procurement patterns. Maharashtra and Telangana manufacturing clusters now audit processors from whey intake through spray-dryer discharge.
China
NMPA excipient registration pathways and domestic infant formula carbohydrate fortification sustain food-grade volume throughput. Yangtze River Delta dairy processors supply regional nutritional supplement manufacturers with shorter documentation cycles. The country's national food and drug administration is gradually tightening microbial specifications for pharmaceutical crossover applications.
Denmark
Scandinavian dairy cooperative networks sustain consistent raw whey supply for high-purity pharmaceutical extraction. EU Green Deal sustainability reporting requirements and REACH chemical safety obligations shape processor investment priorities. Integrated whey processing operations in Jutland serve as compendial-grade supply anchors for northern European pharmaceutical markets.
Lactose Monohydrate Market Competitive Landscape
Player mix skews toward integrated dairy cooperatives with captive whey streams and specialized pharmaceutical-grade processors with dedicated compendial facilities. Market structure concentrates around processors controlling raw material access and qualification-locked customer relationships. Strategic archetypes include Scandinavian dairy-backed suppliers, North American integrated cheese-lactose processors, and European specialized excipient engineers. Dominant competitive moves encompass backward integration into whey supply and pharmacopeial certification cycle positioning.
Among Scandinavian dairy-backed suppliers, Arla Foods amba and Fonterra Co-operative Group Limited occupy positions anchored by cooperative milk supply networks. Hilmar Cheese Company, LLC represents the North American integrated processor archetype with California-based whey operations. Meggle GmbH exemplifies the European specialized excipient engineer model with dedicated pharmaceutical-grade milling and crystallization capabilities. These three company types illustrate how geographic whey concentration and compendial infrastructure investment partition competitive positioning across regional supply chains.
| Leading Market Players |
|---|
| Arla Foods amba |
| Hilmar Cheese Company, LLC |
| Fonterra Co-operative Group Limited |
| Kerry Group |
| Meggle GmbH |
| DMK Deutsches Milchkontor GmbH |
| Glanbia plc |
| DFE Pharma |
| Koninklijke FrieslandCampina N.V. |
| Others |
Supply & Pricing Matrix
Ninety-to-one-hundred-day inventory cycles for pharmaceutical-grade lactose concentrate margin capture with processors maintaining dedicated cleanroom streams, while food-grade spot markets compress working capital returns through seasonal whey availability swings. This lead-time divergence stratifies pricing power across compendial certification tiers and raw material access economics.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade premiums and commodity food-grade baselines. Three-tier pricing structure across compendial, food-grade, and feed-grade levels reflects USP-NF and Ph.Eur. compliance burdens alongside particle engineering investments. Cost compression in food-grade tiers is intensifying because Scandinavian and North American dairy cooperatives face protein extraction competition from whey protein concentrate manufacturers. Large Indian generic houses exhibit lowest price sensitivity due to qualification-locked supplier relationships, while regional confectioners drive spot-market volatility.
Supply Chain Analysis
Ninety-day pharmaceutical-grade inventory cycles rest on dedicated cleanroom segregation from food-grade operations, forcing HVAC-isolated production lines that extend lead times. Supply concentrates in Denmark, Germany, and the United States where integrated whey processors control raw material access. Scandinavian dairy cooperatives, North American cheese manufacturers, and German excipient engineers anchor upstream concentration. Single-source vulnerability runs through seasonal milk production swings and protein extraction competition. Distribution runs through direct sales agreements for pharmaceutical-grade and regional distributors for food-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large Indian generic houses and European contract manufacturers, fragmenting traditional distributor intermediaries and forcing processors into direct qualification relationships with extended audit protocols.
For Market Incumbents: Fortify qualification-locked relationships with Mumbai and Hyderabad pharmaceutical clusters through dedicated pharmaceutical streams and in-house ICP-MS testing capabilities. Invest in continuous crystallization systems to reduce batch-to-batch variability liability. Mannitol substitution in moisture-sensitive applications and Ph.Eur. 1060 endotoxin threshold tightening represent dual threats requiring cleanroom infrastructure expansion. For New Entrants and Emerging Players: Anchor in clinical nutrition fortification segments where low-protein residual lactose grades face specification demand from hospital and homecare channels in India. Target sports nutrition microencapsulation partnerships with functional food developers seeking time-release carbohydrate systems. Pursue direct material qualification protocols with mid-scale generic houses bypassing established trading intermediaries. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because pharmacopeial certification cycles and three-to-five-year requalification windows create durable moats for processors with dedicated analytical capabilities. Acquisition candidates include European specialized excipient engineers with milling and crystallization expertise and North American integrated cheese-lactose processors with captive whey supply. Monitor JP harmonization alignment between USP-NF, Ph.Eur., and Japanese Pharmacopoeia as inflection signal for multi-regional qualification expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Whey Supply | Arla Foods amba leverages Scandinavian dairy networks to secure consistent raw material access for high-purity extraction. |
| Pharmaceutical-Grade Facility Segregation | EMA Ph.Eur. 1060 revisions force HVAC-isolated production lines that block food-grade crossover without reconstruction. |
| Continuous Crystallization Technology | Agitated thin-film evaporation with inline particle sizing eliminates intermediate drying steps for Indian contract manufacturers. |
| Direct Material Qualification Protocols | Large Indian generic houses now audit processors from whey intake through spray-dryer discharge, bypassing distributors. |
| Multi-Regional Pharmacopeial Certification | Convergence between USP-NF, Ph.Eur., and JP standards unlocks qualification for suppliers investing in unified testing protocols. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical formulation scientists, excipient procurement managers at Indian generic houses, dairy cooperative supply planners, and regulatory affairs specialists at EMA-notified bodies. Secondary validation drew from FDA warning letters, Ph.Eur. monograph revision notices, CDSCO import registration databases, and SEC filings of publicly traded dairy processors. Bottom-up volume modeling triangulated against top-down value estimates from trade flow analysis.
Across the analysis window, forecasts integrated product type segmentation by grade tier, application segmentation by regulatory intensity, and end-user segmentation by procurement centralization patterns. CAGRs were derived from regression analysis of historical whey supply elasticity and pharmaceutical output scaling in India and Germany. Forecast inputs included spray-drying automation adoption curves and pharmacopeial harmonization progress indicators.
Decision-makers should treat outputs as directional under assumptions of sustained FDA ICH Q3D enforcement and stable Scandinavian dairy cooperative output; material deviation in regulatory stringency or whey protein concentrate demand would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South America Food Acidulants Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
Bakery Enzymes Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Mexico Food Preservatives Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Carob Bean Gum Market