
 Skim Milk Powder Market | 2026-2036
Skim Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Skim Milk Powder Market Analysis
EU Green Deal carbon-border adjustments are pivoting the cost-of-entry calculus for non-European skim milk powder exporters. Fonterra leverages its captive New Zealand milk supply to sustain cost advantages across Asian nutrition channels. Lactalis anchors European volume through backward integration into cooperative milk collection in France and Poland. Arla Foods differentiates via specialized instant powder formulations for industrial bakery clients.
Skim milk powder is the dehydrated form of milk with fat content reduced below 1.5%, produced through spray-drying or roller-drying of separated skim milk to yield a shelf-stable, protein-rich solid for reconstitution or ingredient use. Spray-dried powder dominates industrial procurement due to superior solubility and lower thermal damage to whey proteins. Instant powder commands premium positioning in nutrition end-use, while roller-dried material occupies cost-sensitive confectionery applications where slight browning is acceptable. Dairy processors represent the most consolidated buyer segment, with direct sales channels capturing the largest margin pools.
FDA standards for dairy identity and labeling shape US import requirements, while EFSA nutritional claims regulation governs European nutrition marketing. India's FSSAI enforces progressively stricter microbiological limits on imported dairy powders. Stakeholders must monitor how carbon-border mechanisms and shifting infant-formula fortification standards redirect procurement geography and product specification demands.
Market Dynamics
The EU F-Gas Regulation is forcing dairy processors to reengineer spray-drying refrigeration systems, compressing operating margins for European operators while advantaging suppliers in jurisdictions with lighter environmental compliance burdens.
Growth Catalysts
- Infant Formula Fortification Mandates:Southeast Asian nutrition regulators are tightening protein-content specifications for imported dairy ingredients, pulling instant-grade powder into regional manufacturing supply chains.
- EU Green Deal Carbon-Border Adjustments:The CBAM mechanism is redirecting procurement toward low-carbon-intensity production clusters, rewarding New Zealand's geothermal-powered Canterbury dairy processing infrastructure.
- Spray-Drying Automation:Advanced process control systems are reducing thermal damage to whey proteins, expanding powder suitability for high-value nutritional applications.
Market Restraints
- Input Cost Volatility:Natural gas and electricity price swings directly compress spray-drying economics, particularly for European operators dependent on spot energy markets.
- Supply Concentration Risk:Fonterra's captive control over New Zealand's Canterbury milk pool creates bottleneck vulnerability for Asian infant formula manufacturers.
- Regulatory Friction:India's FSSAI microbiological limits on imported dairy powders impose testing delays and rejection risk at port of entry.
Strategic Opportunities
- Underpenetrated Nutrition Channels:West African consumer markets remain underserved by instant powder distribution, with informal dairy consumption creating white space for packaged reconstitution products.
- Regulatory Tailwind:China's dual carbon goals are accelerating import preference for low-emission production sources, advantaging geothermal-powered New Zealand supply.
- Technology Convergence:Membrane filtration pre-concentration combined with energy recovery drying is opening retrofit pathways for legacy European processing assets.
Industry Challenges
- Refrigeration Engineer Scarcity:EU F-Gas compliance timelines are outpacing available technician training capacity for ammonia and CO2 system conversions.
- Capex Intensity:Spray-dryer energy recovery retrofits require substantial upfront investment with payback periods sensitive to electricity price trajectories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skim Milk Powder Market |
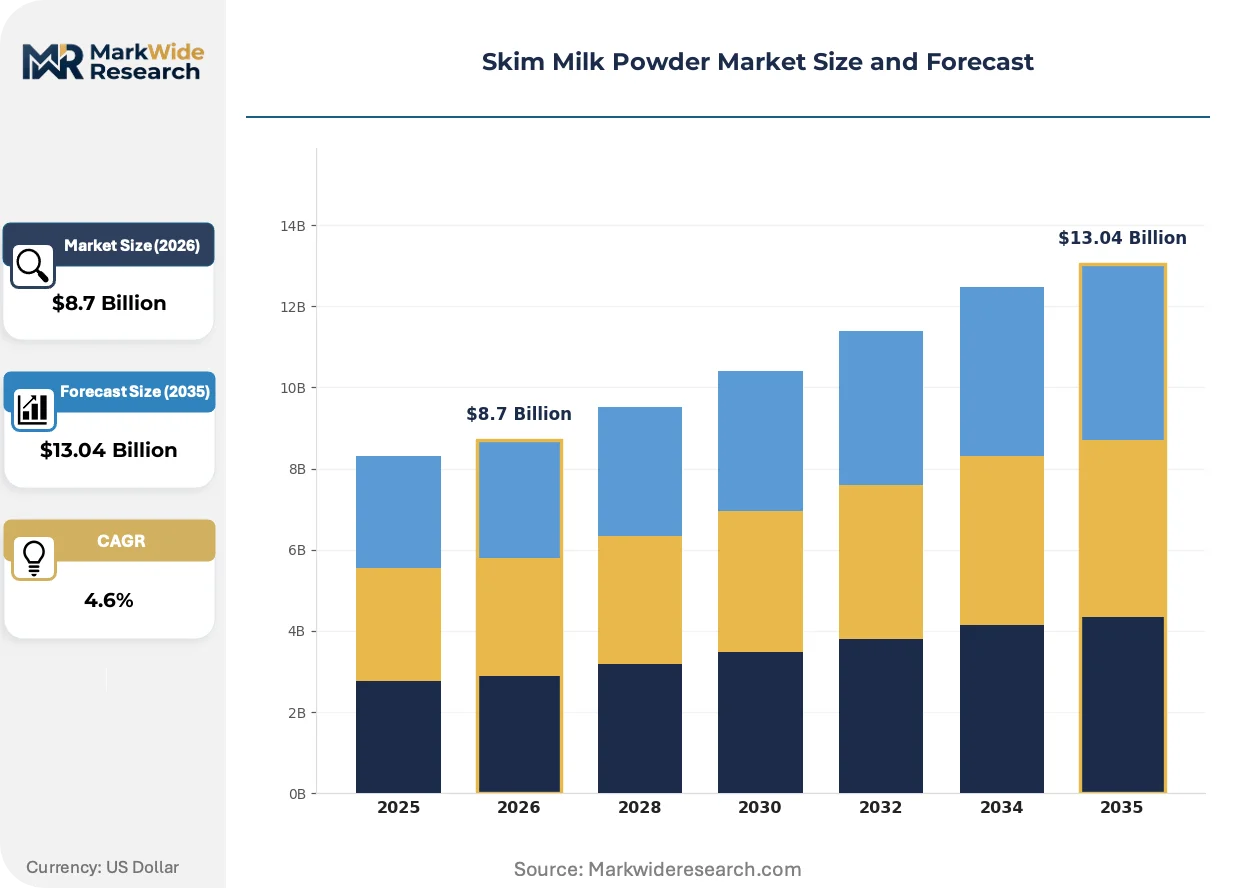
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant, Non-Instant, Spray-Dried, Roller-Dried End User: Dairy Processors, Bakery, Confectionery, Nutrition Packaging Type: Bags, Boxes, Drums, Pouches Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Nestle, Lactalis, FrieslandCampina, Alpen Dairies, DairyAmerica, Arla Foods, Dairy Farmers of America, Amul, Fonterra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skim Milk Powder Market Emerging Trajectories
Processing technology and procurement geography are undergoing simultaneous recalibration, with regulatory pressure on energy systems intersecting with shifting buyer concentration in nutrition end-uses.
Membrane filtration pre-concentration is overtaking traditional evaporative concentration as the standard upstream step before spray-drying. Infant formula manufacturers in Southeast Asia are specifying membrane-processed feedstock to preserve native whey protein structure. This shift is compressing the cost advantage of roller-dried powder in all but the most price-sensitive confectionery applications.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in industrial cooling systems. Dairy processors face retrofit deadlines for spray-dryer heat pumps and condensing equipment. European operators are responding by accelerating ammonia and transcritical CO2 system adoption, while some volume migrates to suppliers in jurisdictions with lighter refrigeration compliance timelines.
Direct procurement relationships between infant formula manufacturers and dairy processors are displacing traditional trading house intermediaries. Large nutrition brands in Southeast Asia are establishing supply agreements with named production clusters. This pattern is most visible in Vietnam and Indonesia, where regulatory traceability requirements favor documented chain-of-custody over spot market purchasing.
Skim Milk Powder Market Segmentation
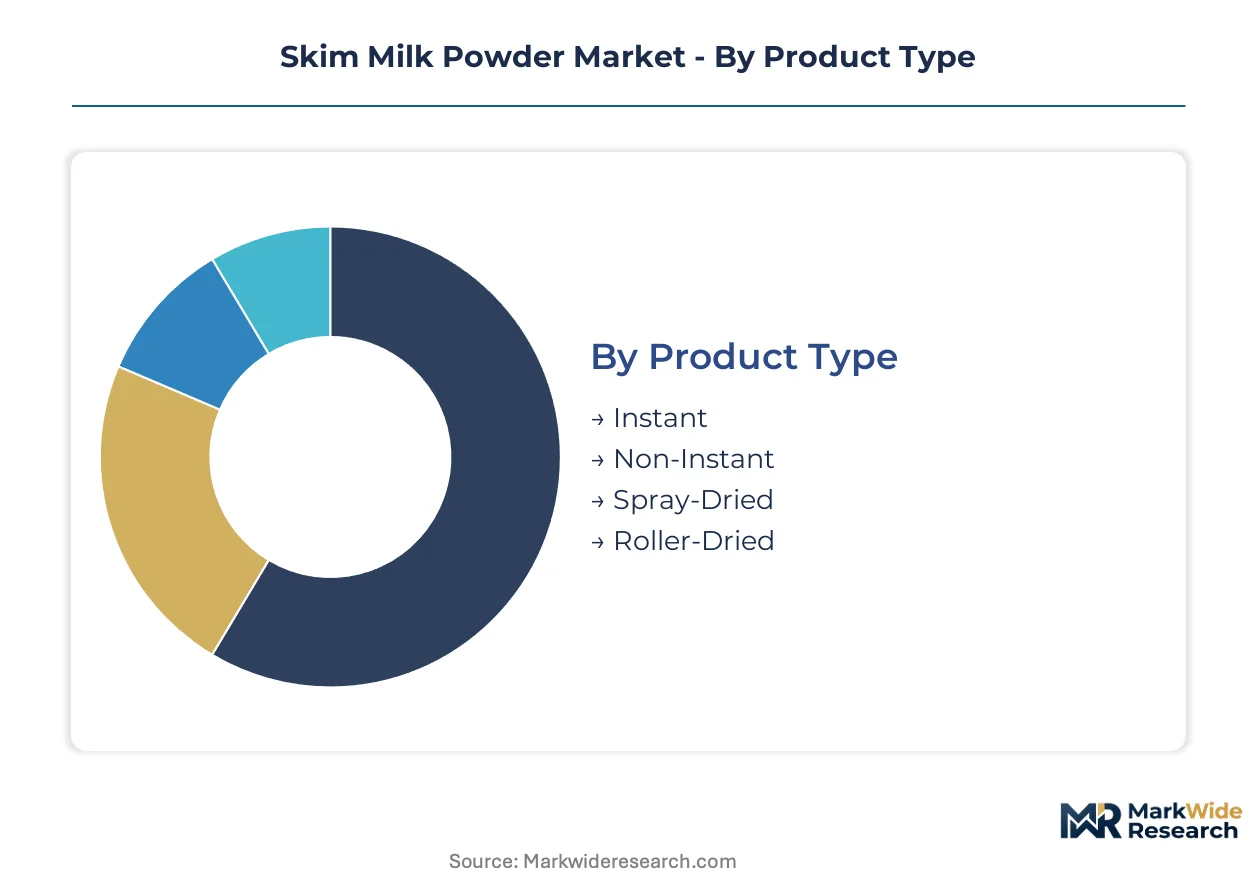
Skim milk powder procurement patterns diverge sharply across product specifications, with instant-grade material commanding premium positioning in infant formula while roller-dried variants serve cost-sensitive industrial applications. Understanding these segment boundaries illuminates where margin pools concentrate and which technical specifications drive purchasing decisions.
Product Type:
Spray-drying and roller-drying technologies create fundamentally different protein structures, solubility profiles, and thermal damage signatures that dictate end-use suitability.
- Instant:Agglomerated particles with enhanced wettability and dispersibility, manufactured through secondary steam-leaching of spray-dried base powder. Demand concentrates in Southeast Asian infant formula manufacturing, where Vietnamese and Indonesian regulators enforce rapid-reconstitution standards for clinical nutrition products.
- Non-Instant:Standard spray-dried powder requiring mechanical agitation for complete dissolution. Cost-sensitive bakery and confectionery operations in India specify this grade where dissolution time is not critical to process economics.
- Spray-Dried:Atomized milk concentrate flash-dried in hot air streams, preserving native whey protein structure. Industrial procurement from New Zealand's Canterbury cluster dominates high-value nutrition channels.
- Roller-Dried:Milk film dried on heated rotating drums, producing dense flakes with slight Maillard browning. European confectionery manufacturers in Poland leverage this grade for caramel and chocolate applications where color development is desirable.
Mature deployment sits with Spray-Dried powder. Newer deployment is concentrated in Instant formulations.
End User:
Customer sophistication and specification stringency vary dramatically across downstream industries, creating tiered pricing power and contract structures.
- Nutrition:Infant formula and clinical nutrition manufacturers impose the most demanding microbiological and protein-specification requirements. Direct procurement agreements with named production clusters in New Zealand are displacing traditional trading house intermediaries.
- Dairy Processors:Recombination operations for fluid milk and yogurt production represent the highest volume offtake. These buyers prioritize cost stability and supply security over premium functional attributes.
- Bakery:Industrial bread and pastry manufacturers utilize skim milk powder for crust color, flavor, and protein enrichment. Arla Foods has developed specialized instant formulations targeting this segment's hydration requirements.
- Confectionery:Chocolate and caramel producers accept roller-dried material with slight thermal degradation. This segment exhibits the highest price elasticity and spot-market purchasing behavior.
Volume leadership belongs to Dairy Processors. Margin expansion is concentrated in Nutrition.
Packaging Type:
Packaging selection reflects supply chain distance, humidity exposure risk, and customer handling infrastructure.
- Bags:Multi-wall paper or woven polypropylene sacks for domestic distribution and short-haul export. This format dominates intra-European trade where transit times minimize moisture absorption risk.
- Drums:Steel or fiber drums with sealed liners for ocean freight and long-term storage. Asian infant formula manufacturers specify this packaging for trans-Pacific supply chains from New Zealand.
- Boxes:Corrugated containers with inner liners for retail and foodservice distribution. Limited to markets with developed cold-chain alternatives and rapid inventory turnover.
- Pouches:Flexible laminated films for consumer reconstitution products. West African consumer markets show emerging adoption for household-sized portions in urban centers.
Industrial procurement favors Drums. Consumer-facing deployment is expanding in Pouches.
Distribution Channel:
Channel selection determines margin capture, traceability documentation, and relationship intensity between processors and end-users.
- Direct Sales:Long-term supply agreements between dairy processors and large nutrition or dairy manufacturing customers. This channel captures the largest margin pools and enables chain-of-custody documentation for regulatory traceability.
- Wholesale:Trading houses and distributors aggregating spot and contract volumes for smaller industrial buyers. Price discovery and liquidity concentrate here, particularly for non-instant and roller-dried grades.
- Retail:Branded consumer packs through supermarkets and specialty food stores. Limited to reconstitution markets with established dairy consumption habits and purchasing power.
- Online:E-commerce platforms for specialty nutrition and foodservice procurement. Emerging channel with fragmented regulatory compliance across cross-border shipments.
Contracted volume concentrates in Direct Sales. Transactional flexibility is highest in Wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's Canterbury Special Economic Zone concentrates geothermal-powered dairy processing infrastructure that supplies Asian infant formula channels. EU F-Gas Regulation retrofit deadlines are compressing margins for European spray-drying operations.
New Zealand
Fonterra's captive control over Canterbury milk pools anchors instant-grade powder supply for Vietnamese and Indonesian nutrition manufacturers. The country's Emissions Trading Scheme rewards geothermal energy use in dairy processing. Christchurch-based spray-drying facilities are expanding membrane filtration capacity to meet Southeast Asian protein-specification demands.
Netherlands
FrieslandCampina's cooperative structure dominates European recombination dairy procurement for West African export. The EU Green Deal CBAM mechanism is redirecting low-carbon-intensity sourcing toward New Zealand suppliers. Wageningen dairy research clusters are piloting ammonia refrigeration retrofits for F-Gas compliance.
United States
Dairy Farmers of America and DairyAmerica coordinate milk powder output for Mexican recombination and Central American bakery supply. FDA dairy identity standards shape import documentation requirements for Asian trading partners. California Central Valley processors face electricity price volatility compressing spray-drying economics.
India
Amul's cooperative network supplies roller-dried powder for domestic confectionery and Middle East expatriate markets. FSSAI microbiological limits on imported dairy powders create testing bottlenecks at Mumbai and Chennai ports. Gujarat's Anand dairy cluster is expanding spray-dried capacity for regional nutrition applications.
France
Lactalis leverages backward integration into cooperative milk collection across Normandy and Brittany for European bakery and chocolate manufacturing. EFSA nutritional claims regulation governs protein-content marketing for export nutrition products. Laval dairy technology suppliers are engineering energy recovery systems for legacy spray-dryer retrofits.
Skim Milk Powder Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor base stratifies between captive milk-supply operators and independent processors dependent on spot milk markets. Three archetypes dominate: cooperative-backed dairy giants with upstream milk control, privately held processors with regional bakery specialization, and state-affiliated entities serving domestic food security mandates. Capacity expansion and direct procurement relationship-building represent the dominant competitive moves.
Within the cooperative-backed tier, Fonterra and FrieslandCampina exemplify structures combining captive milk supply with nutrition-channel vertical integration. Lactalis occupies a position bridging private ownership with cooperative sourcing networks across French and Polish milk sheds. Nestle represents diversified conglomerate positioning, leveraging beverage and nutrition portfolio breadth to secure powder offtake agreements.
| Leading Market Players |
|---|
| Nestle |
| Lactalis |
| FrieslandCampina |
| Alpen Dairies |
| DairyAmerica |
| Arla Foods |
| Dairy Farmers of America |
| Amul |
| Fonterra |
| Others |
Supply Flow & Price Mechanics
Southeast Asian infant formula manufacturers' tightening protein-content specifications are forcing supply chains toward membrane-processed instant-grade powder, compressing margins on standard spray-dried material and widening spreads between functional grades.
Pricing Analysis
Short lead-time premiums now dominate contract negotiations, with Vietnamese and Indonesian nutrition manufacturers paying substantial markups for documented chain-of-custody supply against spot-market roller-dried alternatives. Three-tier pricing structure across instant, standard spray-dried, and roller-dried levels reflects protein integrity and solubility performance. Cost compression in European spray-dried tiers is intensifying because EU F-Gas refrigeration retrofits add capital recovery surcharges. Confectionery buyers in Poland and India exhibit highest price sensitivity, accepting thermal degradation for unit cost savings.
Supply Chain Analysis
Return flows of rejected powder lots at Mumbai and Chennai ports create reverse-logistics complexity for traders managing FSSAI microbiological compliance failures. Production gravity centers on New Zealand's Canterbury cluster, France's Normandy-Brittany belt, and India's Gujarat cooperative network. Raw milk supply, natural gas for thermal processing, and refrigerant gases for drying systems constitute critical input dependencies. Single-source vulnerability concentrates in Fonterra's captive Canterbury milk pool. Distribution runs through direct procurement agreements with named production clusters for nutrition channels, wholesale spot markets for confectionery buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fonterra's locked Canterbury supply position props pricing power across Asian infant formula channels, creating durable margin pools for upstream-controlled operators.
For Market Incumbents: Hedge refrigeration compliance exposure by accelerating ammonia and CO2 system adoption ahead of EU F-Gas deadlines. Secure membrane filtration capacity additions in Christchurch and Wageningen to capture Southeast Asian protein-specification premiums. Defensive positioning requires backward integration into geothermal-powered processing infrastructure before carbon-border adjustments harden. For New Entrants and Emerging Players: Launch via pouch-format consumer reconstitution products in West African urban centers where informal dairy consumption creates packaged white space. Target Ghanaian and Nigerian distribution partnerships ahead of formal retail infrastructure buildout. The most penetrable entry vector sits in household-sized instant powder for emerging middle-class households bypassing traditional trading house channels. For Investors and Strategic Acquirers: The window for entry favors cooperative-backed processors with captive milk supply and existing membrane filtration assets. Long-term viability hinges on geothermal or low-carbon energy access as carbon-border mechanisms mature. Watch China's dual carbon goal implementation timelines as the inflection signal for low-emission supply preference acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Preserves native whey protein structure for Southeast Asian infant formula compliance. |
| Ammonia Refrigeration Retrofit | Secures EU F-Gas compliance for European spray-drying operations ahead of deadlines. |
| Direct Procurement Relationship | Displaces trading house intermediaries for Vietnamese and Indonesian nutrition manufacturers. |
| Geothermal Energy Certification | Unlocks carbon-border adjustment advantages for New Zealand's Canterbury cluster exports. |
| West African Pouch Distribution | Captures informal dairy consumption conversion in Ghanaian and Nigerian urban markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with dairy processing plant managers, infant formula procurement directors, cooperative milk collection coordinators, and refrigeration system engineers. EFSA nutritional claims documentation, India's FSSAI import inspection records, New Zealand's Emissions Trading Scheme disclosures, and EU F-Gas implementation reports provided regulatory validation. Bottom-up volume estimates from named production clusters triangulated against top-down trade flow analysis.
Data-stream reconciliation across production capacity databases, milk supply forecasts, and end-use consumption surveys generated consistent projections across the analysis window. Segmentation modeling incorporated product type, end-user industry, packaging format, and regional production hub dimensions. CAGRs derived from trend extrapolation of protein-specification premium spreads, energy cost trajectories, and carbon-border adjustment phase-in schedules. Infant formula fortification mandate timelines and F-Gas retrofit deadlines served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for transcritical CO2 refrigeration or membrane pre-concentration scale-up would alter the outlook. Forecasts reflect assumptions about EU Green Deal implementation speed, Southeast Asian regulatory harmonization progress, and geothermal capacity expansion rates. Practitioners should monitor FSSAI microbiological limit enforcement intensity, China's dual carbon goal procurement preference signals, and West African retail infrastructure development for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Low-Calorie Butter Market
Dairy Products
Nonfat Dry Milk Market
Dairy Products
Low Temperature Yogurt Market
Dairy Products
Savory Dairy Products Market
Dairy Products
Africa Yogurt Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Filled Cheese Market
Dairy Products
Nigeria Yogurt Drinks Market
Dairy Products
Fruit Yogurt Market
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
Russia Whey Protein Market
Dairy Products
India Dairy Market
Dairy Products
Organic Dairy Products Market