
 Organic Milk Protein Market | 2026-2036
Organic Milk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Milk Protein Market Outlook
Grass-fed and A2-beta-casein specification tiers is reorganizing procurement priorities across the organic milk protein value chain. Arla Foods leverages its cooperative structure to sustain year-round organic milk supply across Northern European farming networks. Organic Valley anchors its competitive position through domestic U.S. sourcing and long-standing farmer partnerships. Fonterra Co-operative Group dominates Oceania's organic dairy ingredient exports with scale advantages in spray-drying infrastructure.
Organic milk protein denotes dairy-derived protein fractions—principally whey and casein—obtained from cattle raised on certified organic feed without synthetic hormones or antibiotics, typically processed through membrane filtration or ion exchange to achieve protein concentrations ranging from 34% to 90% dry basis. These ingredients function as emulsifiers, gelling agents, and complete amino acid sources in formulated foods and clinical nutrition. Isolate grades command premium positioning due to superior protein density and lower lactose content, while hydrolysate forms are gaining traction in infant formula and medical nutrition where allergen reduction matters. Sports nutrition as an end-user category exhibits the fastest volume trajectory, though bakery applications retain steadier contract volumes with longer purchase cycles.
USDA Organic certification and the EU Organic Regulation define feed sourcing, livestock management, and processing allowances that determine market access in North America and Europe. FDA nutrition labeling requirements and EFSA health claim assessments further shape product positioning and permissible marketing language for protein content and performance benefits. Stakeholders must monitor evolving pasture-access standards and antibiotic-treatment protocols, as regulatory divergence between major importing regions threatens to fragment supply chain compliance costs.
Market Dynamics
EU Green Deal farm-to-fork sustainability targets are tightening feed certification requirements and pasture-access standards, forcing processors to requalify supplier networks and compressing compliant raw milk availability across Northern European cooperatives.
Growth Catalysts
- EU Organic Regulation enforcement:Mandatory conversion periods and antibiotic-treatment protocols are locking in supply scarcity premiums that benefit certified processors with established farmer contracts.
- Sports nutrition formulation:Clean-label protein fortification in ready-to-drink beverages is accelerating isolate-grade procurement from organic-certified streams.
- Germany:Maturation of dedicated organic retail infrastructure including Aldi Süd and Rewe's bio-dedicated store formats is concentrating demand pull in Europe's largest organic food market.
Market Restraints
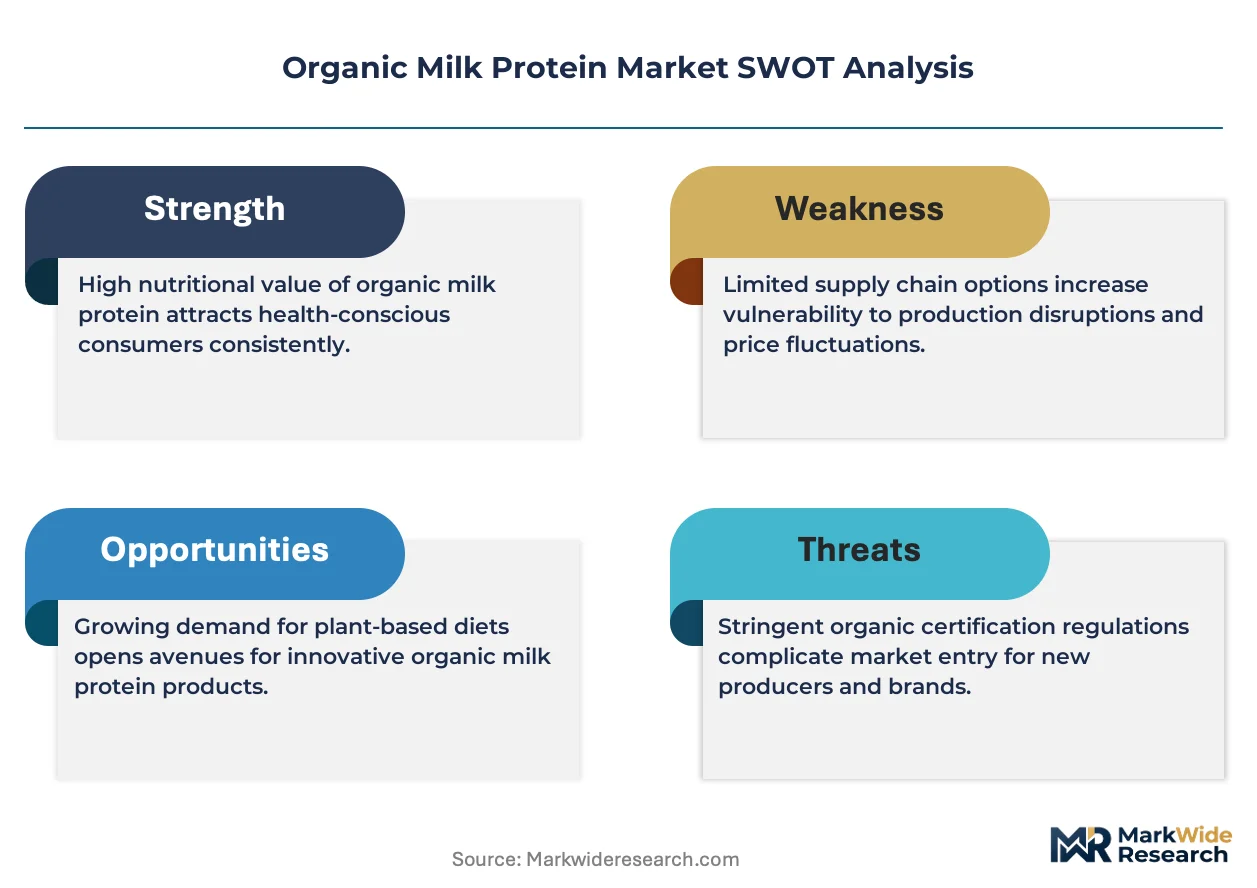
- Organic feed cost volatility:Non-GMO soybean and alfalfa price swings transmit directly to farmgate milk costs, compressing processor margins during commodity spikes.
- Oceania supply concentration:Fonterra's dominance in spray-dried organic dairy exports creates single-source vulnerability for Asian importers seeking whey isolate grades.
- Protein yield limitations:Membrane filtration of organic milk achieves lower concentration efficiency than conventional streams due to seasonal fat and protein variation.
Strategic Opportunities
- A2-beta-casein certification:Genetic testing and segregated processing for A2 protein variants commands 15-30% price premiums in infant formula and digestive-sensitive nutrition segments.
- Grass-fed tier differentiation:Year-round pasture verification through satellite monitoring and blockchain traceability is opening premium positioning in North American direct-to-consumer channels.
- Medical nutrition expansion:Hydrolysate production for allergen-reduced clinical applications remains underdeveloped relative to sports nutrition, with longer contract tenures and lower switching rates.
Industry Challenges
- Certification timeline compression:USDA Organic and EU Organic Regulation re-audits require 18-24 month lead times, freezing supplier additions during demand surges.
- Membrane filtration technician scarcity:Specialized operation of ceramic and spiral-wound ultrafiltration systems limits capacity expansion at mid-scale processors.
- Antibiotic residue detection integration:Rapid PCR testing for therapeutic antibiotic traces must interface with legacy siloed quality management systems without disrupting continuous processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Milk Protein Market |
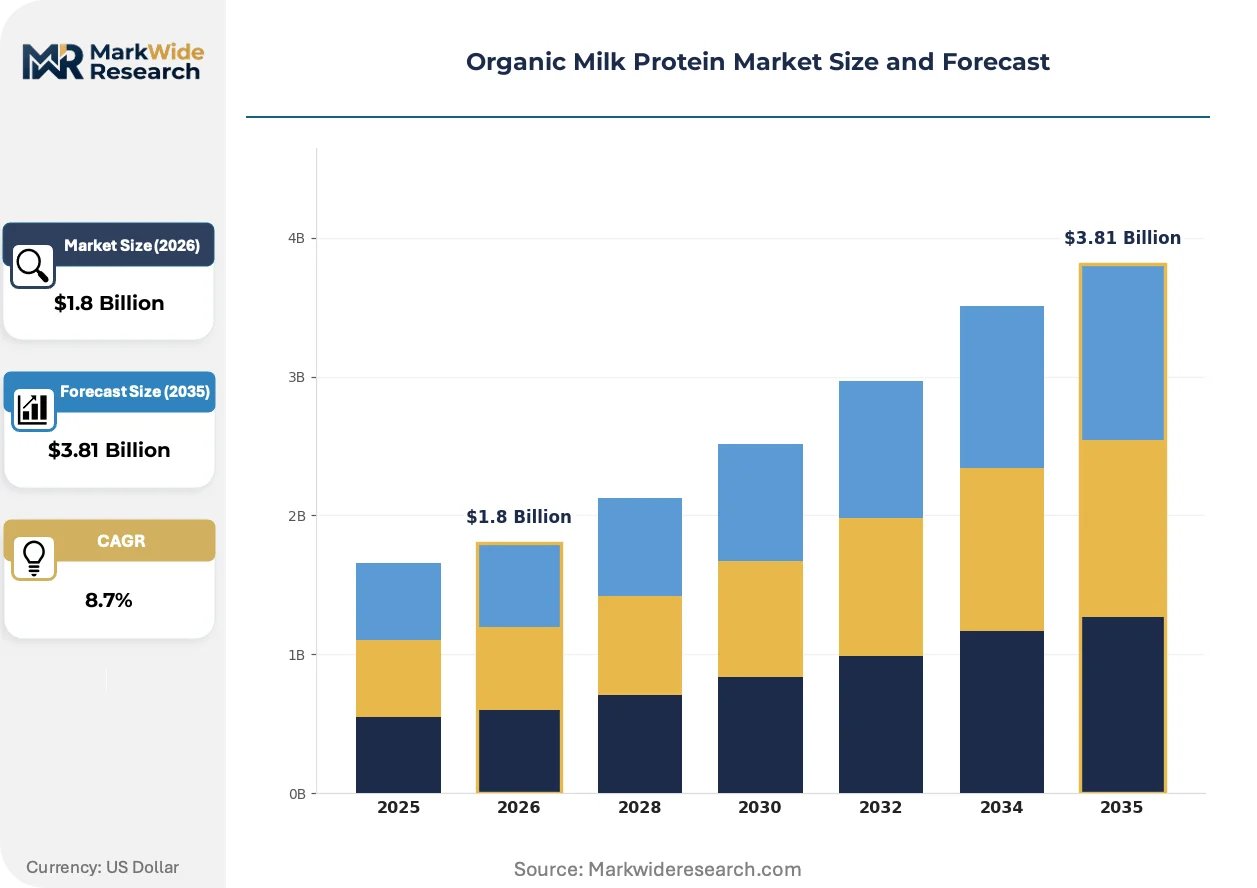
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolysate, Blends End User: Food & Beverage, Nutritional Supplements, Bakery, Sports Nutrition Form: Powder, Liquid, Gel, Creamy Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Arla Foods, Organic Valley, Fonterra Co-operative Group, Agropur Dairy Cooperative, Aurora Organic Dairy, Horizon Organic, Saputo, Groupe Lactalis, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Milk Protein Market Strategic Shifts
Protein fractionation technology and supply chain verification systems are reorganizing competitive advantage around purity tiers and provenance documentation rather than scale alone.
Precision fermentation-derived whey proteins are supplanting animal-sourced isolates in sports nutrition applications where brands prioritize supply security over organic certification. Nestlé and Danone pilot programs in European markets are validating functional equivalence for emulsification and amino acid profiles. This displacement is compressing demand growth for commodity-grade organic whey concentrate while reinforcing premium positioning for verified grass-fed and A2-tier isolates.
EU Green Deal carbon border adjustment mechanisms are extending scope to agricultural inputs, requiring organic dairy exporters to document embedded emissions in feed cultivation and manure management. German and Dutch processors are deploying satellite pasture-monitoring to satisfy audit requirements. The compliance burden falls heaviest on traders sourcing from mixed conventional-organic supplier pools rather than vertically integrated cooperatives.
Sports nutrition brands are consolidating supplier rosters from twelve-plus vendors to three-to-four strategic partners with captive organic streams and dedicated hydrolysate capacity. This concentration eliminates spot-market procurement for isolate grades. The shift is most visible in North American contract manufacturing, where brands like Vital Proteins and Orgain now require multi-year supply commitments with price collars indexed to organic feed futures.
Organic Milk Protein Market Segmentation
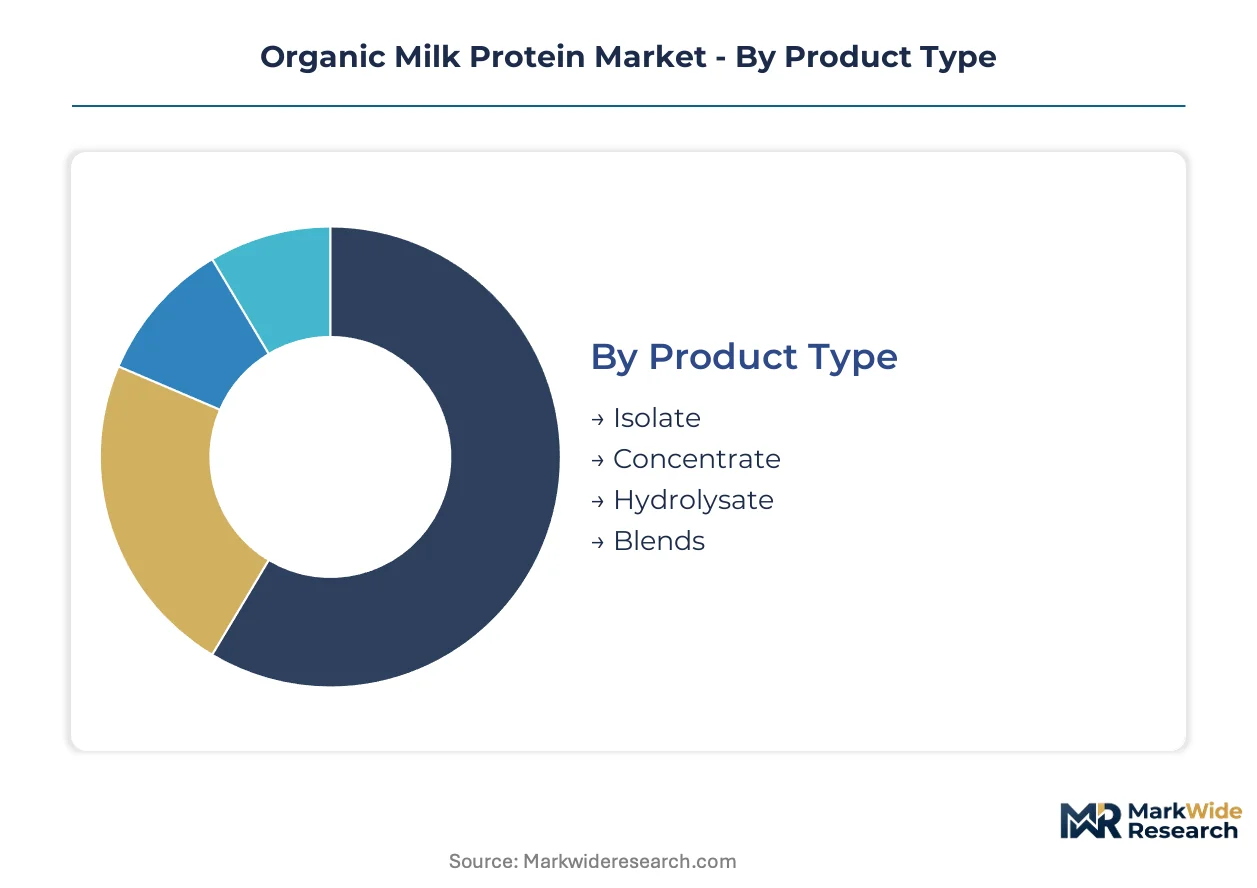
Segmentation in organic milk protein reveals how precision fermentation and plant-based alternatives apply asymmetric pressure across product tiers. Understanding substitution vulnerability by specification grade and channel exposure determines portfolio defense strategies.
Product Type:
Isolate grades face the most acute displacement threat from precision fermentation entrants targeting sports nutrition, while hydrolysate maintains defensive moats through clinical validation requirements.
- Isolate:Protein concentrations reaching 90% dry basis deliver superior amino acid density with minimal lactose residue. Demand concentrates in ready-to-drink sports beverages where brands like Vital Proteins require multi-year supply commitments with price collars indexed to organic feed futures. Substitution pressure from fermentation-derived equivalents is compressing commodity-grade isolate premiums while reinforcing grass-fed and A2-tier positioning.
- Concentrate:Standardized at 34-80% protein with higher fat and lactose content, this grade serves bakery and processed food applications where cost sensitivity dominates. German retail infrastructure maturation through Aldi Süd and Rewe bio-dedicated formats is pulling concentrate volumes into private-label organic dairy lines.
- Hydrolysate:Pre-digested protein fractions with reduced allergenicity for infant formula and medical nutrition segments. Clinical validation requirements and longer contract tenures create defensive barriers against fermentation substitutes.
- Blends:Customized whey-casein ratios optimizing functional properties for specific manufacturing processes. Mid-scale processors leverage blend flexibility to offset membrane filtration yield limitations in seasonal organic milk streams.
Concentrate anchors the volume base while isolate gains share at the steepest rate despite fermentation headwinds.
End User:
Cost tier stratification separates clinical nutrition premiums from commoditized food manufacturing, with sports nutrition occupying the contested middle ground where brand positioning determines margin capture.
- Sports Nutrition:Clean-label protein fortification in powders and ready-to-drink formats commands specification discipline around leucine content and dissolution properties. Supplier roster consolidation from twelve-plus vendors to three-to-four strategic partners with captive organic streams is eliminating spot-market procurement for isolate grades.
- Food & Beverage:Emulsification and gelling applications in organic dairy alternatives and functional beverages. EU Green Deal carbon border adjustment mechanisms are extending documentation requirements to embedded emissions in feed cultivation and manure management.
- Nutritional Supplements:Capsule and tablet formats targeting aging populations and clinical dietary management. Pharmacy channel distribution through German and Dutch health retail networks requires batch-level traceability certification.
- Bakery:Steadier contract volumes with longer purchase cycles retain volume stability despite lower per-unit margins. Protein functionality in dough conditioning and browning reactions sustains technical specification requirements that resist simple substitution.
Food & Beverage generates the largest absolute tonnage while sports nutrition climbs the fastest on value-per-kilogram metrics.
Form:
Supply concentration in spray-dried powder creates geographic dependency, while liquid and gel formats offer differentiation paths for regional processors seeking escape from Fonterra's Oceania dominance.
- Powder:Spray-dried and agglomerated formats dominate international trade logistics and extended shelf-life requirements. Fonterra's scale advantages in spray-drying infrastructure concentrate export capacity in New Zealand and Australia, creating single-source vulnerability for Asian importers seeking whey isolate grades.
- Liquid:Ultra-high temperature processing and aseptic packaging for ready-to-drink applications. Shorter shelf life and refrigerated distribution requirements favor regional production proximity to German and North American consumption clusters.
- Gel:Textured protein matrices for clinical nutrition and dysphagia management. Specialized formulation requirements sustain premium positioning outside commodity protein trading channels.
- Creamy:High-fat protein preparations for dessert and specialty dairy applications. Limited production scale and formulation expertise constrain competitive entry.
Powder commands international trade flows while liquid formats expand most quickly in regional direct-to-consumer channels.
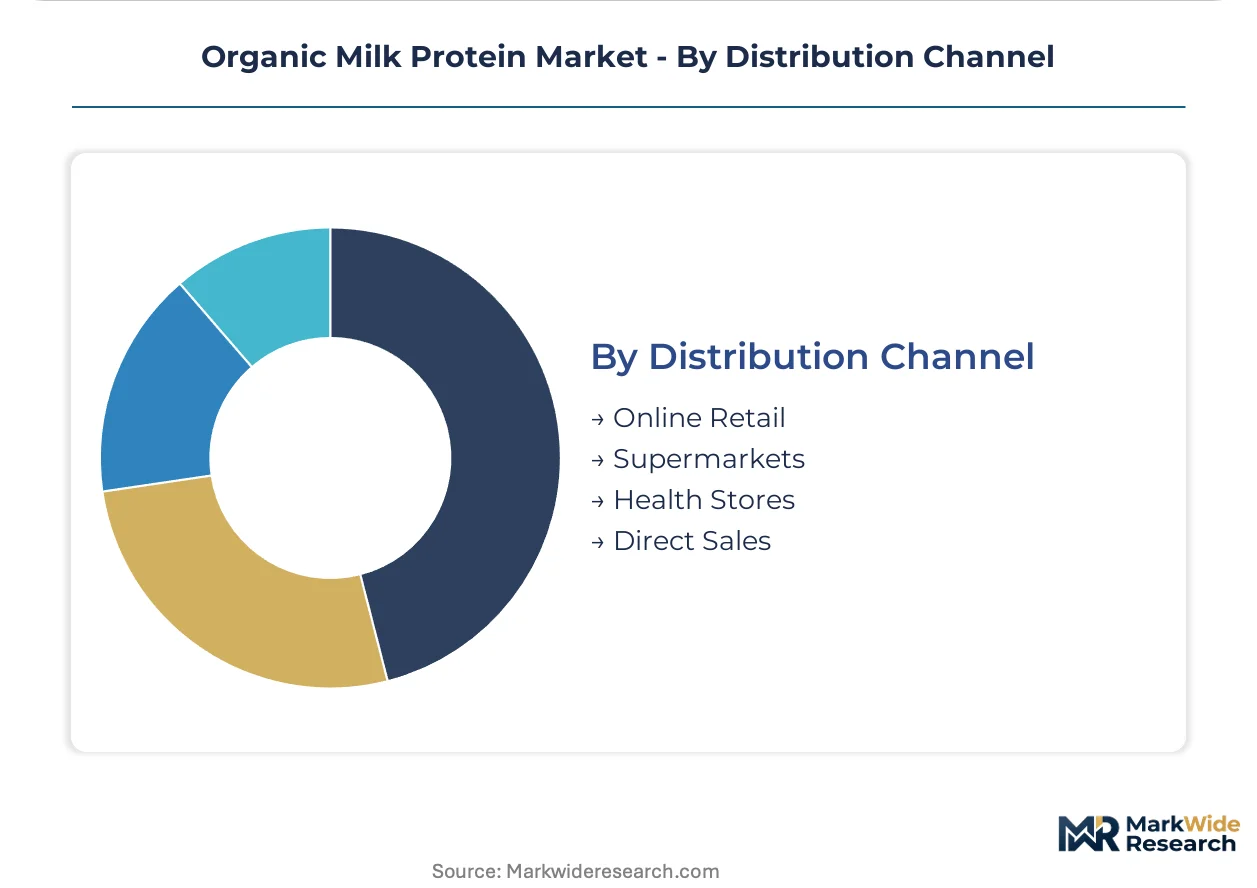
Distribution Channel:
Customer type separation between institutional procurement and retail self-selection determines certification burden and margin structure, with health stores and direct sales capturing premium tiers through advisory relationships.
- Online Retail:Subscription models and direct-to-consumer platforms enable grass-fed and A2-beta-casein tier differentiation through satellite pasture-monitoring and blockchain traceability documentation. North American brands like Orgain leverage digital channels to bypass conventional retail slotting fees.
- Supermarkets:Mass-market penetration through dedicated organic sections and private-label expansion. Rewe's bio-dedicated store formats in Germany demonstrate how retail infrastructure maturation concentrates demand pull in Europe's largest organic food market.
- Health Stores:Pharmacist and nutritionist advisory channels support premium positioning for hydrolysate and medical-grade isolates. Longer purchase consultation cycles sustain price premiums through education-intensive selling.
- Direct Sales:Contract manufacturing relationships and captive supply agreements between processors and brand owners. Multi-year commitments with price collars indexed to organic feed futures are becoming mandatory for isolate-grade procurement.
Supermarkets maintain volume dominance while online retail expands most rapidly through subscription retention models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's Fonterra dominates Oceania's organic dairy ingredient exports to Asian markets, while European processors requalify supplier networks under tightening EU Green Deal standards. German retail infrastructure maturation and North American direct-to-consumer channels are reshaping demand geography.
Germany
Rewe's bio-dedicated store formats and Aldi Süd's organic lines concentrate Europe's largest organic food market demand. The EU Organic Regulation enforces mandatory conversion periods and pasture-access standards that compress compliant raw milk availability. Bavarian cooperatives are deploying satellite pasture-monitoring to satisfy audit requirements for carbon border adjustment documentation.
United States
Domestic sourcing through long-standing farmer partnerships anchors supply security for brands like Orgain and Vital Proteins. USDA Organic certification requires 18-24 month re-audit lead times that freeze supplier additions during demand surges. The Pacific Northwest and Wisconsin dairy clusters are investing in hydrolysate capacity for medical nutrition applications.
New Zealand
Fonterra's spray-drying infrastructure concentrates Oceania's organic whey isolate export capacity, creating single-source vulnerability for Asian importers. The country's national agricultural regulator enforces equivalence agreements with EU and US organic standards to maintain market access. Canterbury and Waikato processing hubs are expanding membrane filtration technician training programs.
Netherlands
Rotterdam's port logistics and Dutch greenhouse feed cultivation position the country as a European organic dairy trade nexus. EU Green Deal farm-to-fork targets are extending carbon documentation requirements to embedded emissions in imported soybean and alfalfa. FrieslandCampina's cooperative structure sustains year-round organic milk supply across Northern European farming networks.
China
Domestic organic infant formula demand pulls isolate-grade imports through cross-border e-commerce channels. The country's national food safety regulator aligns organic certification with international standards while maintaining separate GB labeling requirements. Yangtze River Delta processing clusters are piloting blockchain traceability for grass-fed tier verification in premium segments.
Organic Milk Protein Market Competitive Environment
Listed leaders compete with private specialists across cooperative and corporate ownership structures, creating tiered competition around scale versus provenance verification. European dairy cooperatives leverage member-farmer contracts to secure year-round organic supply, while North American brands emphasize domestic sourcing narratives. Three archetypes dominate: vertically integrated cooperatives with captive milk streams, private-label processors serving retail chains, and ingredient specialists with dedicated hydrolysate capacity. Competitive moves center on multi-year supply commitments with organic feed futures indexing, and satellite-based pasture verification systems for premium tier differentiation.
Among cooperative-structured processors, Arla Foods and Fonterra Co-operative Group exemplify scale-driven positions anchored in Northern European and Oceania farming networks respectively. Organic Valley occupies a specialist archetype through its domestic U.S. sourcing model and farmer partnership density. These three entities represent distinct geographic and structural strategies—Danish-based cooperative, New Zealand-based export dominant cooperative, and American private specialist—illustrating how ownership form and regional milk shed access determine competitive positioning in constrained organic supply environments.
| Leading Market Players |
|---|
| Arla Foods |
| Organic Valley |
| Fonterra Co-operative Group |
| Agropur Dairy Cooperative |
| Aurora Organic Dairy |
| Horizon Organic |
| Saputo |
| Groupe Lactalis |
| Nestlé |
| Others |
Value Chain & Pricing Dynamics
Fonterra's spray-drying infrastructure scale in New Zealand compresses unit costs for commodity-grade organic whey concentrate while simultaneously elevating price floors for isolate grades through single-source export concentration. This scale asymmetry forces Asian importers into long-term offtake agreements with indexed collars, while European processors absorb organic feed volatility through cooperative member contracts.
Pricing Analysis
Membrane filtration technology-generation pricing gaps separate ceramic ultrafiltration isolates from spiral-wound concentrate grades, with hydrolysate commanding further premiums through enzymatic processing steps. Three-tier pricing structure across grass-fed A2-certified premium, standard USDA Organic, and economy-grade concentrate levels reflects certification depth and genetic verification costs. Pricing pressure stems from precision fermentation substitutes in sports nutrition, compressing commodity isolate margins while reinforcing provenance-premium tiers. Bakery and clinical nutrition buyers exhibit lowest price sensitivity due to functional specification lock-in, whereas ready-to-drink beverage brands drive hardest bargain through consolidated supplier rosters.
Supply Chain Analysis
New Zealand and Australia anchor Oceania's spray-dried organic dairy export capacity, while Germany and the Netherlands concentrate European processing and trade logistics. Raw material flows draw from non-GMO soybean cultivation in North America and alfalfa hay production across temperate grassland zones. Single-source vulnerability intensifies for Asian importers dependent on Fonterra's Canterbury and Waikato hubs. Distribution runs through Rotterdam's port nexus for European inbound flows and direct vessel charters for Pacific Rim destinations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic milk protein markets approach a platform-economics inflection as blockchain pasture-verification systems and satellite monitoring create interoperability standards between previously siloed certification regimes. This ecosystem shift rewards processors with captive data infrastructure and penalizes spot-market traders lacking traceability integration.
For Market Incumbents: Fortify supplier contract density through multi-year organic feed futures indexing, locking in Bavarian and Wisconsin cooperative streams before EU Green Deal pasture-access requalification tightens further. Backward integration into satellite pasture-monitoring infrastructure defends against emerging precision fermentation substitutes in sports nutrition isolate tiers. Prioritize hydrolysate capacity expansion for medical nutrition moats where clinical validation requirements resist substitution.
For New Entrants and Emerging Players: Anchor in A2-beta-casein genetic testing and segregated processing infrastructure, where 15-30% price premiums and limited incumbent specialization create penetrable white space. Target German direct-to-consumer subscription channels through Rewe's bio-dedicated format partnerships, bypassing Fonterra-dominated commodity powder trade. Lead with blockchain traceability documentation as differentiated go-to-market angle for grass-fed tier positioning.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors with captive organic milk streams and dedicated hydrolysate capacity, as multi-year supply commitments with price collars displace spot-market exposure. Long-term viability across the analysis window favors vertically integrated cooperatives over trader-intermediary models facing EU carbon border adjustment compliance burdens. Monitor precision fermentation scale-up announcements as inflection signal for commodity-grade isolate demand displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feed Cultivation | USDA Organic and EU Organic Regulation compliance secures raw material access during conversion period bottlenecks. |
| Satellite Pasture-Monitoring Deployment | EU Green Deal carbon border adjustment documentation satisfies audit requirements for German retail channel access. |
| Hydrolysate Production Capacity Expansion | Medical nutrition contract tenures and clinical validation barriers protect against fermentation substitution pressure. |
| Blockchain Traceability System Implementation | Grass-fed tier verification enables premium positioning in North American direct-to-consumer subscription channels. |
| Multi-Year Supply Agreement Structuring | Organic feed futures indexing stabilizes processor margins against non-GMO soybean and alfalfa price volatility. |
Study Parameters
Initial hypotheses were tested against primary input from dairy cooperative procurement directors, membrane filtration plant engineers, sports nutrition brand supply chain managers, and EU regulatory affairs specialists, then refined through secondary validation. Bottom-up triangulation combined customs trade data, USDA Organic certification registries, Fonterra cooperative disclosure filings, and EFSA health claim assessment records with top-down demand modeling across end-use segments.
Variance decomposition across product type, end user, form, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented volume-price elasticity modeling incorporated organic feed cost indices, EU Green Deal implementation timelines, and precision fermentation capacity announcements as industry-specific forecast inputs.
Underlying assumptions cover EU Organic Regulation enforcement continuity and pasture-access standard stability, with deviation risk concentrated in antibiotic-treatment protocol divergence between USDA and EU regimes. Recalibration cycles align with material shifts in carbon border adjustment scope and fermentation-derived protein functional equivalence validations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United Kingdom Dairy Market
Dairy Products
GCC Casein Market
Dairy Products
North America A2 Milk Market
Dairy Products
United States Camel Dairy Market
Dairy Products
Asia-Pacific Milk Protein Market
Dairy Products
Whole Milk Powder Market
Dairy Products
Condensed Milk Market
Dairy Products
United Kingdom Casein and Caseinates Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Malted Milk Powder Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
A2 Milk Market
Dairy Products
GCC UHT Milk Market
Dairy Products
Probiotic Yogurt Market
Dairy Products
North America Dairy Desserts Market
Dairy Products
Lactose-Free Cheese Market