
 Low-Calorie Butter Market | 2026-2036
Low-Calorie Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Butter Market Analytics
Plant-based oil blends is consolidating share from traditional dairy fat formulations as manufacturers reformulate to hit calorie-reduction targets without sacrificing functional performance. Land O'Lakes, Inc. leverages its dairy cooperative structure to maintain cost-advantaged milkfat sourcing even as it diversifies into blended offerings. Upfield Holdings B.V. dominates the plant-based spreadable segment through dedicated R&D facilities in the Netherlands. Arla Foods amba sustains European retail shelf presence with clean-label positioning that emphasizes reduced-fat dairy credentials.
Low-calorie butter denotes a spreadable fat product engineered to deliver standard butter functionality at reduced caloric density, typically achieved through water-in-oil emulsification, aeration, or partial substitution with lower-energy lipid analogs, with finished products generally targeting 25-40% fewer calories per gram than conventional butter. The primary commercial purpose centers on enabling food manufacturers and retail consumers to maintain sensory and processing characteristics in baked goods, sauces, and table spreads while complying with health-positioning requirements. Spreadable low-calorie butter leads volume due to its direct substitution appeal in household breakfast routines, while plant-based ingredient sources capture the fastest expansion as flexitarian consumers reject both full-fat dairy and hydrogenated alternatives. Supermarkets anchor value capture through controlled private-label placement and promotional slotting fees, though online retail grows fastest among subscription-based replenishment models.
FDA standards of identity for butter and related spreads govern permissible fat content and labeling claims in the United States, while EFSA nutrient profiling criteria shape whether products qualify for front-of-pack health endorsements across EU member states. BIS food safety standards in India impose compositional thresholds that low-calorie variants must navigate to access the organized retail channel. Stakeholders must monitor how evolving trans-fat restrictions and clean-label enforcement in multiple jurisdictions will redefine acceptable formulation pathways.
Market Dynamics
Water-in-oil emulsification technology is compressing formulation costs while EU nutrition labeling rules force bakeries across Western Europe into rapid product reformulation cycles.
Growth Catalysts
- EFSA nutrient profiling criteria:Front-of-pack health endorsements now drive retail placement decisions across Germany, France, and the Netherlands, pulling low-calorie butter into premium shelf positions.
- Aeration technology:Industrial bakeries deploy modified atmospheric processing to achieve 30% calorie reduction without sacrificing lamination performance in croissants and puff pastries.
- Food service transparency obligations:German menu labeling mandates force restaurant chains to disclose caloric content, accelerating kitchen-level substitution toward reduced-fat spreads.
Market Restraints
- Milkfat input volatility:Dairy cooperative pricing structures tie formulation costs to commodity butter futures, squeezing margin stability for blended product manufacturers.
- Technical emulsion stability:Extended shelf-life requirements for ambient distribution clash with water-in-oil system breakdown above 20°C storage thresholds.
- Plant oil supply concentration:Rapeseed and sunflower oil sourcing clusters in Black Sea region exposes producers to geopolitical disruption in Ukrainian and Russian export corridors.
Strategic Opportunities
- Subscription-based replenishment:Direct-to-consumer platforms bypass supermarket slotting fees while capturing recurring household demand for spreadable formats.
- Clean-label convergence:Partial substitution with cultured dairy fractions meets flexitarian preference for recognizable ingredient decks without full vegan positioning.
- Indian organized retail channel:BIS food safety standards currently block imported low-calorie variants, creating first-mover advantage for domestic formulation facilities meeting compositional thresholds.
Industry Challenges
- Emulsion science talent scarcity:Food chemistry programs produce insufficient specialists in lipid structuring and aerated fat systems, forcing manufacturers to train internally.
- Dual certification timelines:Simultaneous FDA standards of identity navigation and EFSA health claim validation extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Butter Market |
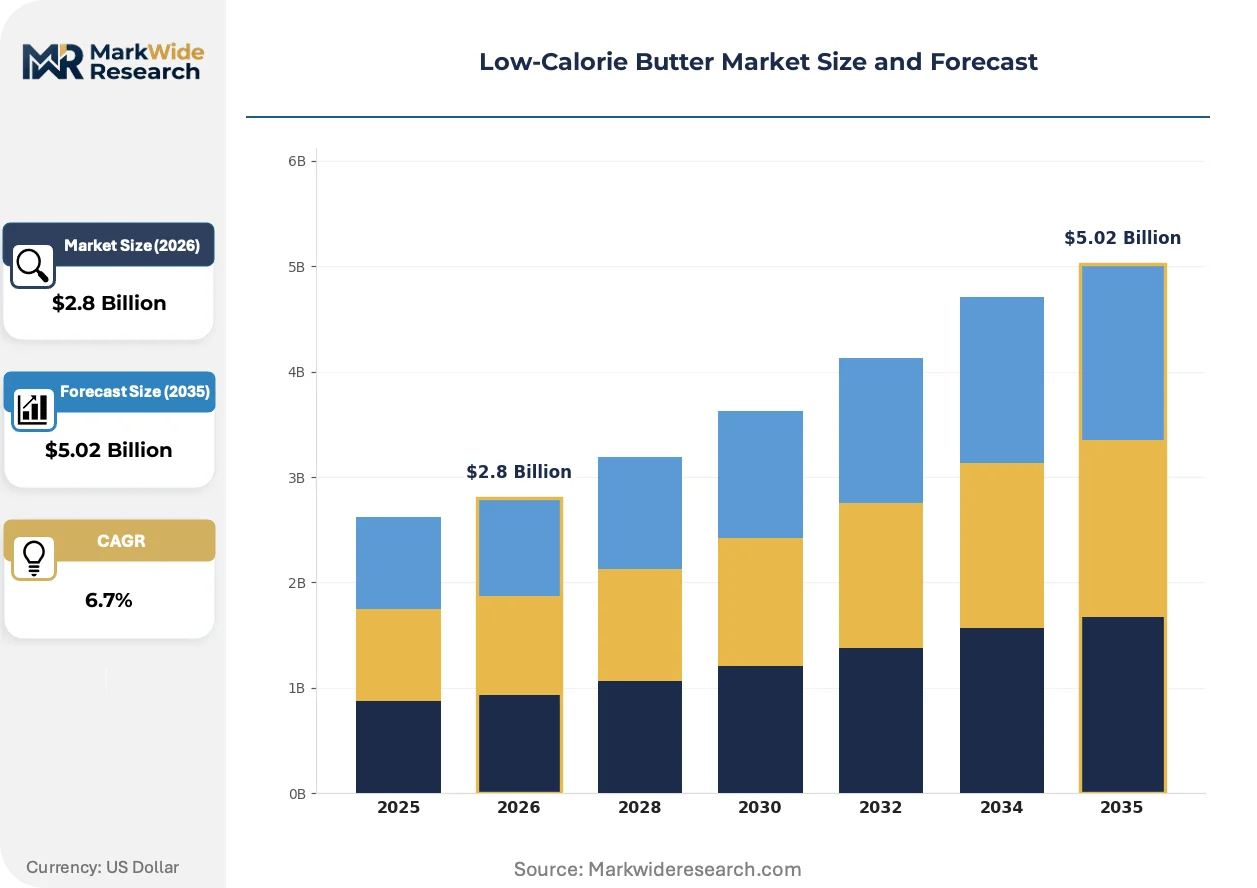
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spreadable, Cooking, Baking, Blending Ingredient Source: Plant-Based, Dairy, Hydrogenated, Emulsifiers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores End User: Households, Food Service, Bakeries, Restaurants |
| Companies Covered | Land O'Lakes, Inc., Arla Foods amba, Ornua Co-operative Limited, Saputo Inc., Gujarat Cooperative Milk Marketing Federation Ltd., Agral S.A., Finlandia Cheese, Inc., Upfield Holdings B.V., Palsgaard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Butter Market Evolving Landscape
Reformulation science is diverging along two paths: dairy-fat optimization for European clean-label preference versus plant-based emulation for North American flexitarian adoption.
Micro-encapsulated water droplet technology is integrating into industrial-scale churning equipment, enabling precise control over dispersed-phase distribution. German bakery cooperatives deploy these systems to maintain dough-handling properties while hitting calorie targets. The technology is integrating quality assurance protocols previously reserved for pharmaceutical emulsion manufacturing, compressing defect rates in high-volume production.
EU Green Deal nutritional benchmarks are tightening permissible saturated fat ratios in products carrying front-of-pack health symbols. Reformulation timelines have compressed from 36 months to 18 months for major retail brands seeking EFSA endorsement. Danish and Swedish dairy processors face the steepest compliance curves due to stricter national interpretation of profiling criteria.
Household buyers now prioritize direct substitution equivalence over premium health claims, forcing private-label development toward sensory-matched benchmarks rather than novel positioning. Supermarket chains in Germany and the Netherlands deploy blind taste panels to validate spreadability and melt-profile parity before shelf placement. Food service distributors report fastest adoption in institutional catering contracts where calorie caps are contractually mandated.
Low-Calorie Butter Market Segmentation
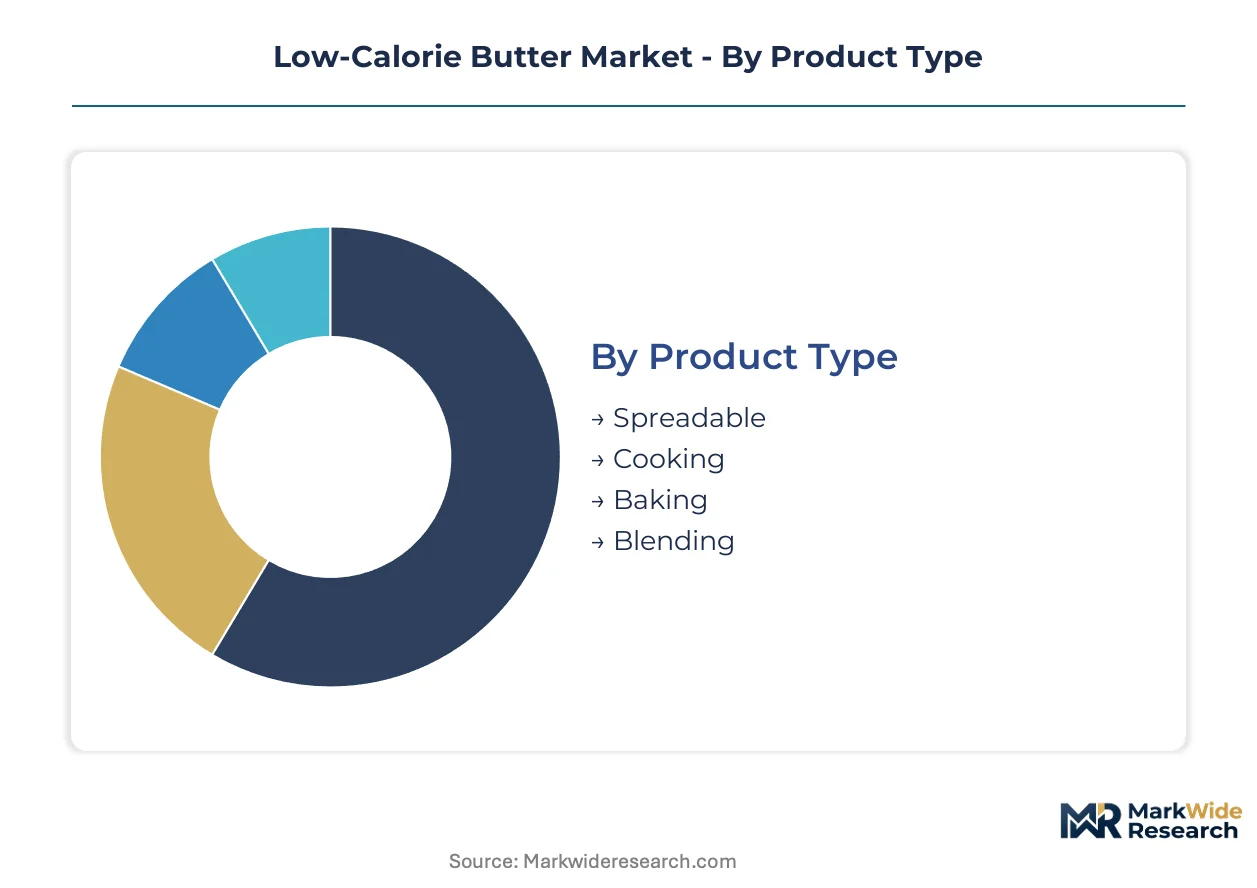
Low-calorie butter formulations diverge sharply across usage contexts and procurement channels, with each segment demanding distinct technical specifications and shelf-life profiles. Manufacturers must balance water-in-oil emulsion stability against cost targets that vary by customer scale and application intensity.
Product Type:
Buyers differentiate primarily by processing temperature requirements and shear tolerance during incorporation.
- Spreadable:Formulations prioritize cold-temperature plasticity and rapid oral melt profiles through controlled aeration and dispersed-phase engineering. German and Dutch supermarket chains drive procurement volume through private-label programs that mandate sensory parity testing against full-fat benchmarks.
- Baking:Lamination-grade products require precise fat crystallization behavior to maintain dough layer integrity through repeated folding and thermal cycling. Industrial bakeries in France and Belgium specify SFI profiles that preserve puff pastry lift even at 30% calorie reduction.
- Cooking:Sauces and pan-frying applications demand higher smoke-point tolerance and emulsion stability under thermal stress. Food service distributors in the United States stock these formulations for institutional kitchen contracts.
- Blending:Ingredient-grade butter serves as a base for compound spreads and flavored variants. Manufacturers value consistent moisture content for predictable downstream processing.
Spreadable formats lead volumes today; baking applications are climbing the fastest as EU nutrition labeling rules compress reformulation timelines.
Ingredient Source:
Cost tier and clean-label positioning determine sourcing strategy across customer segments.
- Plant-Based:Rapeseed and sunflower oil blends deliver the steepest calorie reduction through lipid fractionation and interesterification. Upfield's Dutch R&D facilities and similar operations in Germany refine texturizing systems that replicate dairy mouthfeel for flexitarian households.
- Dairy:Cultured cream and buttermilk fractions preserve recognizable ingredient decks for European clean-label preference. Arla Foods and cooperative processors in Denmark maintain retail shelf presence through reduced-fat dairy credentials and EFSA-aligned nutrient profiling.
- Hydrogenated:Legacy formulations persist in price-sensitive food service channels despite tightening trans-fat restrictions under FDA standards and EU regulations.
- Emulsifiers:Mono- and diglyceride systems enable water-in-oil stability in ambient distribution, though clean-label pressure is forcing migration toward lecithin and natural alternatives.
Dairy-based formulations retain the largest volume share; plant-based sources are expanding most quickly as Black Sea oil supply chains stabilize.
Distribution Channel:
Volume scale and margin structure separate procurement pathways for manufacturers.
- Supermarkets:Controlled shelf placement and promotional slotting fees dominate value capture in organized retail. German chains conduct blind taste panels before accepting low-calorie variants into premium positionings.
- Online Retail:Subscription-based replenishment models bypass traditional slotting costs while capturing recurring household demand. Direct-to-consumer platforms report fastest growth in spreadable format replenishment cycles.
- Specialty Stores:Health-focused independents and organic retailers stock premium-positioned clean-label variants with shorter ingredient lists.
- Convenience Stores:Impulse-driven single-serve and travel formats serve on-the-go consumption with compressed margin expectations.
Supermarkets anchor current volumes; online retail is gaining share fastest through subscription lock-in mechanics.
End User:
Application scale and regulatory exposure shape technical requirements and contract structures.
- Households:Direct substitution equivalence dominates purchasing criteria over premium health claims. Consumers prioritize spreadability and melt-profile parity in breakfast and cooking routines.
- Food Service:Institutional catering contracts increasingly mandate calorie caps through procurement specifications. German menu transparency obligations accelerate kitchen-level substitution toward reduced-fat spreads.
- Bakeries:Industrial-scale operations deploy modified atmospheric processing to achieve calorie targets without sacrificing lamination performance. EU nutrition labeling rules force rapid reformulation cycles across Western European cooperatives.
- Restaurants:Full-service operators balance sensory expectations against disclosure requirements under tightening menu labeling regimes.
Household consumption leads volumes today; food service channels are expanding most quickly as contractual calorie mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bakery cooperatives anchor industrial demand for low-calorie butter formulations as EU nutrition labeling rules compress reformulation timelines across Western Europe. Regulatory divergence between FDA standards in the United States and EFSA nutrient profiling in Europe shapes distinct formulation pathways. Supply chain concentration in Black Sea oil corridors exposes producers to geopolitical volatility.
Germany
Food service operators face tightening menu transparency obligations under national implementation of EU calorie disclosure rules. EFSA nutrient profiling criteria determine front-of-pack health endorsement eligibility for retail placement. Industrial bakeries in North Rhine-Westphalia deploy modified atmospheric processing to maintain lamination performance at reduced caloric density.
United States
Institutional catering contracts increasingly mandate calorie caps through procurement specifications. FDA standards of identity for butter and related spreads govern permissible fat content and labeling claims. Food service distributors in the Midwest stock reduced-fat formulations for contract feeding operations.
Netherlands
Plant-based spreadable formulations capture flexitarian household demand through dedicated R&D infrastructure. EU Green Deal nutritional benchmarks tighten permissible saturated fat ratios for health symbol qualification. Upfield's Wageningen-area facilities refine texturizing systems that replicate dairy mouthfeel without hydrogenated lipids.
India
Organized retail expansion creates first-mover opportunity for domestic formulation facilities meeting compositional thresholds. BIS food safety standards currently block imported low-calorie variants from accessing modern trade channels. Gujarat Cooperative Milk Marketing Federation leverages cooperative structure to scale reduced-fat dairy production for emerging urban markets.
France
Premium bakery segments demand precise fat crystallization behavior for puff pastry applications at calorie-reduced specifications. EFSA-aligned nutrient profiling shapes whether products qualify for front-of-pack health endorsements. Industrial bakeries in Brittany and Normandy specify solid fat index profiles that preserve product lift through thermal cycling.
Low-Calorie Butter Market Competitive Landscape
Global majors compete with regional champions across formulation technology and clean-label positioning. The market structure consolidates around dairy cooperative networks with captive milkfat supply and specialized plant-based emulsion specialists with dedicated R&D infrastructure. Three archetypes dominate: cooperative-backed dairy processors with backward integration into farm supply, multinational spread manufacturers with proprietary lipid structuring capabilities, and regional dairy federations with protected designation credentials. Competitive moves center on portfolio diversification into hybrid dairy-plant formulations and geographic expansion through regulatory-first market entry strategies.
Among cooperative-structured processors, Land O'Lakes, Inc. and Arla Foods amba exemplify the dairy-backed archetype with member-governed supply chains. Upfield Holdings B.V. occupies a distinct position as a plant-based specialist with centralized European R&D operations. These three entities represent the primary competitive vectors: cooperative scale, multinational technology licensing, and purpose-built alternative protein infrastructure.
| Leading Market Players |
|---|
| Land O'Lakes, Inc. |
| Arla Foods amba |
| Ornua Co-operative Limited |
| Saputo Inc. |
| Gujarat Cooperative Milk Marketing Federation Ltd. |
| Agral S.A. |
| Finlandia Cheese, Inc. |
| Upfield Holdings B.V. |
| Palsgaard |
| Others |
Value Network & Pricing Analysis
Supermarket private-label procurement teams in Germany and the Netherlands concentrate purchasing volume, compressing supplier margins through controlled shelf placement and promotional slotting fees. This buyer concentration forces manufacturers into contract-based long-term offtake structures that lock in milkfat input costs against commodity butter futures volatility.
Pricing Analysis
Input-cost pass-through from Black Sea oil corridors and dairy cooperative pricing structures governs margin stability across formulation tiers. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-endorsed clean-label variants from private-label sensory-matched benchmarks and institutional food service contracts. Price differentiation rests on certification grade and volume scale, with industrial bakery procurement commanding steepest discounts. Cost compression in the plant-based tier is intensifying because rapeseed and sunflower oil sourcing clusters expose producers to geopolitical disruption. Food service distributors exhibit highest price sensitivity due to contractually mandated calorie caps, while specialty organic retailers tolerate premium positioning for shortened ingredient lists.
Supply Chain Analysis
Workforce availability in Dutch R&D corridors and Danish dairy processing clusters shapes emulsion science capacity for lipid structuring and aerated fat systems. Manufacturing concentrates in the Netherlands, Germany, and Denmark, with upstream sourcing drawn from Black Sea oil corridors and cooperative milkfat networks. Raw material dependencies center on rapeseed oil, sunflower oil, and cultured dairy fractions. Single-source vulnerability in Ukrainian and Russian export corridors threatens formulation continuity. Distribution runs through supermarket controlled-shelf placement with fastest growth in direct-to-consumer subscription platforms bypassing traditional slotting costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-calorie butter market functions as a geographic-arbitrage play between EU EFSA nutrient profiling compliance costs and Indian BIS threshold navigation, where domestic formulation facilities capture first-mover advantage in organized retail expansion.
For Market Incumbents: Lock in captive milkfat supply through cooperative structure reinforcement while diversifying into hybrid dairy-plant formulations. Plant-based specialists with dedicated R&D infrastructure threaten market share in flexitarian segments. Backward integration into emulsion science talent pipelines addresses workforce scarcity in lipid structuring. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier to entry for spreadable format penetration without supermarket slotting fee burdens. White-space targets include Indian domestic formulation facilities meeting BIS compositional thresholds and German food service channels under menu transparency obligations. A regulatory-first market entry strategy bypasses incumbent shelf control. For Investors and Strategic Acquirers: Dairy cooperative networks with captive farm supply are the most active acquirer in this space, consolidating regional champions for EFSA-aligned nutrient profiling scale. Long-term viability hinges on clean-label convergence and flexitarian preference capture. Acquisition target archetype: specialized plant-based emulsion specialists with proprietary texturizing systems. Watch for EU Green Deal nutritional benchmark tightening as inflection indicator for reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Formulation Development | Arla Foods and cooperative processors capture flexitarian demand without full vegan positioning. |
| Direct-to-Consumer Launch | Subscription platforms bypass German supermarket slotting fees while locking in household replenishment. |
| Regulatory-First Market Entry | Domestic Indian facilities meeting BIS thresholds access organized retail channels blocked to imports. |
| Emulsion Science Talent Pipeline | Internal training programs address scarcity of lipid structuring specialists in food chemistry programs. |
| EFSA Endorsement Investment | Front-of-pack health symbols secure premium shelf placement under EU nutrition labeling rules. |
Research Methodology
Coverage spans Western Europe, North America, and South Asia, with primary inputs from each region combining interviews with food formulation scientists, supermarket category buyers, food service procurement directors, and dairy cooperative supply managers with secondary validation. Secondary sources include EFSA nutrient profiling databases, FDA standards of identity filings, BIS food safety compositional thresholds, EU Green Deal nutritional benchmark disclosures, and customs records for plant oil trade flows. Bottom-up volume modeling triangulates against top-down market sizing across ingredient source and distribution channel dimensions.
Rate-of-change decomposition separates volume growth from value expansion across product type, ingredient source, distribution channel, and end-user segments over the projection horizon. CAGRs derive from segmented growth rate analysis incorporating EFSA endorsement timeline compression, Black Sea oil supply corridor stability, and flexitarian adoption curve trajectories. Industry-specific inputs include bakery reformulation cycle data under EU nutrition labeling rules and food service contract calorie mandate proliferation rates.
The model assumes a particular technology adoption path for water-in-oil emulsification and aeration systems; alternative pathways for micro-encapsulated water droplet integration would alter the outlook. Forecasts reflect assumptions around EFSA nutrient profiling criteria stability, trans-fat restriction enforcement trajectories, and clean-label pressure intensity. Material deviation in EU Green Deal benchmark tightening or Black Sea supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Citrus Yogurt Market
Dairy Products
UHT Milk Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
Global Milk Protein Market
Dairy Products
High Protein Yogurt Market
Dairy Products
Lactose Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
US Cheese Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Low Fat Butter Market
Dairy Products
Reconstituted Milk Market
Dairy Products
Butter and Margarine Market
Dairy Products
Europe Dairy Based Beverages Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
Recombined Milk Products Market