
 Laboratory Sample Container Market | 2026-2036
Laboratory Sample Container Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Sample Container Market Foresight
Chinese polymer resin suppliers is hardening pricing leverage over container molders in North America and Europe. Thermo Fisher Scientific leverages its vertically integrated plastics compounding network to secure resin allocations ahead of spot-market volatility. Corning Incorporated anchors its position through proprietary borosilicate glass formulations that command specification lock-in at reference laboratories. DWK Life Sciences competes by sustaining dual-source manufacturing across German and Mexican plants to hedge freight cost swings.
Laboratory sample containers are vessels engineered to maintain specimen integrity through controlled chemical inertness, thermal stability, and barrier properties against moisture or gas permeation; manufacturers typically injection-mold polypropylene or blow-mold polyethylene to precise dimensional tolerances, then apply gamma irradiation or ethylene oxide terminal sterilization for clinical-grade applications. Plastic containers dominate routine diagnostic workflows due to disposability and breakage resistance, while glass cuvettes and vacutainers retain preference where optical clarity or inertness against solvent extraction is paramount. Cryovials represent the fastest-expanding container type as biobanking infrastructure scales, though blood collection applications still generate the deepest margin pools through high-volume hospital procurement contracts.
The FDA enforces container closure integrity standards under current Good Manufacturing Practice guidelines, while the EU MDR tightens traceability requirements for devices contacting human-derived specimens. ISO 10993 biocompatibility testing and USP Class VI certification now function as baseline market-access credentials rather than differentiators. Stakeholders must monitor how EPA per- and polyfluoroalkyl substance restrictions reshape fluoropolymer barrier coatings used in specialized storage vessels.
Market Dynamics
Pre-sterilized single-use container demand from pharmaceutical quality control laboratories is compressing reusable glass workflows while tightening material validation requirements under FDA guidance reshape supplier qualification protocols.
Growth Catalysts
- EU MDR traceability mandates:Device-level serialization requirements for specimen-contacting containers expand addressable market for integrated RFID-enabled vials in European diagnostic networks.
- Cryopreservation infrastructure buildout:Biobanking scale-up across academic medical centers and CROs accelerates demand for ultra-low temperature certified cryovials with validated thermal cycling performance.
- Heidelberg-Mannheim corridor concentration:Germany's biopharmaceutical manufacturing cluster generates localized procurement volume for GMP-grade containers with documented supply chain provenance.
Market Restraints
- Polypropylene resin cost volatility:Chinese petrochemical suppliers exercise pricing leverage over North American and European molders, compressing margin buffers for non-integrated manufacturers.
- Fluoropolymer coating restrictions:EPA per- and polyfluoroalkyl substance regulations threaten barrier performance of specialized storage vessels requiring gas-impermeable liners.
- Borosilicate glass specification lock-in:Reference laboratory preference for proprietary glass formulations creates switching costs that slow plastic container penetration in high-sensitivity assays.
Strategic Opportunities
- Gamma-stable polymer development:Convergence of radiation-resistant compounding and blow-fill-seal integration enables terminal sterilization without ethylene oxide residue concerns.
- Mexican manufacturing expansion:Nearshoring momentum creates white space for dual-source production hubs serving US diagnostic instrument OEMs with reduced freight exposure.
- ISO 10993 biocompatibility premium tier:Elevated baseline certification requirements open margin expansion for suppliers offering extended extractables testing documentation.
Industry Challenges
- Container closure integrity validation timelines:FDA guidance updates extend qualification periods for new material submissions, delaying product commercialization cycles.
- Freight cost hedging complexity:Dual-source manufacturing across German and Mexican plants requires sophisticated inventory positioning to buffer ocean and air cargo rate swings.
- Legacy sterilization equipment compatibility:Ethylene oxide facility closures force rapid revalidation of gamma irradiation protocols without disrupting existing hospital procurement contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Sample Container Market |
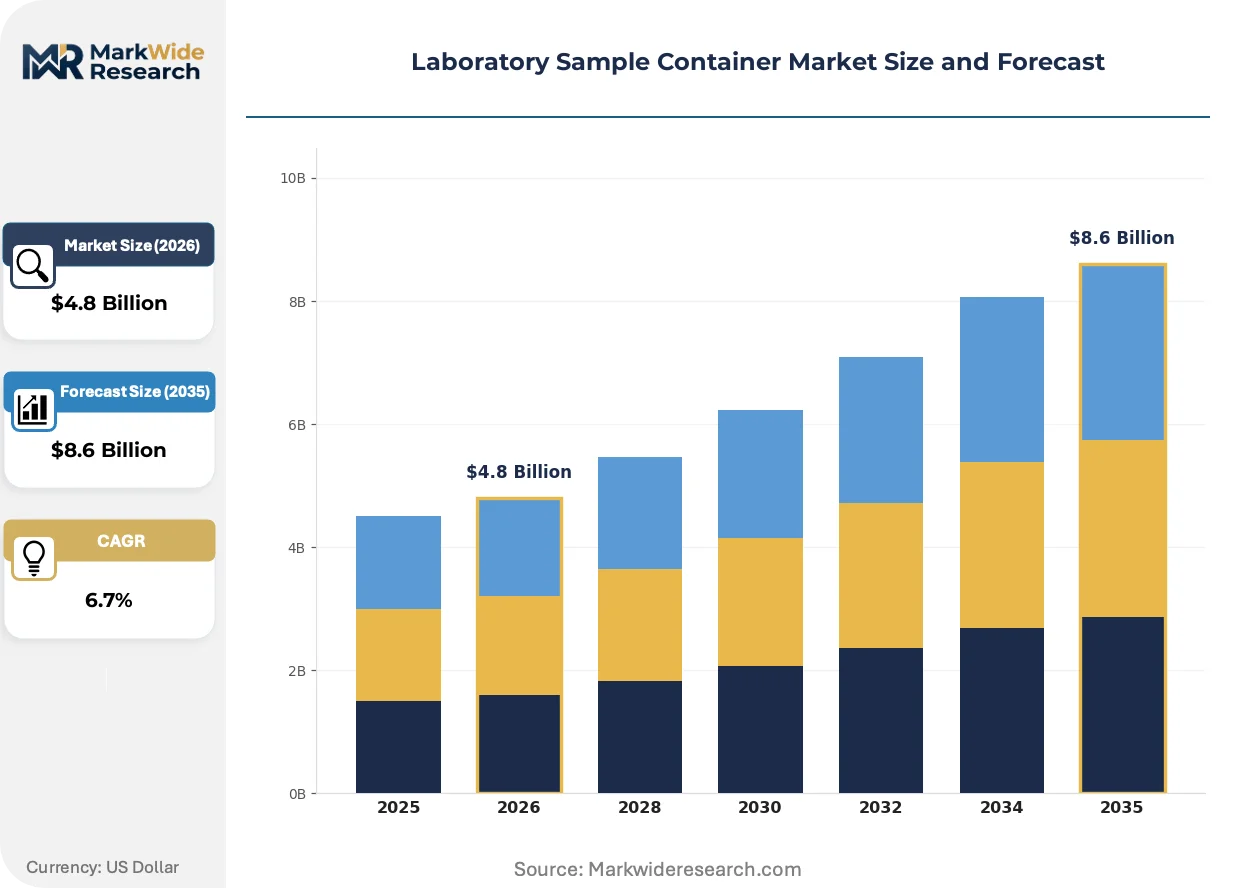
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Vacutainer, Cuvette, Cryovial, Test Tube Material: Plastic, Glass, Polypropylene, Polyethylene Volume Capacity: 1 mL, 5 mL, 10 mL, 20 mL Application: Blood Collection, Urine Testing, Tissue Preservation, Microbiology |
| Companies Covered | Thermo Fisher Scientific Inc., Corning Incorporated, Merck KGaA, Cardinal Health, DWK Life Sciences, Bio-Rad Laboratories, Inc., Eppendorf SE, Avantor, Inc., SARSTEDT AG & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Sample Container Market Shifts & Advancements
Active material science development and regulatory protocol evolution are compressing traditional container categories while enabling functional specialization previously unattainable at scale.
Multi-layer co-extruded barrier films are consolidating performance expectations for long-term biobank storage. Cryovial manufacturers adopt ethylene vinyl alcohol interlayers to achieve oxygen transmission rates below 0.1 cc per square meter per day. Biorepository operators in the US and Germany now specify these structures as default for specimens exceeding ten-year retention protocols.
REACH restrictions on substance of very high concern classifications are forcing reformulation of plasticizers and stabilizers in polypropylene medical grades. Compounders serving diagnostic container molders must resubmit technical files for existing product lines. German chemical suppliers lead transition timelines, creating temporary supply asymmetry against Asian resin competitors.
Consolidated procurement through group purchasing organizations is compressing vendor counts at integrated health networks. Hospital systems in the US now mandate sole-source contracts for high-volume blood collection tubes, displacing fragmented supplier relationships. Reference laboratories respond by certifying secondary vendors to maintain negotiating leverage against price step-ups.
Laboratory Sample Container Market Segmentation
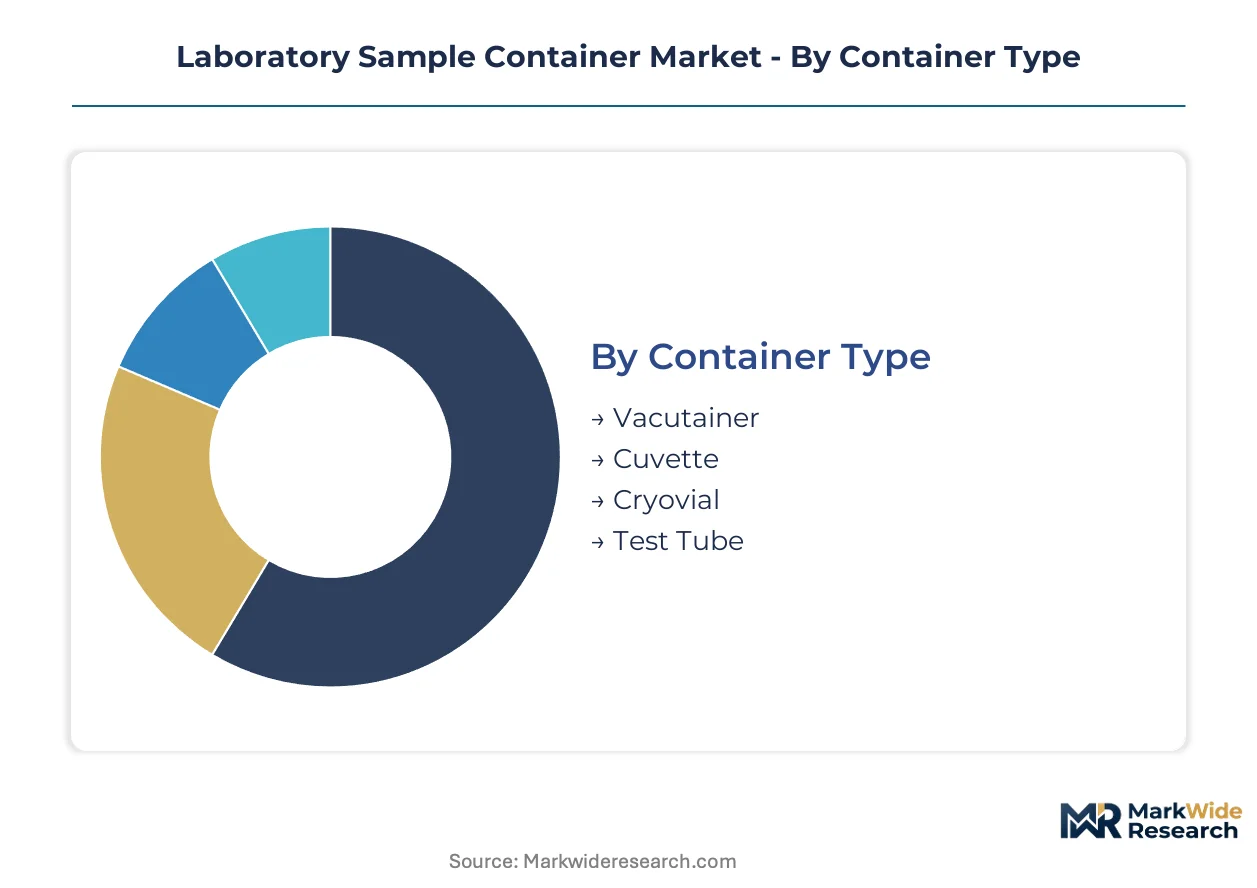
Container selection in laboratory workflows follows upgrade cycles tied to instrument compatibility, sterilization protocol changes, and biobank retention requirements. Procurement decisions increasingly weight total cost of ownership against upfront unit pricing as validation timelines extend.
Container Type:
Upgrade cycles accelerate where legacy formats face instrument obsolescence or new regulatory sterilization mandates.
- Cryovial:Multi-layer co-extruded structures with ethylene vinyl alcohol interlayers achieve oxygen transmission below 0.1 cc per square meter per day. US and German biorepositories specify these as default for specimens under ten-year retention protocols, compressing single-layer polypropylene alternatives.
- Vacutainer:Evacuated blood collection tubes with precise vacuum calibration remain the revenue anchor through high-volume hospital procurement contracts. Integrated health networks in the US now mandate sole-source agreements, displacing fragmented supplier relationships.
- Cuvette:Optical-grade borosilicate or UV-transparent plastic vessels for spectrophotometric analysis.
- Test Tube:General-purpose cylindrical vessels for non-evacuated specimen handling and processing.
Cryovial sits at the top of the volume ranking, with Vacutainer climbing the fastest as blood collection standardization tightens.
Material:
Cost tiers separate integrated compounders from molders exposed to spot resin volatility.
- Polypropylene:Gamma-stable medical grades with reformulated plasticizers respond to REACH substance of very high concern restrictions. German chemical suppliers lead transition timelines, creating temporary supply asymmetry against Asian resin competitors.
- Glass:Proprietary borosilicate formulations command specification lock-in at reference laboratories where solvent extraction resistance and optical clarity are paramount. Corning's captive formulations slow plastic penetration in high-sensitivity assays.
- Plastic:General-purpose injection-molded or thermoformed vessels for routine diagnostic workflows.
- Polyethylene:Blow-molded grades for moisture barrier applications and cost-sensitive high-volume procurement.
Polypropylene dominates procurement tonnage, with Glass defending margin share through specification capture.
Volume Capacity:
Application-driven sizing concentrates procurement around instrument deck compatibility and specimen protocol requirements.
- 10 mL:Standard blood collection volume aligning with automated analyzer throughput specifications. Hospital group purchasing organizations standardize on this capacity to reduce SKU complexity across integrated networks.
- 1 mL:Micro-volume vessels for pediatric sampling and finger-stick capillary collection. Pediatric departments and point-of-care testing sites in Germany's Heidelberg-Mannheim corridor specify these for neonatal metabolic screening programs.
- 5 mL:Mid-range capacity for chemistry panels and coagulation studies.
- 20 mL:Large-volume containers for tissue homogenates and specialized research applications.
10 mL anchors procurement volume, with 1 mL gaining share fastest as point-of-care testing expands.
Application:
End-use concentration shapes regional supply chain configuration and certification requirements.
- Blood Collection:Pre-sterilized single-use containers from pharmaceutical quality control laboratories compress reusable glass workflows. FDA container closure integrity guidance tightens material validation protocols, extending supplier qualification timelines.
- Tissue Preservation:Ultra-low temperature certified vessels with validated thermal cycling performance serve biobanking infrastructure buildout. Academic medical centers and CROs specify these for cryopreservation protocols exceeding twenty-year retention.
- Urine Testing:Leak-resistant containers with boric acid preservatives for microbiological culture and drug screening workflows.
- Microbiology:Sterile vessels with anaerobic or aerobic transport media for pathogen isolation and identification.
Blood Collection commands the deepest margin pools, with Tissue Preservation expanding most quickly behind biobank investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States biopharmaceutical infrastructure outpaces German manufacturing density in absolute container procurement volume, though Heidelberg-Mannheim corridor specialization commands premium pricing for GMP-grade specifications.
United States
Hospital group purchasing organizations consolidate vendor relationships around sole-source blood collection tube contracts. FDA container closure integrity guidance extends material validation timelines for new supplier qualification. Boston-Cambridge biotech cluster drives demand for cryovial specifications supporting twenty-year biobank retention protocols.
Germany
REACH substance of very high concern restrictions force polypropylene medical grade reformulation across diagnostic container supply chains. ECHA compliance deadlines create temporary supply asymmetry favoring domestic chemical suppliers. Heidelberg-Mannheim biopharmaceutical manufacturing corridor concentrates procurement for pre-sterilized single-use containers with documented provenance.
China
Polymer resin suppliers exercise hardened pricing leverage over North American and European container molders through petrochemical capacity concentration. NMPA biocompatibility certification requirements tighten market access for imported diagnostic vessels. Yangtze River Delta injection molding base scales output for cost-sensitive high-volume vacutainer export markets.
Japan
PMDA quality management system inspections emphasize container closure integrity validation for pharmaceutical quality control applications. METI funding for regenerative medicine infrastructure accelerates cryopreservation vessel procurement at academic medical centers. Kansai region specialty chemical compounders develop gamma-stable polymer grades for terminal sterilization workflows.
India
CDSCO medical device rules implementation drives formalization of previously unregistered container suppliers serving diagnostic laboratories. PLI scheme incentives attract blow-fill-seal integration investment for pre-sterilized single-use formats. Maharashtra pharmaceutical manufacturing belt expands backward integration into captive container molding capacity.
Laboratory Sample Container Market Competitive Landscape
United States producers anchor one tier through vertically integrated life science conglomerates; German specialists hold specification-capture positions in borosilicate glass and precision molding. Market structure concentrates around three to five dominant compounder-molder networks with captive resin allocation, while mid-scale regional fabricators compete on logistics proximity. Strategic archetypes include integrated plastics compounders, dual-source manufacturing hedgers, and proprietary formulation defenders. Competitive moves center on gamma-stable polymer development partnerships and Mexican nearshoring capacity expansion.
Among integrated life science conglomerates, Thermo Fisher Scientific and Corning Incorporated exemplify divergent archetype strategies. Thermo Fisher leverages captive plastics compounding networks to secure resin allocations ahead of spot-market volatility. Corning anchors premium positioning through proprietary borosilicate glass formulations that command specification lock-in at reference laboratories. DWK Life Sciences occupies a position between these models, sustaining dual-source manufacturing across German and Mexican plants to hedge freight cost exposure.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Corning Incorporated |
| Merck KGaA |
| Cardinal Health |
| DWK Life Sciences |
| Bio-Rad Laboratories, Inc. |
| Eppendorf SE |
| Avantor, Inc. |
| SARSTEDT AG & Co. KG |
| Others |
Supply & Pricing Matrix
ISO 10993 certification tiers bifurcate the Laboratory Sample Container Market into premium-validated and baseline-compliant supply echelons, with German chemical compounders commanding price premiums through REACH-compliant medical-grade resin formulations while Asian molders compete on spot-market polypropylene pricing. This tier divergence concentrates high-margin procurement around Heidelberg-Mannheim corridor biopharmaceutical manufacturers who mandate documented supply chain provenance, whereas cost-sensitive hospital networks in the United States optimize for freight-minimized Mexican production.
Pricing Analysis
Distributor markups of 15-25 percentage points separate direct OEM contracts from hospital group purchasing organization procurement, with three-tier pricing structure across premium, standard, and economy levels anchored by gamma-sterilization validation depth and extractables testing documentation. Price differentiation stems from ISO 10993 extended certification bundles and captive resin compounding integration, with cost compression in commodity polypropylene containers intensifying because Chinese petrochemical suppliers exercise spot-market pricing leverage. Blood collection tube contracts show highest price sensitivity among integrated health networks, while reference laboratories demonstrate lowest sensitivity due to assay lock-in requirements.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and CDSCO medical device rules are reshaping sourcing patterns for pre-sterilized single-use containers, compelling multinational molders to establish captive blow-fill-seal capacity in Maharashtra. Manufacturing gravity centers on China for polymer resin feedstock, Germany for precision borosilicate glass formulation, and Mexico for North American freight hedging, with raw material dependencies spanning propylene monomer, ethylene vinyl alcohol barrier films, and gamma-irradiation cobalt-60 supply. Single-source vulnerability concentrates in Chinese petrochemical capacity for medical-grade polypropylene, while distribution runs through diagnostic instrument OEMs, hospital group purchasing organizations, and biorepository operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Laboratory Sample Container Market functions as a stable compounder anchored by irreversible biobank infrastructure buildout and tightening FDA container closure integrity mandates that extend validation timelines and deepen incumbent relationships.
For Market Incumbents: Anticipate margin compression from Chinese resin pricing leverage by accelerating backward integration into captive compounding networks or securing long-term offtake agreements with German chemical suppliers ahead of REACH transition deadlines. Defensive positioning requires dual-source manufacturing expansion across Mexican plants to buffer freight cost volatility, while certification investment in gamma-stable polymer development preserves premium tier access against ethylene oxide facility closures.
For New Entrants and Emerging Players: Direct-to-biorepository digital procurement platforms offer white-space entry around cryovial specifications for twenty-year retention protocols, with lowest penetration in US academic medical center networks currently locked into sole-source hospital contracts. Target pediatric micro-volume segments in Germany's Heidelberg-Mannheim corridor where neonatal metabolic screening programs specify 1 mL capacity vessels, deploying rapid-customization tooling to bypass incumbent specification lock-in.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale regional fabricators lack ISO 10993 extended documentation capabilities to serve European diagnostic networks under EU MDR traceability mandates. Long-term viability favors compounder-molder networks with captive resin allocation and dual-continent manufacturing footprints; watch for inflection signals in gamma-irradiation capacity utilization rates as ethylene oxide alternatives revalidate.
| Strategic Initiative | Industry Significance |
|---|---|
| Gamma-Stable Polymer Development | Terminal sterilization without ethylene oxide residue concerns meets FDA guidance timelines. |
| Mexican Manufacturing Expansion | Nearshoring capacity reduces freight exposure for US diagnostic instrument OEM procurement. |
| RFID-Enabled Vial Integration | EU MDR device-level serialization mandates expand addressable market in European networks. |
| REACH-Compliant Reformulation | German chemical suppliers lead medical-grade polypropylene transitions ahead of ECHA deadlines. |
| Biorepository Partnership Certification | Twenty-year retention protocol validation secures premium positioning in cryopreservation infrastructure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with GPO contracts managers, biomedical engineers at academic medical centers, diagnostic instrument OEM procurement leads, and regulatory affairs specialists at container manufacturers with secondary validation against FDA 510(k) filings, EMA medical device registrations, hospital procurement databases, and customs trade records. Bottom-up volume modeling from individual product categories triangulated against top-down industry sizing from polymer resin consumption data.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling spanning container type, material grade tier, sterilization protocol, and regional regulatory cluster. CAGRs derived from instrument upgrade cycle timing, biobank retention protocol standardization, and hospital procurement contract renewal patterns, incorporating cryopreservation infrastructure investment pipelines and REACH compliance transition timelines as industry-specific demand drivers.
The model assumes a particular technology adoption path; alternative pathways for gamma-irradiation sterilization scale-up versus ethylene oxide retention would alter the outlook for polymer formulation requirements and facility capital deployment. Forecasts reflect assumptions around FDA guidance implementation pacing and Chinese petrochemical capacity expansion that could revise supplier pricing leverage. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Foam Containers Market
Containers
Hinged Deli Containers Market
Containers
Spout Containers Market
Containers
Carboy Market
Containers
HDPE Containers Market
Containers
ISO Container Market
Containers
LDPE Containers Market
Containers
Chest-Style Insulated Containers Market
Containers
Half Height Containers Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Containerboard Market
Containers
Square Pails Market
Containers
Bulk Container Packaging Market
Containers
Car Lube Container Market
Containers
Hinged Lid Compostable Container Market
Containers
Jug Shipper Market