
 Chest-Style Insulated Containers Market | 2026-2036
Chest-Style Insulated Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Chest-Style Insulated Containers Market Analysis
The EU F-Gas Regulation is recalibrating material specifications across European cold chain packaging, compelling manufacturers to reformulate insulation chemistries. Pelican Biothermal leverages advanced phase-change material integration to sustain temperature integrity in pharmaceutical lanes. VA-Q-tec anchors its position through vacuum-insulated panel dominance in ultra-low-temperature shipments. Sonoco Products Company competes on manufacturing scale, operating multi-continent production networks that reduce lead times for bulk container orders.
Chest-style insulated containers are rigid, top-opening thermal enclosures engineered with polyurethane foam, vacuum-insulated panels, or polyethylene walls to maintain stable internal temperatures for perishable cargo, typically achieving 48–120 hour protection windows depending on payload and ambient conditions. The food storage container segment leads volume shipments, serving supermarket replenishment and catering logistics where cost efficiency outweighs extreme-duration performance. Beverage chests represent the fastest-growing category, as event planners and outdoor hospitality operators prioritize portable, high-capacity cooling for extended off-grid service. Foam-based insulation occupies the largest material share by unit economics, though polyethylene formulations are gaining ground in reusable circular-economy programs.
The EPA regulates refrigerant emissions in insulated equipment manufacturing under Section 608 of the Clean Air Act, while the EU Green Deal and REACH framework restrict chemical inputs in foam blowing agents and surface coatings. FDA validation requirements for pharmaceutical cold chain containers shape product testing protocols and documentation burdens for suppliers targeting healthcare logistics. Stakeholders must monitor evolving refrigerant-phase-down schedules and material substitution timelines to align R&D pipelines with compliance deadlines.
Market Dynamics
The EU F-Gas Regulation is forcing a wholesale material transition in insulation chemistry, compelling manufacturers to abandon hydrofluorocarbon-based polyurethane foams and requalify vacuum-insulated panels and alternative blowing agents for pharmaceutical cold chain certification.
Growth Catalysts
- Pharmaceutical cold chain expansion:mRNA vaccine distribution protocols now mandate validated thermal protection windows exceeding 96 hours, expanding procurement of premium chest-style containers by biopharma logistics operators in Germany and Switzerland.
- REACH framework compliance:The EU's chemical restriction regime is accelerating substitution toward pentane-blown and water-blown polyurethane formulations, creating first-mover advantages for foam suppliers with certified alternative chemistries.
- Outdoor hospitality recovery:Event planners and catering operators across France and Italy are expanding refrigerated container fleets for off-grid beverage service, driving demand for high-capacity polyethylene-walled chests with rapid-access lid designs.
Market Restraints
- Raw material concentration:Polyol and isocyanate feedstock production clusters in the US Gulf Coast and China's Shandong province expose European manufacturers to freight cost volatility and supply disruption.
- Technical qualification barriers:FDA thermal validation protocols for pharmaceutical containers require 12-18 month stability testing cycles, freezing out smaller suppliers lacking capitalized quality infrastructure.
- Substitute pressure from flexible solutions:High-performance insulated pallet shippers with equivalent duration ratings are capturing mid-volume pharmaceutical lanes where rigidity offers no handling advantage.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Norway lack domestic precision manufacturing clusters for ultra-low-temperature containers, creating import substitution potential for German and Dutch suppliers with vacuum-insulated panel expertise.
- Circular-economy service models:Reverse logistics networks for reusable polyethylene chests are displacing single-use expanded polystyrene in supermarket fresh-produce replenishment, with pooling operators capturing container-as-a-service revenue streams.
- EU Green Deal procurement mandates:Public-sector catering contracts in Denmark and the Netherlands now specify recycled-content thresholds, rewarding manufacturers with closed-loop material certification.
Industry Challenges
- Thermal modeling talent scarcity:Computational fluid dynamics specialists capable of optimizing multi-material wall assemblies command premium salaries, constraining R&D throughput at mid-tier manufacturers.
- Legacy fleet interoperability:Pharmaceutical distributors operate mixed container populations with incompatible data-logger interfaces, complicating temperature excursion traceability across supplier boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chest-Style Insulated Containers Market |
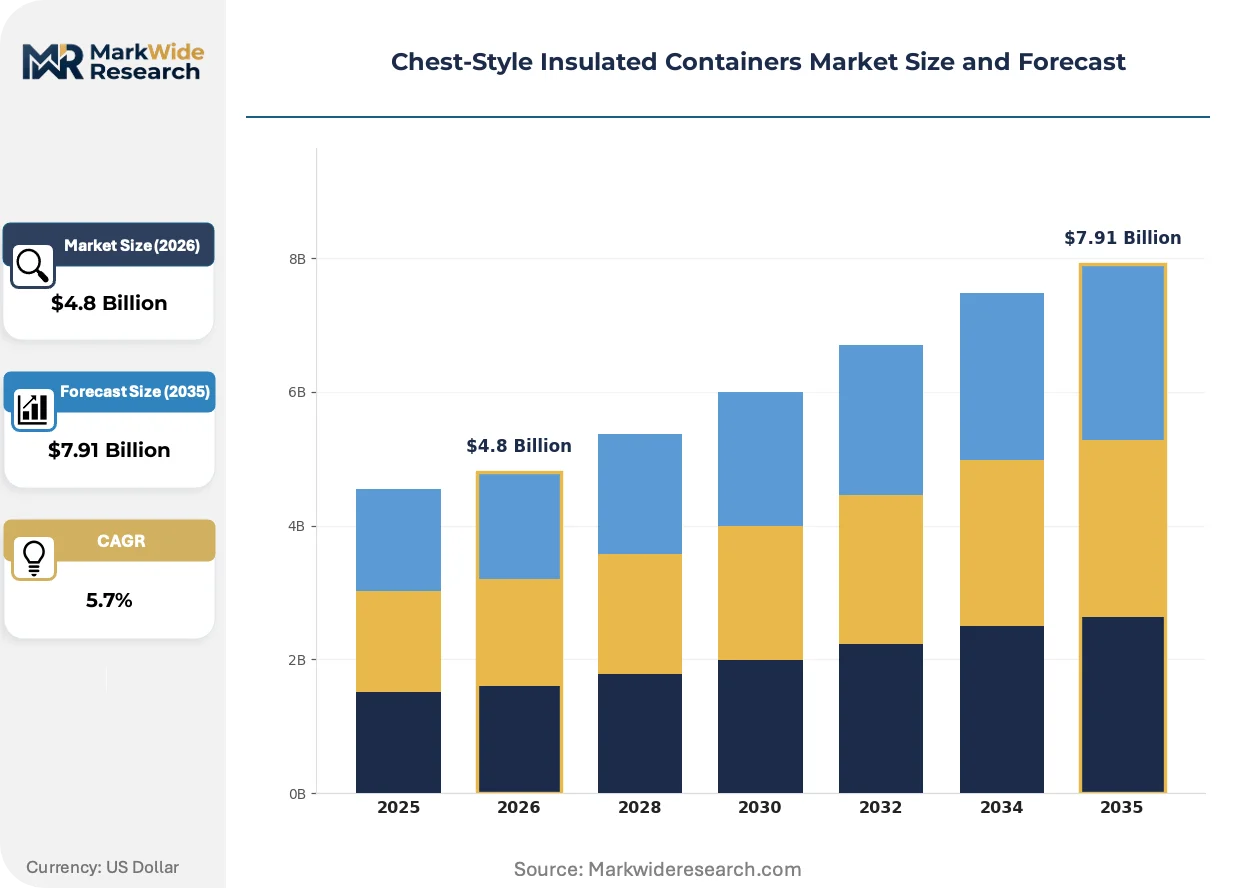
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coolers, Beverage Chests, Food Storage Containers, Ice Chests Material: Polyethylene, Stainless Steel, Aluminum, Foam End User: Outdoor Enthusiasts, Event Planners, Supermarkets, Catering Services Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Sonoco Products Company, Cold Chain Technologies, Pelican Biothermal, Snyder Industries, Saeplast, Creopack, Sofrigram, Inmark Packaging, VA-Q-tec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chest-Style Insulated Containers Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to redefine performance benchmarks, with insulation technologies and validation protocols evolving faster than procurement cycles can absorb.
Vacuum-insulated panel technology is electrifying ultra-low-temperature pharmaceutical logistics. These panels achieve thermal conductivity below 0.004 W/m·K, enabling 120-hour protection in sub-70°C lanes. German biopharma distributors are specifying VIP-dominant wall assemblies for cell therapy shipments. The technology is electrifying competitive positioning, compressing qualification timelines for foam-dependent alternatives.
REACH restrictions on methylene diphenyl diisocyanate exposure limits are tightening occupational safety protocols in European foam manufacturing. The regulation mandates enhanced ventilation and personal protective equipment standards in production facilities. Small-batch custom container shops in Italy and Spain face disproportionate compliance costs, accelerating consolidation toward scaled producers with capitalized safety infrastructure.
Hospital pharmacy buyers are unbundling container procurement from integrated cold chain service contracts. Large health systems in France and the UK now source validated containers directly from manufacturers while contracting separately for lane-risk management and temperature monitoring. This disintermediation is most visible in oncology biologics distribution, where procurement teams seek transparent unit economics for capital equipment versus per-shipment service fees.
Chest-Style Insulated Containers Market Segmentation
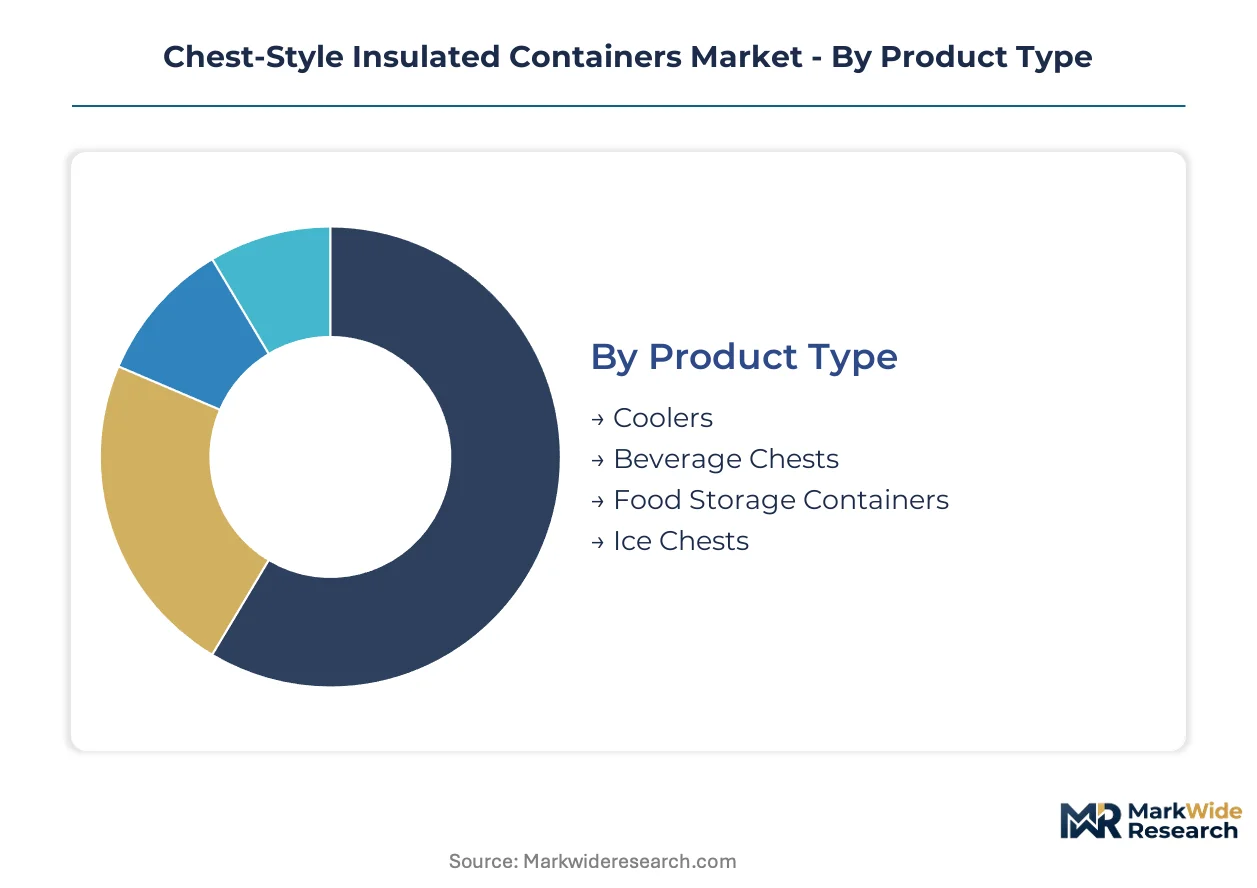
Chest-style insulated containers fragment across four distinct category axes that determine procurement priorities, thermal performance specifications, and margin structures. Buyers in pharmaceutical logistics prioritize material certification and validation documentation over unit economics, while outdoor hospitality operators optimize for access speed and transportability.
Product Type:
Outdoor hospitality buyers and pharmaceutical distributors diverge sharply in their product selection criteria, with the former prioritizing lid geometry and rapid access while the latter demand validated thermal duration windows.
- Food Storage Containers:Rigid polyurethane-foam enclosures engineered for 48–96 hour temperature stability in fresh-produce replenishment cycles. German supermarket chains and Swiss pharmaceutical distributors anchor procurement volumes, driven by EU Green Deal mandates for reusable packaging in public-sector catering contracts.
- Beverage Chests:High-capacity polyethylene-walled units with rapid-access lid designs optimized for off-grid event service. French and Italian event planners are expanding fleet procurement for outdoor hospitality recovery, prioritizing portability over extreme-duration performance.
- Coolers:General-purpose thermal enclosures serving recreational and light commercial applications with standard 24–48 hour protection windows.
- Ice Chests:Traditional top-opening designs retaining dominance in price-sensitive consumer channels and emergency relief logistics.
Volume sits with Food Storage Containers; growth tilts toward Beverage Chests.
Material:
Material selection in this market directly tracks regulatory chemistry restrictions and end-use thermal qualification requirements rather than raw cost optimization.
- Foam:Polyurethane formulations dominate unit economics across supermarket replenishment and catering logistics, though EU F-Gas Regulation phase-downs are forcing rapid substitution toward pentane-blown and water-blown alternatives. REACH compliance timelines favor suppliers with certified alternative chemistries.
- Polyethylene:Reusable wall systems gaining share in circular-economy programs, particularly where Danish and Dutch public-sector contracts specify recycled-content thresholds.
- Stainless Steel:Premium-grade enclosures serving healthcare and laboratory applications requiring sterilization compatibility and structural durability.
- Aluminum:Lightweight structural components in hybrid wall assemblies, constrained by thermal bridging challenges in ultra-low-temperature lanes.
Foam retains the installed base; polyethylene climbs the fastest on sustainability procurement mandates.
End User:
End-user segmentation reveals a bifurcation between validated cold chain requirements and recreational utility optimization.
- Supermarkets:High-volume procurement of reusable polyethylene chests for fresh-produce replenishment, with pooling operators capturing container-as-a-service revenue streams. German precision manufacturing clusters supply dominant share.
- Event Planners:Rapid fleet expansion across France and Italy for off-grid beverage service, favoring high-capacity designs with rapid-access geometries.
- Outdoor Enthusiasts:Consumer-channel demand concentrated in recreational coolers and ice chests with standard durability ratings.
- Catering Services:Mid-tier volume procurement balancing transportability with food safety compliance in mobile service applications.
Supermarkets anchor procurement scale; Event Planners show steepest expansion trajectory.
Capacity:
Capacity selection correlates with payload density requirements and handling infrastructure across pharmaceutical and food service logistics.
- Large:Standard specification for pharmaceutical distribution lanes requiring 96+ hour thermal protection with integrated data-logger accommodation. German biopharma logistics operators specify this tier for cell therapy shipments.
- Medium:Versatile format serving catering replenishment and mid-volume pharmaceutical lanes where flexible pallet shippers compete on equivalent duration ratings.
- Small:Compact formats for last-mile courier delivery and individual patient-directed shipments in oncology biologics distribution.
- Extra Large:Bulk container specifications for supermarket distribution center replenishment and event-scale beverage service.
Large capacity commands premium positioning; Medium capacity faces greatest substitute pressure from flexible alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany's precision manufacturing clusters while consumption spreads across pharmaceutical distribution hubs and outdoor hospitality markets. The EU F-Gas Regulation drives material substitution uniformly, though national implementation timelines diverge. Cold chain infrastructure investments track biopharma manufacturing density and supermarket consolidation patterns.
Germany
Biopharma logistics operators in Frankfurt and Munich procure premium vacuum-insulated containers for cell therapy shipments exceeding 96-hour protection windows. The country's Federal Environment Agency enforces accelerated hydrofluorocarbon phase-down schedules under EU F-Gas Regulation implementation. Precision manufacturing clusters in Baden-Württemberg supply vacuum-insulated panel assemblies to Swiss and Nordic distributors.
Switzerland
Swissmedic validation requirements shape procurement protocols for oncology biologics distribution across Basel and Zurich pharmaceutical hubs. The country's chemical ordinance restricts methylene diphenyl diisocyanate exposure limits in foam manufacturing operations. Geneva-based logistics providers source large-capacity containers for international cell therapy export lanes.
France
Event planners in Provence-Alpes-Côte d'Azur and Île-de-France expand polyethylene-walled beverage chest fleets for outdoor hospitality recovery. ANSM pharmaceutical regulations mandate thermal validation documentation for hospital pharmacy direct procurement. Lyon-based catering operators pilot container-as-a-service pooling models for supermarket fresh-produce replenishment.
Netherlands
Public-sector catering contracts in Randstad municipalities specify recycled-content thresholds for reusable polyethylene containers. The country's National Institute for Public Health and the Environment coordinates REACH compliance timelines for pentane-blown foam alternatives. Rotterdam distribution hubs consolidate cross-border pharmaceutical container pooling networks serving Belgium and Denmark.
Italy
Catering services in Lombardy and Emilia-Romagna balance transportability with food safety compliance for mobile hospitality applications. The country's Ministry of Health enforces EU Green Deal procurement mandates in public hospital food service contracts. Small-batch custom container shops in Veneto face disproportionate REACH compliance costs, accelerating consolidation toward scaled producers.
Chest-Style Insulated Containers Market Vendor Landscape
The competitive structure tilts toward specialization-driven differentiation rather than scale consolidation. Tier-one suppliers dominate pharmaceutical validation lanes with certified thermal performance documentation, while regional fabricators capture outdoor hospitality and food service volumes through rapid-access lid geometries and circular-economy service models. Three archetypes define positioning: vacuum-insulated panel specialists, multi-material scale manufacturers, and reusable polyethylene pooling operators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing feedstock access and qualification laboratory capacity.
Within the pharmaceutical-specialist tier, Pelican Biothermal and VA-Q-tec exemplify divergent insulation technology pathways, with the former representing advanced phase-change material integration and the latter anchoring vacuum-insulated panel dominance in ultra-low-temperature shipments. Sonoco Products Company occupies a position among multi-continent scale manufacturers, leveraging production network breadth to compress lead times for bulk container orders. Cold Chain Technologies sits within the validation-intensive healthcare logistics segment, where FDA thermal qualification protocols create sustained barriers to entry.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Cold Chain Technologies |
| Pelican Biothermal |
| Snyder Industries |
| Saeplast |
| Creopack |
| Sofrigram |
| Inmark Packaging |
| VA-Q-tec |
| Others |
Supply Flow & Price Mechanics
Backward integration into polyol and isocyanate feedstock production anchors pricing power for German precision manufacturers serving pharmaceutical cold chain lanes, while outsourced foam-blowing agent procurement exposes mid-tier Italian fabricators to REACH compliance cost volatility.
Pricing Analysis
Cost-down pressure on standard foam-based containers accelerates because REACH-mandated methylene diphenyl diisocyanate exposure limits force facility upgrades. Three-tier pricing structure across premium VIP-dominant, standard polyurethane-foam, and economy polyethylene tiers separates validated pharmaceutical certification from recreational utility. Price differentiation hinges on FDA thermal validation documentation and volume procurement scale. Supermarket replenishment buyers exhibit highest price sensitivity; biopharma logistics operators in Germany and Switzerland demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Single-source vulnerability sits with polyol production clusters in the US Gulf Coast and isocyanate manufacturing concentration in China's Shandong province. Raw material procurement draws from petrochemical feedstocks, blowing agent formulations, and vacuum-insulated panel core materials. Supply chain risk centers on freight cost volatility from transoceanic raw material movements. Distribution runs through precision manufacturing clusters in Baden-Württemberg, Rotterdam consolidation hubs, and Swissmedic-validated logistics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around qualified thermal validation laboratories prop pricing premiums for certified container manufacturers, creating durable margin structures for incumbents with capitalized quality infrastructure.
For Market Incumbents: Hedge against flexible pallet shipper substitution by deepening phase-change material integration and securing captive vacuum-insulated panel supply agreements. Expand qualification laboratory capacity in Germany to compress FDA stability testing cycles for pharmaceutical clients. Fortify position through backward integration into pentane-blown foam chemistry certification ahead of EU F-Gas Regulation phase-down deadlines. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for alternative insulation chemistry specialists to capture share from HFC-dependent legacy producers. Target Nordic markets in Sweden and Norway where domestic precision manufacturing gaps create import substitution demand for ultra-low-temperature containers. Pursue circular-economy service models with container-as-a-service pooling networks for Danish and Dutch public-sector catering contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multi-material scale manufacturers seeking pharmaceutical validation credentials. Long-term viability favors suppliers with integrated thermal modeling capabilities and REACH-certified foam chemistry portfolios. Watch for inflection signals in biopharma mRNA vaccine distribution protocol changes extending thermal protection window requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Qualification laboratory buildout in Germany compresses FDA thermal validation timelines for pharmaceutical clients. |
| Backward Integration | Captive polyol and isocyanate supply secures margin stability against US Gulf Coast feedstock volatility. |
| Green Manufacturing Transition | Pentane-blown and water-blown foam chemistry certification aligns with EU F-Gas Regulation phase-down schedules. |
| Long-term Supply Agreement | Multi-year container procurement contracts with Swiss biopharma distributors lock in premium pricing tiers. |
| Joint Venture | Pooling operator partnerships in Netherlands and Denmark accelerate circular-economy service model deployment. |
Methodological Framework
Document review covered customs and trade flow databases, EU regulatory filings, and pharmaceutical cold chain validation standards, complemented by interviews with container manufacturing executives, biopharma logistics procurement directors, foam chemistry R&D leads, and supermarket replenishment category managers. Secondary sources included ECHA REACH compliance documentation, FDA thermal validation protocols, and German Federal Environment Agency enforcement schedules. Bottom-up demand modeling triangulated against top-down market sizing across material chemistry and end-use segments.
Segment-level outputs across product type, insulation material, end-user category, and capacity tier were generated through the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns and regulatory compliance timeline impacts. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down schedules and mRNA vaccine distribution protocol evolution.
Caveats apply where REACH enforcement intensity or biopharma cold chain protocol changes could materially shift the outlook. Forecasts reflect assumptions around raw material supply continuity and qualification laboratory capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Americas Container Technology Market
Containers
Club Store Packaging Tray Market
Containers
Global Multi Pack Carriers Market
Containers
Corrugated Bin Boxes Market
Containers
Stainless Steel Cask Market
Containers
Oblong Tub Lids Market
Containers
Carboy Market
Containers
Kuwait Container Glass Market
Containers
Trigger Sprayer Market
Containers
Hinged Lid Tins Market
Containers
Collapsible Sleeve Containers Market
Containers
Laminated Bulk Bins Market
Containers
Tottle Containers Market
Containers
Twist Up Stick Container Market
Containers
Stock Clamshell Packaging Market
Containers
Compartment Take-Out Container Market