
 Half Height Containers Market | 2026-2036
Half Height Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Half Height Containers Market Foresight
Chinese steel-fabrication clusters is expanding their half-height container output to serve rising bulk-commodity flows across Central Asian rail corridors. CIMC leverages integrated mill-to-yard production economics to dominate domestic tendering for mineral-grade units. Hoover Ferguson Group anchors its position through specialized offshore-certified designs for oilfield waste containment. Triton International Limited sustains fleet renewal velocity across European leasing pools with standardized 2-ton and 3-ton configurations.
Half height containers are enclosed or open-top rectangular shipping units measuring approximately half the vertical profile of standard ISO containers, typically fabricated from corten steel or marine-grade aluminum with reinforced corner castings and locking bars to secure bulk payloads during multimodal transit. Their reduced cubic volume optimizes weight-based freight economics for dense cargoes including ores, scrap metal, and construction aggregates. Steel product types command the dominant share of current manufacturing volumes due to their impact resistance and repairability, though aluminum variants are gaining share in weight-sensitive aviation-linked logistics chains. The 2-ton and 3-ton capacity brackets capture the majority of replacement demand, while 4-ton units attract premium positioning in heavy mineral and chemical transport applications.
The International Maritime Organization enforces structural safety standards through the Convention for Safe Containers, which mandates periodic inspection regimes and maximum gross weight certifications that directly influence half-height design specifications and market access conditions. ISO 668 and ISO 1496 establish dimensional and testing protocols that manufacturers must satisfy for international interchange eligibility. Stakeholders should monitor evolving EU Green Deal requirements for embodied carbon disclosure in steel-intensive transport equipment, as these frameworks will increasingly filter procurement criteria across European logistics networks.
Market Dynamics
The International Maritime Organization's container safety certification amendments are compressing production timelines and raising capital requirements for new half-height container entrants, favoring incumbent fabricators with established testing protocols.
Growth Catalysts
- Bulk commodity density optimization:Mineral and chemical transport operators across Germany's Rhine-Ruhr corridor are expanding half-height fleet orders to maximize payload on weight-restricted barge-rail intermodal routes.
- ISO 1496 structural testing harmonization:Standardized international interchange eligibility is reducing certification friction for manufacturers serving Central Asian rail corridors.
- Corten steel fabrication clusters:Integrated mill-to-yard production economics in Chinese manufacturing zones are compressing unit costs for mineral-grade container output.
Market Restraints
- Steel input cost volatility:Corten steel plate prices fluctuate with scrap metal and iron ore indices, compressing fabrication margins during commodity spikes.
- Offshore certification concentration:Oilfield waste containment units require specialized American Bureau of Shipping or DNV certification, limiting supplier pools to established maritime fabricators.
- Standard ISO container substitution:Dense cargo shippers in non-weight-constrained lanes can deploy conventional containers at lower per-unit lease rates.
Strategic Opportunities
- Aviation-linked logistics chains:Aluminum half-height variants are penetrating air cargo ground handling for weight-sensitive pharmaceutical and electronics freight.
- EU Green Deal embodied carbon disclosure:Procurement criteria across European logistics networks will favor fabricators with verified low-carbon steel sourcing.
- Digital fleet tracking convergence:Integration of IoT weight sensors and telematics platforms is creating subscription revenue streams for container lessors.
Industry Challenges
- Welding certification timelines:Marine-grade corten fabrication requires specialized ASME or Lloyd's Register welder qualifications, extending workforce onboarding cycles.
- Corner casting supply reconfiguration:ISO 1161 compliant castings concentrate in foundry clusters, creating vulnerability during logistics disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Half Height Containers Market |
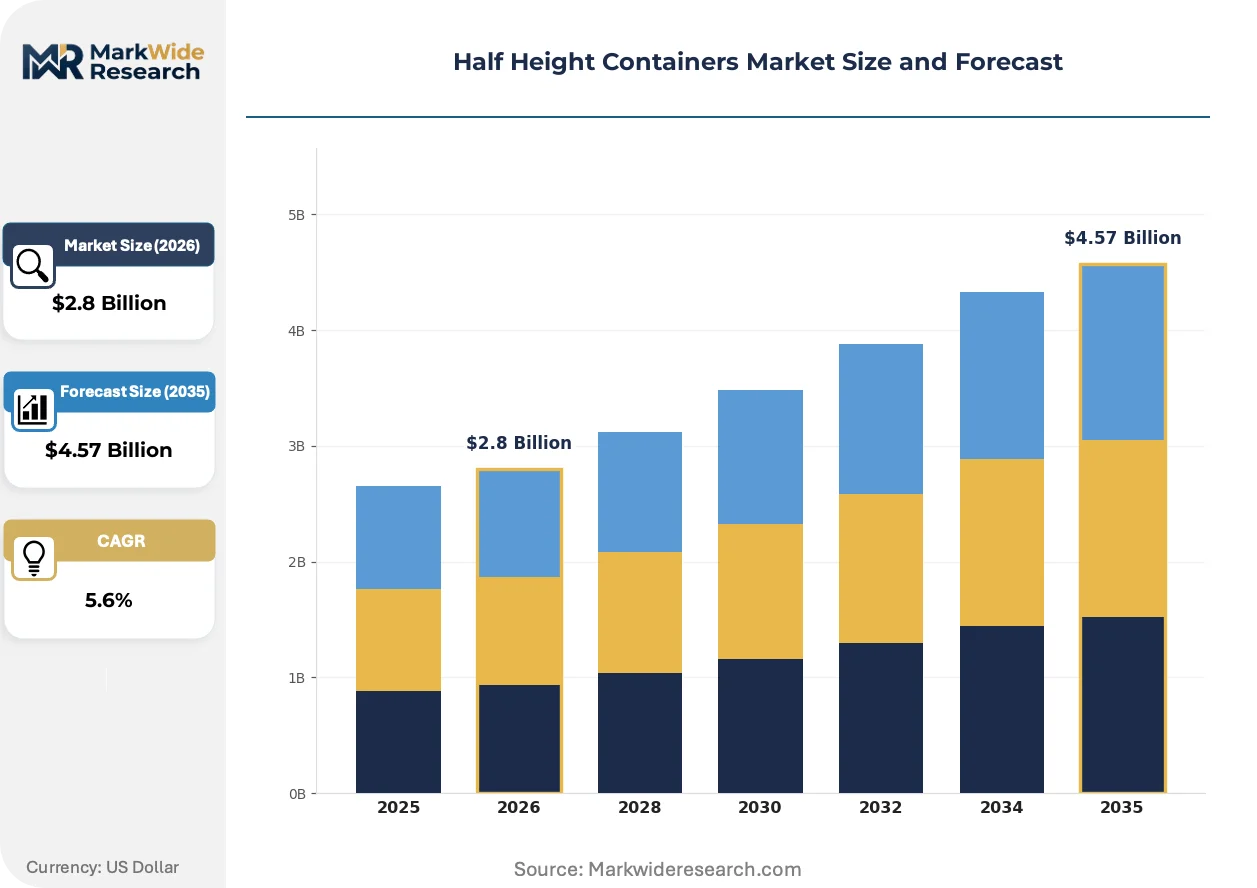
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Plastic, Aluminium, Composite Application: Shipping, Storage, Transport, Logistics Capacity: 1 Ton, 2 Tons, 3 Tons, 4 Tons Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Maersk Container Industry, CIMC, Hoover Ferguson Group, Singamas Container Holdings, TLS Offshore Containers, Triton International Limited, Textainer Group Holdings Limited, Sea Box, Inc., W&K Containers, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Half Height Containers Market Shifts & Advancements
Material substitution and regulatory disclosure requirements are actively reshaping competitive positioning in half-height container fabrication. Fabricators are racing to certify lower-carbon product variants ahead of procurement mandate deadlines.
Marine-grade aluminum alloys are expanding into weight-sensitive aviation ground handling and pharmaceutical cold chain applications. European air cargo operators are trialing 2-ton aluminum units for dense battery and electronics freight. This substitution is compressing the traditional steel-dominant product mix in premium logistics segments.
EU Green Deal embodied carbon disclosure frameworks are mandating lifecycle emissions documentation for steel-intensive transport equipment. German and Dutch logistics procurement departments are inserting carbon thresholds into container tender specifications. Fabricators with integrated electric-arc furnace steel sourcing are securing preferential contract terms.
Leasing pool operators are unbundling maintenance and telematics services from base rental contracts. European mineral transport fleets are adopting usage-based service agreements with embedded weight monitoring. This restructuring is most visible in Germany's Rhine-Ruhr industrial corridor, where barge-rail operators prioritize predictive maintenance coverage over capital ownership.
Half Height Containers Market Segmentation
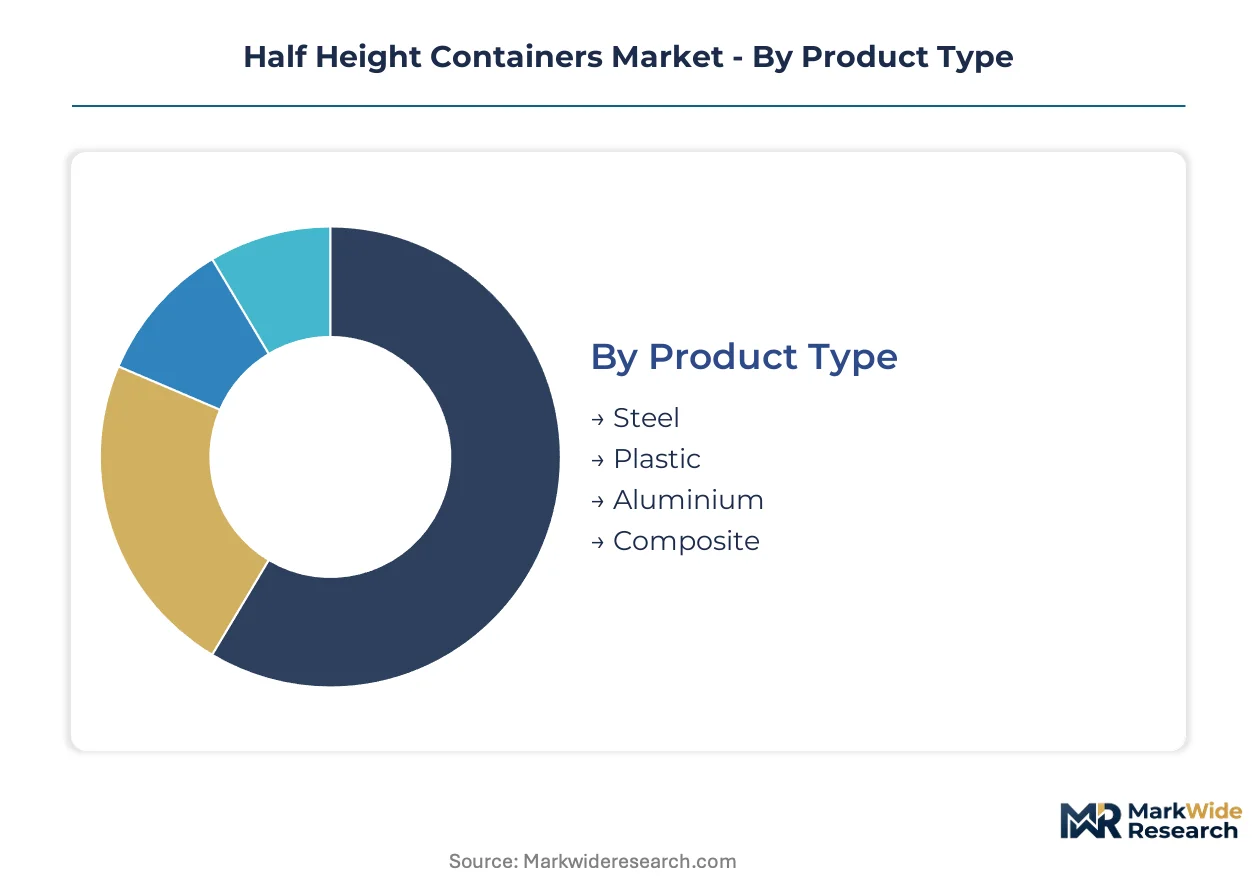
Half-height container procurement patterns diverge sharply across material grades, payload specifications, and channel structures. Fabricators optimize production lines around distinct cost-performance tiers while logistics operators match container specifications to modal constraints and cargo density profiles.
Product Type:
Fabrication capacity clusters heavily around integrated steel mill zones in China and Germany, with secondary concentrations serving specialized aluminum and composite demand.
- Steel:Corten steel plate construction delivers impact resistance and field repairability for mineral and aggregate transport. Rhine-Ruhr barge operators specify steel units for heavy ore flows where weight restrictions favor dense payload optimization over cubic efficiency.
- Aluminium:Marine-grade aluminum alloys reduce tare weight by approximately one-third versus steel equivalents. Air cargo ground handlers in Frankfurt and Amsterdam are adopting 2-ton aluminum variants for dense battery and electronics freight where every kilogram of tare reduction translates to payload recovery.
- Plastic:Polyethylene and polypropylene rotational-molded units serve corrosive chemical containment and food-grade agricultural applications. These variants dominate niche cold-chain buffer storage where rust prevention outweighs structural load requirements.
- Composite:Fiber-reinforced polymer constructions blend glass or carbon fiber with thermoset resins for extreme weight-sensitive deployments. Offshore oilfield waste containment in the North Sea utilizes composite half-heights to minimize crane load limits during platform supply runs.
Steel absorbs the bulk of installed capacity; aluminum is expanding most quickly.
Application:
End-use segmentation tracks modal specialization and custody transfer points across intermodal networks.
- Shipping:Maritime-certified units for vessel-borne containerized bulk cargo. ISO 1496 structural testing mandates govern corner casting specifications and stacking load ratings for ocean-going interchange eligibility.
- Storage:Static depot and yard-based containment for inventory buffering and seasonal agricultural holding. German chemical distributors deploy dedicated storage pools for fertilizer and feed additive staging.
- Transport:Road-rail-barge multimodal movement of construction aggregates, scrap metal, and dense industrial inputs. Weight-bridge optimization drives specification choices on constrained European inland waterways.
- Logistics:Integrated supply chain coordination including empty repositioning, maintenance pooling, and telematics-enabled fleet management. Leasing operators unbundle asset ownership from usage-based service agreements.
Transport commands the dominant share of annual unit demand; logistics services are climbing the fastest as operators shift from ownership to subscription models.
Capacity:
Payload specification segmentation aligns with equipment substitution economics and regulatory weight enforcement intensity.
- 1 Ton:Light-duty units for retail agricultural supply and urban construction material delivery. These configurations suit last-mile truck routes with stringent axle load limits.
- 2 Tons:The workhorse specification for European intermodal mineral transport. Standardized 2-ton units dominate Rhine-Ruhr barge-rail transfer volumes where payload density optimization meets infrastructure weight constraints.
- 3 Tons:Heavy industrial applications including chemical feedstock and processed mineral movement. German chemical producers specify 3-ton units for dense powder and pellet transport.
- 4 Tons:Premium heavy-mineral and bulk chemical segments requiring specialized chassis and lifting equipment. These units attract premium lease rates on dedicated heavy-haul corridors.
2-ton configurations anchor replacement demand volumes; 4-ton units are gaining share fastest in premium heavy-chemical applications.
Distribution Channel:
Channel structure reflects capital ownership preferences and service bundling sophistication across customer tiers.
- Direct Sales:Large fleet operators contract directly with fabricators for batch orders with customized specifications. German mineral transport consortia utilize direct procurement to secure dedicated production slots.
- Retail:Small-lot sales through equipment dealers and agricultural supply cooperatives. These transactions serve replacement demand from independent construction and farming operators.
- Online:Digital platforms for standardized specification comparison and spot procurement. European leasing aggregators are building digital marketplaces for secondary market unit trading.
- Wholesalers:Inventory stocking intermediaries serving regional equipment dealers and maintenance depots. Wholesalers concentrate in Rotterdam and Hamburg port zones to support North Sea coastal demand.
Direct sales capture the majority of new-build volume; online channels are expanding most quickly as fleet digitization accelerates procurement transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corten steel plate fabrication clusters in Shandong Province and the Rhine-Ruhr corridor anchor half-height container production economics. These raw-material localities shape regional competitive positioning through integrated mill-to-yard supply chains.
China
Central Asian rail corridors drive fleet expansion for mineral-grade units. MIIT enforces GB standards for structural safety certification. Shandong Peninsula fabricators exploit captive steel supply to dominate tendering for bulk-commodity containers.
Germany
Rhine-Ruhr barge-rail transfer volumes concentrate demand for 2-ton and 3-ton configurations. KBA coordinates with EU Green Deal frameworks on embodied carbon disclosure for steel-intensive equipment. Duisburg and Dortmund logistics depots prioritize predictive maintenance contracts over asset ownership.
United States
Gulf Coast chemical transport operators expand half-height leasing for dense feedstock movement. EPA regulations on hazardous material containment influence specification requirements. Houston and Corpus Christi port zones attract offshore-certified fabricators serving oilfield waste applications.
Netherlands
Rotterdam port throughput drives storage and transshipment demand for standardized units. REACH compliance mandates shape chemical-grade container procurement criteria. Randstad logistics operators trial aluminum variants for aviation-linked pharmaceutical freight.
United Arab Emirates
Jebel Ali port expansion supports regional mineral re-export flows. MOHAP guidelines on hazardous cargo handling filter into container safety specifications. Dubai logistics free zones attract leasing operators building telematics-enabled fleet management platforms.
Half Height Containers Market Competitive Landscape
Global majors compete with regional champions across certification depth and material specialization. The vendor base stratifies into three tiers: integrated steel-mill fabricators with captive raw-material access, maritime-certified specialists serving offshore applications, and leasing operators unbundling asset ownership from service contracts. Dominant competitive moves include backward integration into corten steel plate supply and geographic expansion through port-zone maintenance depot networks.
Within the integrated-fabricator tier, CIMC and Maersk Container Industry exemplify scale-driven production economics. Among leasing specialists, Triton International Limited occupies a position emphasizing fleet renewal velocity across European pools. Hoover Ferguson Group represents the offshore-certification archetype, anchoring its market presence through specialized designs for oilfield waste containment applications.
| Leading Market Players |
|---|
| Maersk Container Industry |
| CIMC |
| Hoover Ferguson Group |
| Singamas Container Holdings |
| TLS Offshore Containers |
| Triton International Limited |
| Textainer Group Holdings Limited |
| Sea Box, Inc. |
| W&K Containers, Inc. |
| Others |
Supply & Pricing Matrix
Specialized ASME-certified welder pools in Shandong Province and the Rhine-Ruhr corridor create labor-cost differentials that widen pricing-tier spreads between premium ISO-certified units and economy-grade domestic-only containers. Fabricators with captive welding certification programs command premium positioning while uncertified competitors compete on spot-price terms.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium lease rates from bare-metal transactional pricing in European mineral transport pools. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 1496 certification grade and corner-casting provenance. Pricing pressure stems from corten steel plate volatility compressing fabrication margins during iron ore spikes. Small agricultural cooperatives exhibit highest price sensitivity; Rhine-Ruhr barge consortia prioritize total-cost-of-ownership over unit acquisition cost.
Supply Chain Analysis
EU Green Deal local-content rules for embodied carbon disclosure are reshaping sourcing toward electric-arc furnace steel within European Economic Area boundaries. Corten steel plate supply concentrates in China, Germany, and South Korea; corner castings feed from ISO 1161-compliant foundry clusters in Italy and India. The supply chain rests on scrap metal and iron ore index volatility as primary raw material risk. Distribution runs through Rotterdam and Hamburg port-zone wholesaler networks serving North Sea coastal demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Half-height container fabrication is consolidating around ISO certification depth and captive steel supply, with IMO safety amendments forcing sub-scale fabricators toward exit or acquisition.
For Market Incumbents: To counter margin compression from steel input volatility, deepen backward integration into electric-arc furnace corten supply and secure dedicated production slots through multi-year Rhine-Ruhr barge operator contracts. Expand ASME welder certification programs to extend workforce moats against emerging Chinese competitors. For New Entrants and Emerging Players: The price-point gap between premium aluminum aviation-ground units and economy steel mineral containers creates white-space opportunity in 2-ton aluminum variants for Frankfurt and Amsterdam pharmaceutical logistics. Target air cargo ground handlers with tare-weight-sensitive battery freight specifications. Pursue digital marketplace aggregation for secondary market unit trading as go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors leasing operators with telematics-enabled fleet management platforms and established European maintenance depot networks. Long-term viability hinges on subscription revenue unbundling from asset ownership. Watch EU Green Deal procurement mandate enforcement intensity as inflection signal for low-carbon steel sourcing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corten Steel Supply | Captive electric-arc furnace sourcing secures preferential EU Green Deal contract terms from German logistics operators. |
| ASME Welder Certification Program Expansion | Specialized marine-grade fabrication qualifications extend production timelines that protect incumbent market positioning. |
| Telematics-Enabled Fleet Management Platform | IoT weight sensor integration creates recurring subscription revenue streams beyond base container rental rates. |
| Aluminum Variant Certification for Aviation Ground Handling | Marine-grade alloy validation opens Frankfurt and Amsterdam pharmaceutical cold chain replacement demand. |
| Rotterdam Port-Zone Maintenance Depot Network | Geographic clustering near North Sea throughput nodes captures predictive maintenance contract unbundling trends. |
Research Methodology
Trade flow databases, customs records, and ISO certification registries formed the secondary backbone, supplemented by structured interviews with container fleet managers, barge operator procurement leads, port authority logistics planners, and ASME welding certification program directors. Bottom-up unit shipment tallies and top-down steel consumption estimates were triangulated against leasing pool asset registers.
Bottom-up modeling tracked capacity-grade and material-type splits across the projection horizon, while top-down validation anchored against corten steel plate consumption indices and intermodal freight volume trends. CAGRs were derived from segmented replacement demand curves and fleet expansion patterns in Central Asian rail corridors. Mode-specific weight-bridge constraints and EU Green Deal procurement mandate timelines served as industry-specific forecast inputs.
Inputs from customs declarations and ISO certification audits were available through the study window; gaps in private leasing contract terms introduce uncertainty bands around subscription revenue projections. Forecasts reflect documented assumptions on steel price trajectory and regulatory enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Stack and Nest Containers Market
Containers
Multi-Layer Blow Molded Containers Market
Containers
North America Plastic Bottles and Containers Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
ISO Container Market
Containers
Feeder Containers Market
Containers
Asia and Africa Food Cans Market
Containers
Container Market
Containers
Square Pails Market
Containers
Dispensing Jug Market
Containers
Sanitary Cans Market
Containers
Collapsible Sleeve Containers Market
Containers
Single Wall Jars Market
Containers
Disposable Lids Market
Containers
Oblong Container Market
Containers
Club Store Packaging Tray Market