
 Hinged Deli Containers Market | 2026-2036
Hinged Deli Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Hinged Deli Containers Market Foresight
Platform licensing revenue from sustainable material formulations is reshaping how suppliers capture value in foodservice packaging. Pactiv Evergreen Inc. leverages its integrated manufacturing footprint across North American resin conversion. Dart Container Corporation anchors its position through proprietary foam-to-clear plastic technology transitions. Huhtamaki competes by extending its fiber-based packaging expertise into hinged formats for European quick-service chains.
Hinged deli containers are single-use food packaging units with an integrally molded lid attached by a flexible plastic hinge, typically manufactured through thermoforming or injection molding in polypropylene or polyethylene terephthalate, designed to preserve food freshness while enabling one-handed opening and secure reclosure. The product type dimension shows polypropylene variants dominating current volume while compostable grades claim expanding shelf space at premium price points. End user demand fragments across restaurants and food delivery services, with delivery platforms driving smaller-capacity SKUs optimized for portion control and thermal retention.
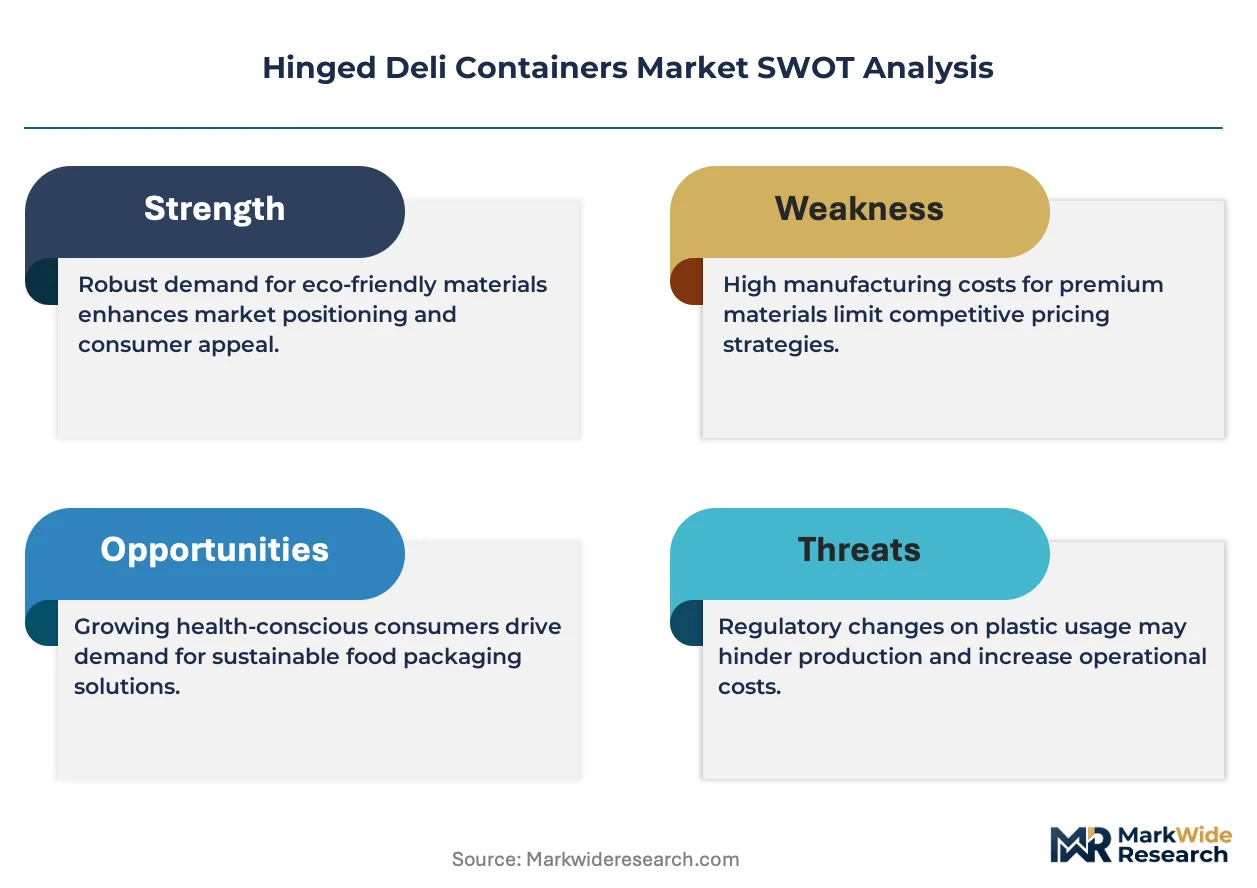
The FDA regulates direct food contact materials through 21 CFR requirements, while the EU REACH framework restricts Substances of Very High Concern in plastic additives, collectively elevating compliance costs for non-domestic suppliers entering either jurisdiction. State-level extended producer responsibility laws in California and Maine are adding layered obligations to packaging recovery systems. Stakeholders must monitor how biopolymer certification standards evolve to determine which material platforms warrant manufacturing commitment.
Market Dynamics
Food delivery platforms are compressing order-to-delivery windows, forcing container specifications toward thinner-gauge, faster-sealing formats that sacrifice durability for speed.
Growth Catalysts
- EU Single-Use Plastics Directive:The 2021 framework mandates phase-outs of expanded polystyrene food containers, redirecting procurement toward polypropylene and fiber-based hinged alternatives across quick-service chains.
- Quick-service restaurant automation:Kitchen robotics require standardized container geometries for automated filling and sealing, locking in hinged formats with precise dimensional tolerances.
- Compostable resin advances:PLA-PHA blends achieve heat-deflection temperatures above 100°C, enabling hot-fill applications previously restricted to petroleum-based polymers.
Market Restraints
- Propylene feedstock volatility:North American resin prices swing with cracker utilization rates, compressing margins for thin-wall thermoformers lacking long-term supply contracts.
- Recycling infrastructure gaps:Mixed-material hinged containers (polypropylene bases with PET lids) contaminate single-stream recovery, triggering landfill diversion penalties in jurisdictions with organics mandates.
- Fiber-based moisture barriers:Bio-based coatings fail at freezer-to-microwave transitions, limiting adoption in meal-kit segments requiring broad temperature tolerance.
Strategic Opportunities
- California SB 54 implementation:The state's extended producer responsibility law creates preferential procurement pathways for containers with 30%+ post-consumer recycled content, rewarding early compliance investments.
- Cloud kitchen densification:Ghost kitchen clusters in urban cores aggregate demand for standardized, stackable formats optimized for third-party logistics handoffs.
- Digital printing integration:Inline decoration during thermoforming enables lot-level traceability and dynamic branding without label adhesives that complicate recycling.
Industry Challenges
- Biopolymer certification timelines:BPI and TÜV OK compostability validations require 12-18 month testing cycles, delaying product launches behind formulation improvements.
- Legacy tooling amortization:Conventional thermoforming molds lack cooling channel designs for high-speed PLA crystallization, necessitating capital-intensive retooling for compostable grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hinged Deli Containers Market |
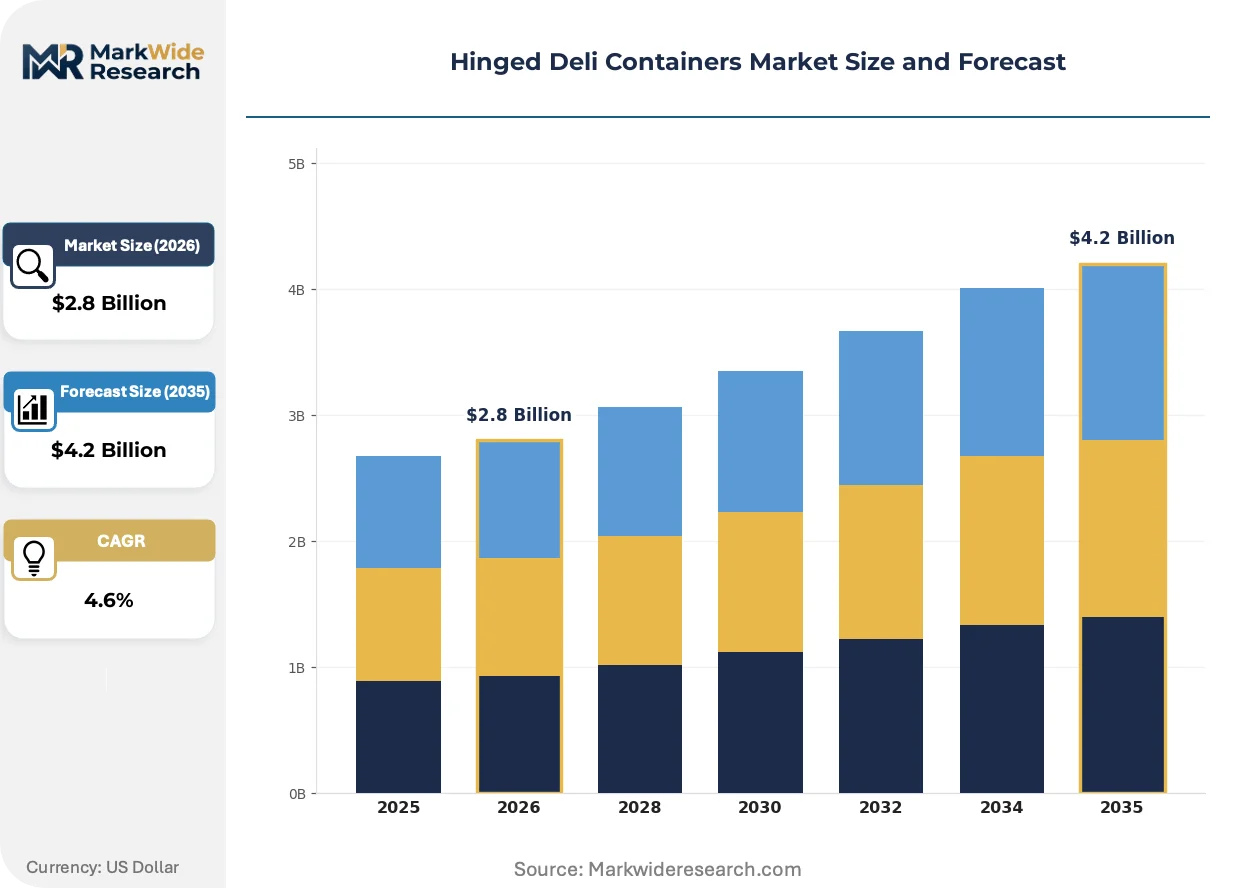
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Polypropylene, Compostable, Reusable End User: Restaurants, Catering Services, Retail Outlets, Food Delivery Services Capacity: Small, Medium, Large, Extra Large Closure Type: Snap-On, Secure Lid, Hinged, Locking |
| Companies Covered | Pactiv Evergreen Inc., Dart Container Corporation, Berry Global Group, Inc., Genpak LLC, Sabert Corporation, Amcor plc, Huhtamaki, Placon, Anchor Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hinged Deli Containers Market Shifts & Advancements
Material virtualization is collapsing the distinction between performance tiers, as digital specification tools let buyers simulate container behavior before physical sampling.
Thin-wall injection molding is virtualizing quality assurance workflows. Real-time cavity pressure sensors feed machine-learning models that predict dimensional drift before parts eject. Tier-one foodservice distributors are adopting these systems to reduce incoming inspection overhead. The technology is virtualizing traditional first-article approval processes that previously delayed supplier onboarding by weeks.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from fiber-based hinged containers. Manufacturers are pivoting to clay-based barrier treatments or switching entirely to polypropylene for oily prepared foods. German quick-service chains face the tightest compliance deadlines, accelerating reformulation timelines ahead of broader European enforcement.
Consolidated procurement through group purchasing organizations is fragmenting supplier relationships. Regional restaurant chains are surrendering specification authority to buying cooperatives that standardize on two-three container SKUs nationwide. This concentration is most visible in the US Southeast, where healthcare and education foodservice operators have merged procurement functions, squeezing mid-tier thermoformers unable to meet volume minimums.
Hinged Deli Containers Market Segmentation
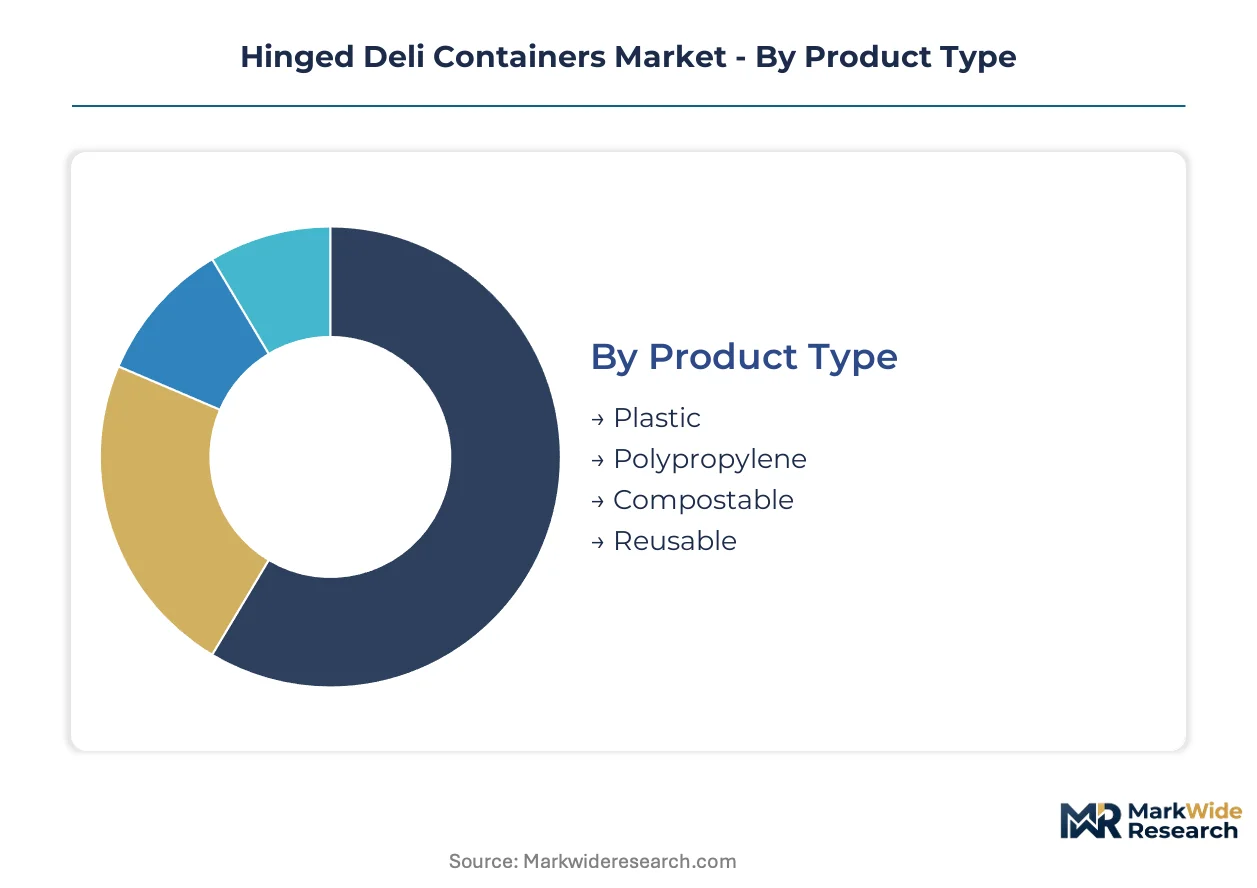
Segmentation in hinged deli containers reveals how material choices and operational requirements fragment procurement patterns across foodservice channels. Container specifications diverge sharply between dine-in restaurants prioritizing presentation durability and delivery platforms optimizing for thermal retention and stackability.
Product Type:
After-sales service intensity varies dramatically by material platform, with compostable grades requiring supplier technical support for shelf-life management and disposal certification that petroleum-based alternatives do not demand.
- Polypropylene:Thermoformed or injection-molded homopolymer and copolymer variants dominate current volume through superior heat-deflection temperatures above 100°C. Quick-service chains in Germany specify these for hot-fill applications under EU Single-Use Plastics Directive compliance timelines.
- Compostable:PLA-PHA blends and fiber-based alternatives command premium positioning as BPI and TÜV OK certifications unlock procurement pathways for operators facing organics mandate deadlines. California SB 54 implementation accelerates demand for these grades among healthcare and education foodservice consolidators.
- Plastic:General-purpose petroleum-based containers span PET and polystyrene legacy formats, though expanded polystyrene faces mandated phase-outs across European quick-service chains.
- Reusable:Durable polypropylene designs with reinforced hinges target closed-loop catering operations and institutional foodservice with return logistics infrastructure.
Polypropylene holds the largest share; momentum sits with compostable grades as regulatory deadlines compress adoption timelines.
End User:
Cost tier stratification separates specification authority, with enterprise restaurant groups standardizing nationwide SKUs while independent operators retain fragmented procurement flexibility.
- Food Delivery Services:Third-party logistics platforms drive demand for thinner-gauge, faster-sealing formats that sacrifice durability for speed. Cloud kitchen densification in urban cores aggregates volume for standardized, stackable geometries optimized for handoff efficiency.
- Restaurants:Full-service and quick-service operators balance presentation requirements against disposal logistics, with German chains prioritizing regulatory-compliant fiber-based solutions ahead of broader European enforcement.
- Catering Services:Event-based and institutional operators favor larger-capacity hinged formats with transport stability for off-premise service.
- Retail Outlets:Grocery deli counters and convenience stores specify clear-lid variants for visual merchandising of prepared foods.
Restaurants retain the largest procurement volume; food delivery services are expanding most quickly as platform order volumes compress operational tolerances.
Capacity:
Volume concentration tracks portion-size standardization across foodservice segments, with delivery platforms driving fragmentation into smaller single-serve formats.
- Small:Single-serve portions dominate delivery platform specifications for portion control and thermal retention efficiency.
- Medium:Standard entree capacities anchor quick-service restaurant procurement with balanced material efficiency.
- Large:Family-size and catering formats concentrate in institutional and event foodservice channels.
- Extra Large:Bulk prepared food and platter service targets grocery retail deli operations with display visibility requirements.
Medium capacity holds the largest share; small formats are climbing the fastest as delivery order mix shifts toward individual portions.
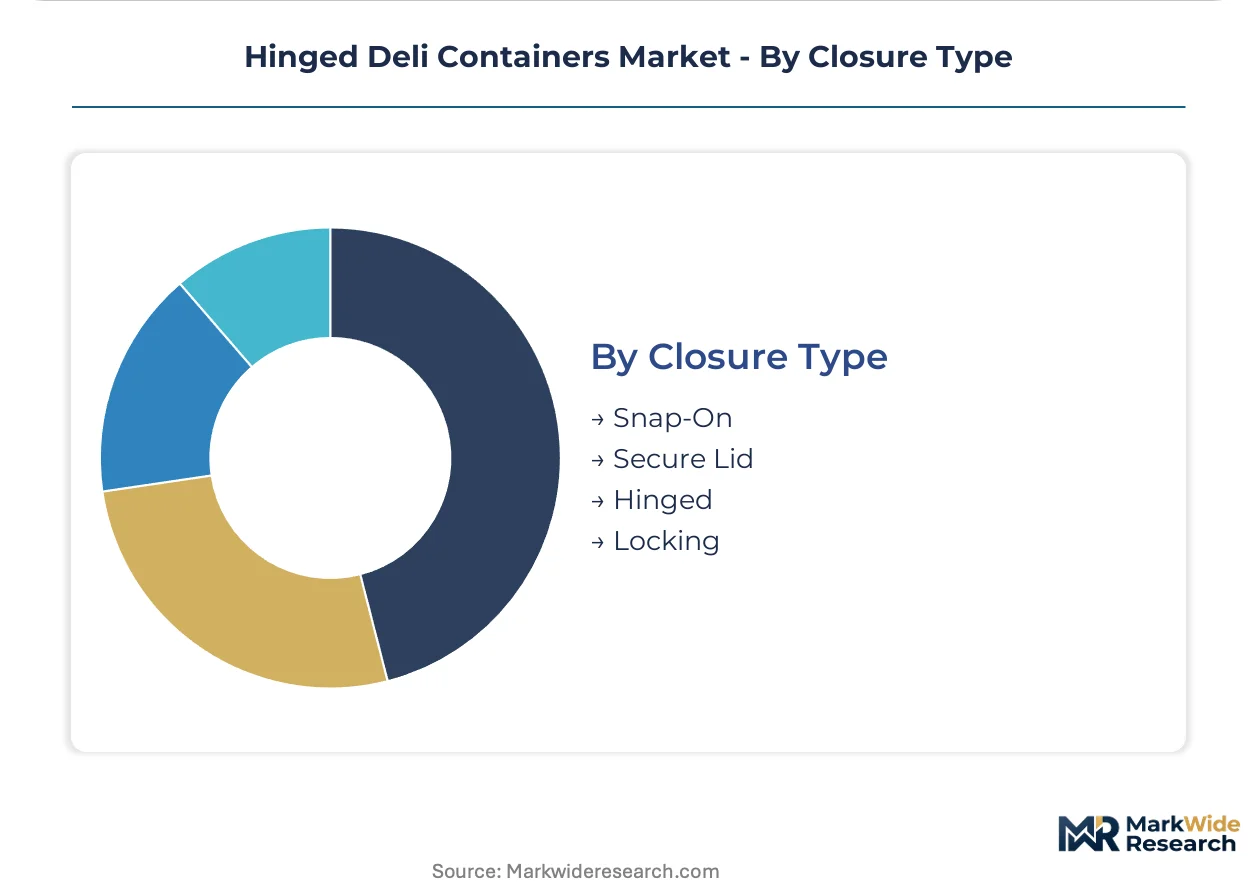
Closure Type:
Margin differentiation separates precision-engineered locking mechanisms from commodity snap-on designs, with automation compatibility commanding price premiums.
- Hinged:Integrally molded flexible connections enable one-handed operation and secure reclosure, forming the baseline specification for deli container category definition.
- Locking:Tamper-evident and leak-resistant mechanisms target delivery applications with rigorous transport integrity requirements.
- Secure Lid:Intermediate sealing performance balances reclosure convenience with manufacturing cost efficiency.
- Snap-On:Separate lid components offer lowest-cost entry point for price-sensitive independent operators with minimal transport risk.
Hinged closures hold the largest share; locking variants are gaining share fastest as delivery platform quality standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in hinged deli containers varies sharply by geography. German buyers absorb premium compostable grades under regulatory pressure, while US independent operators resist cost increases above polypropylene baselines.
United States
Food delivery platforms compress order-to-delivery windows, forcing thinner-gauge specifications. California SB 54 mandates 30% post-consumer recycled content by 2032, reshaping procurement pathways. Los Angeles cloud kitchen clusters aggregate demand for standardized stackable formats optimized for third-party logistics handoffs.
Germany
Quick-service chains prioritize fiber-based hinged solutions ahead of EU Single-Use Plastics Directive enforcement deadlines. ECHA REACH Annex XVII restrictions on per- and polyfluoroalkyl substances eliminate grease-resistant coatings from paperboard alternatives. Berlin-Brandenburg foodservice operators accelerate reformulation timelines under tightest national compliance windows.
China
Domestic food delivery volumes drive demand for cost-optimized polypropylene thermoformed containers. SAMR food contact material standards elevate testing burdens for imported resin formulations. Yangtze River Delta manufacturing bases supply standardized geometries to quick-service automation lines.
India
Organized food retail expansion concentrates procurement among national quick-service chains. FSSAI packaging safety regulations tighten additive disclosure requirements for direct food contact plastics. Maharashtra foodservice distributors consolidate specifications through group purchasing organizations, squeezing mid-tier thermoformer margins.
United Kingdom
Meal-kit subscription growth fragments container demand across temperature-tolerant formats. Defra extended producer responsibility consultations signal pending packaging recovery obligations. London-Southeast logistics corridors prioritize stackable designs for dense urban delivery routing efficiency.
Hinged Deli Containers Market Competitive Landscape
Integrated resin converters and specialized thermoformers split the market along material platform lines. Tier-one foodservice distributors wield specification authority through consolidated procurement programs. Three archetypes dominate: North American integrated manufacturers with captive resin supply, European fiber-based packaging specialists, and Asian cost-optimized thermoforming exporters. Competitive moves center on compostable resin formulation licensing and automated thermoforming line deployment.
Within the integrated manufacturing tier, Pactiv Evergreen Inc. and Dart Container Corporation exemplify scale-driven positioning through North American production footprints. Huhtamaki occupies a specialist position extending fiber-based packaging expertise into hinged formats. These three anchors demonstrate how geographic manufacturing concentration and material platform focus determine competitive differentiation in procurement channels.
| Leading Market Players |
|---|
| Pactiv Evergreen Inc. |
| Dart Container Corporation |
| Berry Global Group, Inc. |
| Genpak LLC |
| Sabert Corporation |
| Amcor plc |
| Huhtamaki |
| Placon |
| Anchor Packaging |
| Others |
Supply & Pricing Matrix
Overcapacity in North American polypropylene resin conversion is pressuring thin-wall thermoformers toward volume-driven pricing postures while compressing margins for operators lacking long-term feedstock contracts. This utilization dynamic rewards integrated manufacturers with captive resin supply and squeezes independent converters exposed to spot market volatility.
Pricing Analysis
After-sales service revenue from compostable grade technical support and BPI certification consulting drives lifetime value capture for suppliers positioned ahead of regulatory deadlines. Three-tier pricing structure across premium compostable, standard polypropylene, and economy petroleum-based grades segments buyer archetypes by compliance urgency and volume scale. Pricing pressure stems from propylene feedstock volatility linked to Gulf Coast cracker utilization swings. Independent restaurant operators exhibit highest price sensitivity, resisting premiums above polypropylene baselines, while German quick-service chains absorb compostable markups under EU Single-Use Plastics Directive enforcement timelines.
Supply Chain Analysis
Export-control restrictions on advanced thermoforming equipment and biopolymer formulation IP limit technology transfer to emerging manufacturing bases. Resin supply concentrates in the United States, Germany, and China, with North American Gulf Coast crackers feeding domestic thin-wall thermoformers and Yangtze River Delta operations supplying Asian delivery platform demand. Raw material dependencies span propylene monomer, PLA-PHA biopolymer feedstocks, and calcium carbonate mineral fillers. Single-source vulnerability runs through specialized mold tooling suppliers in Germany and Japan. Distribution runs through tier-one foodservice distributors consolidating procurement through group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as food delivery platform specifications diverge from traditional restaurant durability requirements, creating distinct procurement channels with incompatible performance priorities.
For Market Incumbents: Insulate core polypropylene volume through backward integration into resin conversion and long-term supply contracts with Gulf Coast crackers. Lock in quick-service automation compatibility by investing in precise dimensional tolerance tooling that kitchen robotics require. Defend against fiber-based substitutes by accelerating compostable resin formulation licensing to capture premium positioning ahead of EU enforcement deadlines.
For New Entrants and Emerging Players: Build out regional compostable thermoforming capacity in California to exploit SB 54 preferential procurement pathways for post-consumer recycled content containers. Target cloud kitchen clusters in Los Angeles and urban cores where standardized stackable formats aggregate demand. Pursue group purchasing organization certification to bypass fragmented independent operator sales cycles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across compostable grade manufacturing as PLA crystallization cooling channel retooling demands fresh capital deployment. Five-to-ten year viability favors integrated players with resin supply control and certification-ready product platforms. Acquisition target archetype: mid-tier thermoformers with established FDA food contact compliance and underutilized tooling capacity. Signal to watch: BPI certification backlog duration as indicator of compostable grade supply constraint.
| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Resin Formulation Licensing | Platform licensing revenue from PLA-PHA blends unlocks premium procurement pathways under EU Single-Use Plastics Directive timelines. |
| Automated Thermoforming Line Deployment | Real-time cavity pressure sensors and machine-learning quality prediction reduce inspection overhead for tier-one distributor onboarding. |
| Backward Integration into Resin Conversion | Captive polypropylene supply insulates margins from Gulf Coast cracker utilization volatility and feedstock price swings. |
| Digital Printing Integration | Inline decoration during thermoforming enables lot-level traceability without label adhesives that contaminate recycling streams. |
| Cloud Kitchen Supply Partnership | Dedicated capacity agreements with Los Angeles and Berlin-Brandenburg ghost kitchen clusters secure volume commitments for standardized geometries. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foodservice packaging procurement managers, thermoforming plant engineers, quick-service chain sustainability directors, and group purchasing organization contract specialists. Secondary validation drew from FDA 21 CFR food contact material filings, ECHA REACH Annex XVII substance restriction updates, EU Single-Use Plastics Directive implementation guidance, and California SB 54 regulatory text. Bottom-up volume estimates from individual facility capacities and top-down demand segmentation from end-user procurement patterns were triangulated to reconcile figures.
Calibration against historical capacity utilization rates and regulatory adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material platform, closure type, end-user channel, capacity tier, and regional regulatory cluster. CAGRs were derived from slope analysis of adoption curve inflection points and material substitution elasticities. Forecast inputs incorporated biopolymer heat-deflection temperature advances and cloud kitchen densification rates in urban logistics corridors.
Stress conditions across propylene feedstock price bands, EU enforcement timeline acceleration, and compostable resin certification backlog durations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory adherence and technology diffusion rates. Material shifts in FDA food contact approval pathways for novel biopolymers or sudden ECHA expansion of restricted substance lists would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Thin Wall Plastic Containers Market
Containers
Lever Lid Cans Market
Containers
Acrylic Container Market
Containers
Packer Bottle Market
Containers
Container Mouth Inner Seal Market
Containers
Wide Mouth Jars Market
Containers
Stackable Container Market
Containers
Thermoformed Containers Market
Containers
Sample Containers Market
Containers
Global Food Containers Market
Containers
Takeaway Containers Market
Containers
Essential Oil Containers Market
Containers
Collapsible Food Packaging Containers Market
Containers
2 Piece Cans Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
Bulk Container Packaging Market