
 Jug Shipper Market | 2026-2036
Jug Shipper Market Size, Share, and Industry Trends Forecast 2026-2036
Jug Shipper Market Foresight
Thermoformed recycled PET cushioning is reshaping how jug shippers protect glass and plastic containers during transit. Berlin Packaging leverages its North American distribution network to supply standardized jug shipper formats to mid-sized beverage bottlers. ACH Foam Technologies Inc. anchors the insulated segment with expanded polystyrene solutions for temperature-sensitive chemical transport. Air Sea Containers competes on UN-certified hazardous material configurations that meet DOT performance standards for chemical jug shipments.
A jug shipper is a protective packaging assembly designed to secure rigid liquid containers—typically one to ten liters in capacity—against impact, vibration, and thermal excursion during distribution. The structure commonly integrates corrugated outer shells with molded pulp, foam, or engineered plastic inserts that cradle the jug neck and base to prevent contact damage. Plastic jug shippers dominate unit volume due to lightweighting advantages and compatibility with automated fulfillment lines, though glass jug variants command premium positioning in wine and craft spirits channels. Composite jug configurations represent the fastest-growing product category as brands seek to balance drop-test performance with post-consumer recyclability targets. The five-liter capacity tier generates outsized revenue contribution from industrial chemical and food ingredient bulk shipments.
The EPA regulates jug shipper materials through Resource Conservation and Recovery Act provisions affecting foam disposal, while the DOT mandates UN performance testing for chemical transport packaging under 49 CFR standards. California's SB 54 extended producer responsibility law is forcing jug shipper redesigns toward mono-material or readily separable component structures. Oregon's Department of Environmental Quality has advanced similar packaging reduction mandates that ripple through Pacific Northwest beverage distribution networks. Stakeholders must monitor how state-level recycling infrastructure investments alter material cost structures and design specifications for multi-jug transit packs.
Market Dynamics
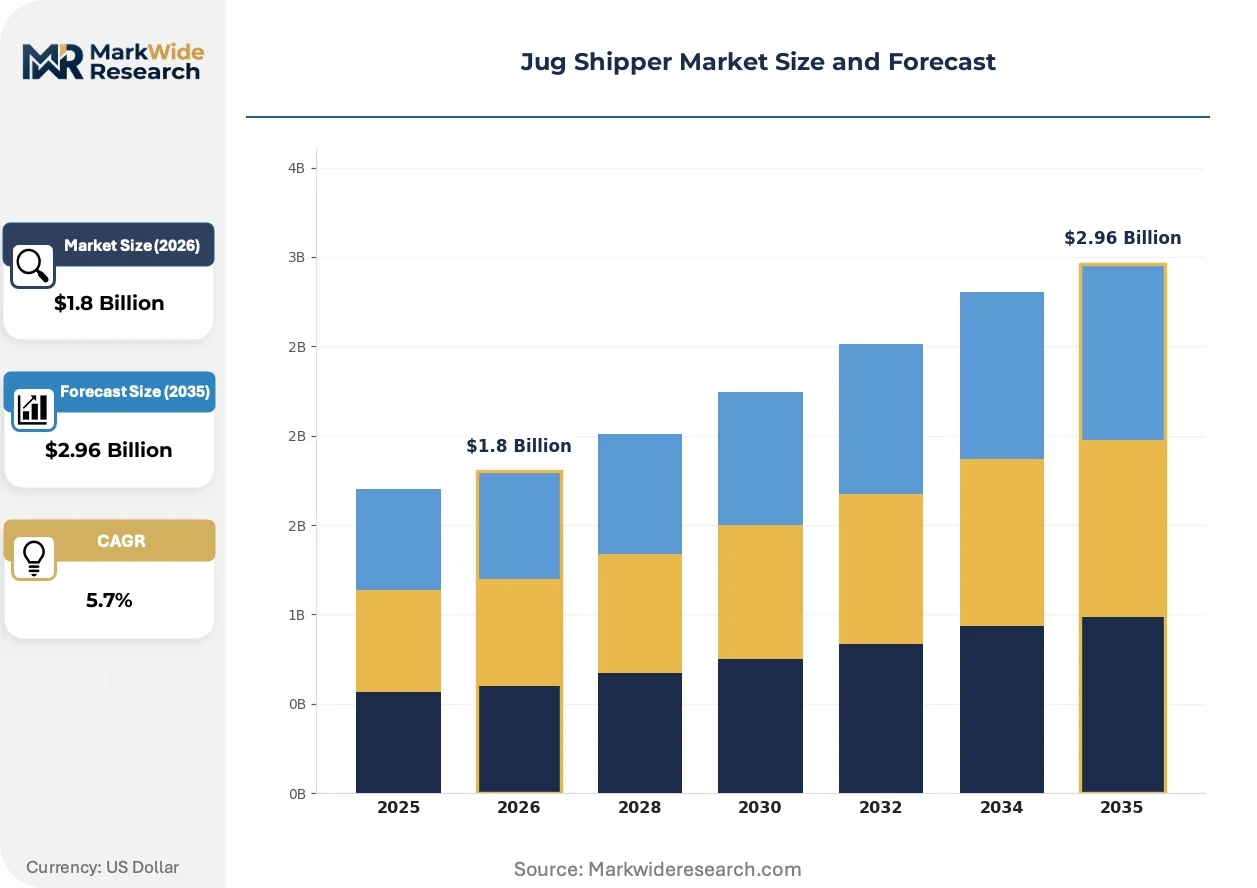
Extended producer responsibility frameworks are forcing jug shipper redesigns toward mono-material structures, compressing design cycles and elevating material science capabilities as the decisive competitive differentiator.
Growth Catalysts
- California SB 54 Mandate:The state's extended producer responsibility law requires 100% recyclable packaging by 2032, accelerating demand for separable component jug shippers among wine and spirits distributors operating along Pacific Coast corridors.
- Reusable Program Expansion:Beverage bottlers across the United States are scaling returnable jug systems that demand durable, multi-trip shipper designs with enhanced structural integrity for repeated handling cycles.
- Thermoformed rPET Adoption:Post-consumer recycled polyethylene terephthalate cushioning is displacing virgin foam inserts in glass jug protection, aligning with corporate sustainability targets without sacrificing drop-test performance.
Market Restraints
- Expanded Polystyrene Disposal Friction:EPA Resource Conservation and Recovery Act provisions classify certain foam residues as regulated waste, elevating end-of-life costs for insulated chemical shippers and constraining material choice.
- Resin Price Volatility:Fluctuations in petroleum-derived feedstock costs compress margins for plastic jug shipper manufacturers, particularly those serving price-sensitive industrial chemical segments.
- Corrugated Input Concentration:Containerboard supply concentrates among a limited base of North American integrated mills, exposing mid-sized shipper fabricators to allocation risk during demand spikes.
Strategic Opportunities
- Five-Liter Industrial Bulk Tier:Food ingredient and chemical manufacturers are consolidating purchases into larger jug formats, creating white space for specialized multi-jug transit packs with integrated dispensing features.
- Oregon Packaging Reduction Pathway:The state's Department of Environmental Quality is advancing mandates that mirror California's framework, opening early-mover advantage for compliant shipper designs in Pacific Northwest beverage networks.
- Composite Material Convergence:Hybrid structures combining molded pulp exteriors with engineered plastic inserts are capturing premium positioning in craft spirits channels seeking differentiated unboxing experiences.
Industry Challenges
- UN Certification Timeline Compression:DOT 49 CFR performance testing for hazardous material configurations requires extended validation cycles, delaying product launches for chemical transport specialists.
- Automation Integration Complexity:Legacy fulfillment lines designed for standardized corrugated formats struggle to accommodate variable-dimension composite shippers without capital-intensive retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jug Shipper Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Jugs, Glass Jugs, Metal Jugs, Composite Jugs Capacity: 1 Liter, 2 Liters, 5 Liters, 10 Liters Distribution Channel: Online Retailers, Wholesale Suppliers, Direct Sales, Distributors End User: Beverage Companies, Chemical Manufacturers, Food Processors, Pharmaceutical Industry |
| Companies Covered | Big Valley Formerly Bee Packaging, Berlin Packaging, Air Sea Containers, ACH Foam Technologies Inc., Atlas Roofing Corporation, IGH Holdings, Inc., BOX Partners LLC, EBKContainers, Big Valley Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jug Shipper Market Shifts & Advancements
Digital design tools and material informatics are compressing development cycles for protective packaging, enabling rapid iteration against evolving performance specifications and regulatory thresholds.
Simulation-driven topology optimization is virtualizing the traditional prototype-test-redesign cycle for jug shipper structures. Packaging engineers at mid-sized beverage bottlers now iterate cushioning geometries through finite element analysis before physical tooling, collapsing development timelines from months to weeks. This capability is virtualizing competitive advantage toward firms with in-house computational design capacity rather than legacy manufacturing scale.
REACH restrictions on persistent organic pollutants are tightening specifications for flame-retardant additives in expanded polystyrene formulations. European chemical transport operators face reformulation mandates that elevate material costs while demanding revalidation of existing UN-certified configurations. The insulated jug segment is responding through accelerated trials of mineral-based alternatives and bio-derived foam precursors.
Direct procurement relationships between large beverage distributors and specialized shipper fabricators are displacing traditional packaging distributor intermediaries. Bulk buyers in California's Central Valley wine corridor now specify custom mono-material formats through sole-source contracts, capturing design control and volume pricing. This pattern is most pronounced among craft spirits brands with sustainability certifications that require supply chain transparency documentation.
Jug Shipper Market Segmentation
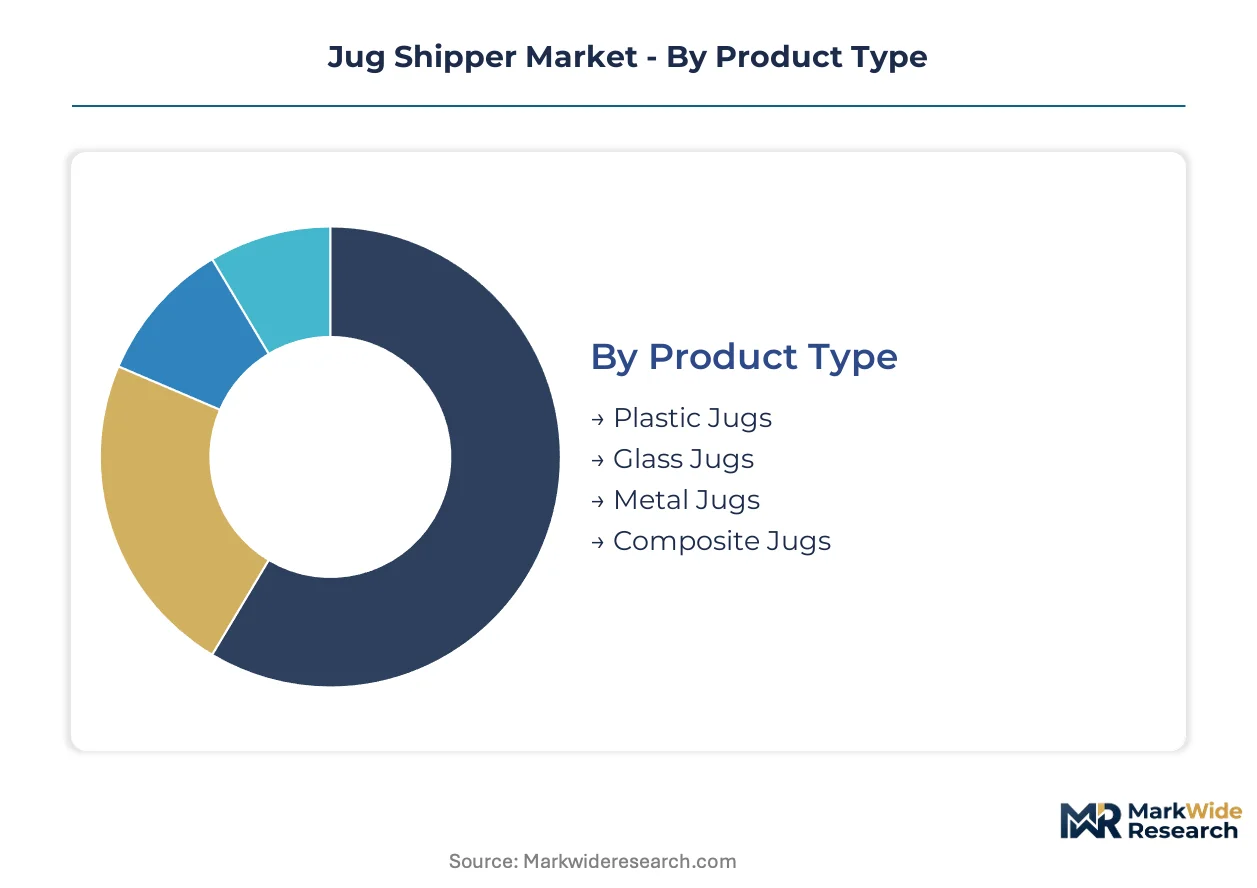
Jug shipper configurations vary sharply across container material, volume tier, and channel economics, with each segmentation axis carrying distinct margin profiles and compliance burdens. Understanding these divides reveals where standardization yields scale and where customization commands premium positioning.
Product Type:
Mature formats dominate unit economics while emerging hybrids capture sustainability premiums.
- Plastic Jugs:Lightweight polyethylene and polypropylene shells integrate seamlessly with automated fulfillment lines. Beverage bottlers in California's Central Valley specify these for high-velocity wine and spirits distribution where transport cost minimization overrides material aesthetics.
- Composite Jugs:Hybrid structures layer molded pulp exteriors over engineered plastic inserts, balancing drop-test performance against post-consumer recyclability mandates. Craft spirits brands seeking differentiated unboxing experiences drive specification here.
- Glass Jugs:Premium wine and spirits channels favor these for perceived quality, though thermoformed rPET cushioning requirements elevate shipper complexity.
- Metal Jugs:Industrial chemical transport leverages steel and aluminum variants for UN-certified hazardous material configurations under DOT 49 CFR standards.
Plastic jug shippers retain volume leadership; composite configurations hold the steepest expansion curve.
Capacity:
Volume tiers segment sharply between consumer convenience and industrial bulk economics.
- 5 Liters:Food ingredient and chemical manufacturers consolidate procurement into this format, generating outsized revenue contribution from multi-jug transit packs with integrated dispensing features. Pacific Northwest distribution networks favor this tier for bulk efficiency.
- 1 Liter:Single-serve beverage and pharmaceutical sampling programs concentrate demand here, with lightweighting priorities driving minimal shipper footprints.
- 2 Liters:Mid-tier beverage retail formats balance portability with per-unit economics.
- 10 Liters:Industrial chemical bulk shipments dominate, with specialized handling equipment requirements constraining addressable channel scope.
Five-liter formats anchor revenue contribution; one-liter specifications expand most quickly in pharmaceutical sampling channels.
Distribution Channel:
Channel structure determines shipper standardization versus customization tradeoffs.
- Wholesale Suppliers:Standardized corrugated formats with molded pulp inserts dominate, achieving scale through volume commitments from mid-sized beverage bottlers.
- Direct Sales:Large distributors in California's wine corridor now specify custom mono-material formats through sole-source contracts, capturing design control and supply chain transparency documentation.
- Online Retailers:E-commerce fulfillment demands shipper compatibility with automated sortation and last-mile durability testing.
- Distributors:Traditional packaging intermediaries face displacement as bulk buyers consolidate procurement relationships directly with specialized fabricators.
Wholesale suppliers retain volume leadership; direct sales channels gain share fastest through sustainability-driven sole-source contracting.
End User:
Regulatory intensity and performance specifications diverge sharply across vertical applications.
- Beverage Companies:California SB 54 compliance deadlines force redesign cycles toward separable component structures, with reusable program expansion demanding multi-trip durability.
- Chemical Manufacturers:DOT UN certification requirements for hazardous material transport constrain material choice and extend validation timelines.
- Food Processors:FDA food contact material specifications govern insert selection, with five-liter bulk formats driving specialized multi-jug transit pack demand.
- Pharmaceutical Industry:Temperature excursion protection and chain-of-custody documentation elevate shipper complexity for active pharmaceutical ingredient transport.
Beverage companies retain volume leadership; pharmaceutical applications follow the steepest specification escalation curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border wine shipments from France to the United States drive specialized jug shipper demand along transatlantic logistics corridors, with California's distribution networks absorbing premium protective packaging formats for glass container transit.
United States
California's Central Valley wine corridor generates concentrated demand for five-liter bulk shipper configurations as food ingredient manufacturers consolidate procurement. The EPA's Resource Conservation and Recovery Act provisions classify certain foam residues as regulated waste, elevating end-of-life compliance costs for insulated chemical transport. Pacific Northwest beverage networks around Oregon's Willamette Valley are scaling reusable jug programs that demand multi-trip durability specifications.
Germany
Rhine-Main industrial chemical clusters anchor European demand for UN-certified hazardous material jug shippers under DOT-aligned performance standards. REACH restrictions on persistent organic pollutants tighten flame-retardant additive specifications for expanded polystyrene formulations. Bavarian packaging fabricators near Nuremberg are accelerating trials of mineral-based foam alternatives to maintain certification compliance.
France
Bordeaux and Burgundy wine export corridors drive premium glass jug shipper specifications for transatlantic distribution. The EU Green Deal packaging waste directives pressure redesigns toward mono-material separability by 2030. Champagne-Ardenne logistics hubs are piloting composite hybrid structures combining molded pulp exteriors with engineered plastic inserts for craft spirits channels.
China
Pearl River Delta chemical manufacturing zones generate industrial-scale demand for ten-liter bulk jug configurations with integrated dispensing features. The Ministry of Ecology and Environment enforces dual carbon goals that constrain virgin petroleum-derived feedstock utilization in protective packaging. Yangtze River Delta fabricators near Shanghai are expanding thermoformed rPET cushioning capacity for glass container protection.
Australia
Barossa Valley and Margaret River wine regions drive specialized shipper demand for temperature-sensitive export logistics. The country's national environmental regulator advances extended producer responsibility frameworks mirroring California's SB 54 structure. New South Wales distribution networks around Sydney are consolidating direct procurement relationships with specialized fabricators to capture supply chain transparency documentation.
Jug Shipper Market Competitive Landscape
On the supply side, the industry is moderately concentrated around integrated packaging conglomerates and specialized protective fabricators, with mid-sized regional players capturing niche sustainability-driven segments. Strategic archetypes include corrugated-integrated conglomerates with North American distribution networks, foam-specialized chemical transport providers with UN certification capabilities, and sustainability-focused composite innovators targeting craft spirits channels. Dominant competitive moves encompass vertical integration into recycled feedstock supply chains and strategic partnerships with large beverage distributors for sole-source custom format contracts.
Among North American fabricators, Berlin Packaging exemplifies the corrugated-integrated conglomerate archetype with standardized format scale, while ACH Foam Technologies Inc. occupies the insulated chemical transport specialist position with expanded polystyrene solutions. Air Sea Containers represents the UN-certified hazardous material configuration segment, anchoring compliance-driven demand from industrial chemical manufacturers. These three entities collectively illustrate how certification capabilities, material science expertise, and distribution network reach define competitive positioning across distinct end-use verticals.
| Leading Market Players |
|---|
| Big Valley Formerly Bee Packaging |
| Berlin Packaging |
| Air Sea Containers |
| ACH Foam Technologies Inc. |
| Atlas Roofing Corporation |
| IGH Holdings, Inc. |
| BOX Partners LLC |
| EBKContainers |
| Big Valley Packaging |
| Others |
Supply & Pricing Matrix
Containerboard mill undercapacity in the Pacific Northwest elevates input costs for corrugated shell fabricators while simultaneously compressing margins for mid-sized jug shipper manufacturers serving California's wine distribution corridor. This utilization squeeze forces suppliers toward longer-term offtake contracts with integrated mills, reshaping pricing power toward upstream producers and away from packaging converters.
Pricing Analysis
Current-generation foam-based cushioning commands premium positioning against prior-generation expanded polystyrene and emerging next-generation bio-derived alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by UN certification grade and volume commitment scale, with DOT-certified hazardous material configurations capturing substantial markups over beverage-grade formats. Pricing pressure stems from resin feedstock volatility linked to petroleum price swings, squeezing converters serving price-sensitive industrial chemical segments. Small-to-mid-sized beverage bottlers exhibit highest price sensitivity due to thin operating margins, while large chemical manufacturers prioritize performance compliance over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk profiles for thermoformed rPET cushioning components. Manufacturing concentrates in China, the United States, and Germany, with Chinese fabricators supplying cost-optimized molded pulp exteriors and German specialists anchoring precision-engineered plastic insert production. Raw material dependencies center on post-consumer PET flake, containerboard linerboard, and bio-based foam precursors. Single-source vulnerability runs through concentrated North American containerboard mills. Distribution runs through direct procurement relationships displacing traditional packaging intermediaries, particularly among California's Central Valley wine distributors seeking supply chain transparency documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The jug shipper market functions as a service-attach opportunity where reusable program logistics and UN certification renewal services expand faster than hardware shipments, creating recurring revenue layers that stabilize cash flow volatility for fabricators with installed base penetration.
For Market Incumbents: Pre-empt displacement from direct procurement consolidation by locking sole-source contracts with California's largest wine distributors before competitors establish design control relationships. Backward integration into post-consumer PET flake supply secures feedstock cost stability against resin volatility threatening margin compression in standard-grade formats. Certification investment in Oregon's emerging packaging reduction pathway creates regulatory moat against mid-tier challengers lacking compliance infrastructure. For New Entrants and Emerging Players: Pursue white-space positioning in five-liter industrial bulk configurations with integrated dispensing features, where food ingredient manufacturers consolidate procurement and specification standards remain unsettled. The Pacific Northwest reusable jug program expansion offers most penetrable geography, with multi-trip durability requirements favoring entrants with materials science capabilities over legacy corrugated converters. Go-to-market execution should emphasize sole-source contracting with sustainability-certified craft spirits brands demanding supply chain transparency documentation. For Investors and Strategic Acquirers: Capital is best deployed toward composite material innovators combining molded pulp exteriors with engineered plastic inserts, as this archetype captures premium positioning in fastest-growing craft spirits channels while meeting California SB 54 recyclability mandates. Long-term viability across the analysis window hinges on regulatory compliance infrastructure rather than manufacturing scale alone. The signal to watch is Oregon Department of Environmental Quality rule finalization, which will replicate California's extended producer responsibility framework and accelerate compliant design demand.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Feedstock Integration | Captive supply of post-consumer PET flake insulates margins from petroleum price swings. |
| UN Certification Investment | DOT 49 CFR compliance infrastructure unlocks hazardous material transport premium pricing tiers. |
| Sole-Source Contracting | Direct procurement relationships with California wine distributors displace packaging intermediaries. |
| Reusable Program Design | Multi-trip durability specifications align with Pacific Northwest beverage network expansion. |
| Composite Material Convergence | Hybrid pulp-plastic structures meet California SB 54 separability mandates while commanding craft spirits premiums. |
Research Methodology
Cross-validation between primary interviews with packaging engineers and secondary validation through EPA regulatory filings anchors the qualitative findings in this study. Packaging procurement managers at beverage bottlers, corrugated mill sales directors, thermoformed cushioning fabricators, and DOT certification specialists provided operational perspective on design cycle compression and material substitution patterns. Secondary sources included customs trade data on containerboard imports, California Department of Resources Recycling and Recovery implementation guidance, and SEC 10-K disclosures from integrated packaging conglomerates. Bottom-up shipment data from regional fabricators triangulates against top-down demand estimates from end-use verticals.
Calibration against historical capacity utilization rates at North American containerboard mills and validated substitution elasticities between foam and rPET cushioning informs the projection framework. Segmentation dimensions span container material, capacity tier, distribution channel structure, and end-use regulatory intensity, with cross-elasticities modeled between reusable and single-use program economics. CAGRs derive from trend extrapolation adjusted for regulatory inflection points, incorporating thermoformed rPET adoption curves and extended producer responsibility compliance deadlines as industry-specific forecast inputs.
Sensitivities concentrate around Oregon regulatory rule finalization timing and containerboard mill capacity expansion decisions. Forecasts reflect assumptions on substitution rates between material formats and state-level recycling infrastructure investment levels. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Global Multi Pack Carriers Market
Containers
Durable Insulated Containers Market
Containers
Bulk Container Packaging Market
Containers
Injection Molding Containers Market
Containers
Stack and Nest Containers Market
Containers
Soup Containers Market
Containers
Cylindrical Cans Market
Containers
Square Pails Market
Containers
Americas Container Technology Market
Containers
Compartment Trays Market
Containers
Algeria Container Glass Market
Containers
Sandwich Containers Market
Containers
Stackable Container Market
Containers
Composite Ibcs System Market
Containers
Vials Market
Containers
Water Resistant Packing Cubes Market