
 Hinged Lid Compostable Container Market | 2026-2036
Hinged Lid Compostable Container Market Size, Share, and Industry Trends Forecast 2026-2036
Hinged Lid Compostable Container Market Outlook
Modular clamshell configurations with integrated hinged lids is restructuring buyer choice across foodservice procurement, replacing separate-lid systems that add labor and leakage risk. Huhtamaki Oyj leverages its molded fiber expertise to dominate European institutional catering contracts. Pactiv Evergreen Inc. anchors North American supply through backward integration into bagasse sourcing and thermoforming capacity. Novolex Holdings LLC competes via its diversified resin-to-retail channel control, spanning both conventional and compostable product lines.
Hinged lid compostable containers are single-use food packaging units manufactured from plant-derived substrates such as polylactic acid, crystallized polylactic acid, bagasse, or bamboo fiber, featuring an integrally molded hinge that eliminates separate lid components while maintaining temperature retention and stackability for prepared food transport. PLA and bagasse formulations currently occupy the largest production volumes, though CPLA variants command premium positioning in hot-fill applications where heat resistance exceeds standard polylactic acid thresholds. Food service end users generate the dominant demand pull, with catering and events segments representing faster-growth niches as temporary food operations face heightened scrutiny for single-use plastic elimination.
The EU F-Gas Regulation and REACH compliance frameworks shape material chemistry choices for European manufacturers, while FDA food contact notifications and ASTM D6400 certification requirements govern United States market access and product labeling legitimacy. BIS standards in India and China's GB compostability protocols create additional compliance layers for exporters targeting Asia-Pacific procurement channels. Stakeholders must monitor municipal composting facility capacity buildouts against certification standard fragmentation, as infrastructure gaps between regions will determine which material platforms achieve viable end-of-life economics.
Market Dynamics
Extended producer responsibility frameworks are forcing foodservice packaging buyers to internalize end-of-life costs, accelerating the displacement of conventional plastic clamshells by compostable hinged alternatives across institutional procurement channels.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandated phase-out of fossil-based foodservice containers is redirecting quick-service restaurant procurement budgets toward certified compostable hinged lid formats.
- Municipal composting infrastructure:Facility expansion in the United States is creating viable end-of-life pathways that validate compostable packaging investments by food service operators.
- Bagasse fiber processing:Advances in sugarcane waste pulping are reducing unit costs for molded fiber hinged containers, narrowing the price gap with conventional polystyrene.
Market Restraints
- PLA resin supply concentration:Polylactic acid production clusters in Thailand and Nebraska create geographic vulnerability for container manufacturers dependent on corn and cassava feedstocks.
- Heat resistance thresholds:Standard PLA formulations deform above 50°C, restricting hot-fill applications and forcing reliance on premium CPLA variants.
- ASTM D6400 certification timelines:Third-party compostability verification requires 6-18 months, delaying product launches and locking out smaller manufacturers.
Strategic Opportunities
- India institutional catering:BIS compostability standards adoption is opening procurement channels for export-ready manufacturers as domestic sugarcane bagasse supply expands.
- Cold chain logistics integration:Hinged containers with integrated temperature indicators are capturing pharmaceutical meal kit and clinical nutrition contracts.
- California SB 54 implementation:State-level extended producer responsibility mandates are creating guaranteed offtake volumes for certified compostable packaging producers.
Industry Challenges
- Composting facility contamination protocols:Non-compostable lookalikes in waste streams trigger rejection of entire batches, requiring costly buyer education and labeling investments.
- Dual certification requirements:Manufacturers targeting both FDA food contact and ASTM D6400 compliance face redundant testing expenses and documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hinged Lid Compostable Container Market |
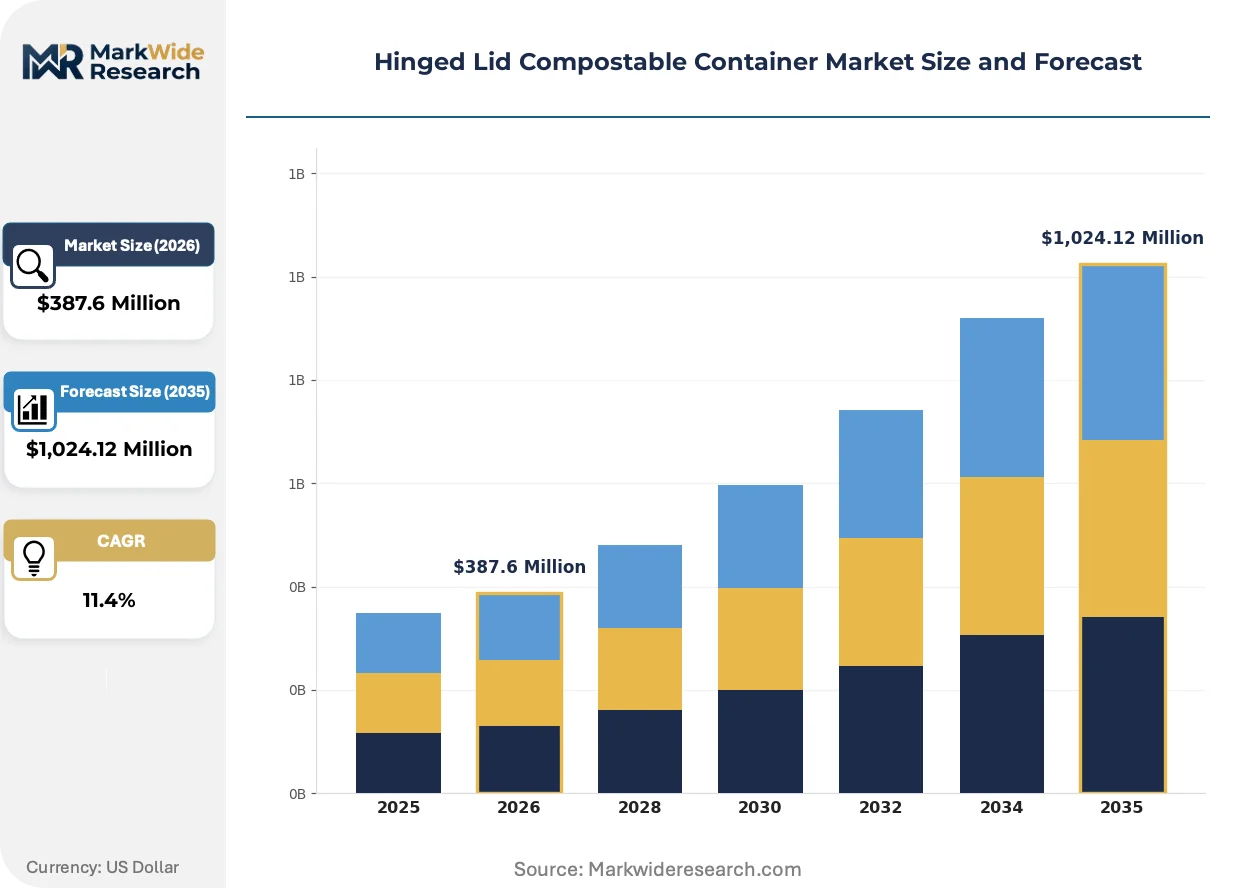
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, CPLA, Bagasse, Bamboo Size: Small, Medium, Large, Extra Large End User: Food Service, Retail, Catering, Events Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | Pactiv Evergreen Inc., Dart Container Corporation, Genpak LLC, Sabert Corporation, Anchor Packaging Inc., Huhtamaki Oyj, Placon Corporation, Novolex Holdings LLC, BioPak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hinged Lid Compostable Container Market Strategic Shifts
Material science advances and regulatory sequencing are compressing product development cycles while fragmenting certification requirements across export markets.
Crystallized polylactic acid is integrating heat-resistant properties into standard hinged lid geometries, enabling hot-fill applications previously reserved for petroleum-based alternatives. Quick-service chains in the southwestern United States are piloting CPLA clamshells for fried protein packaging. The technology is integrating thermal performance with compostability, collapsing the performance premium that conventional plastics previously commanded.
REACH substance restrictions are eliminating certain per- and polyfluoroalkyl substances from molded fiber oil-barrier coatings, forcing reformulation of bagasse containers for European export. Manufacturers are switching to polylactic acid-based barriers or mineral oil alternatives. Hot-fill soup and sauce applications face the tightest compliance deadlines, with German institutional buyers already rejecting legacy-coated inventory.
Corporate sustainability scorecards are compressing supplier qualification timelines, with procurement teams demanding compostability certification as a table-stakes entry requirement rather than a differentiating premium feature. Food service management companies are consolidating vendor lists to partners with multi-certification coverage. This pattern is most pronounced in university and healthcare contract catering, where RFP documents now specify ASTM D6400 or BPI certification as mandatory line items.
Hinged Lid Compostable Container Market Segmentation
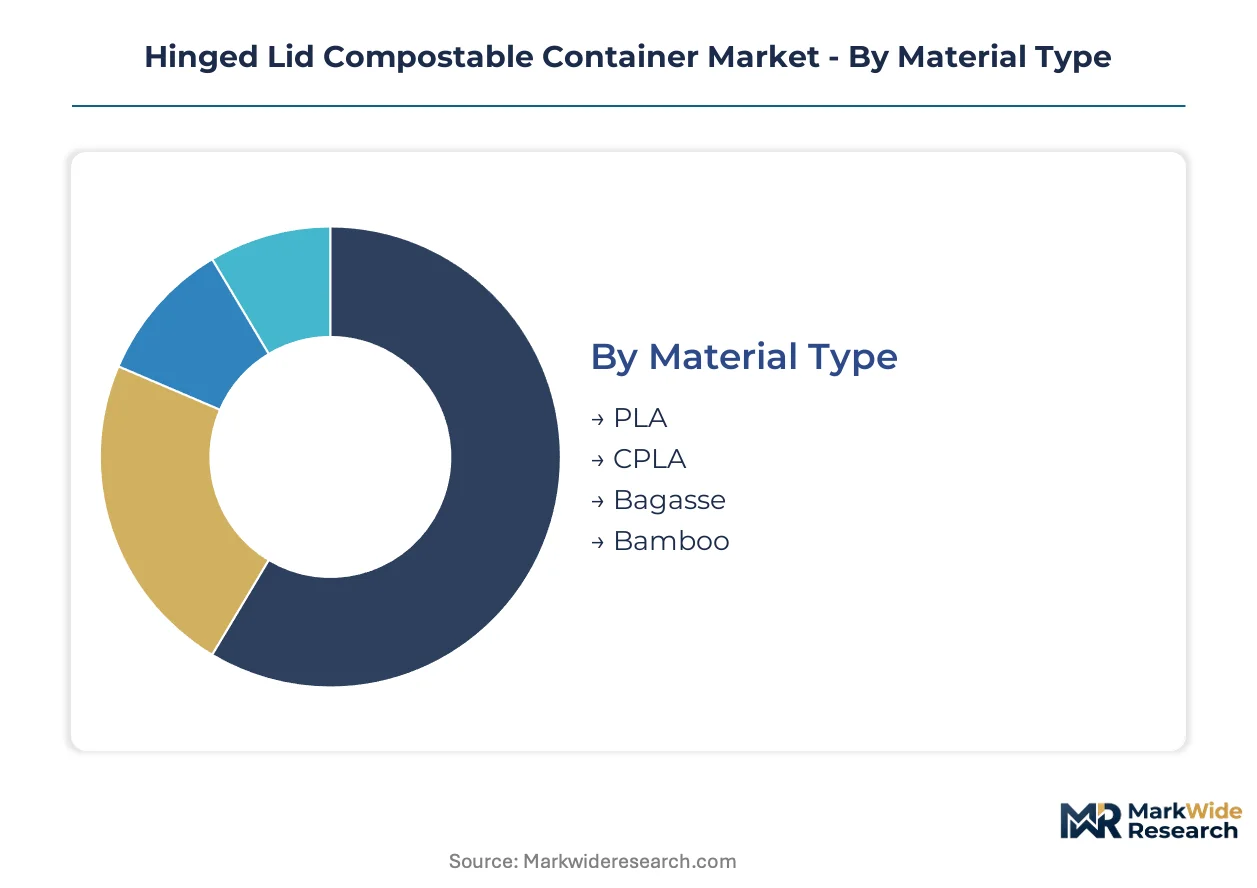
Material chemistry and container geometry dictate end-of-life pathways and procurement economics across foodservice channels. Size configurations and distribution models further stratify buyer access and operational fit.
Material Type:
Standalone compostable resins dominate direct procurement, while composite formulations embed into multi-material systems for performance-critical applications.
- PLA:Polylactic acid derived from corn or cassava starch offers clarity and thermoformability for cold-fill applications. Quick-service salad chains in the United States specify PLA clamshells for refrigerated display cases, though heat resistance constraints limit hot food deployment.
- CPLA:Crystallized polylactic acid undergoes thermal processing to achieve temperature stability above standard PLA thresholds. Fried protein packaging in southwestern United States quick-service trials relies on CPLA hinged lids where hot-fill durability is mandatory.
- Bagasse:Sugarcane fiber pulp delivers molded fiber rigidity at lower unit costs than resin alternatives. European institutional catering contracts specify bagasse containers for oil-barrier compliance under REACH substance restrictions.
- Bamboo:Fast-growth grass fiber provides structural reinforcement in hybrid formulations or standalone premium positioning. Asian export manufacturers leverage domestic bamboo supply chains for North American specialty retail channels.
Bagasse leads volumes today; CPLA is gaining share fastest.
Size:
Operational workflow integration determines size selection, with labor efficiency and storage density driving procurement preferences across foodservice formats.
- Small:Single-serve portions for sides and desserts. Airport concessionaires and healthcare meal programs specify small hinged containers for portion-controlled distribution.
- Medium:Standard entree capacity for grab-and-go retail. Convenience store chains in California stock medium clamshells for prepared sandwich and salad programs.
- Large:Family-size and shared-plate configurations. Catering operations specify large formats for buffet-style service and event drop-off logistics.
- Extra Large:Bulk protein and platter presentations. Barbecue chains in Texas deploy extra large hinged containers for smoked meat takeout orders.
Medium formats anchor procurement volumes; large sizes are expanding most quickly in catering channels.
End User:
Volume concentration varies sharply between permanent foodservice infrastructure and temporary operational setups with distinct compliance pressures.
- Food Service:Quick-service restaurants and institutional cafeterias generate baseline demand through contracted supply agreements. University dining services in the United States mandate ASTM D6400 certification as a vendor qualification threshold.
- Retail:Grocery prepared food departments and convenience stores specify hinged containers for refrigerated case presentation. California SB 54 implementation is redirecting retail procurement toward certified compostable formats.
- Catering:Corporate and social event food providers face heightened scrutiny for single-use plastic elimination. Temporary operations without permanent infrastructure prioritize compostable disposables for sustainability scorecard compliance.
- Events:Stadiums, festivals, and convention centers operate under municipal waste diversion mandates. Los Angeles and San Francisco event permits now require compostable foodservice packaging for large-gatherance approvals.
Food service commands the largest share; events are climbing the fastest as regulatory pressure intensifies on temporary operations.
Distribution Channel:
Channel selection reflects buyer scale and certification verification requirements, with direct relationships dominating institutional procurement.
- Online:E-commerce platforms serve small operators and regional chains seeking flexible order quantities. Amazon Business and specialty foodservice marketplaces aggregate multi-certification product lines for comparison purchasing.
- Offline:Traditional distributor networks including broadline foodservice distributors maintain regional inventory positions. Sysco and US Foods warehouse operations stock certified compostable hinged containers for same-day delivery to restaurant accounts.
- Direct Sales:Manufacturer relationships with national account chains bypass distributor margins. Huhtamaki Oyj and Pactiv Evergreen Inc. maintain dedicated sales teams for quick-service restaurant corporate procurement.
- Wholesalers:Cash-and-carry and independent distributor networks serve smaller independent operators. Restaurant depot formats in major metropolitan areas stock bagasse and PLA hinged lids for walk-up purchasing.
Direct sales capture the highest-value contracts; online channels are expanding most quickly among emerging regional chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hinged lid compostable container industry traces its commercial scaling to early bagasse fiber processing developments in India and Thailand during the 1990s, with subsequent PLA resin commercialization in Nebraska establishing North American production corridors.
United States
State-level extended producer responsibility laws in California, Oregon, and Washington are redirecting foodservice procurement budgets toward certified compostable formats. The FDA maintains food contact notification requirements while ASTM D6400 certification governs compostability labeling legitimacy. Municipal composting facility expansion in the Pacific Northwest and Northeast Corridor is creating viable end-of-life pathways that validate packaging investments by quick-service restaurant operators.
Germany
REACH substance restrictions are eliminating per- and polyfluoroalkyl substances from molded fiber oil-barrier coatings, forcing bagasse container reformulation for institutional catering compliance. The EU F-Gas Regulation shapes material chemistry choices for manufacturers serving European markets. The Rhine-Ruhr industrial cluster hosts specialized thermoforming operations supplying quick-service chains across Central Europe with CPLA hot-fill capable hinged containers.
India
BIS compostability standards adoption is opening procurement channels for export-ready manufacturers as domestic sugarcane bagasse supply expands from Maharashtra and Uttar Pradesh processing centers. The FSSAI governs food contact safety alongside BIS certification requirements for compostability claims. Gujarat-based molded fiber operations are scaling capacity to serve institutional catering contracts in Delhi-NCR and Bangalore metropolitan markets.
Thailand
Cassava feedstock concentration supports regional PLA resin production serving container manufacturers across Southeast Asian export markets. The country's national industrial standards body aligns with ISO compostability protocols for international market access. Bangkok metropolitan area thermoforming facilities supply quick-service restaurant chains operating under Thai government plastic reduction mandates targeting single-use foodservice packaging elimination by 2025.
Canada
Health Canada food contact regulations and provincial extended producer responsibility frameworks in British Columbia and Quebec are accelerating compostable packaging procurement shifts. The PMRA governs agricultural input residues in bagasse fiber sourcing for food contact applications. Toronto and Vancouver metropolitan areas concentrate foodservice distributor networks stocking ASTM D6400 certified hinged containers for regional restaurant and institutional catering accounts.
Hinged Lid Compostable Container Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification coverage and material formulation complexity, with multi-certification manufacturers commanding pricing power in institutional procurement channels. The market structure consolidates around resin-to-retail integrated groups, specialized molded fiber operations, and diversified packaging conglomerates maintaining parallel conventional and compostable product lines. Three archetypes dominate: backward-integrated bagasse processors, PLA resin specialists with captive thermoforming capacity, and broadline distributors leveraging channel control for private-label placement. Competitive moves concentrate on capacity expansion in CPLA hot-fill formulations and strategic partnerships with municipal composting operators to secure end-of-life pathway guarantees.
Among diversified packaging conglomerates, Huhtamaki Oyj and Pactiv Evergreen Inc. exemplify the integrated archetype spanning resin sourcing through retail distribution. Novolex Holdings LLC occupies a position within the channel-control tier, leveraging broadline foodservice distribution relationships. These three companies represent the competitive spectrum from European institutional catering specialization to North American quick-service restaurant supply chain dominance, each anchoring distinct geographic procurement corridors through certification breadth and manufacturing scale.
| Leading Market Players |
|---|
| Pactiv Evergreen Inc. |
| Dart Container Corporation |
| Genpak LLC |
| Sabert Corporation |
| Anchor Packaging Inc. |
| Huhtamaki Oyj |
| Placon Corporation |
| Novolex Holdings LLC |
| BioPak |
| Others |
Value Chain & Pricing Dynamics
Backward integration into bagasse sourcing and thermoforming capacity anchors both supply security and pricing power for North American producers serving quick-service restaurant chains under California SB 54 mandates. Captive control over sugarcane fiber pulp and resin conversion insulates integrated manufacturers from feedstock volatility while supporting premium positioning for ASTM D6400 certified formats.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CPLA hot-fill certified containers from standard PLA cold-fill formats and uncertified bagasse alternatives. Price differentiation rests on certification grade and volume scale, with institutional procurement contracts commanding 15-30 point spreads over spot wholesale. Cost compression in the standard tier is intensifying because Thai and Nebraska resin supply concentration exposes converters to agricultural commodity cycles. Quick-service restaurant chains exhibit the highest price sensitivity, while pharmaceutical meal kit contracts show minimal elasticity for temperature-validated formats.
Supply Chain Analysis
Direct-to-institutional channels handle hyperscale buyer demand from university dining services and healthcare catering contracts, bypassing broadline distributor margins. Geographic supply concentration centers on Thailand for cassava-derived PLA resin, India for sugarcane bagasse fiber, and Nebraska for corn-starch PLA production. Raw material dependencies include agricultural feedstocks, thermoforming equipment, and compostability certification services. Single-source vulnerability in Thai resin supply creates exposure to monsoon-driven crop failures. Distribution runs through manufacturer-direct relationships for national accounts and broadline foodservice distributors for regional restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in CPLA hot-fill formulations as quick-service chains substitute certified compostable containers for petroleum-based clamshells under extended producer responsibility frameworks. Bagasse processing cost-down curves and municipal composting infrastructure buildouts validate premium-tier positioning.
For Market Incumbents: Anticipate CPLA capacity constraints by securing captive resin supply through long-term offtake agreements with Nebraska and Thai producers. Defend against emerging molded fiber specialists by accelerating REACH-compliant oil-barrier coating R&D for European institutional export. Certification breadth across ASTM D6400, BPI, and BIS standards anchors vendor consolidation trends in university and healthcare procurement.
For New Entrants and Emerging Players: Begin with India institutional catering contracts where BIS standards adoption outpaces domestic molded fiber capacity expansion. Gujarat and Maharashtra bagasse supply clusters support cost-competitive positioning against imported PLA alternatives. A go-to-market angle targeting Delhi-NCR and Bangalore metropolitan corporate catering offers white-space penetration before national incumbents establish regional distribution.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap CPLA thermoforming specialists because certification timelines and capital intensity create barriers to greenfield entry. The five-to-ten year viability window favors platforms with backward-integrated bagasse sourcing and multi-certification coverage. Acquisition targets should demonstrate ASTM D6400 or BPI certification and established quick-service restaurant supply relationships. The signal to watch is California SB 54 implementation pace, which determines guaranteed offtake volume availability for certified producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bagasse Sourcing | Captive sugarcane fiber supply from Maharashtra mills insulates margin pressure from agricultural commodity volatility. |
| CPLA Hot-Fill Capacity Expansion | Rhine-Ruhr thermoforming investments capture quick-service fried protein packaging demand under EU Single-Use Plastics Directive. |
| Multi-Certification Coverage Investment | Simultaneous ASTM D6400, BPI, and BIS compliance qualifies vendors for university, healthcare, and Indian institutional RFPs. |
| Municipal Composting Partnership | Guaranteed end-of-life pathway agreements with Pacific Northwest facilities validate customer sustainability investments. |
| REACH-Compliant Barrier Coating R&D | PFAS-free oil-barrier formulations preserve German institutional catering access under ECHA substance restrictions. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with foodservice procurement directors, molded fiber plant managers, composting facility operators, and regulatory compliance officers with secondary validation. Primary sources included ASTM International certification databases, FDA food contact notification filings, and ECHA REACH substance restriction updates. Secondary sources encompassed trade customs data for bagasse fiber and PLA resin, SEC 10-K disclosures from packaging conglomerates, and municipal composting capacity buildout reports. Bottom-up shipment data triangulated against top-down procurement budget surveys.
Segment-weighting approaches modeled material type, container size, end-user category, and distribution channel across the projection horizon. The analytical framework applied penetration curves for CPLA hot-fill adoption, bagasse cost-down trajectories, and municipal infrastructure buildout timelines. CAGRs derived from segment-level volume forecasts weighted by certification premium capture and regional regulatory implementation pace. Industry-specific inputs included quick-service restaurant sustainability pledge timelines and state-level extended producer responsibility enactment schedules.
Several conditions sit outside the modeled scope, including potential PLA resin technology substitutions, breakthrough barrier coating chemistries, and municipal composting contamination protocol changes. Forecasts reflect base-case assumptions regarding certification standard stability and agricultural feedstock supply continuity. Periodic stress-testing of base assumptions is recommended against regulatory delay scenarios and composting facility rejection rate volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Corrugated Bin Boxes Market
Containers
Tin Containers Market
Containers
Old Corrugated Containers (OCC) Market
Containers
Jars Market
Containers
Lever Lid Cans Market
Containers
Foldable Large Containers Market
Containers
Slide Top Tins Market
Containers
Thin Wall Containers Market
Containers
Jerry Cans Market
Containers
Packaging Bins Market
Containers
Collapsible Food Packaging Containers Market
Containers
Pail Lids Market
Containers
Clear Hinged Container Market
Containers
HDPE Bottles Market
Containers
Latin America Intermediate Bulk Container Liner Market
Containers
Takeout Containers Market