
 Rotogravure Printing Cylinder Market | 2026-2036
Rotogravure Printing Cylinder Market Size, Share, and Industry Trends Forecast 2026-2036
Rotogravure Printing Cylinder Market Insights
China is tilting toward domestic cylinder supply as local engraving shops scale laser-based production. Flint Group leverages its ink-cylinder integration to capture bundled contracts across Asia-Pacific flexo-to-gravure conversions. Pamarco sustains North American market presence through specialized anilox and gravure cylinder refurbishment networks. Huber Group anchors European demand with corrosion-resistant coating formulations that extend copper cylinder lifecycles.
Rotogravure printing cylinders are precision-engraved metal rollers, typically copper-plated and chromium-finished, that transfer ink from microscopic cells to substrates in high-speed rotary presses running at 300-600 meters per minute. The cylinder's cell volume and wall angle determine ink laydown accuracy for long-run packaging jobs where color consistency across millions of impressions is mandatory. Steel cylinders dominate volume production for flexible packaging due to structural rigidity at web widths exceeding 1.5 meters, while laser engraving displaces mechanical methods as brands demand shorter runs with faster changeover. Chromium-plated cylinders retain premium positioning in publication and decorative segments where extreme durability justifies higher replacement cycles.
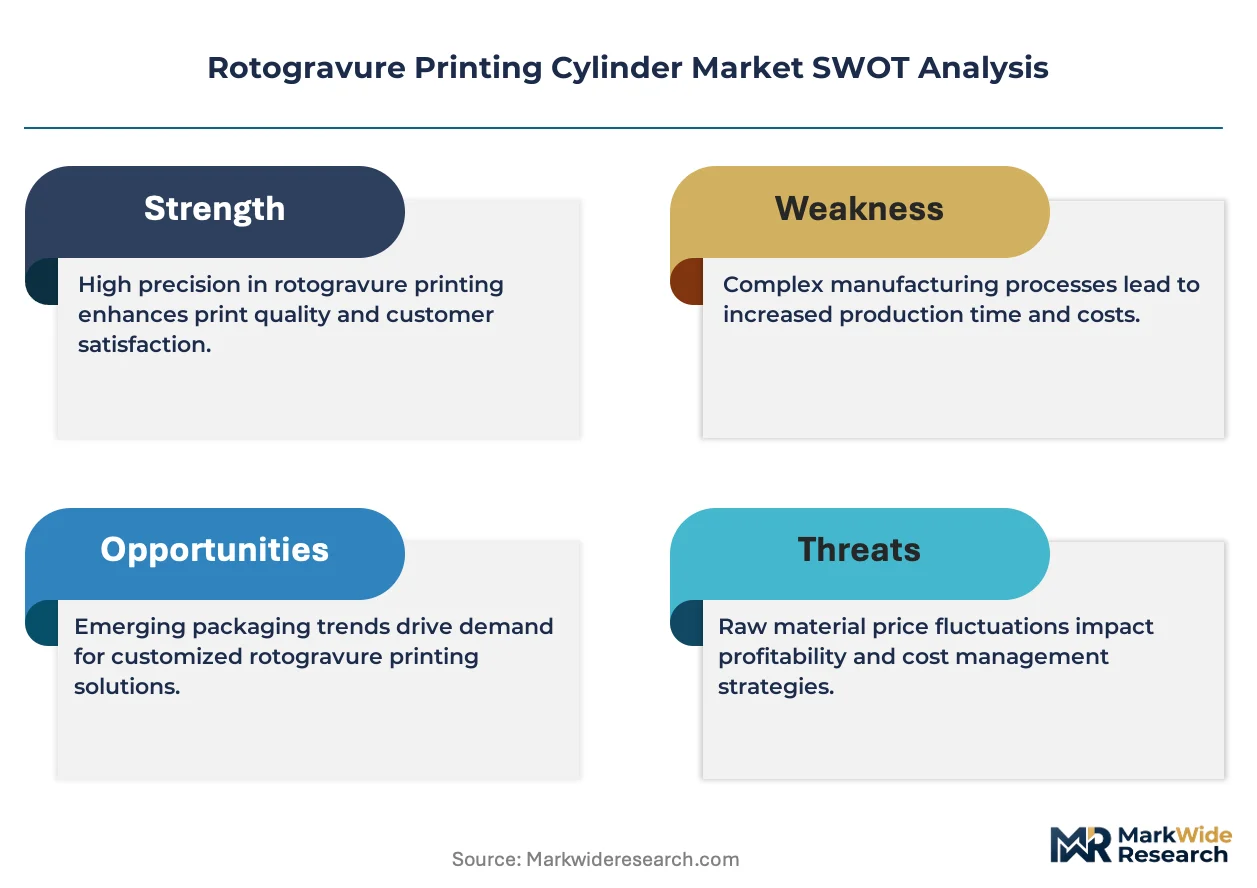
EPA air quality standards and OSHA hexavalent chromium exposure limits in the United States compel cylinder shops to invest in closed-loop plating and exhaust scrubbing systems. REACH restrictions on chromium trioxide in Europe accelerate ceramic and alternative barrier-coating trials among plating houses. China's MEE enforcement of wastewater discharge rules for electroplating clusters forces smaller cylinder producers toward centralized treatment facilities or process outsourcing. Stakeholders must weigh capital intensity against regulatory compliance timelines when evaluating captive engraving versus merchant supply.
Market Dynamics
REACH restrictions on chromium trioxide and OSHA hexavalent chromium exposure limits are compressing plating chemistry choices while laser engraving adoption accelerates run-length flexibility demands from flexible packaging converters.
Growth Catalysts
- Flexible packaging expansion:Snack food and beverage brands in Vietnam and Indonesia are commissioning high-volume gravure lines, pulling cylinder demand toward Southeast Asian production hubs.
- Chrome-free plating chemistry:ECHA's REACH authorization requirements for chromium trioxide are forcing plating houses to commercialize trivalent chrome and ceramic barrier alternatives.
- Laser engraving precision:Digital cell definition at 4000+ lines per inch enables shorter run lengths with faster changeover, matching brand owner just-in-time packaging requirements.
Market Restraints
- Copper price volatility:Electrodeposited copper constitutes 35-45% of raw material input costs, exposing cylinder producers to LME price swings without pass-through contracts.
- Capital intensity barrier:Closed-loop plating and exhaust scrubbing systems required by EPA air quality standards demand $2-4 million per facility upgrade, consolidating supply toward well-capitalized shops.
- Flexographic substitution:Central impression flexo presses with sleeve-based anilox systems are capturing mid-run packaging jobs below five million impressions.
Strategic Opportunities
- Refurbishment services:Copper layer stripping and re-engraving extends cylinder lifecycle, creating recurring revenue streams as European converters face extended replacement cycles.
- China domestic supply gap:Local engraving shops scaling laser-based production present equipment and consumables partnerships for foreign technology licensors.
- Corrosion-resistant coatings:Huber Group's extended-lifecycle formulations demonstrate demand for premium cylinder protection in high-humidity Southeast Asian operating environments.
Industry Challenges
- Skilled engraver shortage:Mechanical engraving expertise is aging out while laser system operation requires combined electromechanical and software competencies that training pipelines have not matched.
- Legacy press integration:Retrofitting 1990s-era rotogravure lines with laser-engraved cylinders demands cell geometry recalibration that many converters lack in-house metrology capability to execute.
- Compliance timeline compression:China's MEE wastewater discharge enforcement for electroplating clusters forces smaller producers toward centralized treatment facilities or process outsourcing within 18-24 month windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotogravure Printing Cylinder Market |
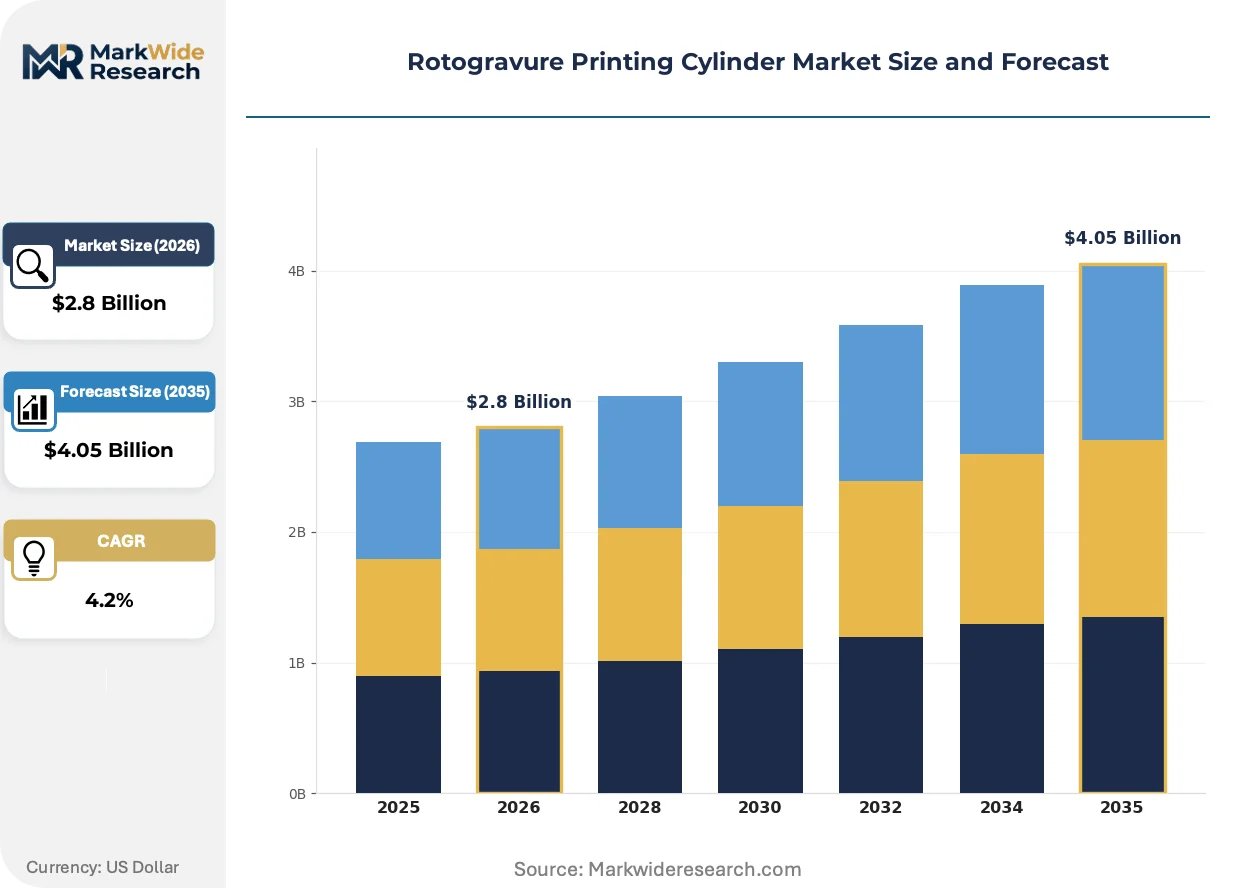
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Cylinder, Copper Cylinder, Chromium-Plated Cylinder, Aluminum Cylinder, Ceramic Cylinder Technology: Mechanical Engraving, Laser Engraving, Chemical Etching, Electroforming, Direct Gravure Application: Flexible Packaging, Label Printing, Security Printing, Decorative Printing, Publication Printing End User: Packaging Manufacturers, Label Producers, Security Firms, Printing Agencies, Publishing Houses |
| Companies Covered | Huber Group, Flint Group, Pamarco, Seamless Cylinder, Rotometal, Meredith-Springfield, Allison Systems, Insta Graphic Systems, Rotoflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotogravure Printing Cylinder Market Trends and Innovations
Electromechanical engraving is yielding to laser-based cell formation while regulatory chemistry constraints and converter procurement model changes are restructuring supplier relationships across the value chain.
Direct laser engraving of copper-plated steel cylinders is collapsing the traditional separation between high-volume mechanical engraving for long runs and digital proofing for short runs. Flexible packaging converters in Indonesia and Vietnam are adopting hybrid press configurations that switch between gravure and flexo units within the same job. This compression eliminates the minimum economic order quantity that historically protected gravure's position in high-volume snack and beverage packaging.
REACH authorization timelines for chromium trioxide are accelerating trivalent chrome and ceramic coating trials among European plating houses. The industrial consequence is a bifurcation between premium publication cylinders retaining hexavalent chrome durability and packaging cylinders migrating to shorter-lifecycle alternatives. Decorative laminate producers in Germany and Italy face the steepest cost increases as their extreme durability requirements resist substitution.
Converter procurement of cylinder engraving is fragmenting from bundled press-maintenance contracts toward spot purchasing from merchant engravers. Brand owner pressure for faster design iteration is compressing the traditional 4-6 week cylinder delivery window toward 10-14 day turnarounds. This behavioral shift concentrates demand in Vietnam and Indonesia where merchant engraving capacity has expanded fastest to serve regional packaging hub requirements.
Rotogravure Printing Cylinder Market Segmentation
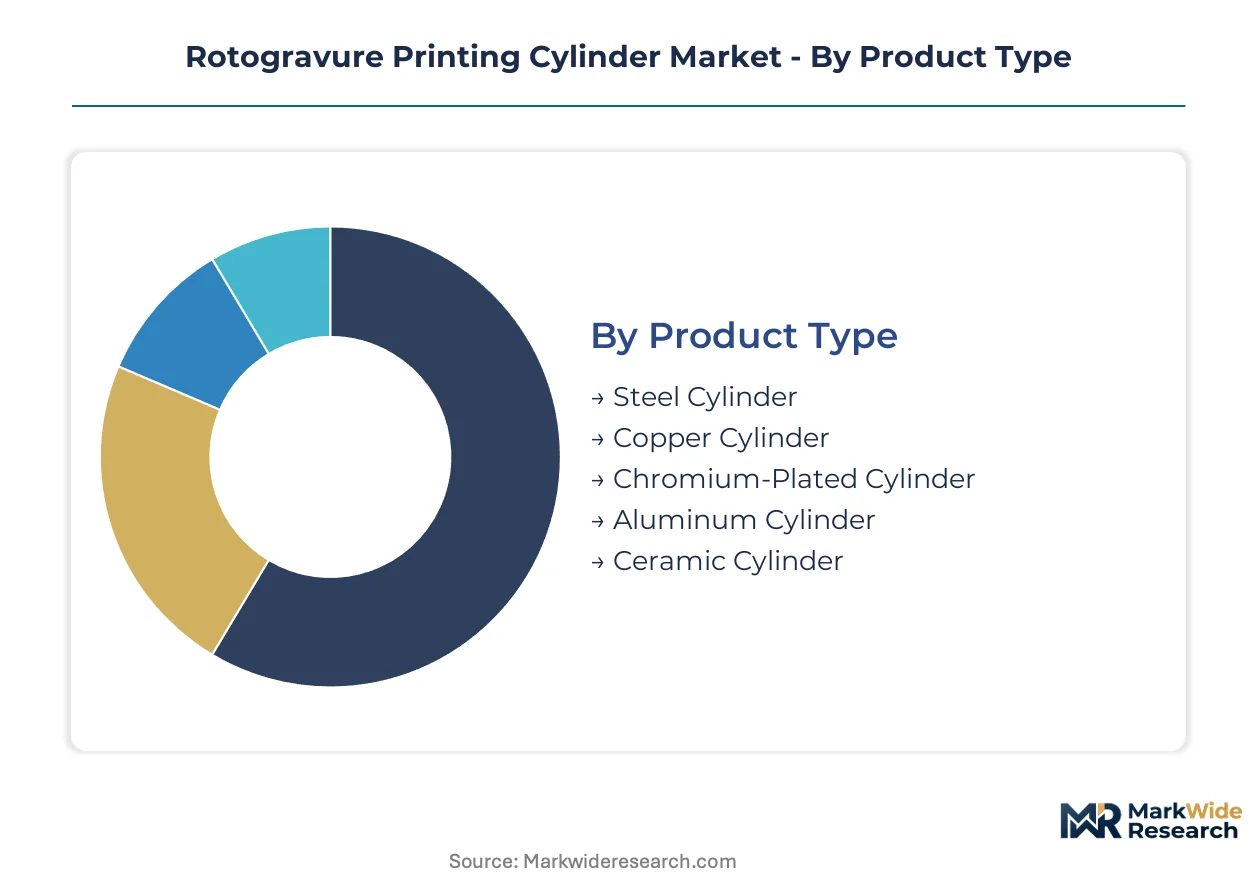
Rotogravure printing cylinder procurement patterns diverge sharply across substrate requirements, engraving precision needs, and regulatory compliance burdens. Understanding these segment boundaries clarifies why steel cylinders dominate flexible packaging while chromium-plated alternatives retain defensive positions in publication and decorative segments.
Product Type:
Mature structural materials coexist with emerging surface-engineered alternatives as converters balance rigidity demands against plating chemistry constraints.
- Steel Cylinder:Carbon or stainless steel substrates provide structural rigidity for web widths exceeding 1.5 meters at press speeds of 300-600 meters per minute. Vietnamese and Indonesian flexible packaging converters are pulling steel cylinder demand toward Southeast Asian production hubs as regional snack food and beverage brands commission high-volume gravure lines.
- Copper Cylinder:Electrodeposited copper layers enable precise cell formation through mechanical or laser engraving methods, with copper constituting 35-45% of raw material input costs. LME price volatility exposes producers to margin compression without pass-through contracts, particularly affecting European plating houses navigating REACH compliance timelines.
- Chromium-Plated Cylinder:Hexavalent chrome finishes deliver extreme durability for publication and decorative segments where replacement cycles extend across millions of impressions.
- Aluminum Cylinder:Lightweight substrates suit narrow-web label presses where reduced rotational inertia enables faster acceleration and deceleration cycles.
- Ceramic Cylinder:Ceramic barrier coatings are emerging as chrome-free alternatives under ECHA REACH authorization requirements for chromium trioxide.
Steel cylinders retain volume leadership; ceramic cylinders hold the steepest expansion curve as chrome-free plating chemistry commercialization accelerates.
Technology:
Cost tier stratification separates capital-intensive digital systems from depreciated mechanical equipment still serving legacy long-run contracts.
- Mechanical Engraving:Diamond stylus systems cut cells into copper surfaces with proven reliability for runs exceeding five million impressions. Skilled engraver expertise is aging out across European and North American shops, creating competency gaps that training pipelines have not matched.
- Laser Engraving:Digital cell definition at 4000+ lines per inch enables shorter run lengths with faster changeover, matching brand owner just-in-time packaging requirements in Vietnam and Indonesia where merchant engraving capacity has expanded fastest.
- Chemical Etching:Acid-based cell formation serves prototype and proofing applications where engraving speed outweighs cell geometry precision.
- Electroforming:Nickel shell reproduction from master cylinders enables simultaneous production of multiple identical rollers for wide-format presses.
- Direct Gravure:Laser ablation directly into steel substrates bypasses copper plating entirely, eliminating hexavalent chrome exposure risks.
Mechanical engraving retains installed base dominance; laser engraving commands the sharpest adoption slope as run-length flexibility demands intensify.
Application:
Customer type differentiation separates commodity packaging converters from security-sensitive end-users with certification-driven procurement protocols.
- Flexible Packaging:Snack food and beverage brands in Southeast Asia are expanding gravure capacity, pulling cylinder demand toward regional production hubs. Hybrid press configurations in Indonesia and Vietnam now switch between gravure and flexo units within the same job, compressing minimum economic order quantities.
- Label Printing:Pressure-sensitive and shrink-sleeve labels demand precise ink laydown across varying substrate thicknesses, with laser-engraved cylinders enabling 10-14 day turnaround windows versus traditional 4-6 week delivery.
- Security Printing:Banknote and document authentication features require microtext and guilloche patterns at resolutions exceeding standard packaging specifications.
- Decorative Printing:Woodgrain and metallic laminate producers in Germany and Italy face steepest cost increases from REACH restrictions as extreme durability requirements resist chrome-free substitution.
- Publication Printing:Magazine and catalog gravure retains hexavalent chrome durability where extended replacement cycles justify premium cylinder positioning.
Flexible packaging retains volume leadership; security printing maintains the most defensible margin structure through certification barriers.
End User:
Supply concentration patterns favor merchant engravers in high-growth geographies over captive engraving operations at legacy converter sites.
- Packaging Manufacturers:Flexible packaging converters in Vietnam and Indonesia are fragmenting procurement from bundled press-maintenance contracts toward spot purchasing from merchant engravers.
- Label Producers:Narrow-web specialists prioritize quick-change sleeve systems compatible with laser-engraved cylinder geometries.
- Security Firms:Central bank and government document printers maintain stringent qualification protocols for cylinder suppliers.
- Printing Agencies:Commercial gravure houses serving multiple brand owners demand refurbishment services to extend cylinder lifecycles.
- Publishing Houses:Magazine and catalog printers face consolidation pressure as digital media displaces print subscription volumes.
Packaging manufacturers retain demand concentration; security firms exhibit the most stable procurement cadence through long-term qualification cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cylinder engraving capacity clusters in Germany, China, Vietnam, Indonesia, and the United States, with each geography presenting distinct regulatory and demand profiles. Local plating chemistry rules and converter procurement patterns are reshaping where production investment flows.
Germany
Decorative laminate and publication printers in Baden-Württemberg and Bavaria sustain demand for hexavalent chrome durability. ECHA REACH authorization requirements for chromium trioxide are accelerating trivalent chrome trials among plating houses in the Stuttgart industrial corridor. Huber Group anchors European corrosion-resistant coating supply from its German base.
China
Domestic engraving shops in the Yangtze River Delta and Pearl River Delta are scaling laser-based production to replace imported cylinders. MEE enforcement of wastewater discharge rules for electroplating clusters is forcing smaller producers toward centralized treatment facilities in Guangdong and Jiangsu provinces. Local supply chains are capturing share from foreign merchants.
Vietnam
Snack food and beverage brands are commissioning high-volume gravure lines in Ho Chi Minh City and Binh Duong province. The country's industrial zone incentives are attracting multinational packaging converters seeking shorter cylinder delivery windows. Merchant engraving capacity has expanded fastest here to serve regional hub requirements.
Indonesia
Flexible packaging converters in Jakarta and Surabaya are adopting hybrid press configurations switching between gravure and flexo units. The national environmental ministry's pending electroplating discharge regulations are pushing cylinder shops toward pre-emptive treatment system investments. Local procurement is fragmenting from bundled contracts toward spot purchasing.
United States
Publication and security printing sustain demand in the Midwest and Northeast corridors. EPA air quality standards and OSHA hexavalent chromium exposure limits compel cylinder shops to invest in closed-loop plating and exhaust scrubbing systems. Pamarco sustains market presence through specialized refurbishment networks.
Rotogravure Printing Cylinder Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in engraving and surface treatment. The vendor base separates into three strata: multinational chemical-coating houses with cylinder-adjacent portfolios, dedicated engraving shops with regional density, and equipment-technology licensors supplying laser systems. Consolidation pressure concentrates in European plating houses facing REACH compliance timelines, while Asian markets fragment around domestic capacity expansion. Competitive moves cluster on chrome-free chemistry commercialization and merchant engraving network buildout.
Within the chemical-coating tier, Huber Group and Flint Group exemplify platform integrators leveraging corrosion-resistant formulations and ink-cylinder bundling respectively. Pamarco occupies a position among dedicated specialists with North American refurbishment density. These three represent distinct archetypes: formulation-led extension, supply-chain integration, and service-network geographic concentration. Each anchors a different competitive vector without overlapping core positioning.
| Leading Market Players |
|---|
| Huber Group |
| Flint Group |
| Pamarco |
| Seamless Cylinder |
| Rotometal |
| Meredith-Springfield |
| Allison Systems |
| Insta Graphic Systems |
| Rotoflex |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Vietnamese merchant engraving shops is compressing cylinder delivery premiums and forcing European plating houses to absorb REACH compliance costs rather than pass them through. This utilization imbalance rewards spot purchasing from Southeast Asian converters while penalizing legacy bundled contracts.
Pricing Analysis
REACH authorization requirements for chromium trioxide dictate the pricing tier structure across European cylinder supply. Three-tier pricing structure across premium hexavalent chrome, standard trivalent chrome, and economy ceramic barrier levels separates publication durability from packaging flexibility. Cost compression in mid-tier copper plating is intensifying because LME price volatility lacks pass-through mechanisms in legacy converter contracts. Flexible packaging manufacturers exhibit highest price sensitivity due to hybrid press substitution options; security printers show lowest sensitivity through long-term qualification lock-ins.
Supply Chain Analysis
Extended payment terms from Indonesian snack food brands are forcing merchant engravers to absorb working capital strain or seek supply-chain finance facilities. Geographic supply concentration rests on Germany for hexavalent chrome expertise, China for laser engraving equipment, and Vietnam for merchant capacity expansion. Raw material dependencies center on electrodeposited copper, chromium plating chemistry, and precision steel substrates. Single-source vulnerability runs through German decorative laminate cylinder supply where REACH timelines compress alternative qualification windows. Distribution runs through direct converter relationships in Southeast Asia and bundled press-maintenance contracts in legacy European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rotogravure printing cylinder market is entering a cyclical recovery phase as Southeast Asian packaging hub investment absorbs regional overcapacity. Flexible packaging converter capital expenditure cycles drive this inflection.
For Market Incumbents: Pre-empt flexographic substitution by accelerating chrome-free chemistry commercialization ahead of ECHA authorization deadlines. Consolidate Vietnamese merchant engraving networks to capture spot purchasing volume migrating from bundled contracts. Huber Group's coating formulation leverage demonstrates how corrosion-resistant R&D investment defends margin position against ceramic barrier entrants. For New Entrants and Emerging Players: Pursue refurbishment service contracts in European markets where extended replacement cycles create recurring revenue white space. Target German decorative laminate producers facing steepest REACH cost increases with trivalent chrome qualification partnerships. Laser engraving equipment licensing to Yangtze River Delta shops offers the most penetrable go-to-market angle as domestic supply gaps persist. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across laser engraving sub-segments as equipment costs depreciate and software competencies commoditize. Long-term viability favors plating houses with closed-loop treatment infrastructure already deployed. Acquisition target archetype: Vietnamese merchant engravers with multinational converter relationships and pre-qualified environmental compliance. The signal to watch is Indonesia's pending electroplating discharge regulations accelerating pre-emptive treatment investments.| Strategic Initiative | Industry Significance |
|---|---|
| Chrome-Free Chemistry Commercialization | ECHA REACH timelines force trivalent chrome and ceramic barrier trials ahead of authorization deadlines. |
| Merchant Engraving Network Expansion | Vietnamese and Indonesian spot purchasing growth rewards regional capacity buildout over bundled contracts. |
| Laser Engraving Equipment Licensing | Chinese domestic supply gaps present technology transfer opportunities for foreign system providers. |
| Refurbishment Service Development | European extended replacement cycles create recurring revenue streams from copper stripping and re-engraving. |
| Closed-Loop Plating Infrastructure | EPA air quality standards and MEE wastewater rules consolidate supply toward compliant facilities. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cylinder engraving shop managers, flexible packaging converter procurement leads, plating house technical directors, and OEM press manufacturers; and secondary validation through customs trade data, ECHA REACH authorization filings, SEC equipment supplier disclosures, and regional environmental ministry enforcement notices. Bottom-up demand modeling from converter capacity expansion announcements was triangulated against top-down supply estimates from plating chemistry consumption patterns.
Forecast inputs considered cylinder procurement by product type, engraving technology, application segment, and end-user category across the projection horizon. CAGRs were derived from segmented growth rate analysis weighted by regional packaging hub investment intensity. Industry-specific inputs included laser engraving adoption curves in Southeast Asia and REACH compliance cost absorption rates among European plating houses.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic engraving shops or accelerated ceramic barrier commercialization would shift outcomes. Macroeconomic deviation in copper pricing, regulatory acceleration in Indonesia's electroplating discharge rules, or technological breakthrough in direct steel laser ablation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Global Pre Print Flexo Press Market
Packaging Printing
Stamping Foils Market
Packaging Printing
LAMEA Label Printing Software Market
Packaging Printing
Heat Transfer Press Printing Machine Market
Packaging Printing
Digital Label Printing Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Flexographic Printing Market
Packaging Printing
Soft Signage Market
Packaging Printing
Laser Coders Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Thermal Transfer Overprinter Market
Packaging Printing
Global Electrophotographic Printing in Packaging Market
Packaging Printing
Label Printers Market
Packaging Printing
Asia-Pacific Digital Printing Packaging Market
Packaging Printing
Europe Printed Packaging Market
Packaging Printing
North America Thermal Transfer Overprinter Market