
 Packaging Machine Heaters Market | 2026-2036
Packaging Machine Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Machine Heaters Market Analytics
European ceramic heater foundry capacity is shifting toward modular cartridge designs for form-fill-seal machines. Watlow Electric Manufacturing leverages its vertically integrated mineral-insulated cable operations to sustain delivery timelines for OEM retrofits. Chromalox Inc. anchors North American aftermarket demand through an extensive distributor network serving food packaging plants.
Packaging machine heaters are precision thermal elements, typically constructed from nickel-chromium resistance wire encased in stainless steel sheaths or ceramic cores, engineered to deliver controlled heat output between 100°C and 600°C for sealing, shrink-wrapping, and thermoforming operations in continuous production environments. Cartridge heaters dominate installed base volumes due to their cylindrical form factor compatibility with sealing jaws on vertical and horizontal flow wrappers. Infrared technology captures expanding share in high-speed beverage lines where non-contact heating reduces film contamination risk and enables faster line changeovers.
FDA food-contact safety standards and EU Machinery Directive 2006/42/EC compliance requirements shape material selection and thermal response verification protocols for equipment sold into regulated end uses. EPA energy efficiency guidelines for industrial process heat in the United States add secondary design constraints on watt density and insulation specifications. Stakeholders must weigh total cost of ownership against retrofit compatibility when specifying heater replacements across aging packaging fleets.
Market Dynamics
Pharmaceutical serialization mandates and EU F-Gas phase-down schedules are forcing simultaneous thermal capacity expansion and energy source conversion across installed packaging fleets. OEMs face compressed retrofit windows as converters balance compliance deadlines against production continuity.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating electric infrared adoption in beverage and food sealing lines across Germany, France, and Italy.
- Pharmaceutical serialization:Track-and-trace mandates in the United States and European Union are driving thermal sealing capacity additions on existing blister and bottle packaging lines.
- Ceramic heater modularity:Cartridge heater foundries in Germany are retooling toward standardized form-fill-seal machine interfaces to reduce OEM lead times.
Market Restraints
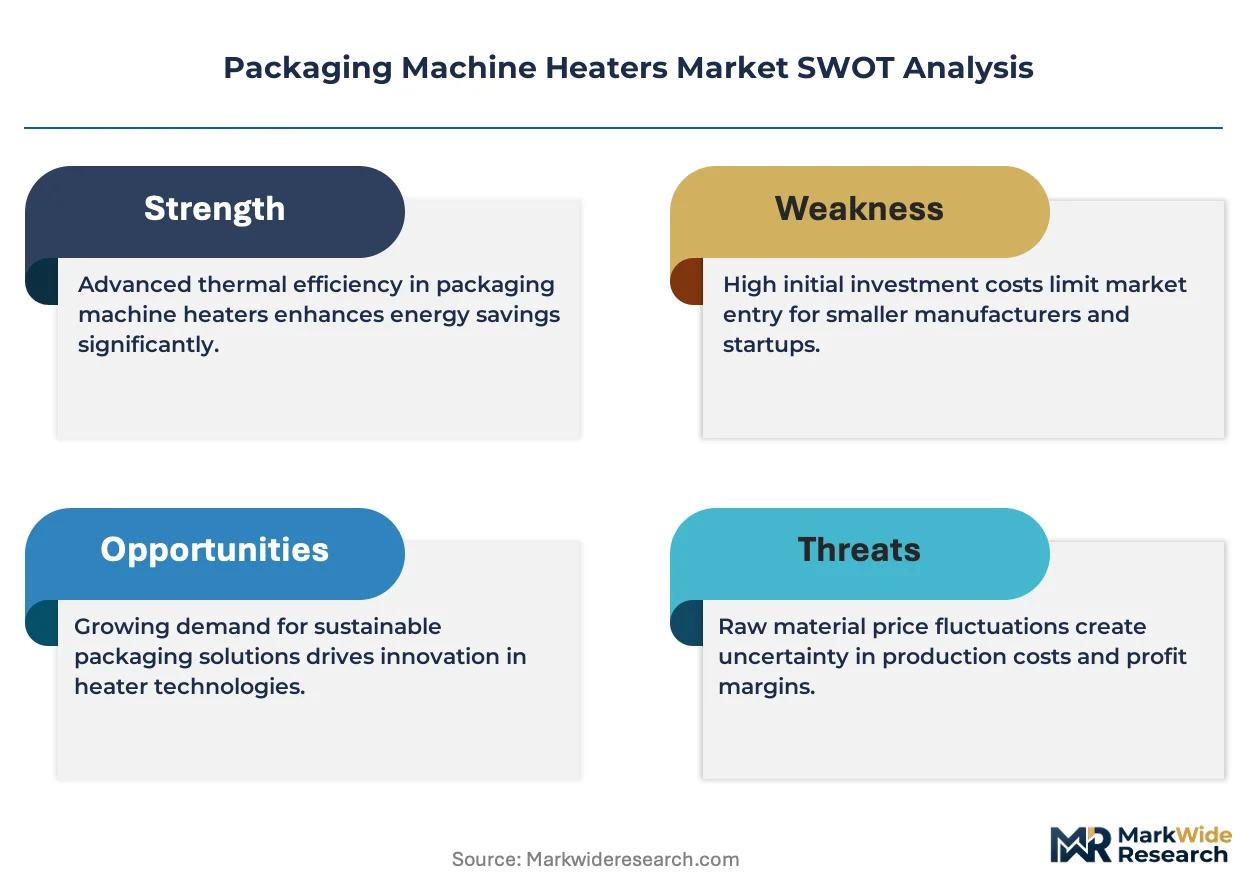
- Nickel-chromium supply concentration:Resistance wire sourcing depends on a narrow supplier base in China and Russia, exposing heater manufacturers to alloy price volatility and export control risk.
- Gas infrastructure lock-in:Converters with sunk capital in natural gas distribution systems face elevated switching costs to electric infrared despite F-Gas compliance pressure.
- Watt density thermal limits:Stainless steel sheath materials impose hard ceilings on heat flux output, constraining line speed gains in high-throughput thermoforming applications.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO serialization deadlines and PLI scheme incentives are creating first-mover openings for electric heater suppliers in Mumbai and Hyderabad manufacturing corridors.
- Non-contact infrared convergence:Integration of quartz halogen elements with machine vision systems enables real-time temperature profiling for delicate film substrates.
- Aftermarket service unbundling:Predictive maintenance contracts based on thermal element degradation curves are emerging as a separate revenue stream distinct from hardware sales.
Industry Challenges
- Thermal engineering talent scarcity:OEMs and end-users compete for specialists capable of integrating multi-zone temperature control with legacy PLC architectures.
- CE marking timeline compression:EU Machinery Directive 2006/42/EC conformity assessment for modified sealing stations now averages fourteen months, delaying retrofit revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Machine Heaters Market |
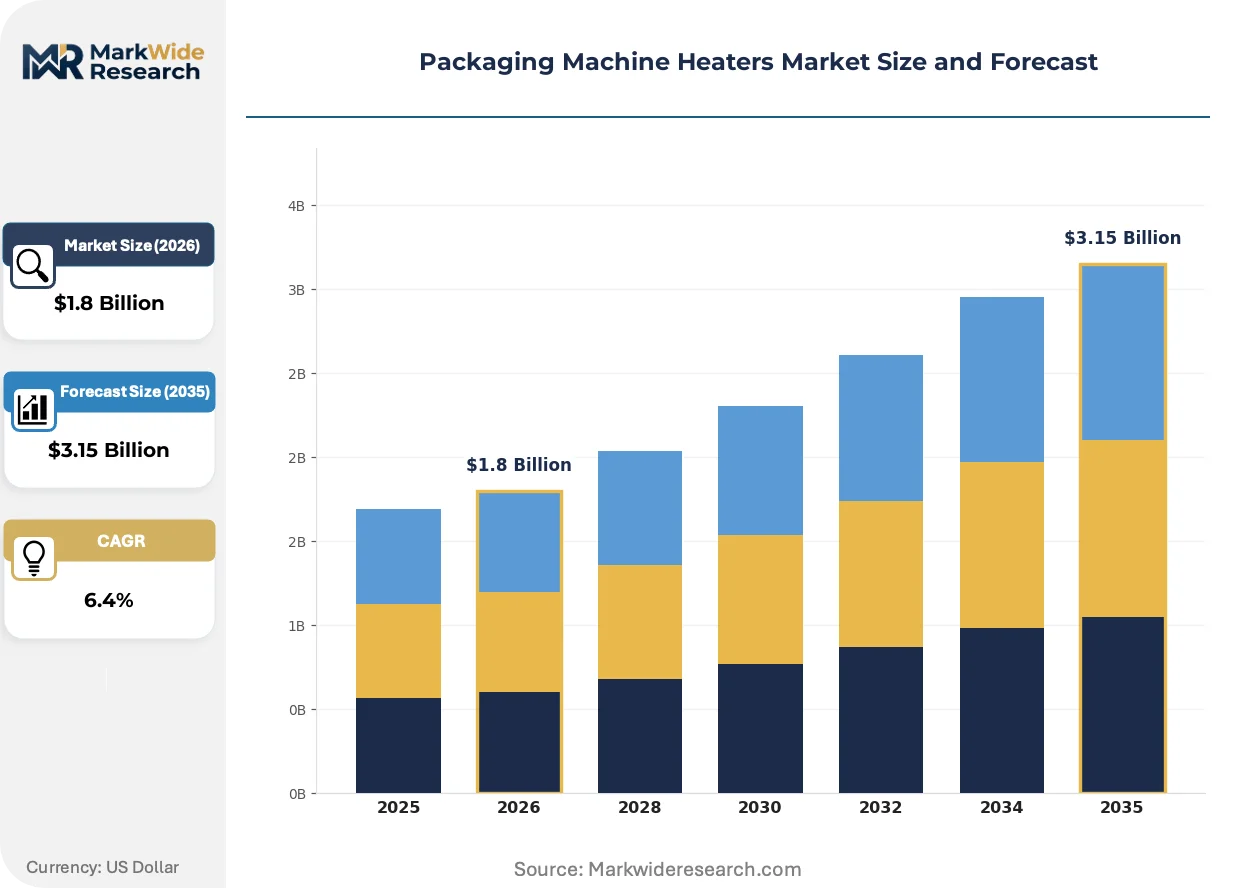
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Infrared, Conduction, Convection, Induction Product Type: Heat Guns, Cartridge Heaters, Band Heaters, Flexible Heaters End User: Food, Beverage, Pharmaceuticals, Electronics Installation Type: Fixed, Portable, Integrated, Standalone |
| Companies Covered | Watlow Electric Manufacturing, Tempco Electric Heater, Chromalox Inc., Backer Hotwatt, Tutco Heating Solutions Group, Heatron Inc., OMEGA Engineering, DBK Group, Thermal Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Machine Heaters Market Evolving Landscape
Electrification of industrial process heat and predictive thermal management are converging to reshape equipment specification criteria. Buyers now prioritize total energy cost and uptime predictability over upfront capital expenditure.
Quartz halogen infrared emitters deliver rapid thermal response for high-speed flow wrapper sealing jaws without mechanical contact. Beverage converters in Germany and the Netherlands are retrofitting gas-powered stations at accelerated pace. Electric infrared is expanding into thermoforming applications previously dominated by conductive heating, compressing the addressable market for traditional cartridge elements.
EPA energy efficiency guidelines for industrial process heat are tightening watt density and insulation specifications for equipment sold into United States food packaging plants. The rules now require documented thermal response verification protocols that extend engineering cycles. North American OEMs are responding by pre-certifying modular heater subassemblies to accelerate customer compliance timelines.
Maintenance procurement is consolidating under centralized technical procurement functions at multinational food and pharmaceutical groups. Regional plant engineers lose autonomy over heater replacement specifications, forcing suppliers to engage corporate engineering standards committees. This shift is most visible in Germany, where Düsseldorf-based packaging groups now mandate cross-site spare part harmonization.
Packaging Machine Heaters Market Segmentation
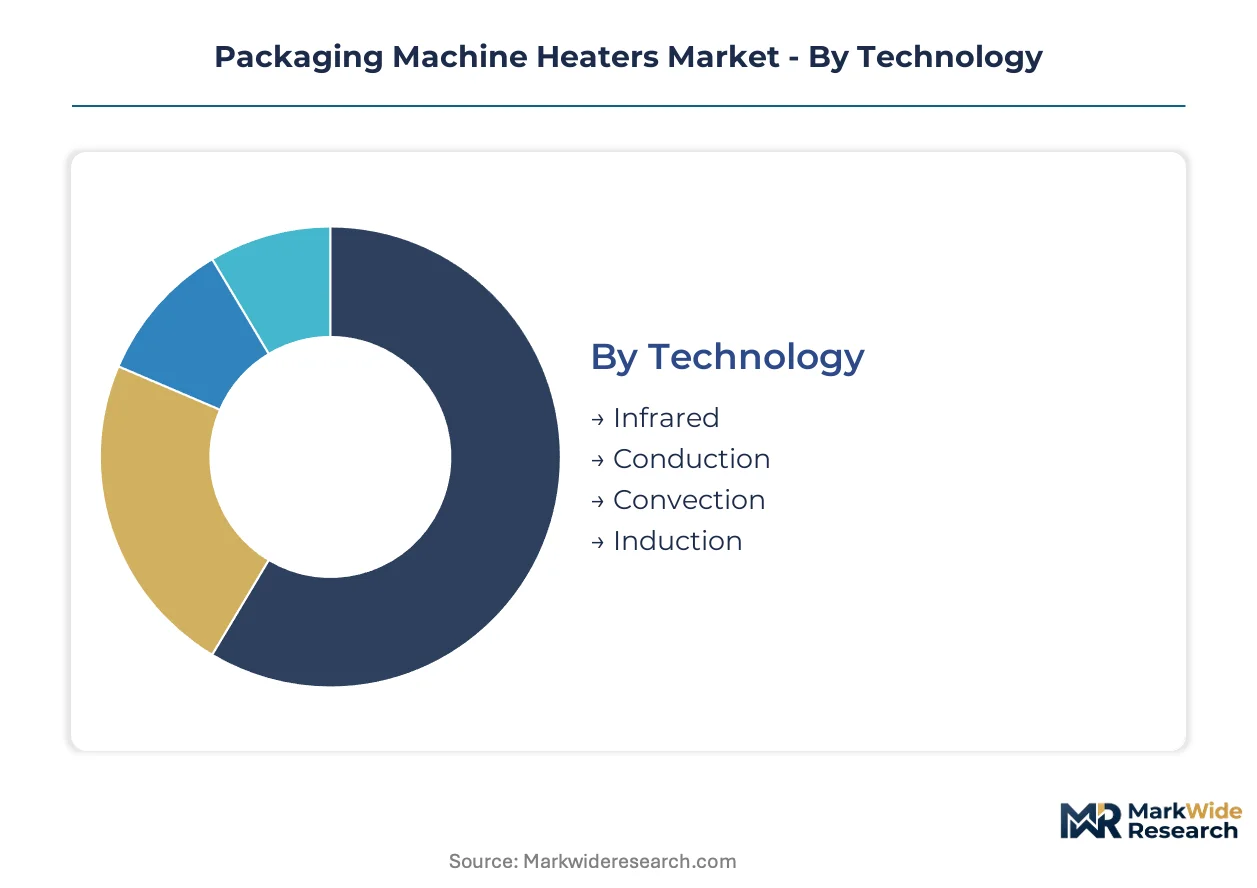
Packaging machine heater specification hinges on thermal response requirements, retrofit compatibility, and energy source constraints. Buyers prioritize watt density limits, sealing speed targets, and compliance with FDA food-contact or EU Machinery Directive standards when selecting across these four dimensions.
Technology:
Cost tier separates buyers seeking premium thermal precision from those optimizing capital expenditure on legacy infrastructure.
- Infrared:Quartz halogen and ceramic emitters deliver non-contact radiant heat between 200°C and 800°C for high-speed beverage sealing lines. German and Dutch converters are retrofitting gas stations to electric infrared ahead of EU F-Gas phase-down deadlines.
- Conduction:Direct surface contact through metal-sheathed elements provides precise temperature control for pharmaceutical blister packaging. Demand concentrates in serialization-mandated lines where thermal sealing integrity directly impacts track-and-trace compliance.
- Convection:Forced-air systems circulate heated air for shrink-wrapping operations on irregular product geometries. Food packaging plants in the United States specify these for tray-sealing applications under EPA energy efficiency guidelines.
- Induction:Electromagnetic field heating enables rapid, localized energy delivery without thermal mass. Electronics manufacturers deploy these for moisture-sensitive component packaging where contamination control is critical.
Conduction leads volumes today; infrared is gaining share fastest.
Product Type:
Application environment dictates form factor selection, from confined sealing jaws to expansive thermoforming surfaces.
- Cartridge Heaters:Cylindrical nickel-chromium elements encased in stainless steel sheaths insert into drilled bores on sealing jaws. These dominate vertical and horizontal flow wrapper retrofits across Germany's Düsseldorf and Stuttgart OEM clusters.
- Band Heaters:Mica-insulated or ceramic-insulated rings wrap around cylindrical surfaces for barrel and platen heating. Pharmaceutical bottle capping lines in the United States specify these for consistent thread seal thermal profiles.
- Heat Guns:Handheld or fixtured forced-air tools deliver directed thermal streams for shrink-sleeve applications. Beverage converters use these for secondary packaging where line flexibility outweighs energy efficiency.
- Flexible Heaters:Etched-foil or wire-wound polyimide/silicone constructions conform to curved thermoforming molds. Electronics packaging for curved display panels drives specification in South Korean and Japanese manufacturing corridors.
Cartridge heaters anchor installed base volumes; flexible heaters are expanding most quickly in display electronics.
End User:
Volume scale and regulatory intensity vary sharply across these four verticals, with pharmaceuticals demanding the most rigorous thermal validation protocols.
- Food:Thermoforming and tray-sealing operations require FDA-compliant materials and documented thermal response curves. EPA watt density rules constrain equipment specification for United States frozen and fresh food packaging plants.
- Beverage:High-speed flow wrapper and shrink-sleeve lines prioritize line changeover speed and film contamination avoidance. EU F-Gas Regulation is accelerating electric infrared adoption across German, French, and Italian bottling facilities.
- Pharmaceuticals:Blister sealing and bottle capping demand precise temperature control for serialization compliance. CDSCO mandates in India are creating first-mover demand in Mumbai and Hyderabad manufacturing zones.
- Electronics:Moisture barrier bag sealing and anti-static packaging require clean thermal delivery without particulate generation. Japanese and South Korean semiconductor packaging lines specify induction and infrared for contamination-sensitive environments.
Food packaging commands the largest installed base; pharmaceutical applications are climbing the fastest on serialization investment cycles.
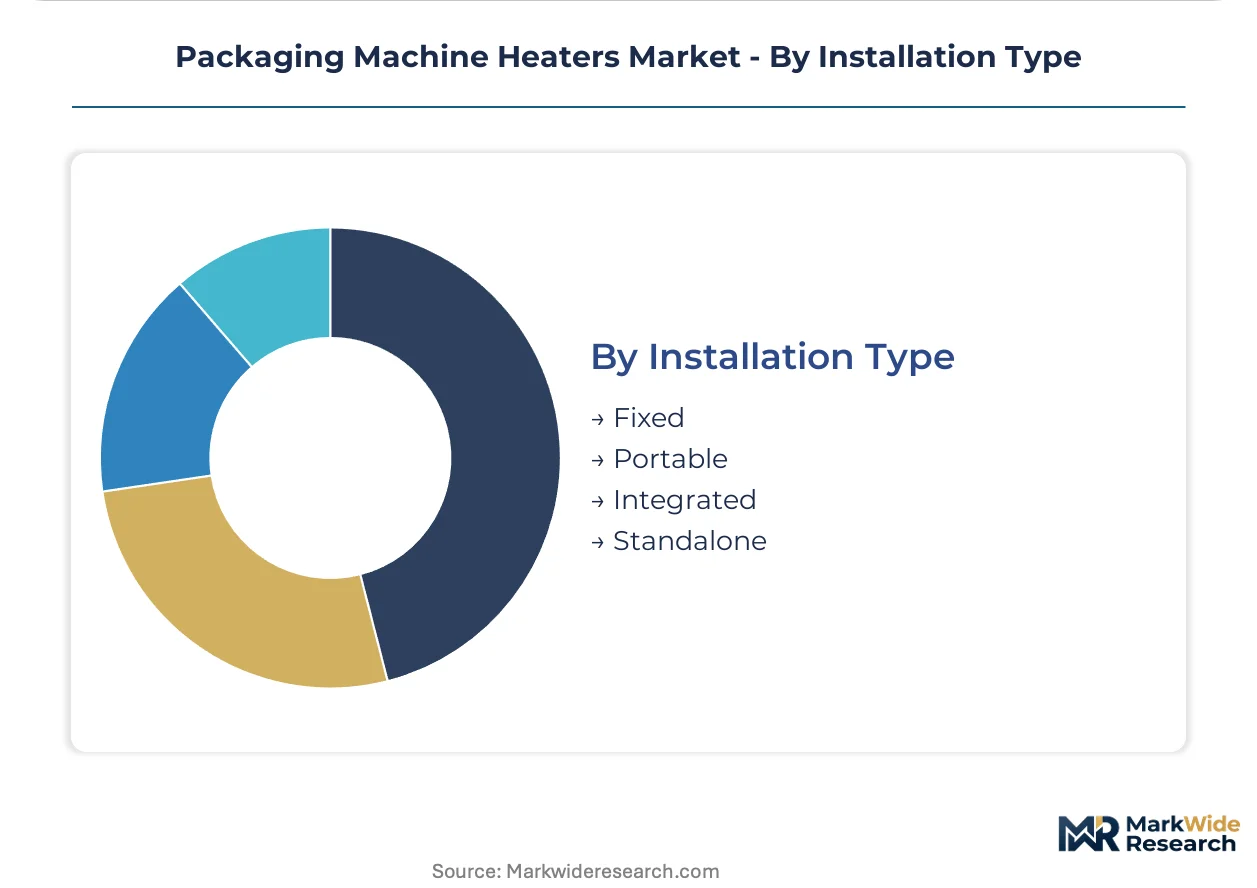
Installation Type:
Customer type distinguishes multinational fleet standardization from single-plant retrofit flexibility requirements.
- Fixed:Permanently mounted elements integrated into original equipment designs during manufacturing. OEM pre-certification of modular heater subassemblies is accelerating under EPA and EU Machinery Directive compliance pressures.
- Integrated:Heater assemblies built into machine frames with shared control architectures and multi-zone thermal management. These dominate new form-fill-seal machine builds where predictive maintenance contracts are bundled.
- Standalone:Self-contained heating units with independent power and control systems for auxiliary operations. Regional food packaging plants specify these for seasonal capacity expansion without line reconfiguration.
- Portable:Mobile heater systems for maintenance, prototyping, or temporary production line supplementation. Aftermarket service providers in North America deploy these for emergency thermal sealing jaw repairs.
Fixed installation dominates OEM shipments; integrated systems are gaining share fastest on predictive maintenance bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping heater procurement patterns as pharmaceutical and beverage converters relocate capacity to jurisdictions with compressed compliance timelines or subsidized electrification programs.
United States
Pharmaceutical serialization mandates from FDA are driving thermal sealing retrofits across New Jersey and North Carolina packaging corridors. EPA watt density rules for industrial process heat constrain equipment specification for frozen food plants in the Midwest. Chicago-area OEMs are pre-certifying modular heater subassemblies to accelerate customer compliance timelines.
Germany
EU F-Gas Regulation phase-down deadlines are accelerating electric infrared adoption in beverage bottling facilities. CE marking timelines under EU Machinery Directive 2006/42/EC now average fourteen months for modified sealing stations. Düsseldorf and Stuttgart OEM clusters are retooling cartridge heater foundries toward standardized form-fill-seal machine interfaces.
India
CDSCO serialization deadlines and PLI scheme incentives are creating first-mover demand for electric heater suppliers. Mumbai and Hyderabad manufacturing corridors are scaling pharmaceutical packaging thermal capacity. The country's national pharmaceutical regulator is tightening track-and-trace compliance verification protocols.
China
Dual carbon goals and GB standards for industrial energy efficiency are pressuring converters toward electric process heat. Yangtze River Delta packaging machinery builders are integrating predictive thermal management into form-fill-seal designs. Shanghai-area foundries are expanding mineral-insulated cable capacity for cartridge heater exports.
Japan
Electronics packaging for semiconductor and display manufacturers drives specification of contamination-sensitive thermal solutions. METI efficiency guidelines favor induction and infrared for moisture barrier bag sealing in Kyushu manufacturing zones. Osaka-based machinery OEMs are bundling predictive maintenance contracts with integrated heater assemblies.
Packaging Machine Heaters Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular retrofit compatibility and predictive service bundling. The market structure reflects moderate consolidation around vertically integrated resistance wire suppliers and regional distributor networks. Three archetypes dominate: mineral-insulated cable specialists, ceramic foundry operators, and infrared emitter fabricators. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs compress retrofit windows.
Among North American fabricators, Watlow Electric Manufacturing exemplifies vertical integration into mineral-insulated cable operations. Chromalox Inc. anchors aftermarket positioning through extensive distributor networks. Tempco Electric Heater occupies a position within the standard-tier cartridge heater segment serving food packaging retrofits.
| Leading Market Players |
|---|
| Watlow Electric Manufacturing |
| Tempco Electric Heater |
| Chromalox Inc. |
| Backer Hotwatt |
| Tutco Heating Solutions Group |
| Heatron Inc. |
| OMEGA Engineering |
| DBK Group |
| Thermal Corporation |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation compliance gates qualified supply access and premium-tier pricing power for electric infrared systems, forcing converters to pay certification premiums for CE-marked mineral-insulated cable assemblies while locking out uncertified foundries from pharmaceutical and beverage retrofit contracts.
Pricing Analysis
Distributor margins of fifteen to twenty-five percent separate standard-tier cartridge heater transactions from direct-to-OEM volume discounts on integrated infrared assemblies. Three-tier pricing structure across premium, standard, and economy levels reflects watt density certification, FDA food-contact compliance, and predictive maintenance bundling. Cost compression in standard-tier conduction heaters is intensifying because Chinese resistance wire suppliers are expanding stainless steel sheath foundry capacity. Regional food packaging plants in the United States Midwest exhibit highest price sensitivity due to EPA energy efficiency retrofit mandates, while German pharmaceutical OEMs prioritize thermal response precision over unit cost.
Supply Chain Analysis
Workforce scarcity for thermal engineering specialists in Germany's Düsseldorf and Stuttgart corridors is extending OEM lead times and compressing foundry utilization rates. Supply concentrates in China for nickel-chromium resistance wire, Germany for mineral-insulated cable fabrication, and the United States for ceramic core cartridge assembly. Raw material flows draw from Russian and Indonesian nickel mining operations, Japanese precision wire drawing, and domestic stainless steel sheet rolling. Single-source vulnerability in nickel-chromium alloy supply exposes heater manufacturers to export control disruption. Distribution runs through authorized distributor networks for aftermarket cartridge replacement, with direct OEM supply agreements dominating integrated system shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The packaging machine heaters market compounds steadily as pharmaceutical serialization mandates and EU F-Gas electrification deadlines sustain replacement demand across aging installed fleets.
For Market Incumbents: Hedge nickel-chromium supply disruption through backward integration into mineral-insulated cable operations or long-term offtake contracts with Russian and Indonesian mining consortia. Defend against quartz halogen infrared displacement by pre-certifying modular cartridge subassemblies under compressed EU Machinery Directive timelines. Prioritize predictive maintenance contract bundling to capture recurring revenue streams distinct from hardware commoditization. For New Entrants and Emerging Players: Launch via direct technical sales to pharmaceutical packaging OEMs in India's Mumbai and Hyderabad corridors, where CDSCO serialization deadlines create first-mover openings without entrenched incumbent relationships. Target standalone portable heater systems for North American aftermarket emergency repair, bypassing integrated system certification barriers. Penetrate through ceramic heater modularity for form-fill-seal machine retrofits, offering standardized interfaces that reduce OEM engineering cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among mineral-insulated cable specialists with captive resistance wire supply and established CE marking protocols. Long-term viability over a five-to-ten year window rests on electrification tailwinds from industrial decarbonization mandates and pharmaceutical track-and-trace expansion. Target acquisition archetypes combine vertical integration into alloy sourcing with installed base lock-in through predictive service contracts. Watch for inflection in nickel export control severity as the primary signal for supply-side margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral-Insulated Cable | Watlow Electric Manufacturing's captive cable operations sustain delivery timelines for OEM retrofits under EU F-Gas deadlines. |
| Predictive Maintenance Contract Bundling | Osaka-based machinery OEMs lock in recurring revenue through thermal element degradation curve monitoring for semiconductor packaging lines. |
| CE Marking Pre-Certification of Modular Subassemblies | Chicago-area OEMs compress fourteen-month conformity assessment timelines for EPA-compliant frozen food plant retrofits. |
| Geographic Expansion into Indian Pharmaceutical Corridors | CDSCO serialization mandates in Mumbai and Hyderabad create first-mover demand for electric heater suppliers without incumbent entrenchment. |
| Long-Term Nickel-Chromium Supply Agreement | Heater manufacturers anchor alloy cost stability against Russian and Indonesian export control volatility. |
Research Methodology
Coverage spans the United States, Germany, India, China, and Japan, with primary inputs from each market combining structured interviews with thermal engineering directors at packaging OEMs, maintenance procurement leads at multinational food and pharmaceutical groups, ceramic heater foundry operators, and aftermarket service providers. Secondary validation draws from EPA energy efficiency filings, EU Machinery Directive conformity assessment databases, CDSCO serialization compliance notices, and customs trade data for nickel-chromium alloy shipments. Bottom-up demand modeling for cartridge and infrared heater unit shipments triangulates against top-down packaging machinery production forecasts.
Granularity-level modeling disaggregates demand across technology type, product form factor, end-use vertical, and installation configuration throughout the forecast period. Segmentation dimensions include conduction versus infrared versus convection versus induction heat transfer modes; cartridge, band, heat gun, and flexible heater geometries; food, beverage, pharmaceutical, and electronics end-use applications; and fixed, integrated, standalone, and portable mounting approaches. CAGRs derive from fitted growth curves applied to retrofit cycle analysis and regulatory deadline clustering. Industry-specific forecast inputs incorporate EU F-Gas phase-down schedules, pharmaceutical serialization mandate timelines, and EPA watt density rule implementation trajectories.
Several conditions sit outside the modeled scope, including abrupt nickel export embargoes, accelerated EU Machinery Directive revision cycles, and breakthrough induction heating cost parity in thermoforming applications. Forecasts reflect assumptions around regulatory deadline adherence, alloy price stability, and OEM retrofit capacity availability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Carton Erecting Machinery Market
Packaging Machinery
Paper Slitting Machine Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Vacuum Chamber Packaging Machines Market
Packaging Machinery
Lid Applicator Machine Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Form-Fill-Seal (FFS) Packaging Machine Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Blind Box Machine Market
Packaging Machinery
Automatic Banding Machine Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Liquid Pouch Filling and Sealing Machine Market
Packaging Machinery
Tamper Evidence Machinery Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
Bundling Machine Market
Packaging Machinery
Binding & Lamination Machines Market