
 Flexographic Printing Machine Market | 2026-2036
Flexographic Printing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Flexographic Printing Machine Market Intelligence
Buyer concentration among flexible packaging converters is pivoting toward mid-tier regional players as multinational food brands fragment sourcing across multiple suppliers. Bobst leverages its integrated die-cutting and printing platforms to anchor premium installations in European folding carton plants. Mark Andy Inc. sustains narrow-web dominance through servo-driven press architectures that serve craft beverage label producers. Nilpeter A/S specializes in hybrid flexo-digital configurations that compete for short-run pharmaceutical labeling contracts.
A flexographic printing machine employs a flexible photopolymer plate wrapped around a rotating cylinder to transfer ink onto substrates ranging from plastic films to corrugated board, typically operating at web speeds exceeding 300 meters per minute for high-volume packaging production. Central impression presses dominate flexible packaging for their register accuracy across multiple color stations, while inline type configurations capture corrugated carton applications where board stiffness demands sequential processing. UV curing technology leads margin pools in food-compatible printing as brands eliminate solvent-based systems to meet migration limits, though laser engraving of anilox rolls is displacing mechanical engraving for finer cell geometries.
FDA migration thresholds for food-contact materials and EPA volatile organic compound rules shape ink formulation and drying system investments across US installations, while REACH compliance in Europe restricts photoinitiator chemistries in UV-curable inks. The EU Green Deal packaging waste directives are forcing converters to validate recyclable mono-material structures, which alters tension control and drying parameters on existing press lines. Stakeholders must monitor how anilox specification standards evolve under ISO frameworks as water-based ink rheology demands tighter volume tolerance bands.
Market Dynamics
Flexible packaging converters in Germany and the US are reconfiguring press lines to handle mono-material recyclable films, forcing retrofits of tension control systems and drying architectures originally engineered for multi-layer laminates.
Growth Catalysts
- EU Green Deal packaging waste directives:Mandates for recyclable mono-material structures are pulling investment into press lines capable of processing thinner gauge films without registration drift.
- Water-based ink rheology advances:Tighter anilox volume tolerances under evolving ISO standards are enabling food-contact compliant output without solvent recovery infrastructure.
- Stuttgart machinery cluster:Concentrated engineering talent around Baden-Württemberg is shortening delivery cycles for integrated press-diecutting lines serving multinational converters.
Market Restraints
- Photopolymer plate cost volatility:Raw material exposure to petrochemical feedstocks compresses margin for short-run job shops unable to amortize plate costs across long campaigns.
- Anilox roll supply concentration:Laser engraving equipment and ceramic coating capacity clusters in southern Germany and northern Italy, creating bottleneck risk for North American rebuild schedules.
- UV LED curing technical limitation:Lower energy density versus arc systems restricts line speeds on high-opacity white applications, segmenting addressable substrate thickness ranges.
Strategic Opportunities
- India flexible packaging expansion:FSSAI food-contact compliance requirements and PLI scheme incentives for packaging machinery are creating first-mover advantage for servo-press installations in Maharashtra and Gujarat.
- Hybrid flexo-digital convergence:Integration of inkjet modules for variable data onto central impression architectures captures pharmaceutical serialization contracts with batch sizes below 5,000 linear meters.
- Direct-to-converter channel restructuring:Bypassing traditional machinery distributors through manufacturer-owned technical service hubs shortens commissioning cycles and captures aftermarket revenue pools.
Industry Challenges
- Multi-skilled technician scarcity:Operators must simultaneously manage servo drive calibration, ink rheology adjustment, and color management software, stretching training pipelines in Midwestern US converting hubs.
- Legacy press integration complexity:Retrofitting UV LED curing onto mechanical shaft presses originally commissioned in the 1990s demands custom frame modifications that void original manufacturer warranties.
- REACH photoinitiator compliance timelines:Rapid restriction of specific chemistries under ECHA evaluation programs forces ink formulation switches mid-contract, disrupting qualified supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexographic Printing Machine Market |
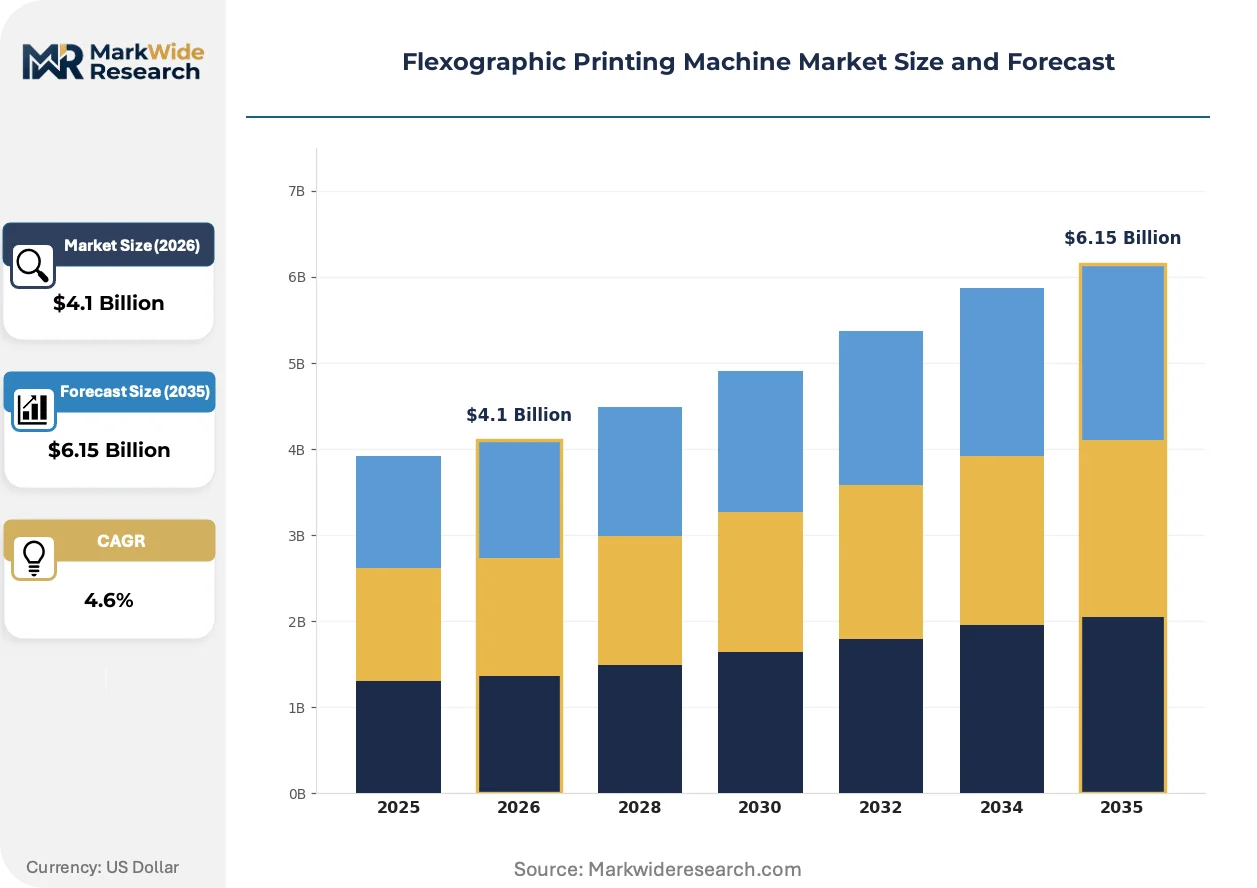
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stack Type, Central Impression, Inline Type, Rotary Type Technology: Laser Engraving, Digital Plate Making, Anilox Roll, UV Curing End User Industry: Packaging Manufacturers, Label Producers, Textile Printers, Paper Goods Fabricators Application: Food Packaging, Pharmaceutical Labeling, Corrugated Cartons, Gift Wrapping |
| Companies Covered | Bobst, Mark Andy Inc., Nilpeter A/S, Comexi, Windmöller & Hölscher, Heidelberger Druckmaschinen AG, Koenig & Bauer AG, Uteco Converting, Edale Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexographic Printing Machine Market Strategic Shifts & Innovations
Servo-driven press architectures are compressing make-ready times while digital front-end integration enables mass customization at flexo economics. Three developments are restructuring competitive position.
Electron beam curing is decentralizing food-compatible printing by eliminating photoinitiator migration risk entirely. Mid-tier converters in Wisconsin and Pennsylvania are adopting EB retrofits for dairy and ready-meal applications. This technology is decentralizing the premium segment away from UV-arc strongholds toward regional players lacking solvent recovery capital.
REACH authorization requirements for specific photoinitiators are forcing ink reformulation across European flexible packaging. ECHA substance evaluation timelines are compressing qualification windows for new chemistries. UV-curable narrow-web label producers in France and Benelux are accelerating water-based system trials to preempt supply disruption.
Brand procurement teams are unbundling press acquisition from multi-year service contracts. Converters in California and Texas are negotiating separate maintenance agreements with third-party technical specialists. This pattern is most pronounced in craft beverage label segments where capital constraints favor used press purchases with independent rebuild support.
Flexographic Printing Machine Market Segmentation
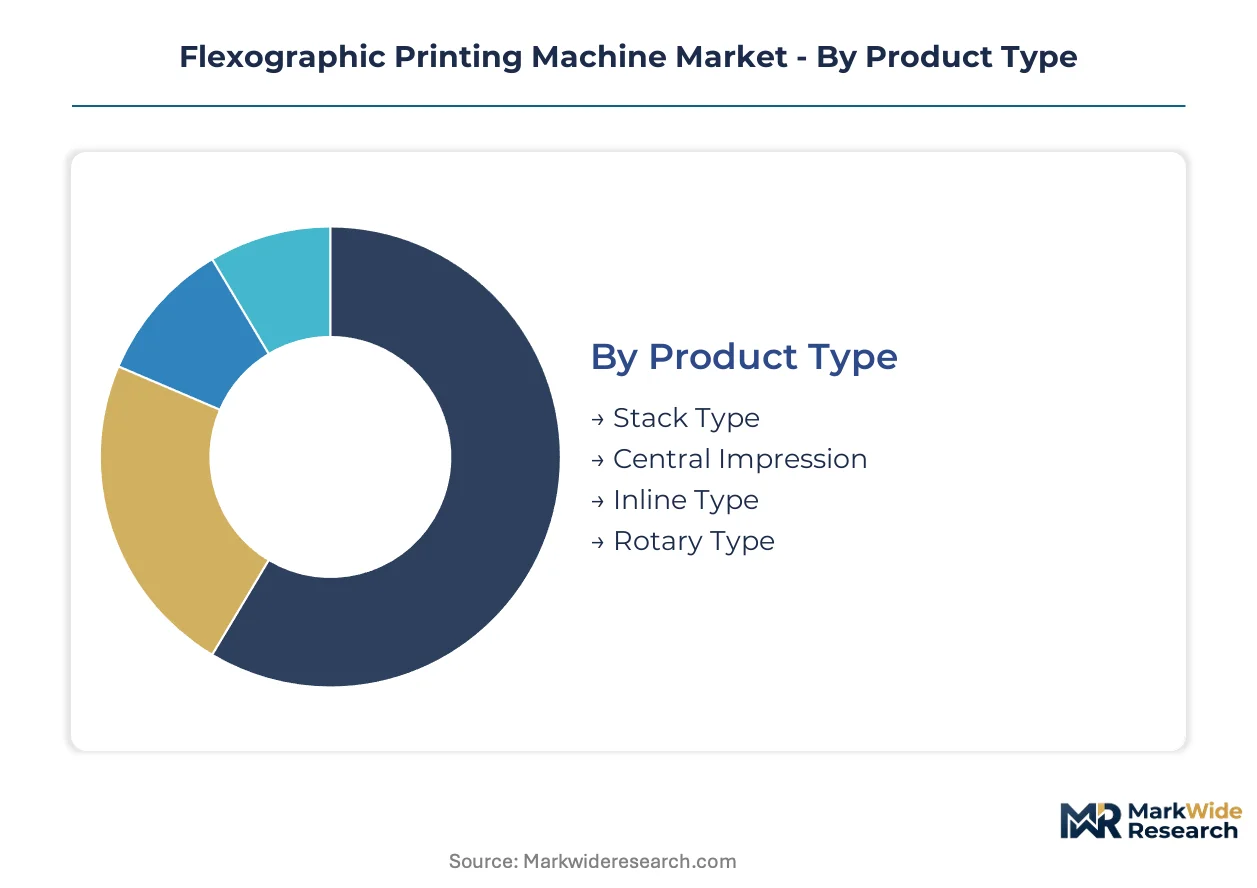
Press configuration and curing technology determine capital intensity, operating cost structure, and regulatory compliance pathways for converters. Segmentation reveals where margin pools concentrate and which technical specifications dominate procurement criteria.
Product Type:
Converters select press architecture based on substrate stiffness, color station count, and registration tolerance requirements.
- Central Impression:A single large drum carries the web through successive color stations, eliminating inter-station register drift. Flexible packaging converters in Germany and the US favor this architecture for thin-gauge mono-material films where tension control failures produce waste.
- Inline Type:Sequential processing stations accommodate corrugated board stiffness without web distortion. Carton plants in Wisconsin and Pennsylvania deploy these configurations for high-opacity white printing on recycled fiber substrates.
- Stack Type:Vertical color station arrangement suits narrow-web label production with frequent job changes. Craft beverage producers in California specify stack presses for short-run seasonal label campaigns.
- Rotary Type:Continuous cylinder contact enables textile printing on non-woven fabrics. Technical textile printers in Baden-Württemberg utilize rotary configurations for industrial filter media production.
Volume sits with Central Impression; growth tilts toward Inline Type as corrugated substitution accelerates.
Technology:
Technology selection hinges on ink chemistry compliance, anilox specification precision, and curing energy density.
- UV Curing:Photoinitiator-based polymerization delivers instant drying for food-contact applications. REACH restrictions on specific photoinitiators are forcing European converters toward water-based alternatives.
- Laser Engraving:Femtosecond ablation produces anilox cell geometries below 20 microns for high-line-count screening. Southern German engraving houses supply ceramic-coated rolls to multinational converters.
- Anilox Roll:Cell volume specification determines ink transfer consistency across water-based and solvent formulations. ISO standard tightening is demanding tighter volume tolerance bands for food-compliant output.
- Digital Plate Making:Computer-to-plate workflows compress make-ready times for variable-data jobs. Pharmaceutical label producers in France adopt digital plate systems for serialization compliance.
Installed base concentrates in Anilox Roll; regulatory pressure is accelerating UV Curing retrofits fastest.
End User Industry:
End-user technical requirements span migration thresholds, color consistency tolerances, and production volume profiles.
- Packaging Manufacturers:Flexible film and folding carton converters process the highest web volumes. FSSAI compliance requirements in Maharashtra and Gujarat are pulling investment into servo-press installations.
- Label Producers:Narrow-web specialists manage frequent job changes with automated plate mounting. Craft beverage segments in Texas favor independent rebuild support for used press acquisitions.
- Paper Goods Fabricators:Tissue and towel printers prioritize absorbency preservation over graphic density. Midwestern US converting hubs face technician scarcity across servo calibration and color management functions.
- Textile Printers:Non-woven and industrial fabric applications demand specialized ink penetration control. Technical textile clusters in northern Italy configure rotary presses for filtration media production.
Revenue pools concentrate with Packaging Manufacturers; qualification complexity is expanding Label Producers' service attach rates most rapidly.
Application:
Application-specific regulations govern ink migration limits, substrate compatibility, and drying system architecture.
- Food Packaging:FDA migration thresholds and EPA volatile organic compound rules shape US installation specifications. Electron beam curing retrofits are eliminating photoinitiator risk for dairy and ready-meal applications.
- Pharmaceutical Labeling:Serialization mandates and tamper-evidence requirements demand variable-data integration. Hybrid flexo-digital configurations capture batch sizes below 5,000 linear meters in France and Benelux.
- Corrugated Cartons:Recycled fiber content and board stiffness dictate inline press selection. California converters negotiate separate maintenance agreements to bypass traditional machinery distributors.
- Gift Wrapping:Seasonal volume spikes and metallic ink effects favor short-run digital hybrid workflows. Specialty converters in Pennsylvania manage peak demand through third-party technical service hubs.
Capital deployment concentrates in Food Packaging; regulatory serialization requirements are steepening Pharmaceutical Labeling's technology upgrade curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible packaging converters cluster in Germany and the United States, where multinational food brands drive press line investments. Stuttgart machinery manufacturers supply integrated press-diecutting systems to converters adapting to mono-material film specifications.
United States
Midwestern converting hubs in Wisconsin and Pennsylvania process dairy and ready-meal packaging on retrofitted electron beam curing lines. FDA migration thresholds and EPA volatile organic compound rules shape ink formulation and drying system specifications. California and Texas converters negotiate independent maintenance agreements for used press acquisitions.
Germany
Baden-Württemberg and North Rhine-Westphalia host concentrated engineering talent supplying servo-driven press architectures to multinational converters. REACH authorization requirements for photoinitiators force ink reformulation across flexible packaging operations. Stuttgart machinery clusters shorten delivery cycles for integrated press lines.
India
Maharashtra and Gujarat flexible packaging converters expand capacity under FSSAI food-contact compliance requirements and PLI scheme incentives for packaging machinery. Servo-press installations capture first-mover advantage as regional food brands fragment sourcing. Mumbai and Ahmedabad technical hubs develop local service capabilities.
France
Narrow-web label producers in France and Benelux accelerate water-based system trials to preempt REACH-driven supply disruption. Pharmaceutical serialization contracts drive hybrid flexo-digital configuration demand for batch sizes below 5,000 linear meters. Lyon and Paris packaging clusters adapt to rapid ECHA substance evaluation timelines.
Italy
Technical textile printers in northern Italy configure rotary presses for industrial filtration media production. Laser engraving equipment and ceramic coating capacity concentrates in southern Germany and northern Italy, creating supply dependencies for North American anilox roll rebuild schedules. Milan machinery specialists serve non-woven fabric applications.
Flexographic Printing Machine Market Key Industry Players
German producers anchor the premium tier for integrated press-diecutting lines; Swiss and Austrian specialists hold positions in narrow-web and label configurations. Market structure concentrates around machinery clusters with deep engineering talent pools, creating tiered competition between full-line integrators and application-specific fabricators. Two strategic archetypes dominate: servo-driven platform specialists and hybrid flexo-digital convergence players. Capacity expansion in Asian markets and technology licensing for electron beam curing represent the dominant competitive moves.
Within the premium integrated systems tier, Bobst exemplifies full-line platform dominance, while Windmöller & Hölscher occupies a position among German machinery fabricators with concentrated engineering heritage. Nilpeter A/S represents the hybrid configuration archetype, sitting within the narrow-web specialist segment where digital front-end integration commands service attach rates. These three anchors illustrate how geographic clustering around Stuttgart and Düsseldorf machinery ecosystems shapes competitive positioning.
| Leading Market Players |
|---|
| Bobst |
| Mark Andy Inc. |
| Nilpeter A/S |
| Comexi |
| Windmöller & Hölscher |
| Heidelberger Druckmaschinen AG |
| Koenig & Bauer AG |
| Uteco Converting |
| Edale Ltd. |
| Others |
Cost & Logistics Intelligence
Photopolymer plate resin costs cascade through three distinct pricing tiers, with petrochemical feedstock volatility compressing margins for short-run job shops while integrated converters in Germany absorb fluctuations through long-term supply agreements. The Stuttgart machinery cluster's concentration of engineering talent enables premium tier producers to bundle after-sales service into capital contracts, insulating sticker prices from raw material swings.
Pricing Analysis
Volume sits with standard-tier central impression presses serving multinational flexible packaging converters, while premium tier integrated press-diecutting lines command service-attach premiums. Price differentiation rests on servo architecture sophistication and REACH-compliant ink system bundling. Cost compression in the economy tier is intensifying because used press rebuilds with independent technical support are capturing craft beverage label demand. Short-run job shops exhibit highest price sensitivity due to plate cost amortization constraints; multinational converters with long campaigns demonstrate lowest sensitivity.
Supply Chain Analysis
Dual-sourcing mandates from North American converters are forcing qualification of secondary anilox roll suppliers beyond southern Germany and northern Italy. Laser engraving equipment and ceramic coating capacity draws from these two countries plus Austria, creating geographic concentration risk. Supply chain vulnerability centers on single-source dependency for femtosecond ablation systems. Distribution runs through manufacturer-owned technical service hubs that bypass traditional machinery distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH authorization timelines for photoinitiators erect regulatory moats favoring incumbents with reformulation R&D infrastructure.
For Market Incumbents: Acquire electron beam curing technology assets to preempt UV-arc displacement in dairy and ready-meal applications. Backward integration into laser engraving capabilities secures anilox roll supply continuity against southern German capacity bottlenecks. Defensive positioning demands servo-drive platform standardization to compress make-ready times below emerging hybrid flexo-digital entrants. For New Entrants and Emerging Players: Regional craft beverage label producers represent an underserved buyer archetype with capital constraints favoring used press acquisitions with independent rebuild support. White-space concentration sits in Maharashtra and Gujarat where FSSAI compliance requirements and PLI scheme incentives are pulling first-mover servo-press installations. Go-to-market execution should anchor on direct-to-converter channel restructuring through manufacturer-owned technical service hubs. For Investors and Strategic Acquirers: ECHA substance evaluation timeline acceleration is the leading indicator that ink formulation qualification windows are compressing, favoring targets with established supplier relationships. Long-term viability hinges on hybrid flexo-digital convergence capabilities serving pharmaceutical serialization contracts. Acquisition screening should prioritize narrow-web specialists with digital front-end integration expertise. Deviation in REACH authorization scope would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Electron Beam Curing Retrofit | Eliminates photoinitiator migration risk for FDA-compliant dairy packaging applications. |
| Servo-Driven Platform Standardization | Compresses make-ready times below 15 minutes for craft beverage seasonal campaigns. |
| Hybrid Flexo-Digital Integration | Captures pharmaceutical serialization contracts with batch sizes below 5,000 linear meters. |
| Direct-to-Converter Channel Restructuring | Bypasses machinery distributors to capture aftermarket revenue pools in California and Texas. |
| Backward Integration into Laser Engraving | Secures anilox roll supply continuity against southern German capacity concentration. |
Research Approach
Independent corroboration across machinery OEM technical directors, flexible packaging plant engineers, and narrow-web label production managers underwrites the qualitative findings. Primary fieldwork with servo-drive calibration specialists and color management software vendors combined with secondary validation from SEC filings of listed machinery producers, VDMA packaging machinery statistics, and ECHA substance evaluation databases. Bottom-up press installation tracking and top-down converter capacity expansion analysis enable triangulation.
Rate-of-change decomposition separates volume effects from mix-shift and pricing dynamics across the projection horizon. Segmentation modeling incorporates press configuration architecture, curing technology compliance pathway, end-use industry migration threshold requirements, and regional regulatory cluster. CAGRs derive from machinery shipment data cross-referenced with converter capital expenditure disclosure patterns. Ink formulation qualification timelines and anilox specification standard evolution under ISO frameworks constitute industry-specific forecast inputs.
Revisions become necessary when REACH authorization scope expands beyond photoinitiators to encompass additional UV-curable chemistries, when FSSAI enforcement intensity in India deviates from current trajectory, or when electron beam curing capital costs drop below UV LED retrofit economics. Deviation in EU Green Deal packaging waste directive implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Global Pre Print Flexo Press Market
Packaging Printing
Asia-Pacific Digital Printing Packaging Market
Packaging Printing
Global Digital Printing Packaging Market
Packaging Printing
Label Printers Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Stamping Foils Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Pre-Press for Packaging Market
Packaging Printing
Rotogravure Printing Machine Market
Packaging Printing
Flexographic Printing Market
Packaging Printing
Heat Transfer Press Printing Machine Market
Packaging Printing
Europe Printed Packaging Market
Packaging Printing
Flex Banner Market
Packaging Printing
Label Printing Software Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
Lithographic Printing for Packaging Market