
 Printed Boxes Market | 2026-2036
Printed Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Boxes Market Analytics
E-commerce direct-to-consumer channels is reshaping how printed boxes reach end buyers, bypassing traditional wholesale distributors. WestRock Company leverages its integrated mill-to-box network to control fiber supply and finished goods distribution across North American corridors. Mondi Group anchors its competitive stance through specialty kraft paper innovations that serve premium cosmetic and food-grade applications. Smurfit Kappa Group dominates European corrugated printed box supply through continent-spanning recycling and manufacturing infrastructure.
Printed boxes are fiber-based containers manufactured through die-cutting, printing, and folding or gluing processes, typically constructed from paperboard, kraft paper, or cardstock substrates with grammage ranging from 200 to 400 gsm, designed to protect, display, and communicate brand identity for retail and shipped goods. Folding cartons lead volume demand in food and beverage applications where high-speed filling lines require precise dimensional tolerance and print registration. Corrugated boxes with multi-color flexographic or lithographic lamination represent the fastest-expanding segment as unboxing experience investments intensify across electronics and cosmetics direct-to-consumer channels. Rigid boxes command concentrated margin pools in luxury cosmetics and premium spirits where embossed, textured, and multi-layered design complexity justifies specialized manual assembly and quality control.
The US EPA guides recycled content standards for paper packaging materials, while the EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recyclability labeling across member states. India's BIS certification requirements for paperboard food contact materials shape import and domestic manufacturing compliance pathways. Stakeholders must monitor evolving state-level packaging EPR legislation in the US and EU Green Deal implementation timelines to align capital allocation with compliance-driven material substitution cycles.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material traceability investments across European supply chains while e-commerce unboxing expectations compress print-to-ship lead times from weeks to days.
Growth Catalysts
- Extended Producer Responsibility Mandates:The EU Packaging and Packaging Waste Regulation requires recyclability labeling and waste fee structures that favor fiber-based printed boxes over plastic alternatives in European consumer goods.
- Direct-to-Consumer Channel Expansion:Electronics and cosmetics brands are commissioning multi-color lithographic laminations for corrugated shipper boxes to differentiate unboxing moments in crowded e-commerce fulfillment.
- India Organized Retail Buildout:Modern grocery and apparel chains in Mumbai, Delhi, and Bangalore are consolidating folding carton procurement through long-term vendor agreements with domestic converters.
Market Restraints
- Pulp Price Volatility:Kraft linerboard and white-top linerboard input costs fluctuate with Brazilian and Scandinavian softwood pulp contract pricing, squeezing converter margins during supply tightness.
- Recycling Infrastructure Gaps:Post-consumer fiber collection and de-inking capacity concentrates in Germany, Netherlands, and select US Gulf Coast hubs, leaving peripheral European and Indian markets dependent on virgin fiber.
- Dimensional Tolerance Limits:High-speed beverage filling lines demand folding carton registration precision within 0.3 millimeters, restricting supplier qualification to capital-intensive operations with servo-controlled die-cutting.
Strategic Opportunities
- Smart Packaging Convergence:Near-field communication chips and printed electronics are embedding track-and-trace functionality into pharmaceutical and luxury cosmetic rigid boxes.
- India Direct-to-Consumer Penetration:Domestic beauty and wellness brands in Tier-2 cities are bypassing traditional distributor networks to source custom-printed mailer boxes directly from Ahmedabad and Surat converters.
- US State-Level EPR Legislation:California, Oregon, and Colorado extended producer responsibility frameworks are creating compliance service revenue streams for packaging suppliers with lifecycle assessment capabilities.
Industry Challenges
- Prepress Talent Scarcity:Skilled operators for Esko Automation Engine and Kongsberg cutting tables command premium wages in European and North American corrugated plants facing retirement waves.
- Legacy Equipment Integration:Brownfield folding carton facilities struggle to retrofit Heidelberg and Bobst lines with inline spectral color measurement for brand color consistency requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Boxes Market |
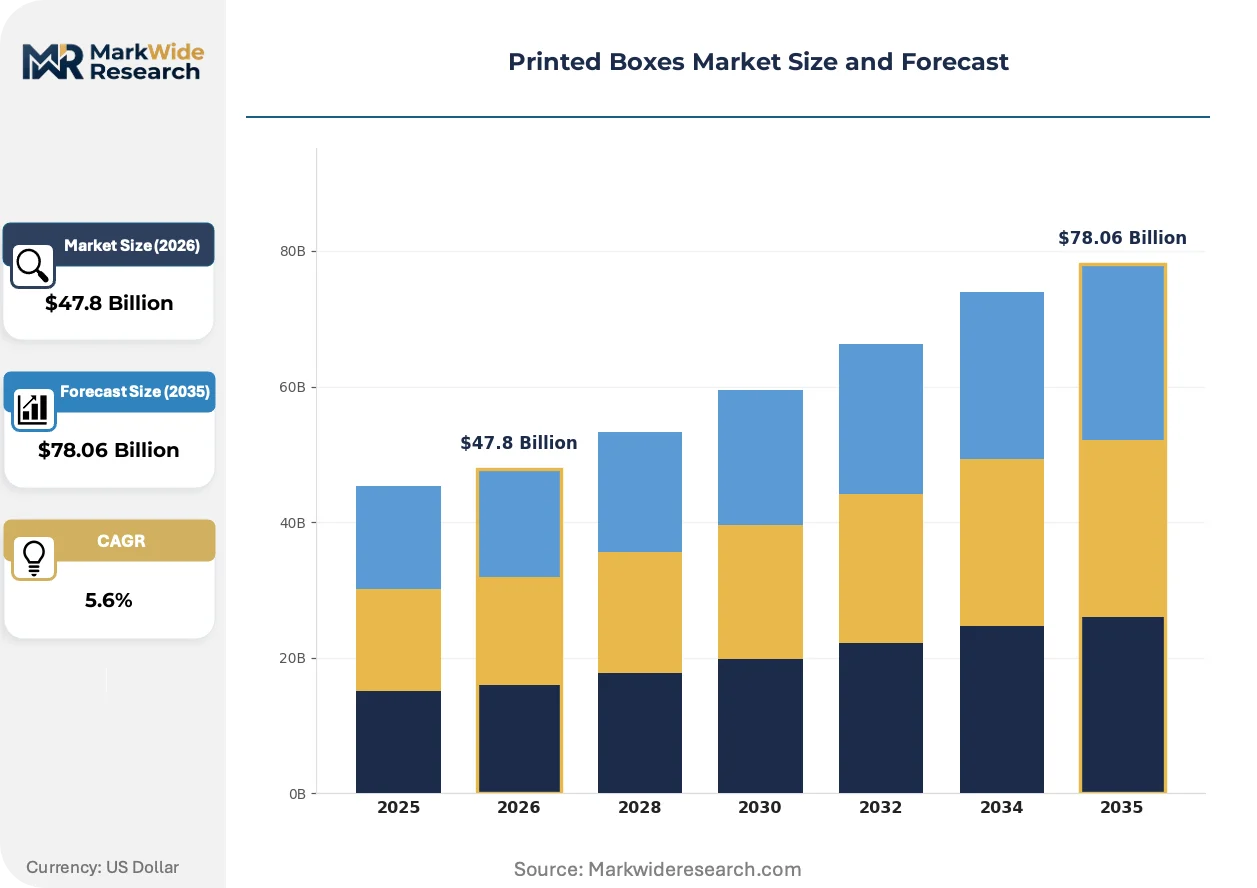
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $78.06 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Folding Cartons, Rigid Boxes, Corrugated Boxes, Flexible Packaging Material: Paperboard, Kraft Paper, Cardstock, Recycled Material End User: Food & Beverage, Cosmetics, Electronics, Retail Design Complexity: Simple, Textured, Embossed, Multi-layered |
| Companies Covered | WestRock Company, Amcor Limited, International Paper Company, Packaging Corporation of America, Smurfit Kappa Group, Stora Enso, Mondi Group, Sonoco, Nine Dragons Paper (Holdings) Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Boxes Market Evolving Landscape
Digital print workflows and substrate science are collapsing minimum order quantities while regulatory chemistry restrictions are accelerating water-based ink formulation substitution across food-contact applications.
Single-pass inkjet systems from vendors including EFI and HP are virtualizing the traditional offset makeready process, enabling corrugated converters to produce versioned packaging with variable data and imagery without plate changeovers. Cosmetic and nutraceutical contract manufacturers are adopting these systems for seasonal and regional SKU proliferation. The technology is virtualizing the economics of short-run production, compressing break-even quantities from ten thousand units to hundreds.
The EU Green Deal implementation timeline tightens per- and polyfluoroalkyl substance restrictions in food-contact paperboard, forcing converters to validate grease-barrier alternatives including clay coatings and bio-based waxes. Folding carton suppliers serving frozen food and quick-service restaurant chains face reformulation deadlines and migration testing protocols. German and French retail private-label programs are accelerating certification requirements ahead of regulatory enforcement dates.
Brand procurement teams are consolidating vendor panels and demanding integrated design-to-delivery platforms that compress concept-to-shelf cycles. Direct-to-consumer electronics and apparel companies are replacing transactional spot-buying with annual volume commitments tied to sustainability scorecards. This consolidation is most visible in California and New York metro areas where venture-backed brands co-locate fulfillment operations with converter design studios.
Printed Boxes Market Segmentation
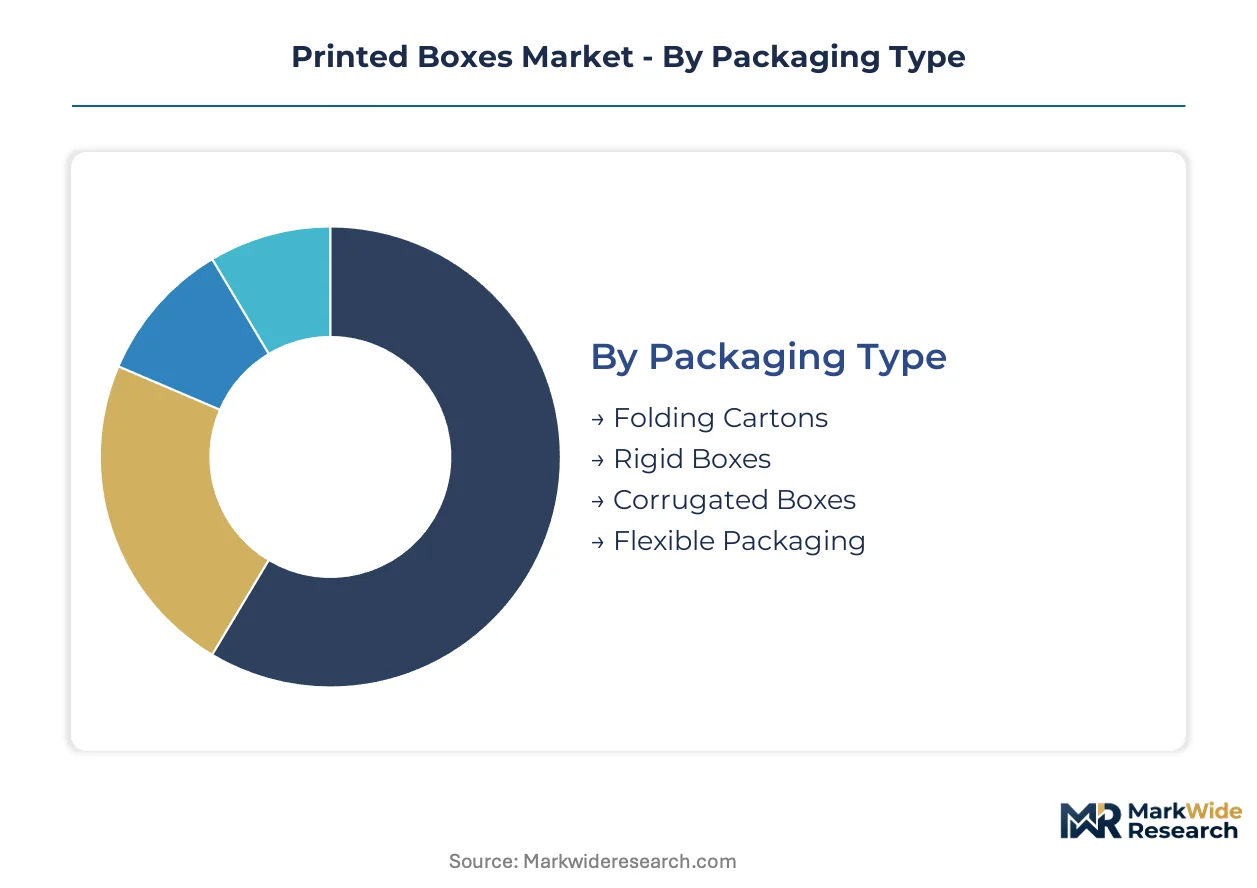
Segmentation in printed boxes reveals divergent production economics and customer decision cycles. Cycle times stretch from hours for digital-print corrugated shippers to weeks for hand-assembled rigid luxury packaging. Understanding these velocity differences shapes capital allocation and capacity planning across converter operations.
Packaging Type:
Cycle times vary dramatically: corrugated boxes turn in 24-72 hours for digital workflows, while rigid boxes demand 2-4 weeks for manual assembly and finishing.
- Folding Cartons:Precision-die-cut paperboard constructions with 200-400 gsm grammage, engineered for high-speed beverage and pharmaceutical filling lines. Demand concentrates in European dairy and ready-meal segments where EU Packaging and Packaging Waste Regulation recyclability mandates favor fiber-based solutions over plastic trays.
- Corrugated Boxes:Fluted medium sandwiched between linerboards, flexographic or lithographic laminated for direct-to-consumer unboxing experiences. Electronics and cosmetics brands in California and New York metro areas are commissioning versioned seasonal designs with compressed print-to-ship windows.
- Rigid Boxes:Thick paperboard wrapped around glued chipboard cores, requiring specialized manual assembly for embossed and textured finishes. Luxury spirits and high-end cosmetics in French and German markets sustain this segment despite labor intensity.
- Flexible Packaging:Converted films and laminates for pouches and wraps, occupying adjacent technical territory with different equipment footprints and substrate chemistry requirements.
Folding cartons dominate installed base across food and beverage infrastructure. Corrugated boxes are where expansion concentrates as e-commerce fulfillment reshapes procurement patterns.
Material:
Cost tiers stratify sharply: virgin kraft commands premium pricing, recycled fiber operates at mid-tier economics, and specialty cardstocks anchor luxury applications.
- Paperboard:Bleached or unbleached cellulose sheets with calibrated stiffness-to-weight ratios, the workhorse substrate for folding cartons and rigid box construction. Indian organized retail buildout in Mumbai and Delhi is driving volume commitments for SBS and CUK grades.
- Kraft Paper:Unbleached softwood pulp sheets with high tear resistance, forming the structural backbone of corrugated linerboard. Brazilian and Scandinavian pulp contract volatility directly squeezes converter margins on this input.
- Cardstock:Heavyweight papers above 300 gsm, specified for premium direct-mail and retail display applications requiring dimensional stability without corrugation.
- Recycled Material:Post-consumer fiber processed through de-inking and repulping, constrained by collection infrastructure gaps in peripheral European markets and India outside major urban centers.
Kraft paper dominates tonnage throughput. Recycled material is where regulatory pressure and brand sustainability commitments are forcing fastest formulation change.
End User:
Application requirements drive specification divergence: food contact demands migration testing, cosmetics prioritizes shelf presence, electronics needs damage protection.
- Food & Beverage:Folding cartons for frozen meals, dairy, and beverages with FDA and BIS compliance for direct food contact. EU Green Deal PFAS restrictions are accelerating clay coating and bio-based wax validation for grease barrier properties.
- Cosmetics:Rigid boxes with multi-layered embossing and textured finishes for premium skincare and fragrance, plus corrugated mailers for direct-to-consumer subscription channels.
- Electronics:Corrugated shipper boxes with lithographic lamination for unboxing differentiation, specified by venture-backed brands co-locating fulfillment with converter design studios.
- Retail:Point-of-sale display boxes and shelf-ready packaging, consolidating procurement through annual volume commitments tied to sustainability scorecards.
Food and beverage dominates volume demand. Cosmetics is where design complexity and margin extraction concentrate.
Design Complexity:
Customer type separates execution capability: mass-market brands standardize on simple designs, luxury houses commission multi-layered constructions requiring specialized craft labor.
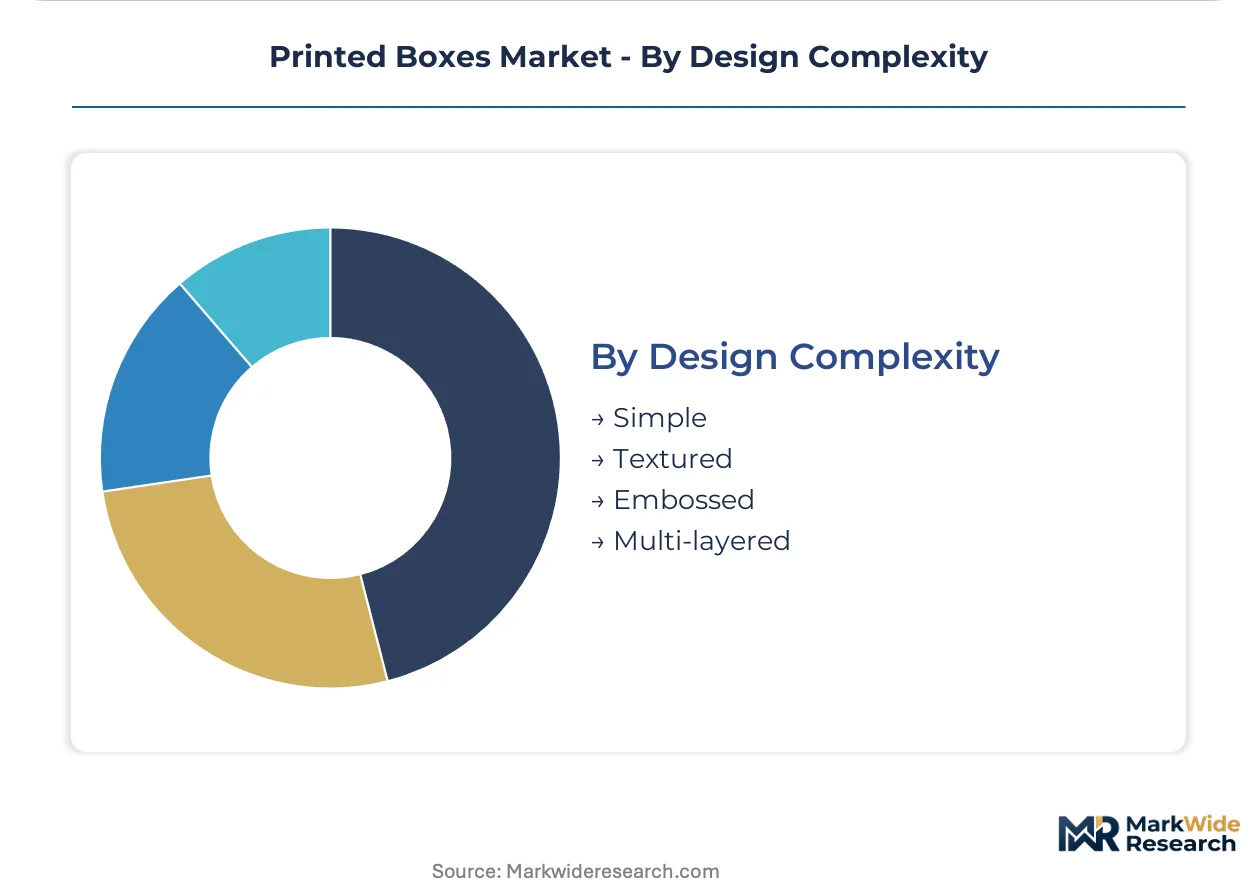
- Simple:Single-color flexographic or basic offset printing with standard die-cutting, enabling high-volume economies and fastest turnaround times for promotional and commodity packaging.
- Textured:Specialty coatings and substrate finishes adding tactile dimension without structural complexity, adopted by mid-tier cosmetics and spirits brands seeking differentiation at moderate cost.
- Embossed:Raised relief patterns requiring dedicated tooling and press customization, specified by luxury houses for brand recognition and counterfeit resistance.
- Multi-layered:Composite constructions combining rigid substrates with wrapped exteriors, magnetic closures, and interior fitments, demanding manual assembly and quality control that limits supplier qualification.
Simple designs dominate production volume. Multi-layered is where specialist converters defend margin position through capability scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation anchors European compliance frameworks, while India and the United States drive divergent demand patterns through organized retail expansion and direct-to-consumer channel maturation respectively.
Germany
EU Green Deal PFAS restrictions are accelerating grease-barrier coating reformulations for frozen food folding cartons. The national packaging regulator enforces extended producer responsibility fee structures that favor fiber-based substrates over plastic alternatives. Industrial converters in the Rhine-Ruhr corridor are consolidating de-inking capacity to serve private-label retail programs ahead of enforcement deadlines.
United States
California, Oregon, and Colorado extended producer responsibility frameworks are creating compliance service revenue streams for packaging suppliers with lifecycle assessment capabilities. The EPA guides recycled content standards for paper packaging materials entering interstate commerce. Venture-backed electronics and apparel brands in New York and California metro areas are co-locating fulfillment operations with converter design studios to compress print-to-ship cycles.
India
Organized retail buildout in Mumbai, Delhi, and Bangalore is consolidating folding carton procurement through long-term vendor agreements with domestic converters. BIS certification requirements for paperboard food contact materials shape import and domestic manufacturing compliance pathways. Tier-2 city beauty and wellness brands are bypassing traditional distributor networks to source custom-printed mailer boxes directly from Ahmedabad and Surat converters.
China
Dual carbon goals and national emission reduction targets are pressuring coastal paperboard mills to upgrade pulping and coating operations. The Ministry of Ecology and Environment enforces discharge standards that raise capital requirements for folding carton and corrugated producers. Manufacturing clusters in the Yangtze River Delta maintain integrated supply chains serving export-oriented electronics brands with lithographic-laminated shipper specifications.
Brazil
Softwood pulp contract pricing volatility from southern plantation forests directly squeezes converter margins on kraft linerboard inputs. ANVISA regulates food-contact paper packaging migration limits for folding cartons serving domestic dairy and beverage markets. São Paulo-state corrugated plants are investing in flexographic upgrade capacity to capture e-commerce fulfillment demand from Mercado Libre and domestic marketplace vendors.
Printed Boxes Market Competitive Landscape
Vertically integrated multinationals and regional specialists split the market between scale-driven cost leadership and design-intensive premium positioning. The vendor base concentrates around fiber supply control and converter network density rather than pure manufacturing scale. Two strategic archetypes dominate: integrated mill-to-box operators with captive pulp and paperboard supply, and independent converters with specialized finishing and design capabilities. Competitive moves center on recycling infrastructure consolidation and digital print workflow integration.
Among North American integrated operators, WestRock Company and International Paper Company exemplify the mill-to-box archetype through upstream fiber supply control. Mondi Group anchors European specialty kraft paper positioning for premium cosmetic and food-grade applications. Smurfit Kappa Group occupies a position within the corrugated recycling and manufacturing infrastructure tier across continental European markets. These three represent divergent geographic and capability emphases rather than direct segment overlap.
| Leading Market Players |
|---|
| WestRock Company |
| Amcor Limited |
| International Paper Company |
| Packaging Corporation of America |
| Smurfit Kappa Group |
| Stora Enso |
| Mondi Group |
| Sonoco |
| Nine Dragons Paper (Holdings) Limited |
| Others |
Value Network & Pricing Analysis
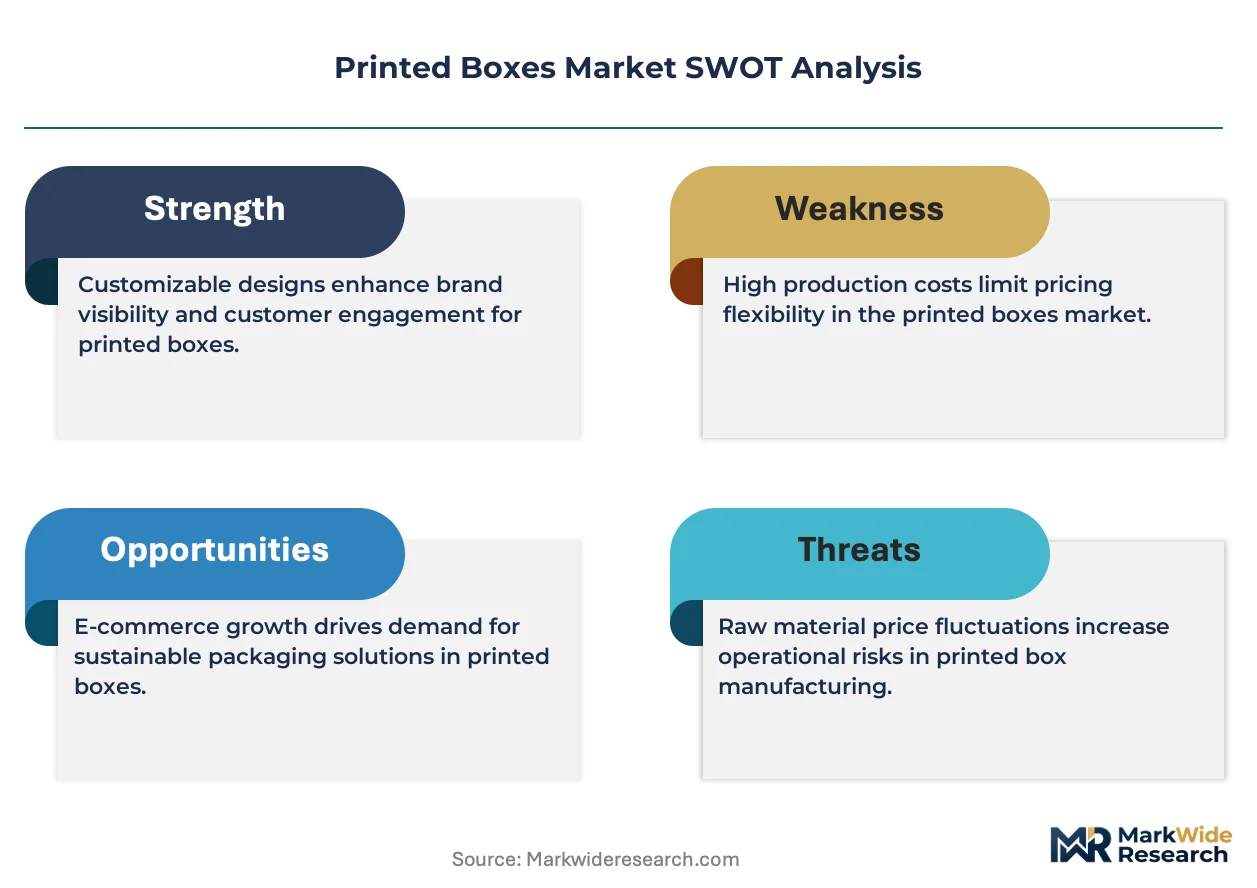
Pulp contract volatility from Brazilian and Scandinavian softwood markets determines both converter margin compression and the geographic clustering of integrated mill-to-box operators. Pricing tier spreads widen when kraft linerboard input costs spike, forcing buyers toward recycled fiber alternatives and reshaping supplier qualification around captive pulp supply.
Pricing Analysis
The customization-premium spread separates lithographic-laminated corrugated shippers from standard flexographic brown boxes by a factor of three to five. Three-tier pricing structure across premium, standard, and economy levels reflects substrate grade, print complexity, and volume commitment scale. Pricing pressure stems from Brazilian pulp contract volatility squeezing converter margins on kraft linerboard inputs. Mass-market food and beverage brands exhibit highest price sensitivity, while luxury cosmetics houses prioritize design complexity over unit cost.
Supply Chain Analysis
Export-control regimes on advanced coating chemistries and digital print systems limit technology flows into Indian and peripheral European markets. Fiber supply concentrates in Brazil, Scandinavia, and the US South, with converter networks clustering around coastal ports and inland mill complexes. Raw material dependencies include softwood pulp, clay coatings, and water-based ink formulations. Single-source vulnerability runs through Brazilian plantation pulp supply. Distribution runs through converter direct sales for large accounts and regional distributor networks for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized finishing capabilities for embossed and multi-layered rigid boxes remain scarce relative to demand from luxury spirits and cosmetics brands, creating supplier leverage in a market otherwise crowded with commodity corrugated capacity.
For Market Incumbents: Insulate margin position by deepening backward integration into de-inking and repulping capacity ahead of EU Green Deal enforcement timelines. Secure long-term vendor agreements with organized retail chains in Mumbai and Delhi before domestic converters scale comparable finishing capabilities. For New Entrants and Emerging Players: Build out digital print workflows serving Tier-2 Indian beauty brands in Ahmedabad and Surat with compressed print-to-ship cycles. Target corrugated mailer boxes for direct-to-consumer wellness subscriptions as the most penetrable white-space segment, leveraging direct sales bypass of traditional distributor networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors converters with captive fiber supply and specialized finishing assets. Long-term viability across the projection horizon hinges on recycling infrastructure control and EPR compliance service capabilities. Acquisition targets should demonstrate servo-controlled die-cutting precision and established BIS certification pathways. Watch Indian state-level packaging waste regulations as the signal for accelerated domestic consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Print Workflow Integration | Enables versioned seasonal packaging for California cosmetics brands without plate changeover costs. |
| Backward Integration into De-inking | Secures post-consumer fiber supply for EU private-label programs ahead of PFAS restriction deadlines. |
| Specialized Rigid Box Capacity Addition | Captures luxury spirits margin pools through manual assembly capabilities scarce in automated corrugated plants. |
| EPR Compliance Service Launch | Creates recurring revenue streams from California and Oregon brand customers facing extended producer responsibility mandates. |
| India Direct Sales Channel Buildout | Bypasses traditional distributor markups for Surat and Ahmedabad converters serving Tier-2 beauty brands. |
Research Methodology
Initial hypotheses were tested against primary input from corrugated plant managers, folding carton procurement leads at food and beverage brands, prepress operators, and sustainability directors at luxury cosmetics houses and refined through secondary validation. Sources included customs trade data on kraft linerboard imports, EPA recycled content guidance documents, EU Packaging and Packaging Waste Regulation filings, and SEC 10-K disclosures from integrated paper packaging companies. Bottom-up volume estimates from converter capacity and utilization rates were triangulated against top-down demand projections from end-use industry consumption patterns.
Demand-supply balance modeling across the analysis window incorporated packaging type segmentation, material grade tiers, end-use industry clusters, and design complexity levels. CAGRs were derived from trend extrapolation of historical volume data adjusted for regulatory-driven material substitution effects and channel shift impacts. Industry-specific inputs included e-commerce fulfillment growth trajectories, EU Green Deal implementation pacing, and Indian organized retail square footage expansion.
Stress conditions across Brazilian pulp price bands, EU PFAS enforcement timelines, and Indian BIS certification backlogs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on channel migration rates and regulatory compliance cost pass-through. Material shifts in US state-level EPR legislation adoption or breakthroughs in bio-based barrier coating performance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Laser Coders Market
Packaging Printing
Qatar Printing and Packaging Market
Packaging Printing
Soft Signage Market
Packaging Printing
Lithographic Printing for Packaging Market
Packaging Printing
Stack Flexo Printing Press Market
Packaging Printing
LAMEA Label Printing Software Market
Packaging Printing
Pigment Hot Stamping Foil Market
Packaging Printing
Digital Label Printing Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Pre-Printed Liners Market
Packaging Printing
North America Print Label Market
Packaging Printing
Electrophotography Printing for Packaging Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
Flexographic Printing Market
Packaging Printing
Rotogravure Printing Machine Market