
 Laser Coders Market | 2026-2036
Laser Coders Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Coders Market Outlook
Market Context
The capital-intensity divergence between fiber-source owners and system integrators is rotating competitive dynamics toward upstream control. IPG Photonics Corporation leverages captive ytterbium fiber laser production to dominate high-power industrial marking, while TRUMPF sustains German-engineered precision in automotive coding lines. Keyence Corporation differentiates through integrated vision-and-marking workstations that reduce commissioning time for electronics manufacturers.
Technical Definition and Segment Structure
Laser coders are non-contact marking systems that use focused laser beams to permanently alter substrate surfaces through thermal ablation, carbonization, or photochemical reaction, typically operating at wavelengths from 355 nm (UV) to 10,600 nm (CO2) with scan speeds exceeding 2,000 characters per second for inline production. Fiber laser systems anchor the product type hierarchy due to their efficiency on metals and engineered plastics, while UV laser etching commands premium positioning in electronics where heat-sensitive semiconductor packages require cold marking. CO2 laser labeling retains mature share in food and beverage date coding on paper and glass substrates, though green laser systems are gaining traction in specialized branding applications on reflective materials.
Regulatory Environment
EU MDR and FDA UDI regulations mandate permanent, machine-readable device identifiers on pharmaceutical and medical device packaging, directly expanding laser coder deployment in cleanroom environments. REACH compliance and F-Gas Regulation restrictions on industrial gases further displace solvent-based inkjet systems in European manufacturing, channeling substitution demand toward laser marking systems. Stakeholders must monitor evolving national serialization deadlines and substrate-specific code durability standards to calibrate technology roadmaps and service network investments.
Market Dynamics
Pharmaceutical serialization mandates are compressing buyer decision cycles and forcing rapid technology transitions from solvent-based marking to permanent laser solutions. Fiber laser source concentration among ytterbium fiber producers is reshaping competitive positioning upstream.
Growth Catalysts
- EU Falsified Medicines Directive:Mandates for tamper-evident track-and-trace codes on pharmaceutical packaging are accelerating fiber laser deployment across European contract manufacturing organizations.
- Automotive component traceability:German OEMs and tier-1 suppliers require permanent direct-part marking for powertrain and chassis components to satisfy warranty and recall management protocols.
- UV cold marking technology:Semiconductor packaging manufacturers are adopting 355 nm UV laser systems to mark heat-sensitive substrates without thermal damage to die structures.
Market Restraints
- Ytterbium fiber supply concentration:Captive production of doped fiber laser sources by vertically integrated manufacturers limits independent system integrators' margin flexibility.
- High initial capital outlay:Industrial fiber laser coding stations require substantially higher upfront investment than continuous inkjet alternatives, extending payback periods for small-batch producers.
- Substrate compatibility constraints:CO2 laser systems struggle with reflective metal marking without pretreatment, restricting deployment in certain automotive and aerospace applications.
Strategic Opportunities
- Indian pharmaceutical export manufacturing:CDMO facilities serving regulated markets are upgrading marking infrastructure to meet FDA and EMA serialization requirements for US and EU-bound shipments.
- Battery cell traceability:Lithium-ion cell producers are implementing laser direct part marking for electrode and casing identification to support circular economy mandates and second-life tracking.
- Vision-guided marking convergence:Integration of machine vision with laser coding workstations enables real-time quality verification and reduces commissioning time for electronics contract manufacturers.
Industry Challenges
- Multijurisdictional compliance complexity:Manufacturers must reconcile divergent national serialization deadlines and substrate-specific code durability standards across FDA, EMA, and emerging market regulators.
- Laser safety certification timelines:IEC 60825-1 compliance documentation and third-party verification processes delay product launches in medical device and aerospace verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Coders Market |
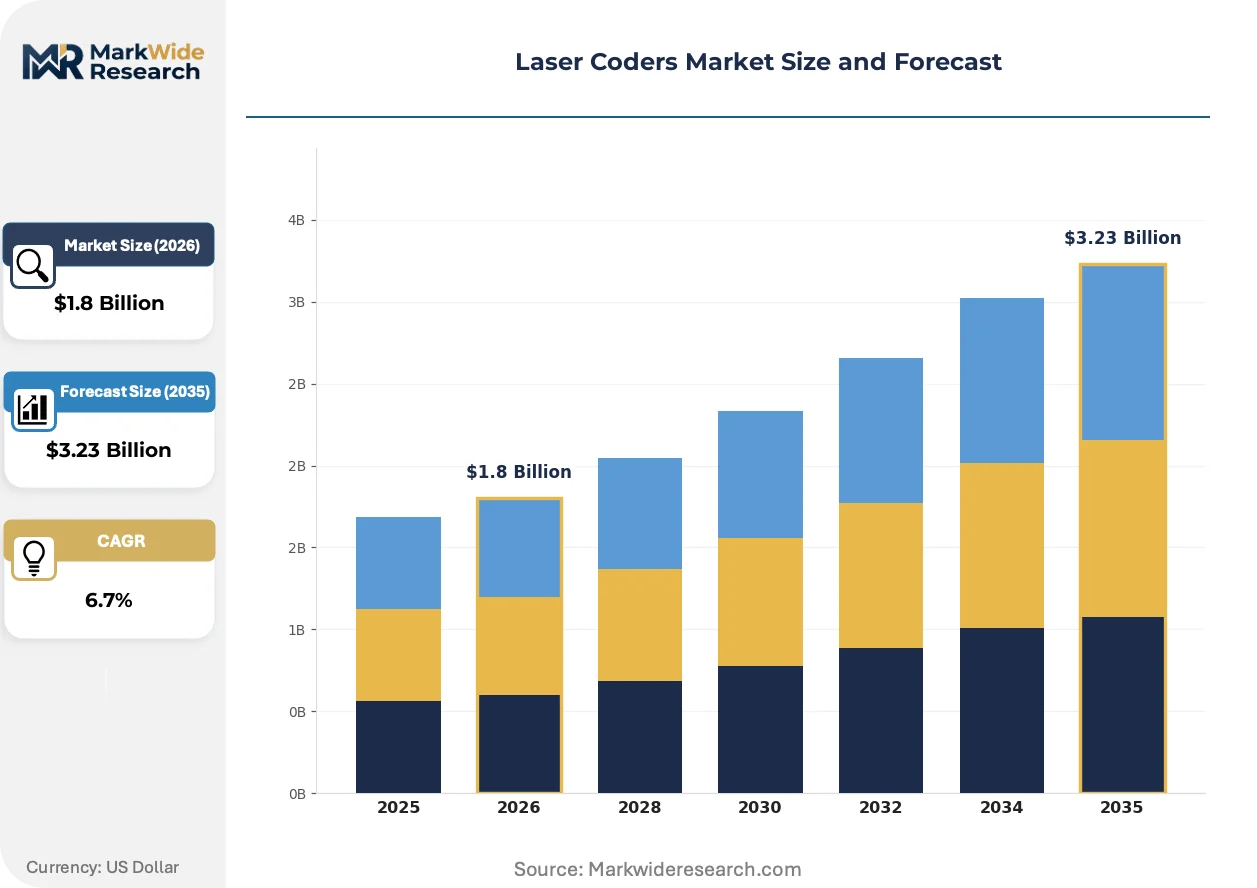
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Laser, CO2 Laser, UV Laser, Green Laser Technology: Direct Marking, Inkjet Printing, Laser Etching, Marking Systems End User: Food & Beverage, Pharmaceuticals, Electronics, Automotive Application: Labeling, Date Coding, Branding, Product Identification |
| Companies Covered | Domino Printing Sciences, Videojet Technologies, Markem-Imaje, Danaher Corporation, Keyence Corporation, IPG Photonics Corporation, TRUMPF, Coherent Corp., Han's Laser Technology Industry Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Coders Market Strategic Shifts
Technology roadmaps in laser coding are converging on higher-speed scan systems and wavelength diversification to address substrate expansion. Competitive differentiation is migrating from hardware specifications to integrated workflow solutions.
Green laser marking at 532 nm is bifurcating application possibilities for highly reflective substrates such as gold-plated connectors and polished copper busbars. Electronics manufacturers serving telecommunications and data center infrastructure are adopting these systems for branding and traceability without surface damage. The technology is bifurcating the premium marking segment from traditional fiber and UV alternatives based on aesthetic quality requirements.
REACH compliance and F-Gas Regulation restrictions on industrial solvents are systematically displacing continuous inkjet systems in European food, beverage, and personal care packaging. Manufacturers face mandatory transition timelines that compress capital equipment replacement cycles. German and French packaging lines are responding with accelerated CO2 and fiber laser deployments to eliminate volatile organic compound emissions and solvent storage liabilities.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts into discrete hardware, software, and consumable subscription components. Electronics and pharmaceutical contract manufacturers are favoring outcome-based uptime guarantees over capital purchase models. This shift is most pronounced in Germany and Switzerland, where precision engineering clusters prioritize operational expenditure flexibility over asset ownership.
Laser Coders Market Segmentation
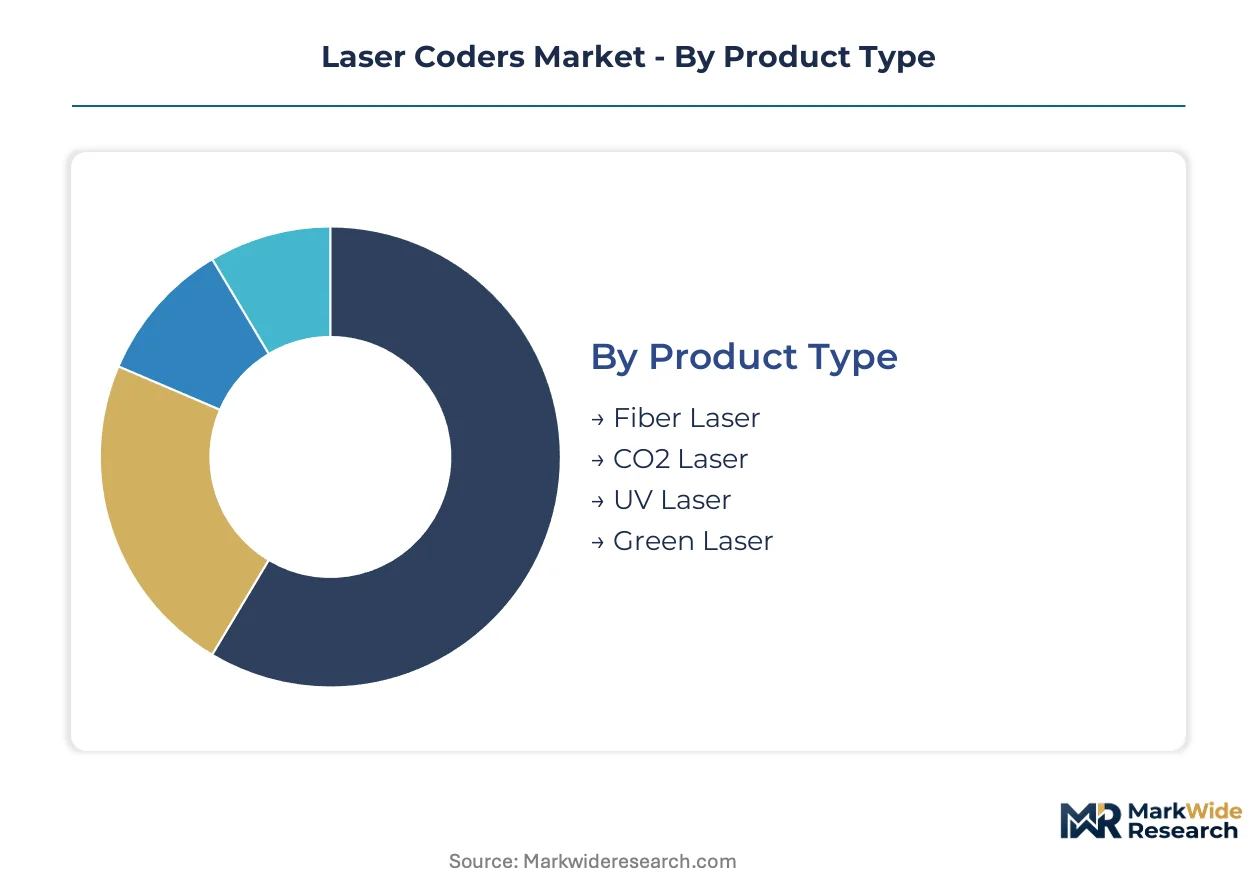
Laser coder purchasing decisions pivot on substrate compatibility and regulatory compliance requirements. Segmentation reveals where substitution pressure from inkjet alternatives is weakest and where permanent marking commands premium positioning.
Product Type:
Continuous inkjet systems face displacement pressure from fiber and UV laser alternatives as REACH compliance tightens across European manufacturing.
- Fiber Laser:Ytterbium-doped fiber sources generate 1,064 nm wavelength beams optimized for metals and engineered plastics. German automotive OEMs and tier-1 suppliers specify fiber systems for powertrain component direct-part marking under warranty traceability protocols.
- UV Laser:355 nm solid-state sources deliver cold marking through photochemical reaction rather than thermal ablation. Semiconductor packaging facilities adopt UV systems to mark heat-sensitive die structures without thermal damage to adjacent circuitry.
- CO2 Laser:10,600 nm gas laser systems dominate food and beverage date coding on paper, glass, and organic substrates where thermal marking is acceptable.
- Green Laser:532 nm frequency-doubled Nd:YAG sources address highly reflective substrates including gold-plated connectors and polished copper busbars in telecommunications infrastructure.
Fiber laser systems retain volume leadership across industrial metal marking; UV laser configurations hold the steepest expansion curve driven by electronics miniaturization.
Technology:
Cost tier stratification separates capital-intensive laser installations from lower-barrier inkjet alternatives, with hybrid marking systems occupying intermediate positioning.
- Direct Marking:Laser beams permanently alter substrate surfaces through ablation, annealing, or carbonization without consumable inks or solvents. Pharmaceutical manufacturers deploy direct marking to satisfy FDA UDI and EU MDR mandates for permanent, machine-readable device identifiers.
- Laser Etching:Controlled material removal creates recessed codes with enhanced durability against abrasion and chemical exposure. Aerospace component suppliers specify etched markings for flight-critical parts subject to extreme environmental cycling.
- Inkjet Printing:Continuous and drop-on-demand systems retain installed base in cost-sensitive batch coding where permanence requirements are relaxed.
- Marking Systems:Integrated workstations combining laser sources, beam delivery, and motion control for automated production line deployment.
Direct marking commands the premium tier on total cost of ownership; laser etching is climbing the fastest as durability specifications tighten across regulated industries.
End User:
Application maturity varies sharply across verticals, with pharmaceuticals and automotive leading compliance-driven technology transitions while food and beverage lags on permanence requirements.
- Pharmaceuticals:Serialization mandates under the EU Falsified Medicines Directive and US Drug Supply Chain Security Act mandate tamper-evident track-and-trace codes. Contract manufacturing organizations across Germany, Switzerland, and India are upgrading fiber laser infrastructure to meet FDA and EMA requirements for export-bound shipments.
- Automotive:Powertrain and chassis components require permanent identification to support warranty management and recall traceability. German precision engineering clusters specify integrated vision-guided marking workstations to reduce commissioning time for multi-model production lines.
- Electronics:Miniaturized semiconductor packages and printed circuit assemblies demand non-contact marking without particulate contamination.
- Food & Beverage:Date coding and lot traceability on packaging materials where CO2 laser systems displace solvent-based inkjet under F-Gas Regulation compliance timelines.
Pharmaceutical end-use retains volume leadership on regulatory compulsion; automotive applications are gaining share fastest as battery cell traceability mandates expand.
Application:
Margin structure diverges between commoditized date coding and value-added branding applications where aesthetic quality commands pricing power.
- Product Identification:Permanent machine-readable codes including Data Matrix, QR, and alphanumeric strings for supply chain traceability. Medical device manufacturers implement product identification to satisfy FDA UDI and EU MDR requirements for unique device identification.
- Branding:High-contrast logos, decorative patterns, and aesthetic surface treatments on premium consumer goods and industrial components. Electronics manufacturers serving data center infrastructure adopt green laser branding on reflective copper busbars without surface damage.
- Date Coding:Variable information printing including expiration dates, lot numbers, and production timestamps on food, beverage, and pharmaceutical packaging.
- Labeling:Adhesive label application integrated with laser-marked substrates for multi-layer identification systems.
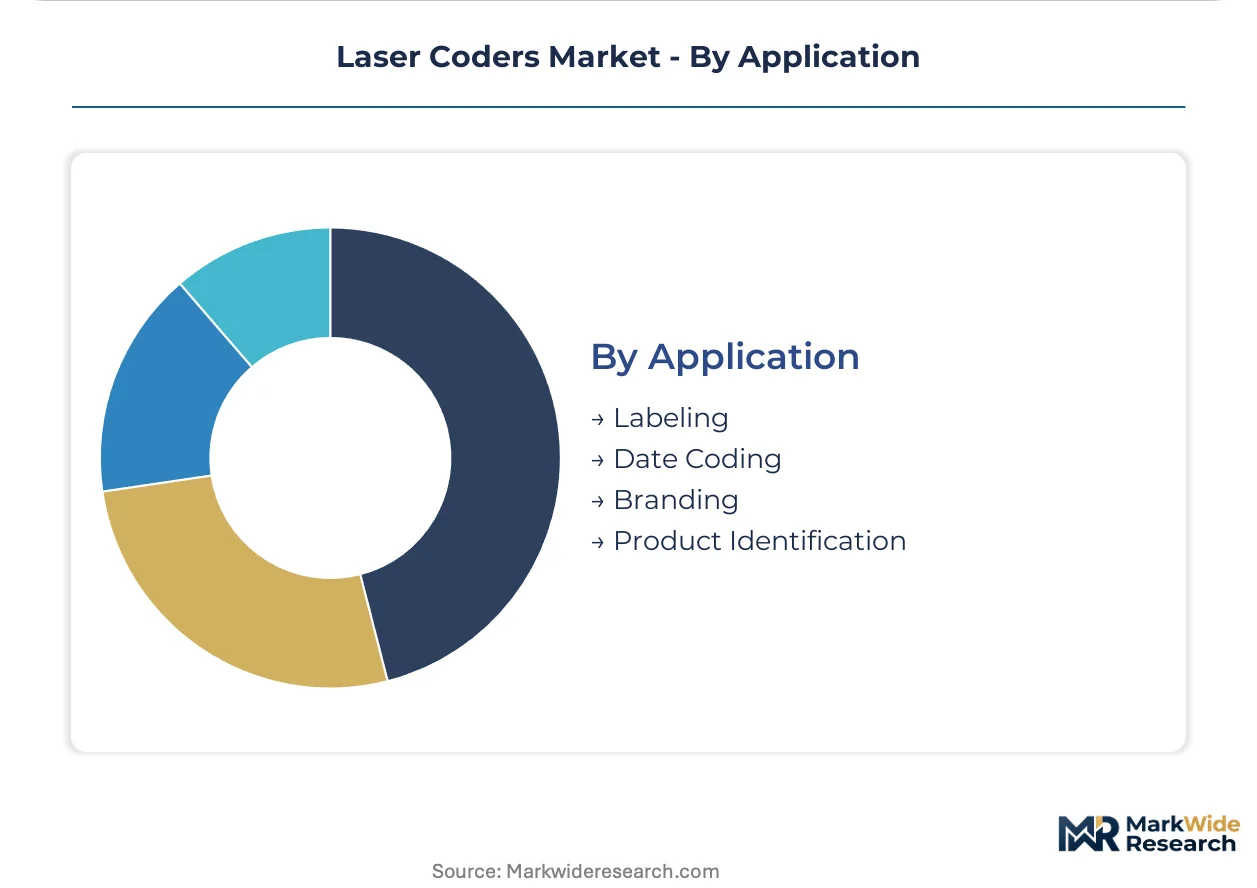
Product identification retains volume leadership across regulated verticals; branding applications hold the steepest expansion curve as aesthetic differentiation gains priority in electronics and luxury goods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian pharmaceutical contract manufacturers exhibit the highest price elasticity as they upgrade legacy inkjet lines to meet export compliance, while German automotive OEMs absorb premium fiber laser costs without procurement friction due to warranty traceability mandates.
Germany
Automotive powertrain and chassis component traceability drives fiber laser demand among OEMs and tier-1 suppliers. REACH compliance and F-Gas Regulation restrictions systematically displace solvent-based marking systems in manufacturing clusters. Bavaria's precision engineering corridor around Munich deploys integrated vision-guided marking workstations to compress commissioning cycles for multi-model production lines.
United States
FDA UDI mandates for permanent device identifiers on medical device packaging accelerate laser coder deployment in cleanroom environments. The Drug Supply Chain Security Act serialization requirements force pharmaceutical manufacturers toward tamper-evident track-and-trace infrastructure. Medical device manufacturing concentrates in Minnesota and Massachusetts, where contract manufacturers upgrade marking stations to satisfy durability specifications.
India
CDMO facilities serving regulated export markets face compressed upgrade timelines to meet FDA and EMA serialization requirements for US and EU-bound pharmaceutical shipments. The country's national pharmaceutical regulator aligns with international traceability standards through progressive mandate implementation. Gujarat and Maharashtra pharmaceutical corridors are replacing continuous inkjet systems with fiber laser infrastructure to eliminate solvent storage liabilities and emissions compliance costs.
China
Electronics contract manufacturers adopt UV laser systems for semiconductor packaging marking as die miniaturization intensifies heat sensitivity constraints. GB standards for product traceability and circular economy mandates expand laser marking requirements across battery cell production. Yangtze River Delta electronics clusters implement 355 nm cold marking technology to protect adjacent circuitry during high-density package identification.
Switzerland
Precision pharmaceutical and medical device manufacturers specify premium laser coding systems to satisfy Swissmedic durability and cleanliness requirements. The country's pharmaceutical regulator maintains stringent code permanence standards that exceed baseline EU MDR specifications. Basel-area life sciences manufacturing facilities favor outcome-based service contracts over capital purchases to preserve operational expenditure flexibility.
Laser Coders Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with ytterbium fiber source ownership determining upstream margin capture. The competitive map separates vertically integrated laser source manufacturers from system integrators dependent on external component supply. Three archetypes dominate: captive fiber producers controlling core technology, vision-integrated workstation specialists, and regional fabrication houses serving cost-sensitive batch producers. Consolidation pressure and wavelength diversification represent the primary competitive vectors as substrate compatibility requirements multiply.
Among German-engineered precision specialists, TRUMPF exemplifies the integrated manufacturing archetype with in-house fiber laser production, while Keyence Corporation represents the vision-guided workstation convergence model. IPG Photonics Corporation anchors the upstream control tier through captive ytterbium doped fiber manufacturing. Domino Printing Sciences and Videojet Technologies occupy positions within the marking systems integration segment, bridging legacy inkjet replacement demand with laser technology transitions.
| Leading Market Players |
|---|
| Domino Printing Sciences |
| Videojet Technologies |
| Markem-Imaje |
| Danaher Corporation |
| Keyence Corporation |
| IPG Photonics Corporation |
| TRUMPF |
| Coherent Corp. |
| Han's Laser Technology Industry Group Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term service contracts with capacity reservation clauses lock in ytterbium fiber supply access for German automotive OEMs while freezing after-sales pricing visibility across multi-year equipment lifecycles. This contract structure concentrates procurement leverage among vertically integrated fiber laser producers and compresses margin flexibility for independent system integrators serving pharmaceutical contract manufacturers in India and Switzerland.
Pricing Analysis
After-sales service and consumable subscription tiers drive lifetime value capture more than initial hardware margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and geographic service network density. Cost compression in the economy tier is intensifying because Indian CDMOs prioritize operational expenditure flexibility over capital ownership. Small-batch producers in European food packaging exhibit the highest price sensitivity, while German automotive OEMs absorb premium positioning without procurement friction due to warranty traceability mandates.
Supply Chain Analysis
Inventory lead times for ytterbium-doped fiber laser sources stretch substantially longer than for CO2 gas laser tubes or UV solid-state components. Supply concentrates in Germany, the United States, and China, with captive fiber production anchoring upstream control for integrated manufacturers. Raw material dependencies center on rare-earth elements, specialized optical fibers, and precision motion control subsystems. Single-source vulnerability in ytterbium fiber supply creates structural risk for independent system integrators. Distribution runs through direct sales forces for automotive and pharmaceutical verticals, with regional fabrication houses serving cost-sensitive batch producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmaceutical contract manufacturers as CDMO consolidation across India and Switzerland compresses vendor selection cycles and forces outcome-based contracting terms.
For Market Incumbents: Consolidate backward integration into ytterbium fiber production to defend margin position against emerging Chinese laser source manufacturers. Expand service network density in Gujarat and Maharashtra pharmaceutical corridors to capture replacement demand from continuous inkjet system obsolescence. Lock in long-term capacity reservation contracts with German automotive OEMs before regulatory serialization deadlines accelerate. For New Entrants and Emerging Players: Lead with vision-guided marking workstation convergence targeting electronics contract manufacturers in China's Yangtze River Delta. Battery cell traceability mandates for lithium-ion producers represent the most penetrable white-space segment. Deploy subscription-based uptime guarantee models to bypass capital purchase barriers among Indian pharmaceutical exporters. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors vision-integrated workstation specialists over pure hardware fabricators. Long-term viability across the analysis window hinges on software and service revenue mix rather than equipment shipment volume. Acquisition targets should demonstrate installed base density in regulated verticals with recurring service contract attachment. Monitor FDA and EMA serialization deadline enforcement as the primary inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Laser Sources | Captive ytterbium fiber production secures supply access and upstream margin capture for German automotive lines. |
| Vision-Guided Marking Workstation Launch | Real-time quality verification reduces commissioning time for electronics contract manufacturers in precision clusters. |
| Outcome-Based Service Contract Expansion | Uptime guarantees align vendor incentives with Swiss pharmaceutical operational expenditure preferences. |
| Battery Cell Traceability System Deployment | Laser direct part marking supports circular economy mandates for lithium-ion electrode identification. |
| Indian Pharmaceutical Corridor Service Network Buildout | Localized technical presence captures CDMO upgrade demand driven by FDA and EMA export compliance. |
Study Parameters
Operator-level perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and pharmaceutical manufacturing directors anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, customs trade records, IEC compliance documentation, and laser safety certification databases. Bottom-up equipment shipment analysis and top-down end-use demand modeling provided cross-verification.
Sensitivity analysis tested forecast outputs against variable adoption rates for UV cold marking technology and regulatory deadline slippage scenarios. Segmentation dimensions spanned laser source type, marking technology, end-use vertical, and regional production cluster. CAGRs were derived from installed base replacement cycles and greenfield capacity expansion patterns. Industry-specific inputs included pharmaceutical serialization mandate enforcement timelines and automotive warranty traceability protocol adoption.
Underlying assumptions cover regulatory compliance deadline adherence and ytterbium fiber supply continuity, with deviation risk concentrated in multijurisdictional standard harmonization delays. Forecasts reflect these conditions without claiming precision against unobservable future states. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Pigment Hot Stamping Foil Market
Packaging Printing
Global Digital Printing Packaging Market
Packaging Printing
Soft Signage Market
Packaging Printing
Digital Label Printing Market
Packaging Printing
Global Electrophotographic Printing in Packaging Market
Packaging Printing
Flexographic Printing Machine Market
Packaging Printing
Flex Banner Market
Packaging Printing
Stack Flexo Printing Press Market
Packaging Printing
Flexographic Printing Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Heat Transfer Press Printing Machine Market
Packaging Printing
Europe Printed Packaging Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
Printed Boxes Market
Packaging Printing
Asia-Pacific Digital Printing Packaging Market
Packaging Printing
Label Printing Software Market