
 Qatar Printing and Packaging Market | 2026-2036
Qatar Printing and Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Printing and Packaging Market Analytics
Modular packaging configurations is decoupling bulk procurement from brand-specific finishing in Qatar's industrial supply chains. Qatar National Printing Press leverages in-house gravure and offset capacity to anchor government and corporate contract flows. Galaxy Carton Factory competes through rigid box specialization for luxury consumer goods re-export. Green Print differentiates via digital short-run capabilities serving event-driven and seasonal promotional cycles.
Printing and packaging encompasses the design, reproduction, and fabrication of protective and communicative enclosures using substrates ranging from coated paper and polymer films to aluminum laminates, with functional parameters including barrier properties, print resolution measured in lines per centimeter, and shelf-life extension through controlled atmosphere engineering. Flexible packaging leads volume consumption in Qatar's market due to its lightweight logistics profile and compatibility with automated filling lines for food and beverage processors. Digital printing represents the fastest-expanding technology segment as pharmaceutical end users demand serialized track-and-trace compliance with shorter production runs. Rigid packaging occupies the premium margin pool where glass and metal formats serve gift-oriented consumer goods and electronics re-export through Hamad Port.
Qatar's Ministry of Municipality and Environment enforces extended producer responsibility frameworks for plastic waste reduction, compelling converters toward recyclable mono-material structures and bio-based alternatives. The Qatar General Organization for Standardization (QS) mandates labeling conformity for food contact materials and pharmaceutical serialization, shaping product standards and market access thresholds. Stakeholders must monitor how sustainability certification requirements and digital workflow investments reshape supplier qualification criteria without explicit regulatory deadlines.
Market Dynamics
Qatar's single-use plastics reduction mandates are forcing converters toward recyclable mono-material structures and bio-based alternatives, compressing legacy multi-layer film demand while creating qualification barriers for non-compliant suppliers.
Growth Catalysts
- Extended Producer Responsibility Frameworks:The Ministry of Municipality and Environment's waste reduction mandates accelerate investment in recyclable packaging infrastructure among Doha-based converters.
- Pharmaceutical Serialization Requirements:Qatar General Organization for Standardization labeling conformity rules drive digital printing adoption for track-and-trace compliance in drug exports.
- Food and Beverage Processing Clusters:Automated filling lines in Doha's industrial zones pull demand for flexible packaging formats compatible with high-speed production.
Market Restraints
- Petrochemical Feedstock Volatility:Polymer resin costs fluctuate with regional hydrocarbon pricing, squeezing converter margins on fixed-price government contracts.
- Gravure Cylinder Supply Concentration:Specialized engraving services concentrate in European and East Asian supplier bases, extending lead times for Qatar-based high-volume print runs.
- Multi-Material Recycling Technical Limits:Laminated barrier structures with aluminum foil layers resist mechanical recycling streams, creating compliance gaps with circular economy targets.
Strategic Opportunities
- Bio-Based Polymer Feedstocks:PLA and PHA alternatives from agricultural waste streams offer pathways to meet Ministry sustainability certification requirements.
- Digital-Offset Hybrid Workflows:Convergence of inkjet personalization with offset base printing enables pharmaceutical short-runs without cylinder changeover costs.
- Hamad Port Re-Export Logistics:Gift-oriented rigid packaging for electronics and luxury goods leverages Qatar's transshipment infrastructure for Gulf Cooperation Council markets.
Industry Challenges
- Serialized Track-and-Trace Integration:Pharmaceutical packagers face software-hardware alignment costs connecting digital presses to national verification databases.
- Mono-Material Barrier Performance Gaps:Recyclable polyethylene structures struggle to match aluminum laminate shelf-life extension for sensitive food products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Printing and Packaging Market |
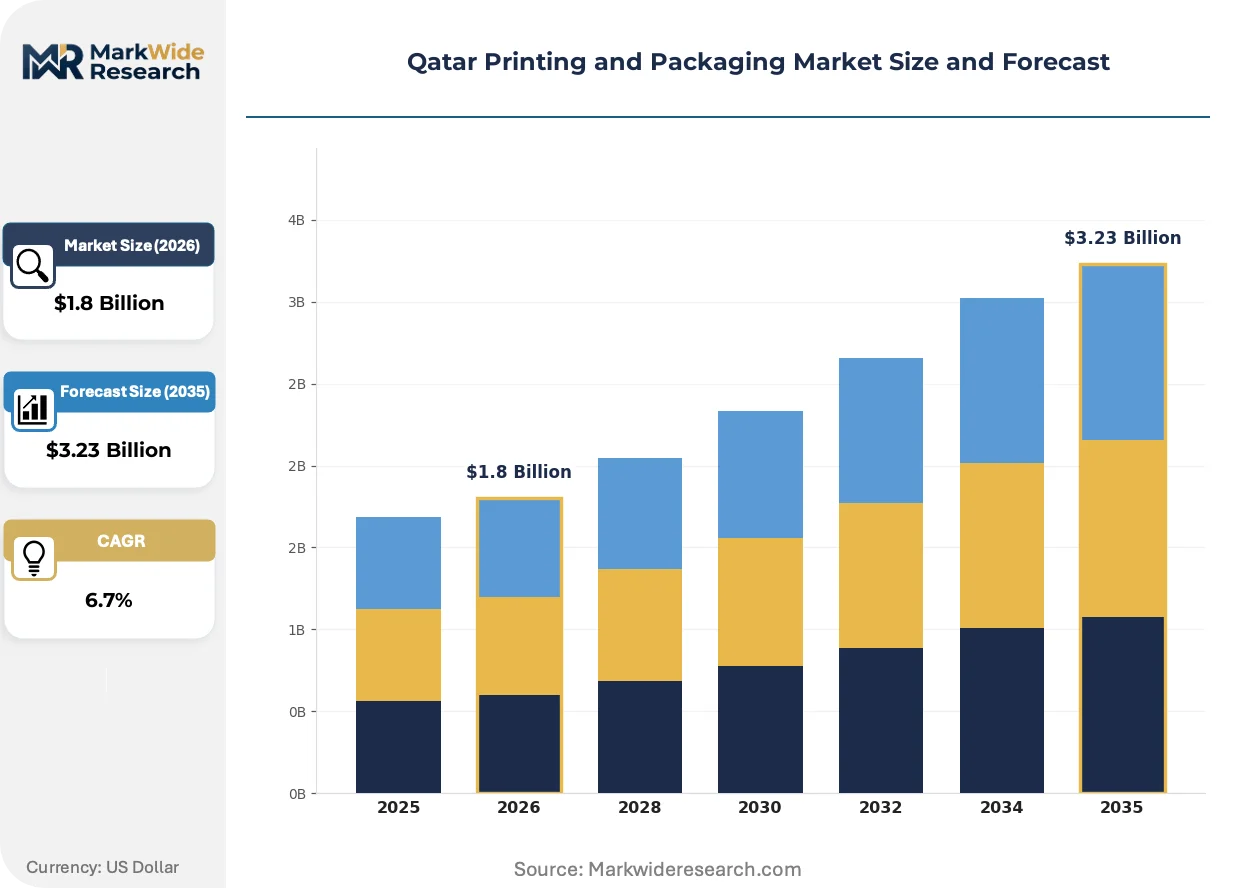
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Flexible Packaging, Rigid Packaging, Specialty Print Material: Paper, Plastic, Metal, Glass End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Printing Technology: Digital Printing, Flexo Printing, Offset Printing, Gravure Printing |
| Companies Covered | Qatar National Printing Press (QNPP), Green Print, Aspire Printing, Qatar Polymer Industrial Company, Jama Plastic Industries Factory (JPIF), Arabian Packaging Industries, MATCO Packaging LLC, New Printing Company, Galaxy Carton Factory, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Printing and Packaging Market Evolving Landscape
Digital printing architectures are penetrating pharmaceutical and promotional segments previously dominated by gravure, while regulatory pressure on plastic waste forces substrate innovation at unprecedented speed.
Water-based flexographic ink systems is converging with high-definition plate imaging to enable food-contact compliant printing without solvent recovery infrastructure. Mid-sized converters serving dairy and snack processors adopt these systems to bypass emissions permitting bottlenecks. The technology is converging with inline quality inspection, collapsing pre-press-to-delivery cycles from weeks to days for seasonal promotional campaigns.
The Ministry of Municipality and Environment's extended producer responsibility enforcement compels converters to document recyclability pathways for all packaging placed on market. Industrial consequence includes mandatory design-for-recycling audits and penalty structures for non-compliant materials. Food and beverage processors in Doha industrial zones respond by specifying mono-material polyethylene structures despite 15-20% barrier performance trade-offs against legacy laminates.
Brand procurement teams now unbundle specification development from production execution, engaging specialized design studios for structural engineering while sourcing manufacturing through competitive tender. This disintermediation compresses converter margins on creative services while shifting value capture upstream. Pharmaceutical and luxury goods exporters through Hamad Port demonstrate this pattern most visibly, separating brand asset control from geographic production placement.
Qatar Printing and Packaging Market Segmentation
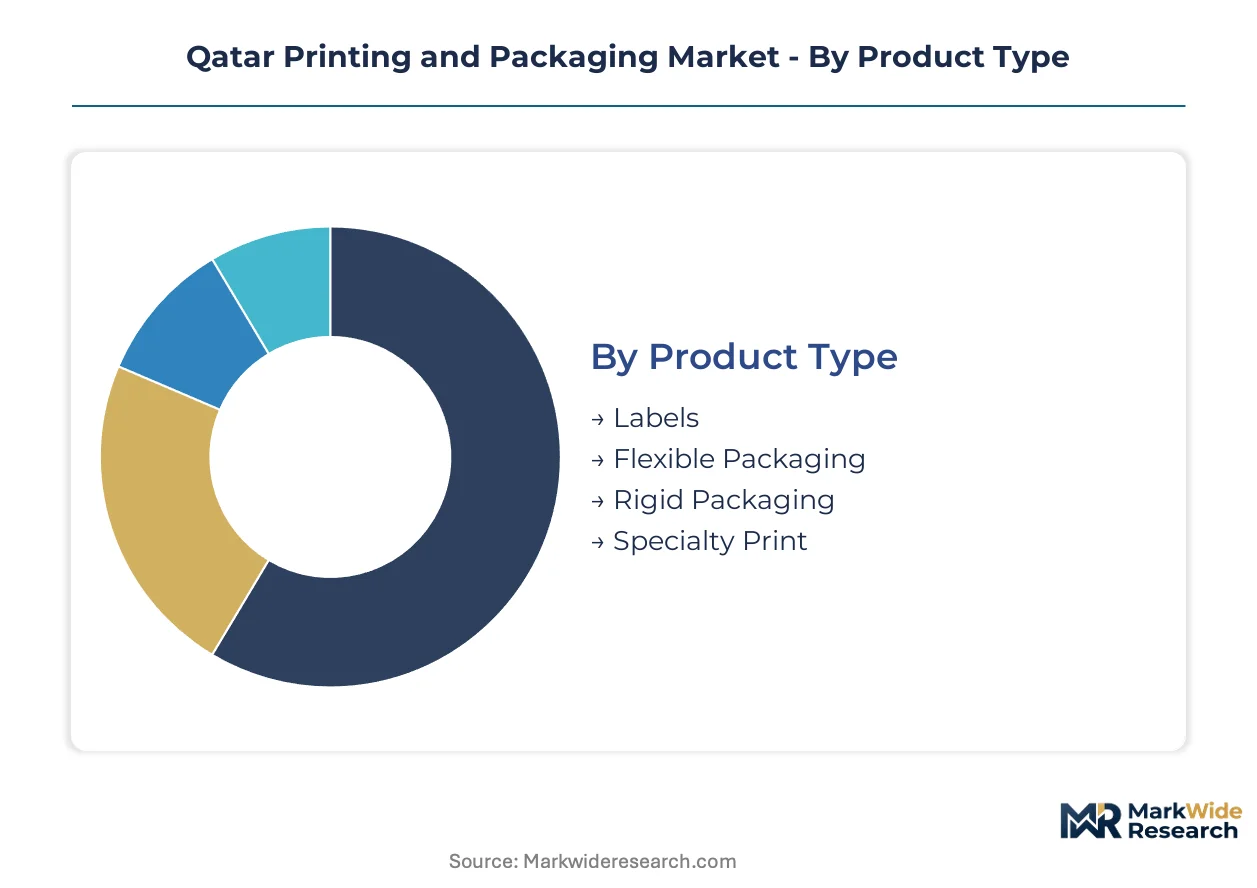
Qatar's printing and packaging market segments reflect divergent buyer priorities across regulatory compliance, logistics efficiency, and brand positioning. Understanding these divisions reveals where converter investments concentrate and which technology platforms capture margin.
Product Type:
Buyers differentiate by protection requirements versus communication intensity, with automated filling lines and shelf-life extension driving specification divergence.
- Flexible Packaging:Multi-layer polymer laminates and mono-material polyethylene structures dominate food and beverage applications. Demand concentrates in Doha's industrial zones where processors seek lightweight formats compatible with high-speed filling equipment and Qatar's single-use plastics reduction mandates.
- Rigid Packaging:Glass, metal, and corrugated board enclosures serve premium gift-oriented consumer goods and electronics re-export through Hamad Port. Specifications emphasize structural integrity for transshipment handling and luxury unboxing experiences.
- Labels:Pressure-sensitive and shrink-sleeve formats carry regulatory serialization for pharmaceuticals and brand differentiation for beverages.
- Specialty Print:Security printing and high-fidelity promotional materials serve government contracts and seasonal campaigns.
Volume sits with flexible formats serving mass-market food processors; growth tilts toward rigid packaging for Hamad Port re-export corridors.
Material:
Specification choices hinge on recyclability compliance versus barrier performance trade-offs under Ministry of Municipality and Environment enforcement.
- Plastic:Polyethylene, polypropylene, and emerging PLA alternatives span flexible films and rigid containers. Food and beverage processors in Doha industrial zones specify mono-material structures despite barrier performance gaps with legacy laminates.
- Paper:Coated and uncoated stocks, corrugated board, and molded fiber serve secondary packaging and sustainable primary formats. Pharmaceutical exporters favor paperboard for serialization compatibility and patient information leaflets.
- Metal:Aluminum cans and tinplate containers preserve shelf-stable foods and premium beverages.
- Glass:Molded bottles and jars target luxury cosmetics, spirits, and pharmaceutical syrups requiring inert contact surfaces.
Plastic commands current volume through flexible packaging dominance; paper gains share fastest as converters retool for circular economy audits.
End User:
Application-specific regulations and automation requirements fragment procurement specifications across Qatar's industrial base.
- Food & Beverage:Dairy, snack, and beverage processors in Doha industrial zones pull flexible packaging demand. Qatar General Organization for Standardization labeling conformity rules shape material selection and print verification protocols.
- Pharmaceuticals:Drug manufacturers and contract packagers require serialized track-and-trace compliance. Digital printing adoption accelerates here for short-run flexibility and national verification database integration.
- Consumer Goods:Personal care and household product brands balance shelf impact with logistics cost containment.
- Electronics:Re-export through Hamad Port drives anti-static rigid packaging and premium unboxing structures for Gulf Cooperation Council markets.
Food and beverage anchors volume through processing cluster scale; pharmaceuticals expand most quickly on serialization mandate deadlines.
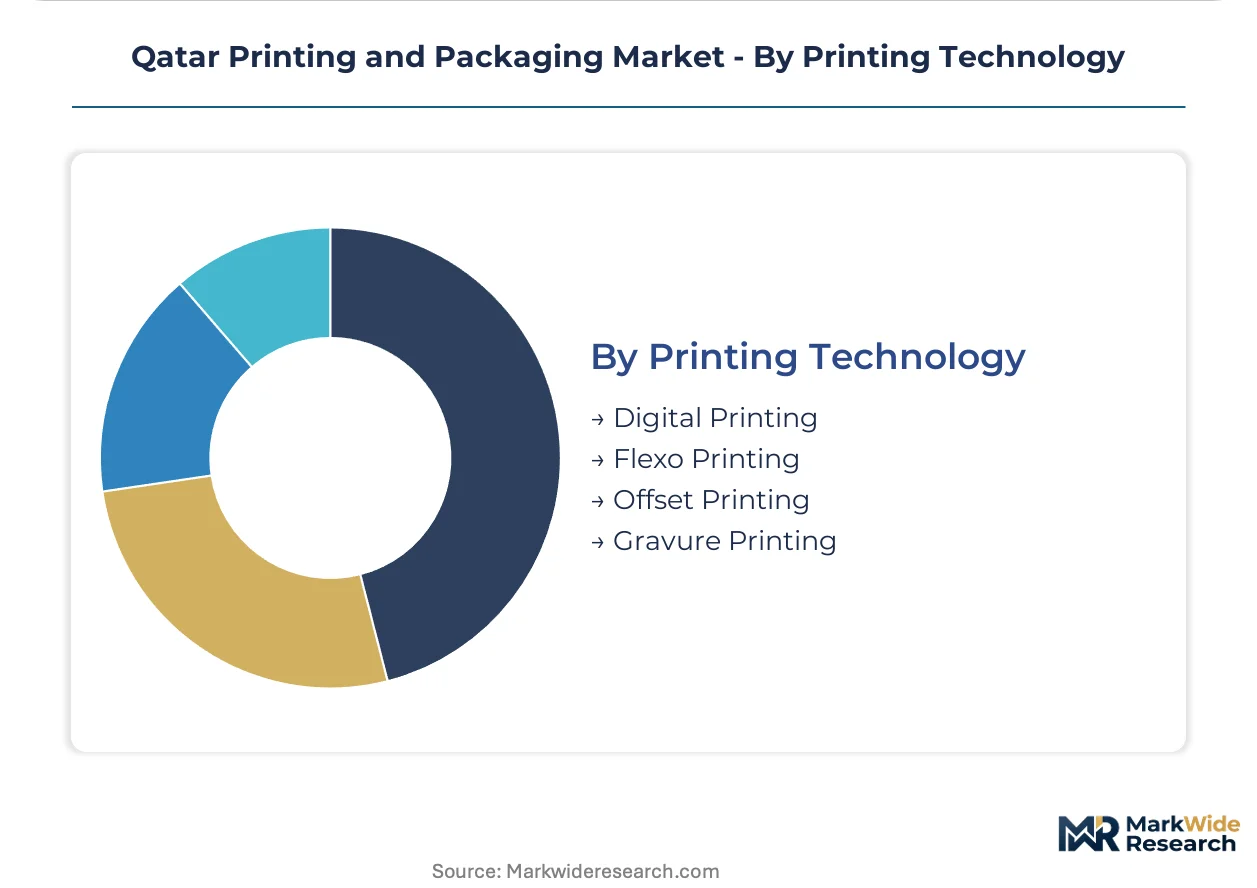
Printing Technology:
Capital intensity and changeover economics separate high-volume gravure adopters from digital entrants serving variable-data requirements.
- Digital Printing:Inkjet and toner systems enable pharmaceutical serialization and promotional short-runs without cylinder investment. Qatar National Printing Press and mid-sized converters deploy these for event-driven campaigns and compliance-driven drug packaging.
- Gravure Printing:Cylinder-based high-volume reproduction serves government contracts and long-run flexible packaging. European and East Asian engraving supply concentration extends lead times for Qatar-based operations.
- Flexo Printing:Water-based and UV-cured flexographic systems serve food-contact compliant labels and flexible films. Inline quality inspection convergence collapses pre-press-to-delivery cycles.
- Offset Printing:Sheet-fed and web offset lithography handles folding cartons and commercial print with color consistency advantages.
Gravure retains volume through government and export contract scale; digital climbs the fastest on pharmaceutical track-and-trace mandates and hybrid workflow adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's packaging production capacity outstrips domestic consumption, positioning converters as regional suppliers for Gulf Cooperation Council re-export corridors. Doha industrial zones anchor converter investment, while regulatory harmonization with Saudi and UAE standards shapes cross-border qualification protocols.
Doha Metropolitan Area
Food and beverage processing clusters in Doha's industrial zones pull flexible packaging demand from automated dairy and snack lines. Qatar General Organization for Standardization labeling conformity rules mandate serialization compatibility for pharmaceutical exports. Ras Laffan and Mesaieed industrial cities concentrate polymer feedstock access and converter co-location.
Al Wakrah Industrial Corridor
Hamad Port logistics infrastructure drives rigid packaging investment for electronics and luxury goods re-export to Saudi Arabia and Kuwait. The Ministry of Municipality and Environment's extended producer responsibility frameworks compel recyclability documentation for all export-bound materials. Al Wakrah's free zone status attracts foreign converter joint ventures serving GCC transshipment.
Al Khor Manufacturing Zone
North Qatar's industrial expansion targets petrochemical downstream integration into packaging substrates. QatarEnergy's polymer supply agreements anchor converter feedstock security for polyethylene and polypropylene films. Al Khor's emerging cluster serves construction materials and agricultural packaging for domestic food security programs.
Lusail Development District
Smart city infrastructure and event-driven promotional cycles generate digital printing demand for seasonal campaigns and government communications. Qatar National Printing Press maintains gravure capacity for long-run government contracts in this zone. Lusail's mixed-use development creates specialty print requirements for retail and hospitality fit-outs.
Umm Salal Logistics Hub
Inland container depot connectivity supports just-in-time packaging supply to Doha processors while reducing port congestion exposure. Bio-based polymer warehousing and distribution nodes are emerging here to serve Ministry sustainability certification requirements. Umm Salal's location optimizes last-mile delivery to northern industrial zones.
Qatar Printing and Packaging Market Competitive Landscape
The competitive structure tilts toward state-affiliated and family-owned enterprises with long-standing government contract relationships. Market concentration remains moderate, with no single converter commanding dominant share across all substrate categories. Three archetypes define competitive positioning: integrated polymer-to-package operators, specialized rigid box fabricators, and digital short-run service providers. Capacity expansion and sustainability certification acquisition represent the dominant competitive moves as converters respond to Ministry audit requirements.
Among state-linked and established private operators, Qatar National Printing Press, Galaxy Carton Factory, and Green Print occupy distinct archetype positions. Qatar National Printing Press represents the integrated gravure-offset incumbent with anchored government contract flows. Galaxy Carton Factory exemplifies rigid packaging specialization targeting luxury consumer goods re-export. Green Print sits within the digital-native tier serving event-driven promotional cycles and compliance-driven pharmaceutical short-runs.
| Leading Market Players |
|---|
| Qatar National Printing Press (QNPP) |
| Green Print |
| Aspire Printing |
| Qatar Polymer Industrial Company |
| Jama Plastic Industries Factory (JPIF) |
| Arabian Packaging Industries |
| MATCO Packaging LLC |
| New Printing Company |
| Galaxy Carton Factory |
| Others |
Value Network & Pricing Analysis
Qatar's Ministry of Municipality and Environment extended producer responsibility mandates gate qualified supply access and premium-tier pricing power, forcing converters to absorb sustainability certification costs or forfeit government and pharmaceutical contract eligibility.
Pricing Analysis
Margin tightening in standard-grade flexible packaging reflects petrochemical feedstock volatility and fixed-price government contract exposure. Three-tier pricing structure across premium certified, standard compliant, and economy non-compliant levels segments buyers by Ministry audit status. Cost-down pressure on mono-material structures accelerates because barrier performance trade-offs against legacy laminates force renegotiation with food processors. Pharmaceutical exporters demonstrate lowest price sensitivity due to serialization compliance requirements, while commodity snack processors drive hardest bargain.
Supply Chain Analysis
Specialized gravure cylinder engraving services concentrate in Germany, Italy, and Japan, constraining Qatar-based high-volume print capacity expansion. Polymer resin supply draws from Saudi Arabia, UAE, and South Korean petrochemical exporters, with converter margins tethered to regional hydrocarbon pricing swings. Single-source vulnerability in European engraving infrastructure extends lead times for government contract fulfillment. Distribution runs through Hamad Port free zone warehousing for GCC re-export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive polymer feedstock supply and in-house digital printing capacity determine contract win rates against import-dependent competitors.
For Market Incumbents: Lock in long-term polymer supply agreements with QatarEnergy to defend against resin cost volatility squeezing fixed-price government contracts. Acquire digital printing certification for pharmaceutical serialization before track-and-trace mandates harden qualification barriers. Backward integration into bio-based PLA feedstock development secures Ministry sustainability audit compliance.
For New Entrants and Emerging Players: Digital-native short-run capabilities offer a technology-first wedge into event-driven promotional cycles and seasonal campaign niches underserved by gravure-heavy incumbents. Target pharmaceutical contract packagers in Doha industrial zones seeking serialization compliance without cylinder changeover delays. Lead with water-based flexographic food-contact compliance to bypass emissions permitting bottlenecks constraining solvent-based competitors.
For Investors and Strategic Acquirers: Accelerated Ministry audit penalty enforcement is the leading indicator that sustainability-certified converter assets will command scarcity premiums. Five-to-ten year viability favors mid-sized operators with hybrid digital-offset workflows and documented recyclability pathways. Monitor Qatar General Organization for Standardization labeling conformity rule expansion as inflection signal for compliance-tech investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | QatarEnergy supply agreements anchor resin cost stability for flexible film converters. |
| Digital Printing Certification Investment | Pharmaceutical serialization mandates drive track-and-trace compliance capability acquisition. |
| Bio-Based Material Qualification | Ministry sustainability audits reward PLA and PHA alternative documentation. |
| Hamad Port Free Zone Expansion | GCC re-export logistics infrastructure captures electronics and luxury goods packaging flows. |
| Gravure Cylinder Inventory Pre-Positioning | European engraving lead time mitigation secures government contract delivery reliability. |
Research Methodology
Document review covered Qatar General Organization for Standardization regulatory filings, Ministry of Municipality and Environment enforcement notices, and GCC customs trade data, complemented by interviews with flexible packaging plant managers, pharmaceutical contract packager procurement leads, gravure cylinder supply specialists, and food processor specification engineers. Secondary validation drew from Qatar Central Bank industrial sector reports, Hamad Port throughput statistics, and petrochemical feedstock pricing benchmarks. Bottom-up converter capacity assessments triangulated against top-down end-use demand modeling.
Segment-level value and volume trajectories across the projection horizon reflect product type, material substrate, end-use application, and printing technology dimensions. CAGRs were derived from regression analysis against polymer resin cost indices, regulatory compliance cost curves, and pharmaceutical export growth patterns. Modeling incorporated Ministry audit penalty probability, digital press adoption rates, and Hamad Port transshipment volume elasticity.
Several conditions sit outside the modeled scope, including abrupt GCC trade policy shifts, breakthrough barrier coating technologies eliminating mono-material performance gaps, and sovereign wealth fund direct converter acquisition activity. Forecasts assume continued Ministry enforcement trajectory and pharmaceutical serialization deadline adherence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Global Digital Printing Packaging Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Digital Label Printers Market
Packaging Printing
Soft Signage Market
Packaging Printing
Flexographic Printing Machine Market
Packaging Printing
Flex Banner Market
Packaging Printing
Pigment Hot Stamping Foil Market
Packaging Printing
Europe Printed Packaging Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
Electrophotography Printing for Packaging Market
Packaging Printing
Label Printing Software Market
Packaging Printing
North America Print Label Market
Packaging Printing
Global Pre Print Flexo Press Market
Packaging Printing
Printed Boxes Market
Packaging Printing
Pre-Printed Liners Market