
 Areca Plates Market | 2026-2036
Areca Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Areca Plates Market Outlook
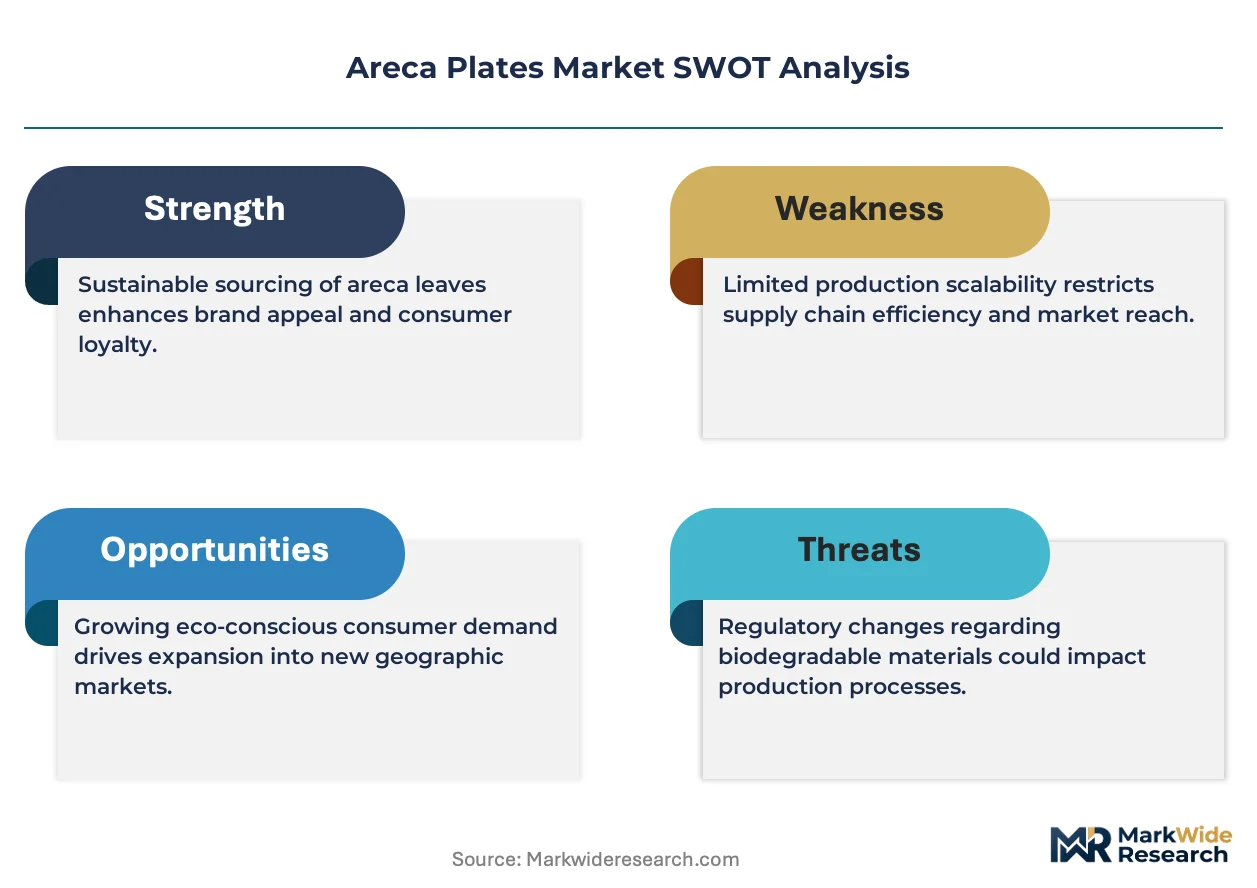
ISO 17088 compostability certification is unwinding competitive access across the Areca Plates Market, filtering out uncertified producers in India and Southeast Asia. GreenHaven Bioproducts leverages integrated leaf collection networks across South India to sustain raw material cost advantages. Kiran Global Exports anchors European foodservice penetration through BRCGS-accredited production lines. EcoLeaf Solutions differentiates via proprietary moisture-resistant coating technology that extends shelf stability in humid climates.
Areca plates are rigid, single-use serving vessels pressed from fallen areca palm sheaths without chemical binders, typically measuring 6-12 inches in diameter and degrading within 60-90 days in industrial composting. These products serve institutional foodservice and event catering segments seeking plastic-alternative tableware with verified end-of-life pathways. Round plates dominate current volume owing to standardized pressing dies and universal serving utility across cuisines. Compartment plates capture expanding demand from institutional catering contracts requiring portion separation. Serving trays remain a premium-margin segment where bamboo-reinforced variants command price premiums in specialty retail channels.
India's BIS standards for disposable tableware, the EU's Packaging and Packaging Waste Regulation, and the US FDA's food contact substance notifications collectively shape product specifications and cross-border market access for areca plate exporters. Compliance with compostability verification protocols now functions as a de facto trade barrier, advantaging producers with in-house testing laboratories. Stakeholders must monitor evolving extended producer responsibility schemes in target export markets, as fee structures and collection infrastructure requirements will determine which production geographies retain cost-competitive positioning.
Market Dynamics
ISO 17088 compostability certification is filtering producer access across the Areca Plates Market, advantaging integrated manufacturers with in-house testing laboratories while marginalizing small-scale press operators lacking verification infrastructure.
Growth Catalysts
- EU Single-Use Plastics Directive:Institutional foodservice operators across Germany, France, and the Netherlands are accelerating procurement of verified compostable tableware to comply with bans on conventional plastic serveware.
- Kerala-Karnataka-Tamil Nadu collection networks:Dense areca palm plantations in South India enable integrated leaf aggregation systems that compress raw material logistics costs for regional producers.
- Moisture-resistant coating advances:Proprietary barrier technologies are extending shelf stability in humid climates, unlocking export viability to tropical foodservice markets previously inaccessible to uncoated areca products.
Market Restraints
- Seasonal leaf supply volatility:Monsoon patterns in South India disrupt collection cycles, creating input cost spikes during Q3-Q4 that compress margins for non-integrated processors.
- Bamboo-palm hybrid substitution:Reinforced bamboo fiber tableware commands price premiums in specialty retail, diverting institutional buyers seeking elevated aesthetic positioning.
- BRCGS accreditation thresholds:European foodservice distributors require certified production lines, excluding uncertified Indian and Southeast Asian suppliers from premium contract tiers.
Strategic Opportunities
- Compartment plate penetration:Institutional catering contracts requiring portion separation represent underexploited demand within the North American education and healthcare sectors.
- Extended producer responsibility tailwinds:Emerging fee structures in EU member states advantage compostable tableware with verified end-of-life pathways, creating preferential procurement frameworks.
- Direct-to-hotel distribution:Bypassing traditional hospitality supply intermediaries allows areca plate manufacturers to capture margin previously allocated to wholesale distributors.
Industry Challenges
- ISO 17088 testing timeline compression:Certification cycles extending 6-12 months delay market entry for new product formulations, straining working capital for mid-scale producers.
- Press die standardization gaps:Non-uniform equipment specifications across Indian manufacturing clusters complicate quality consistency for export-grade output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Areca Plates Market |
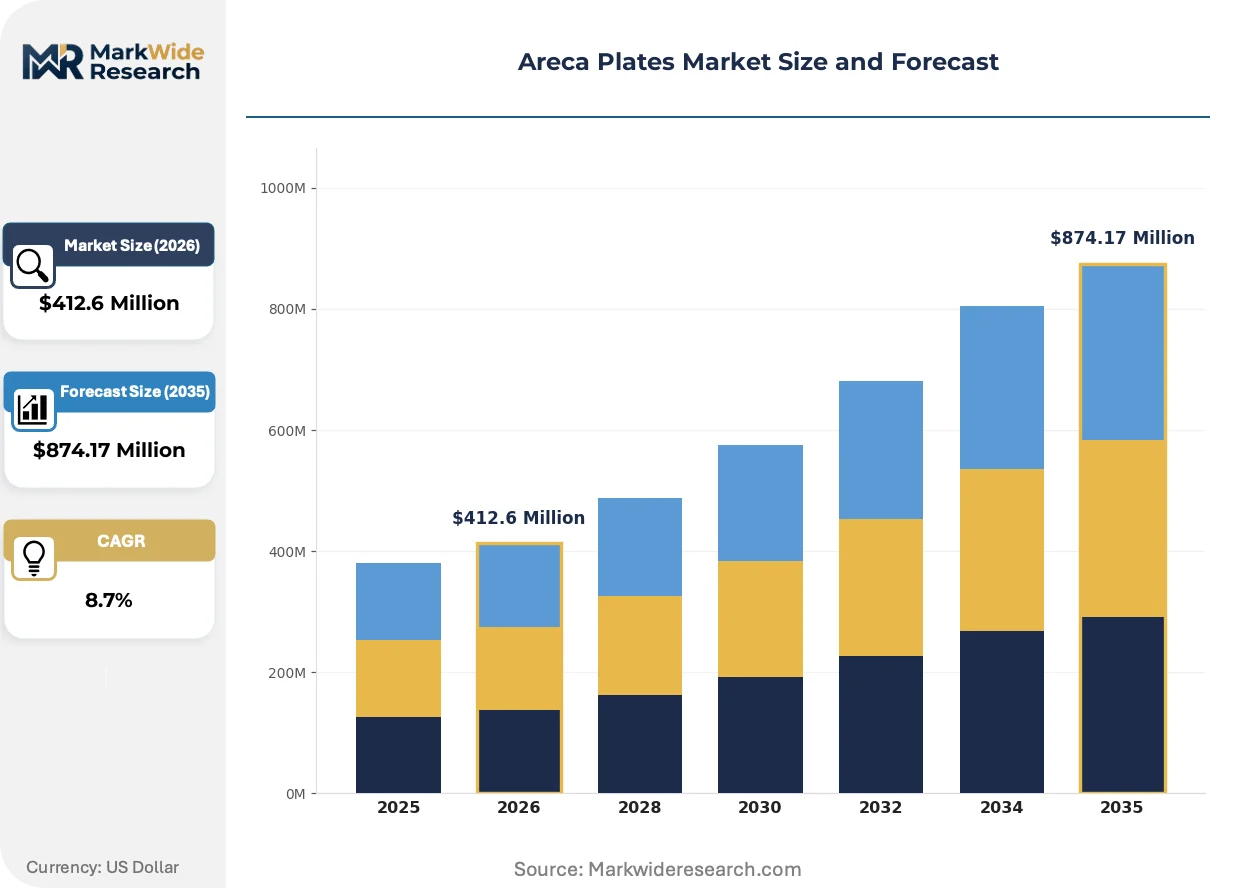
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Plates, Square Plates, Compartment Plates, Serving Trays Raw Material: Areca Nut Leaves, Palm Leaves, Bamboo, Wood End User: Restaurants, Catering Services, Households, Events Distribution Channel: Online Retailers, Grocery Stores, Specialty Shops, Wholesale |
| Companies Covered | GreenHaven Bioproducts, Kiran Global Exports, EcoLeaf Solutions, Vegware Ltd., Nature Packwell Pvt Ltd, NatureServe Innovations, LeafLogic Systems, BioPak, Verdant Table Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Areca Plates Market Strategic Shifts
Proprietary coating chemistry and automated pressing systems are compressing quality variance across the Areca Plates Market, enabling tier-1 producers to displace hand-pressed imports in price-sensitive institutional channels.
Moisture-resistant barrier coatings derived from plant-based polymers are decomposing the traditional trade-off between compostability and humidity tolerance. European foodservice distributors are specifying coated variants for tropical climate deployments. This technology is decomposing regional supply advantages by enabling non-tropical producers to compete for Southeast Asian export contracts.
REACH-compliant additive formulations are reshaping cross-border material specifications for areca plate exporters targeting EU foodservice channels. The European Chemicals Agency's evolving restricted substance lists now govern coating chemistries and pressing lubricants. German and French institutional buyers are requiring full material disclosure documentation, compressing supplier qualification timelines.
Certification-driven procurement mandates are restructuring buyer-supplier relationships across institutional foodservice. Large-scale catering operators are consolidating vendor bases around dual-certified producers holding both ISO 17088 and BRCGS credentials. This concentration is most visible in the Netherlands and Belgium, where government procurement frameworks now embed compostability verification as a mandatory evaluation criterion.
Areca Plates Market Segmentation
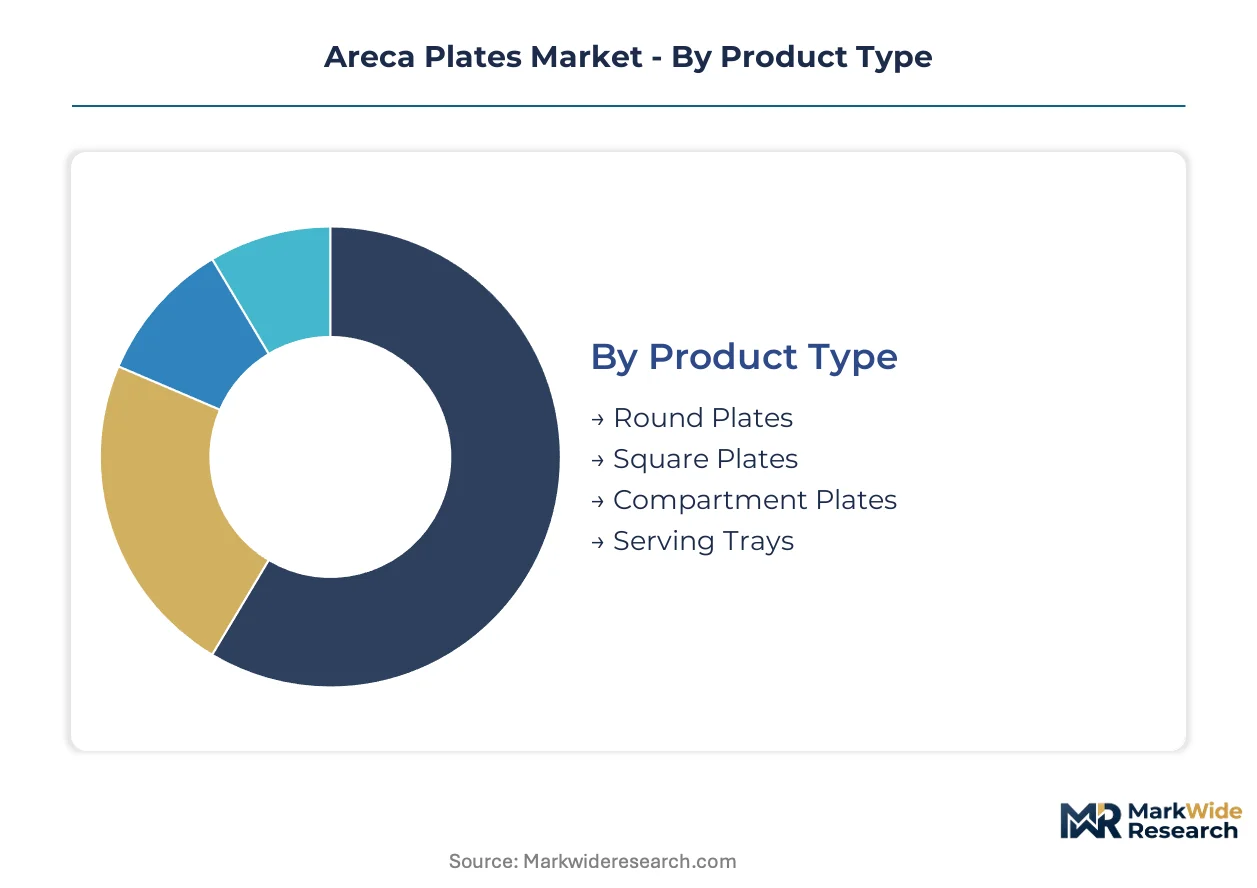
Areca plate manufacturers navigate divergent margin structures across product geometries and raw material sourcing strategies. Channel economics vary sharply between institutional procurement and retail distribution, forcing portfolio prioritization decisions that reshape competitive positioning.
Product Type:
Foodservice distributors route round and compartment variants through institutional procurement channels, while specialty retail absorbs premium serving trays.
- Round Plates:Pressed from single areca sheath sections using standardized dies, these 6-12 inch vessels serve universal cuisine formats. Kerala-based producers supply German and Dutch institutional foodservice operators seeking ISO 17088-verified compostable serveware under EU Single-Use Plastics Directive compliance mandates.
- Compartment Plates:Multi-cavity designs with 2-4 portion separations require complex die configurations and stronger raw material selection. North American education and healthcare catering contracts in the United States and Canada are absorbing rising volumes as portion-controlled meal delivery expands.
- Square Plates:Angular geometry demands modified pressing equipment with corner reinforcement. Contemporary plating aesthetics in premium casual dining drive niche adoption.
- Serving Trays:Larger format pressedware with reinforced rim structures commands specialty retail placement. Bamboo-areca hybrid variants penetrate gift and home goods channels.
By volume, round plates lead. By growth pace, compartment plates are expanding most quickly.
Raw Material:
Input cost tiers stratify producer economics, with captive leaf collection networks compressing logistics spend for integrated operators.
- Areca Nut Leaves:Fallen sheaths from Areca catechu palms in Karnataka and Tamil Nadu supply the dominant feedstock. South Indian producers with direct farmer collection contracts sustain 15-20% raw material cost advantages over non-integrated competitors.
- Palm Leaves:Broader Arecaceae family sourcing expands geographic supply bases to Indonesia and Sri Lanka. EUDR due diligence requirements are complicating traceability documentation for European-bound shipments.
- Bamboo:Phyllostachys and Bambusa species provide fiber reinforcement for hybrid products. Higher tensile strength supports thinner-wall designs with reduced material intensity.
- Wood:Rubberwood and acacia offcuts from furniture manufacturing enter pressedware as composite fillers. FSSAI food contact approvals constrain viable species selection for Indian domestic sales.
Areca nut leaves dominate tonnage throughput. Bamboo blends capture the steepest margin expansion trajectory in specialty segments.
End User:
Contract duration and specification rigor vary dramatically across buyer categories, with institutional accounts demanding certification depth that excludes smaller producers.
- Restaurants:Full-service and quick-service operators in France, Germany, and the Netherlands specify BRCGS-accredited production lines for dine-in and takeaway applications. Procurement consolidation around dual-certified vendors is compressing supplier counts.
- Catering Services:Event and institutional caterers in the United States and United Kingdom prioritize portion control and stackability for logistics efficiency. Compartment plate penetration is deepest in this channel.
- Households:Retail-packaged assortments through Amazon and specialty grocers serve sustainability-motivated consumers. Seasonal demand spikes align with outdoor entertaining cycles.
- Events:Wedding and festival catering in India and Southeast Asia drives bulk procurement of uncoated economy grades. Price sensitivity limits coating technology adoption.
Restaurants generate the highest revenue per unit. Catering services are gaining share fastest as contract catering scales.
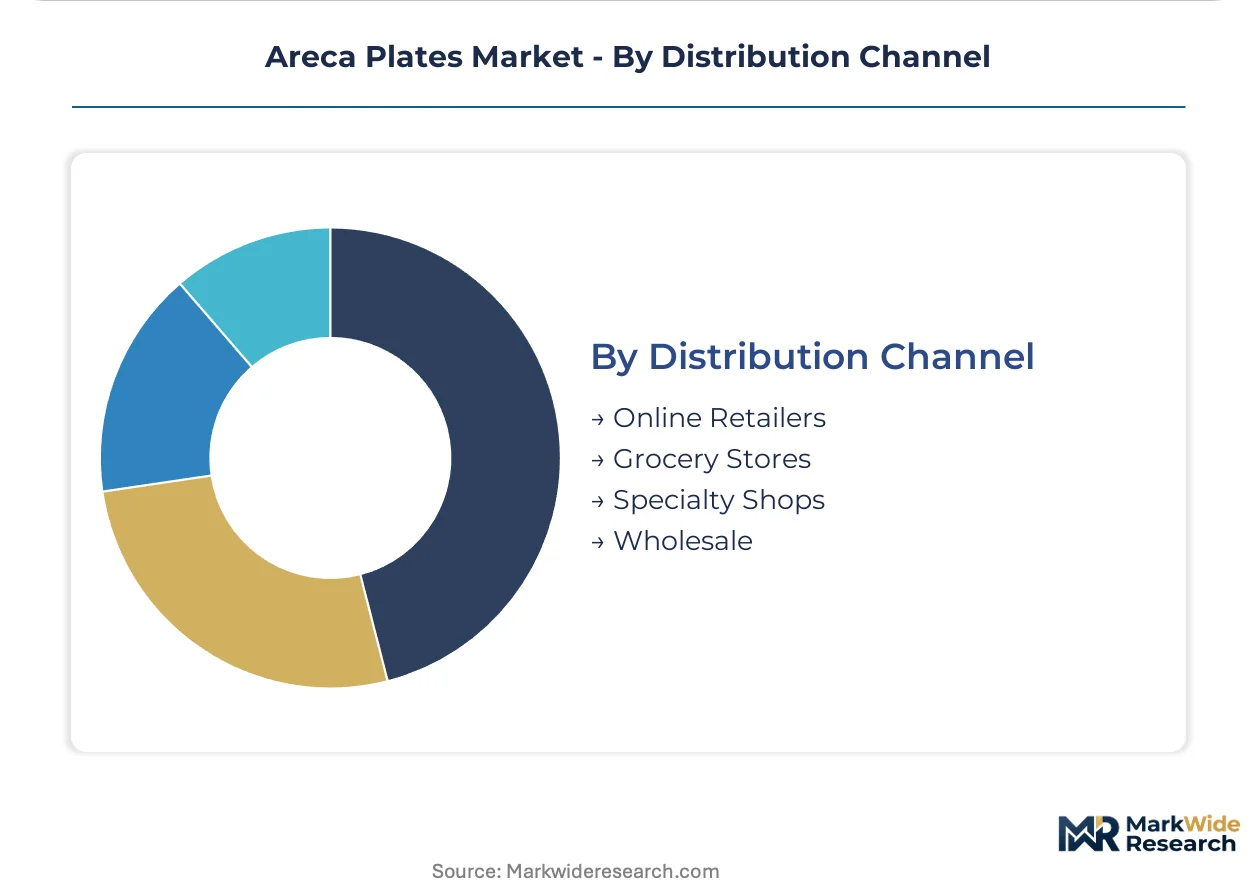
Distribution Channel:
Margin capture and working capital intensity diverge sharply between direct institutional sales and layered retail distribution.
- Online Retailers:Amazon, Flipkart, and niche sustainability platforms enable direct-to-consumer reach with 40-50% gross margins. Return logistics and damage rates compress net economics.
- Grocery Stores:Whole Foods Market, DM Drogerie Markt, and Waitrose position areca plates in disposable tableware aisles alongside paper and plastic alternatives. Slotting fees and promotional funding strain smaller suppliers.
- Specialty Shops:Zero-waste retailers and eco-focused gift shops in Copenhagen, Amsterdam, and Portland stock premium coated variants with educational packaging. Staff training requirements slow scaling.
- Wholesale:Hospitality supply distributors like Bunzl and Sysco route institutional volumes through established foodservice channels. BRCGS and ISO 17088 documentation requirements filter supplier eligibility.
Wholesale moves the highest absolute volumes. Online retailers are climbing the fastest as direct-to-consumer sustainability purchasing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS certification mandates and the EU Single-Use Plastics Directive are redirecting institutional procurement toward compostable tableware. Supply networks concentrate where areca palm density supports integrated leaf collection. Regulatory divergence across export destinations is reshaping producer geographic strategies.
India
Kerala-Karnataka-Tamil Nadu belt producers leverage dense areca palm plantations to compress raw material logistics costs. FSSAI food contact approvals and BIS standards for disposable tableware govern domestic market access. Coimbatore and Mysuru manufacturing clusters supply German and Dutch foodservice distributors seeking ISO 17088-verified output.
Germany
Institutional catering operators accelerate procurement of compostable serveware to comply with national implementation of EU Single-Use Plastics Directive bans. ECHA REACH compliance governs coating chemistries and pressing lubricants for imported areca products. Hamburg and Berlin foodservice distributors consolidate vendor bases around dual-certified producers.
United States
Education and healthcare sector catering contracts absorb rising compartment plate volumes as portion-controlled meal delivery expands. FDA food contact substance notifications shape product specifications for Indian and Southeast Asian exporters. California and New York institutional buyers prioritize stackability and logistics efficiency in procurement criteria.
Netherlands
Government procurement frameworks embed compostability verification as mandatory evaluation criterion for institutional foodservice. Extended producer responsibility fee structures advantage tableware with verified end-of-life pathways. Amsterdam and Rotterdam distributors filter supplier eligibility through BRCGS and ISO 17088 documentation requirements.
France
Full-service and quick-service operators specify BRCGS-accredited production lines for dine-in and takeaway applications. ANSM and ECHA govern material disclosure documentation for imported pressedware. Paris and Lyon institutional buyers require full coating chemistry transparency, compressing supplier qualification timelines.
Areca Plates Market Competitive Environment
Player mix skews toward regional fabricators with captive leaf collection networks and export-oriented specialists holding dual certification. Market structure fragments across three tiers: integrated South Indian producers with upstream collection control, European distributors with accreditation gatekeeping positions, and coating technology specialists differentiating on humidity tolerance. Consolidation pressure concentrates around certification infrastructure investments and automated pressing system deployment.
Among South India-integrated producers, GreenHaven Bioproducts and Kiran Global Exports exemplify the archetype of manufacturers leveraging geographic concentration of areca palm resources. EcoLeaf Solutions occupies a position within the technology-differentiated tier, representing producers investing in proprietary barrier formulations. These three entities anchor the competitive landscape across distinct strategic vectors: upstream supply control, export market accreditation, and product performance engineering.
| Leading Market Players |
|---|
| GreenHaven Bioproducts |
| Kiran Global Exports |
| EcoLeaf Solutions |
| Vegware Ltd. |
| Nature Packwell Pvt Ltd |
| NatureServe Innovations |
| LeafLogic Systems |
| BioPak |
| Verdant Table Co. |
| Others |
Value Chain & Pricing Dynamics
Bamboo fiber substitution for pure areca sheaths is compressing raw material sourcing geography toward Kerala-Karnataka-Tamil Nadu belt producers while fragmenting pricing power across certification tiers. This input shift simultaneously elevates coating technology premiums and erodes hand-pressed economy margins.
Pricing Analysis
Certification level creates the primary spread across the Areca Plates Market, with ISO 17088-BRCGS dual-certified products commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects coating technology, humidity tolerance, and export-grade finish quality. Pricing pressure stems from monsoon-driven leaf supply volatility that spikes input costs during Q3-Q4 collection disruptions. Institutional foodservice buyers in Germany and the Netherlands exhibit lowest price sensitivity due to regulatory compliance mandates, while Indian event catering segments drive aggressive economy-tier negotiation.
Supply Chain Analysis
Just-in-time leaf collection dominates South Indian production clusters, with monsoon-season strategic stockpiling reserved for premium export contracts. Geographic concentration centers on India, Indonesia, and Sri Lanka, with Karnataka and Tamil Nadu plantations supplying dominant feedstock volumes. Raw material dependencies encompass fallen areca sheaths, plant-based coating polymers, and pressing lubricants governed by REACH compliance. Single-source vulnerability concentrates around monsoon-disrupted collection cycles that interrupt Q3-Q4 supply continuity. Distribution runs through hospitality supply distributors like Bunzl and Sysco for institutional channels, with Amazon and specialty grocers absorbing direct-to-consumer volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around European foodservice distributors consolidating vendor bases around dual-certified producers, fragmenting access for uncertified competitors.
For Market Incumbents: Shield margin position by deepening captive leaf collection networks across Kerala-Karnataka-Tamil Nadu belt to compress raw material cost exposure against monsoon volatility. Accelerate automated pressing system deployment to displace hand-pressed imports in price-sensitive institutional channels. Certification infrastructure investment functions as the priority defensive lever against BRCGS-accreditation thresholds that exclude non-compliant suppliers from German and Dutch premium contract tiers. For New Entrants and Emerging Players: Differentiate on proprietary moisture-resistant coating chemistry to unlock tropical climate export viability previously inaccessible to uncoated competitors. Target North American education and healthcare catering segments where compartment plate penetration remains underexploited and portion-control specifications favor new supplier qualification. Direct-to-hotel distribution bypassing traditional hospitality supply intermediaries captures margin previously allocated to wholesale distributors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed South Indian integrated producers holding captive collection networks and dual certification credentials. Five-to-ten year viability hinges on extended producer responsibility scheme evolution across EU member states. Acquisition target archetype encompasses coating technology specialists with REACH-compliant additive formulations. The signal to watch is ECHA restricted substance list expansion that would obsolete incumbent coating chemistries and trigger replacement cycle demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leaf Collection Networks | Captive supply from Kerala-Karnataka-Tamil Nadu belt compresses logistics spend and insulates against monsoon volatility. |
| ISO 17088-BRCGS Dual Certification Investment | Compliance infrastructure unlocks German and Dutch institutional foodservice procurement frameworks. |
| Proprietary Coating Technology Development | REACH-compliant barrier formulations extend shelf stability in humid climates and satisfy ECHA material disclosure requirements. |
| Direct-to-Hotel Distribution Channel Launch | Bypassing Bunzl and Sysco intermediaries captures margin previously allocated to wholesale distributors. |
| Compartment Plate Manufacturing Scale-Up | Multi-cavity die configurations address North American education and healthcare catering contract specifications. |
Study Parameters
Desk research of EU regulatory filings, BIS standards documentation, and FSSAI food contact approvals preceded structured interviews with plant managers at Coimbatore and Mysuru manufacturing clusters, procurement leads at German foodservice distributors, and regulatory affairs specialists navigating REACH compliance. Secondary validation drew from customs trade data, SEC filings of listed packaging companies, and hospitality supply distributor annual reports. Bottom-up volume modeling triangulated against top-down market sizing across product geometry and end-use segments.
Variance decomposition across product type, raw material sourcing strategy, end-user category, and distribution channel shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory implementation timelines. Industry-specific forecast inputs encompassed monsoon pattern correlation with leaf supply volatility and EU Single-Use Plastics Directive enforcement acceleration curves.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation, India's BIS disposable tableware standards, and US FDA food contact substance notification frameworks; material policy shifts would require re-modeling. Specific risk factors include ECHA restricted substance list expansion, extended producer responsibility fee structure recalibration, and monsoon pattern disruption from climate variability. Revision becomes warranted when certification timeline compression or raw material cost spikes cross thresholds that alter producer competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
GCC Green Packaging Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
North America Eco-Friendly Packaging Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Compostable Tableware Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
Europe Eco-Friendly Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Bagasse Tableware Products Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
United States Green Packaging Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market