
 Flexographic Printing Market | 2026-2036
Flexographic Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Flexographic Printing Market Analysis
Flexible packaging converters are redrawing procurement priorities in flexographic printing, shifting volume toward recyclable mono-material films and extended-color-gamut workflows. Bobst Group SA leverages its press-to-finishing integration to anchor premium flexible packaging lines across European converter floors. Koenig & Bauer AG competes through high-speed corrugated board specialization, while Asahi Kasei Corporation differentiates via water-washable plate technology that reduces solvent handling costs.
Flexographic printing employs a rotary relief plate process where a flexible photopolymer or elastomer image carrier transfers fast-drying inks onto continuous web substrates at speeds exceeding 500 meters per minute, serving high-volume packaging decoration with run lengths from thousands to millions of units. Flexible packaging dominates value generation due to SKU proliferation and shelf-life extension demands from food brands, while UV-cured ink systems represent the fastest-expanding technology segment as converters target instant-drying, low-migration compliance for sensitive food contact. Labels remain structurally mature with stable margin pools concentrated in pharmaceutical and logistics authentication applications.
The European Chemicals Agency enforces REACH restrictions on photoinitiator migration, while the FDA maintains 21 CFR 175.105 adhesive and coating compliance thresholds for food-contact printed materials in the United States. These frameworks compel ink formulators and plate manufacturers to validate substance safety across multi-jurisdictional supply chains. Stakeholders must monitor regulatory divergence between EU migration limits and FDA threshold approaches when configuring global product platforms.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing converters to reformulate ink chemistries and plate systems toward solvent-free, low-migration architectures, compressing supplier lead times and reshaping procurement qualification criteria across European flexible packaging floors.
Growth Catalysts
- REACH photoinitiator restrictions:ECHA enforcement on migration limits accelerates UV-LED curing adoption, pushing converters toward compliant ink platforms that eliminate solvent handling and reduce VOC emissions.
- Mono-material film demand:Food and beverage brands in Germany and France specify recyclable polyethylene structures, requiring plate and anilox configurations optimized for single-substrate printability.
- Extended color gamut workflows:Seven-color fixed palette printing reduces make-ready waste and inventory complexity for converters serving SKU-proliferating snack and confectionery markets.
Market Restraints
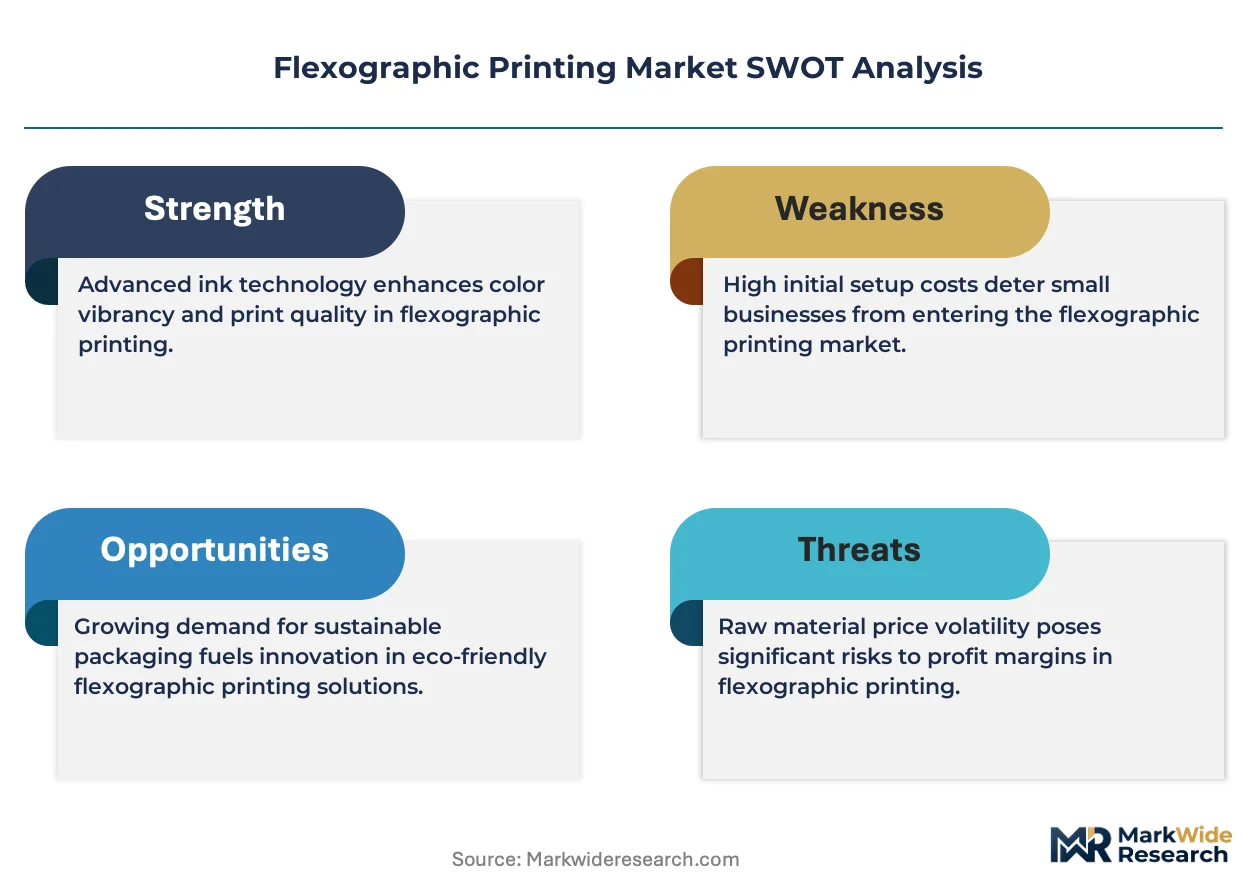
- Photopolymer plate cost volatility:Raw material concentration among Asian elastomer suppliers exposes European converters to freight and tariff fluctuations on image carrier inputs.
- Corrugated substitution pressure:E-commerce fulfillment demand for rigid secondary packaging diverts capital from flexible film lines toward board-based formats in certain logistics applications.
- REACH compliance timeline friction:Substance authorization delays for novel photoinitiators extend new product development cycles beyond typical converter equipment refresh schedules.
Strategic Opportunities
- Water-washable plate penetration:Solvent elimination appeals to converters in Netherlands and Belgium facing local environmental permitting constraints on VOC emissions.
- Pharmaceutical serialization integration:Track-and-trace mandates create demand for flexo-printed tamper-evident labels with embedded authentication features.
- Digital-flexo hybrid workflows:Convergence of inkjet personalization stations with rotary flexo bases enables short-run versioning for craft beverage and specialty food launches.
Industry Challenges
- Prepress operator scarcity:Specialized skills in color management and plate mounting face generational attrition as vocational training programs shrink across German industrial regions.
- Legacy press integration complexity:Retrofitting analog winders with Industry 4.0 sensor arrays demands capital coordination between converter maintenance schedules and OEM upgrade windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexographic Printing Market |
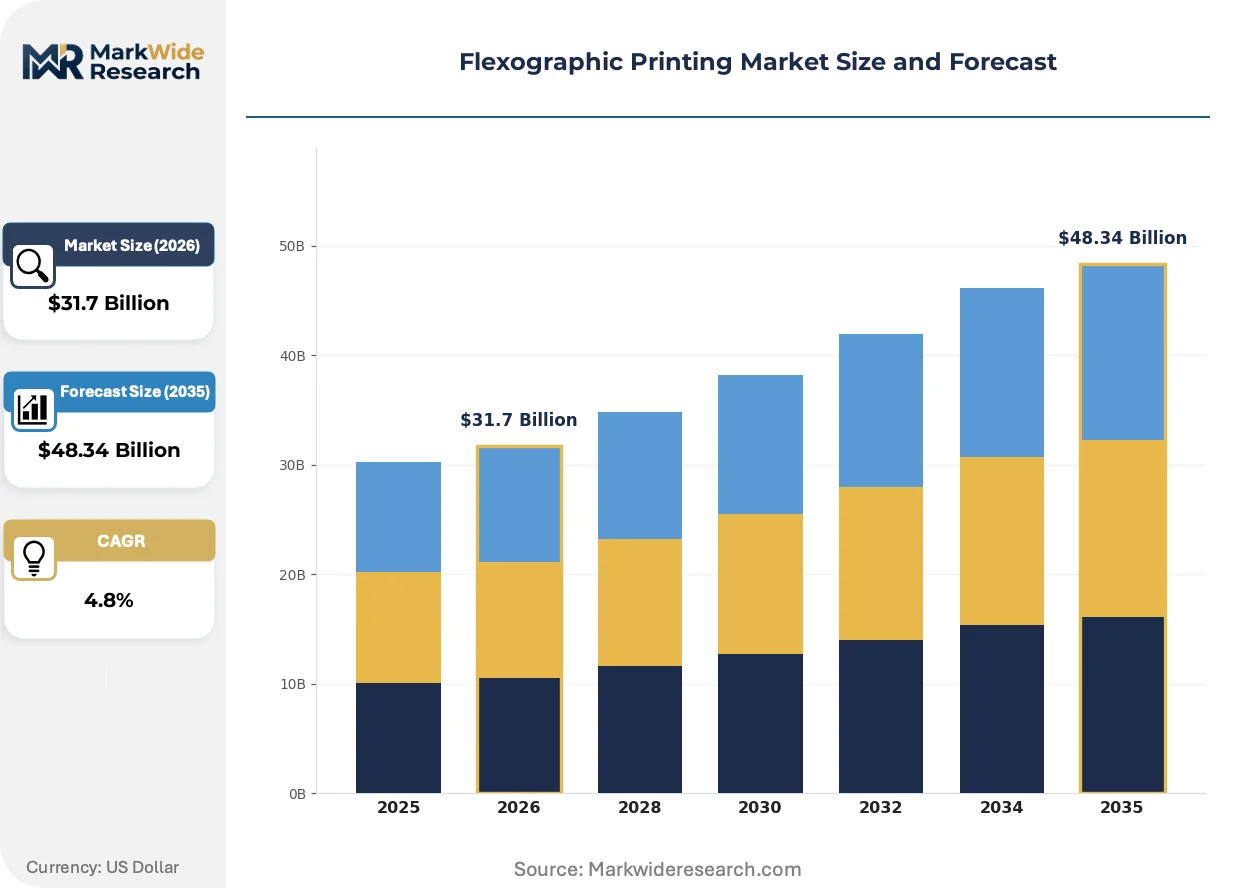
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $48.34 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Labels, Corrugated Containers, Paperboard Material: Plastic, Paper, Textile, Metal Foil End User: Food & Beverages, Personal Care, Healthcare, Industrial Products Technology: Water-based Ink, Solvent-based Ink, UV Ink, Glow-in-the-dark Ink |
| Companies Covered | Bobst Group SA, Mark Andy Inc., Comexi Group, Amcor PLC, Westrock Company, Koenig & Bauer AG, Windmöller & Hölscher KG, Uteco Group, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexographic Printing Market Emerging Trajectories
Digital front-end systems and automated plate mounting are compressing make-ready intervals, while regulatory chemistry reforms and buyer consolidation are redrawing competitive advantage around compliance velocity rather than unit cost alone.
Electron beam (EB) curing is supplanting conventional thermal drying in high-throughput flexible packaging lines serving dairy and ready-meal segments. German and Dutch converters operating 24-hour production schedules adopt EB for instant polymerization that eliminates solvent retention risk. This technology is supplanting heat-set configurations in applications where migration thresholds fall below 10 parts per billion.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluoroolefin adoption in climate control systems that stabilize pressroom humidity. Compressed air drying and anilox conditioning now face refrigerant retrofit requirements that affect total cost of ownership calculations for new press installations. Southern European converters in Spain and Italy encounter accelerated replacement timelines due to higher ambient temperature exposure.
Brand-direct specification of certified sustainable packaging is compressing traditional distributor channels in flexible packaging procurement. Major food manufacturers in France and Germany now mandate chain-of-custody documentation that bypasses non-audited intermediaries. This concentration is visible most acutely in private-label retail where sustainability scorecards determine converter qualification status independent of historical relationship tenure.
Flexographic Printing Market Segmentation
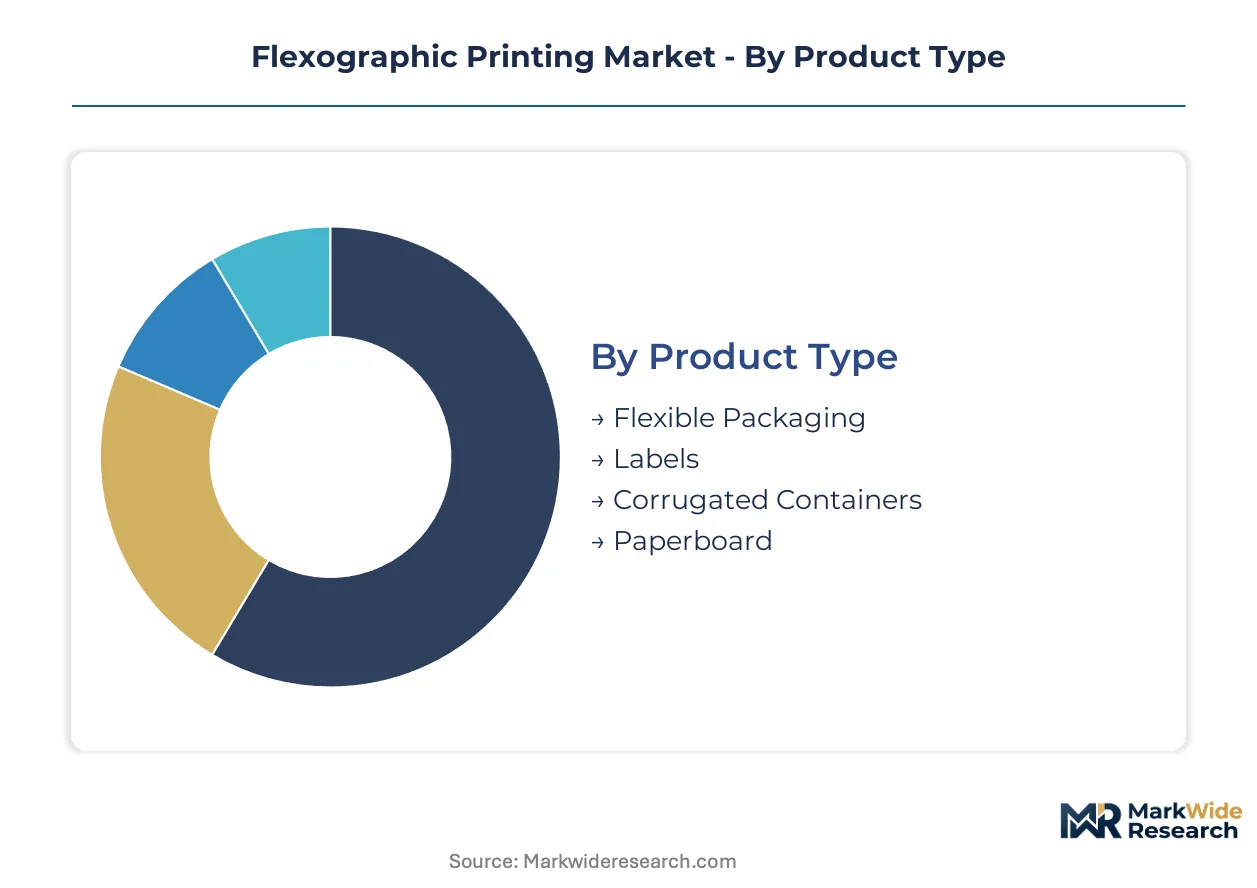
Segmentation in flexographic printing reveals how substrate specifications, ink chemistry constraints, and end-use compliance requirements fragment procurement patterns across converter operations. Each dimension carries distinct margin profiles and capital intensity thresholds that reshape competitive positioning.
Product Type:
Channel flow diverges sharply: flexible packaging moves through brand-direct specifications with sustainability auditing, while corrugated and labels retain distributor intermediaries with shorter qualification cycles.
- Flexible Packaging:Multi-layer film structures for snack, confectionery, and ready-meal applications dominate value generation. German and French food brands specify recyclable mono-material polyethylene constructions, compressing plate and anilox configuration lead times.
- Labels:Pressure-sensitive and shrink-sleeve formats serve pharmaceutical serialization and logistics authentication with stable margin pools. Demand concentrates in track-and-trace mandates requiring tamper-evident flexo-printed features.
- Corrugated Containers:E-commerce secondary packaging formats divert converter capital from film lines.
- Paperboard:Folding carton applications for dry goods and cosmetics sustain mid-tier volume throughput.
Flexible packaging dominates installed base. UV-cured and EB-enabled flexible lines are where expansion concentrates.
Material:
Cost tier stratification separates premium substrate portfolios from commodity grades, with plastic films commanding anilox customization premiums versus standardized paper treatments.
- Plastic:Polyethylene and polypropylene films require specialized plate shore hardness and ink adhesion chemistry for mono-material recyclability. Netherlands and Belgium converters face VOC permitting constraints that favor water-washable plate systems on plastic substrates.
- Paper:Uncoated and coated kraft grades sustain corrugated and paperboard volume with lower anilox specification complexity.
- Textile:Non-woven and woven substrates for industrial sacks and retail bags occupy niche throughput tiers.
- Metal Foil:Laminated aluminum structures for barrier-sensitive dairy and pharmaceutical applications demand ultra-low migration ink systems.
Plastic films anchor revenue concentration. Paper substrates sustain margin stability in mature geographic markets.
End User:
Customer type fragmentation splits procurement between multinational brand direct specifications and regional converter spot purchasing with diverging compliance documentation requirements.
- Food & Beverages:Shelf-life extension and SKU proliferation drive seven-color fixed palette adoption for snack and confectionery versioning. ECHA REACH photoinitiator restrictions compel UV-LED curing migration compliance below 10 parts per billion.
- Personal Care:Cosmetic and hygiene brands specify extended color gamut workflows with reduced make-ready waste for seasonal packaging refreshes.
- Healthcare:Pharmaceutical serialization mandates create demand for flexo-printed authentication features with embedded track-and-trace elements.
- Industrial Products:Chemical and agricultural sack applications sustain solvent-based ink throughput in non-food contact segments.
Food and beverage applications dominate installed capacity. Healthcare authentication requirements are where technology upgrading concentrates.
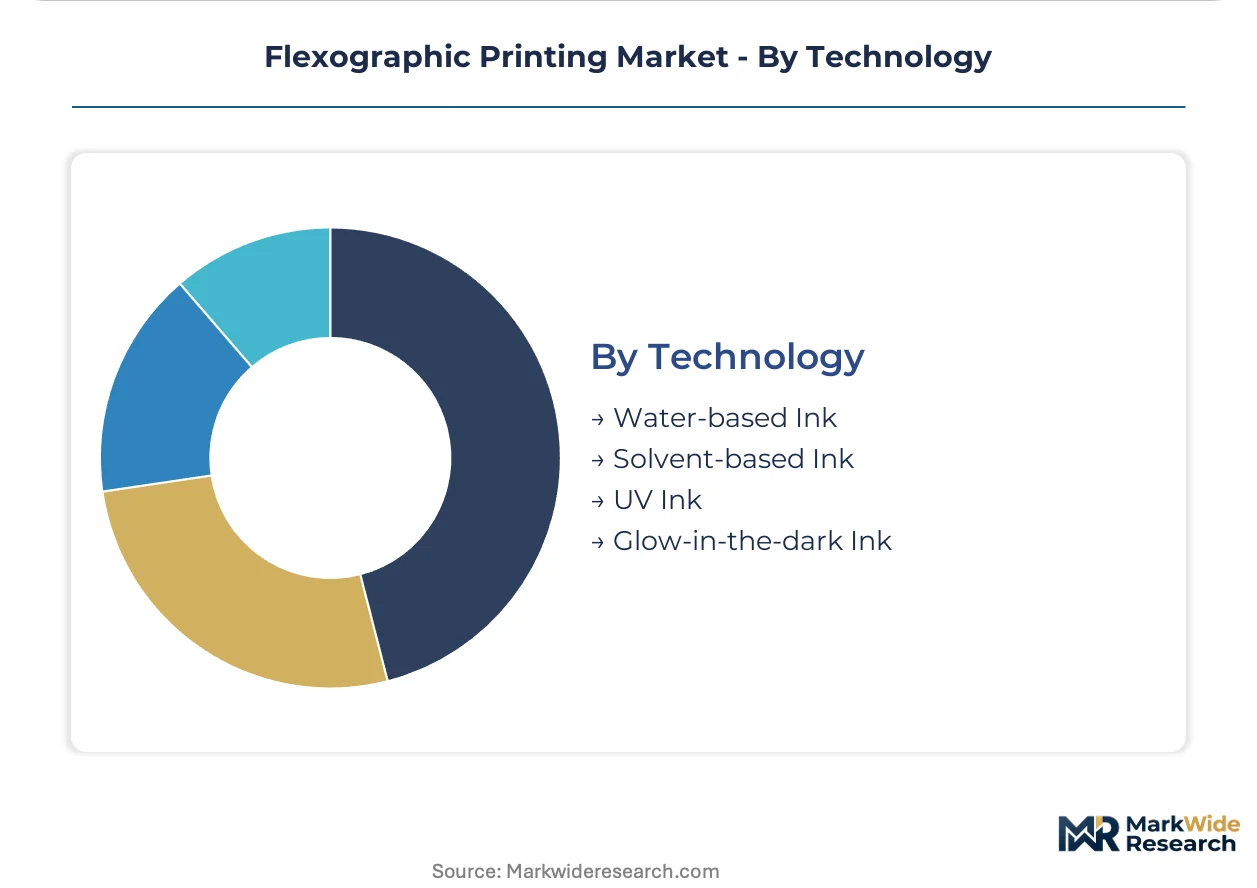
Technology:
Application maturity separates instant-cure architectures from legacy thermal drying, with regulatory chemistry reforms accelerating capital reallocation toward low-migration platforms.
- UV Ink:Mercury and LED-cured systems eliminate solvent retention risk with instant polymerization for dairy and ready-meal flexible packaging. EU F-Gas Regulation phase-down schedules accelerate refrigerant retrofits in pressroom climate control for UV stabilization.
- Water-based Ink:Reduced VOC emission profiles align with Netherlands and Belgium environmental permitting constraints on converter operations.
- Solvent-based Ink:Nitrocellulose and polyurethane systems retain cost advantage in industrial non-food segments with less stringent migration thresholds.
- Glow-in-the-dark Ink:Phosphorescent photoinitiator formulations serve safety and promotional applications with specialized curing requirements.
Water-based systems dominate legacy installed base. UV-LED and electron beam curing are where compliance-driven replacement concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment and chemistry suppliers cluster in German industrial corridors, where converter consolidation and packaging machinery heritage concentrate procurement influence. ECHA REACH enforcement and EU Packaging and Packaging Waste Regulation mandates ripple outward from this core, reshaping qualification standards across continental supply chains.
Germany
Food and beverage brands specify recyclable mono-material polyethylene structures, compressing plate configuration lead times. ECHA REACH photoinitiator restrictions drive UV-LED curing adoption among converters serving sensitive food contact applications. The Düsseldorf-Cologne corridor hosts packaging machinery clusters where Bobst Group SA and Koenig & Bauer AG anchor converter procurement relationships.
France
Private-label retail sustainability scorecards determine converter qualification status independent of historical tenure. ANSM enforces migration thresholds below 10 parts per billion for dairy and ready-meal flexible packaging. The Lyon-Grenoble axis concentrates converter operations reformulating toward solvent-free ink architectures.
United States
FDA 21 CFR 175.105 compliance thresholds govern food-contact adhesive and coating specifications for exported flexible packaging. E-commerce fulfillment demand diverts converter capital toward corrugated secondary packaging formats. The Midwest industrial belt sustains legacy press installations facing Industry 4.0 retrofit coordination challenges.
Netherlands
Local environmental permitting constraints on VOC emissions favor water-washable plate system adoption. The Randstad logistics hub enables just-in-time ink and anilox supply to Benelux converter floors. Rotterdam-area converters lead EB curing penetration for instant polymerization eliminating solvent retention risk.
China
Domestic flexible packaging volume serves snack and confectionery markets with SKU proliferation driving seven-color fixed palette adoption. NMPA and GB standards govern food-contact material safety with increasing alignment toward EU migration limit methodologies. The Yangtze River Delta concentrates photopolymer plate raw material suppliers exposing European converters to freight fluctuation exposure.
Flexographic Printing Market Vendor Landscape
Concentration sits with diversified packaging machinery conglomerates and specialized plate chemistry suppliers. Tier-one players command converter procurement through press-to-finishing integration, while mid-tier specialists compete on regional service density and environmental compliance velocity. Two strategic archetypes dominate: integrated machinery-to-finishing systems providers, and water-washable plate technology specialists. Competitive moves center on strategic partnerships for digital-flexo hybrid workflows and capacity expansion for EB curing installations.
Within the integrated systems tier, Bobst Group SA and Koenig & Bauer AG exemplify machinery-to-finishing consolidation strategies. Asahi Kasei Corporation occupies a position representing water-washable plate chemistry specialization. These three anchors span Swiss, German, and Japanese industrial bases, reflecting geographic diversification in core technology sourcing.
| Leading Market Players |
|---|
| Bobst Group SA |
| Mark Andy Inc. |
| Comexi Group |
| Amcor PLC |
| Westrock Company |
| Koenig & Bauer AG |
| Windmöller & Hölscher KG |
| Uteco Group |
| Asahi Kasei Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German flexible packaging converters and photopolymer plate suppliers lock in multi-year price visibility while securing priority allocation during raw material tightness. These arrangements transfer freight volatility risk to buyers yet insulate against spot market spikes in elastomer feedstocks.
Pricing Analysis
EU REACH photoinitiator restrictions dictate the pricing tier structure across ink chemistry portfolios. Three-tier pricing structure across premium, standard, and economy levels separates UV-LED compliant formulations from legacy solvent-based systems and commodity industrial grades. Cost compression in standard-tier water-based inks is intensifying because of anilox specification standardization. Small-batch craft beverage converters exhibit highest price sensitivity, while multinational food brands prioritize migration compliance over unit cost.
Supply Chain Analysis
China and Japan anchor photopolymer plate raw material production, with the Yangtze River Delta concentrating elastomer resin manufacturing. European converter operations draw from Asian monomer feedstocks, specialized anilox engraving equipment from German industrial corridors, and UV-LED curing hardware from Dutch engineering clusters. Single-source vulnerability concentrates in photoinitiator intermediates subject to ECHA authorization delays. Distribution runs through converter-direct channels for certified sustainable packaging, bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexographic printing is approaching a platform-economics inflection where digital front-end systems and automated plate mounting create interoperability standards that reshape competitive advantage around workflow integration rather than equipment scale alone.
For Market Incumbents: Fortify converter relationships through backward integration into water-washable plate chemistry, neutralizing Asahi Kasei's specialization advantage. Anchor premium positioning by embedding EB curing modules within press-to-finishing lines, creating switching costs against corrugated substitution pressure from e-commerce fulfillment demand. For New Entrants and Emerging Players: Lead with pharmaceutical serialization integration for track-and-trace mandates, the most penetrable segment given incumbent complacency in authentication-feature development. Target Benelux converter floors facing VOC permitting constraints with water-washable plate service density. Pursue digital-flexo hybrid workflow partnerships with craft beverage brands requiring short-run versioning. For Investors and Strategic Acquirers: Capital is best deployed toward water-washable plate technology specialists with established Netherlands and Belgium converter relationships, given regulatory tailwinds from EU F-Gas phase-down schedules and REACH enforcement. Long-term viability rests on compliance velocity rather than unit cost optimization. Monitor EB curing adoption rates in German dairy and ready-meal segments as inflection signal for platform shift toward instant polymerization architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plate Chemistry | Captures margin pool from Asian elastomer suppliers while securing REACH-compliant formulation control. |
| EB Curing Capacity Expansion | Addresses ANSM migration thresholds below 10 parts per billion for French dairy flexible packaging. |
| Digital-Flexo Hybrid Partnership | Enables versioning workflows for SKU-proliferating snack brands without dedicated inkjet lines. |
| Water-Washable Plate Service Density | Aligns with Netherlands environmental permitting constraints on VOC emissions from solvent-based systems. |
| Pharmaceutical Serialization Integration | Captures track-and-trace mandate demand with embedded authentication features for tamper-evident labels. |
Methodological Framework
Operator-level perspectives from converter plant managers, prepress technical directors, ink formulation chemists, and packaging procurement leads at food and beverage brands anchored the qualitative base. These primary insights combined with secondary validation from ECHA substance authorization databases, EU Packaging and Packaging Waste Regulation impact assessments, FDA 21 CFR 175.105 compliance documentation, and SEC filings from listed packaging machinery manufacturers. Bottom-up equipment installation tracking and top-down market sizing triangulated volume estimates.
Sensitivity analysis tested forecast outputs against regulatory timeline acceleration, raw material cost volatility, and technology substitution scenarios across the projection horizon. Segmentation dimensions modeled include substrate type, ink chemistry platform, curing technology, end-use compliance tier, and regional regulatory cluster. CAGRs derived from equipment refresh cycle analysis, brand specification trend extrapolation, and converter capacity expansion announcements. Industry-specific inputs incorporated REACH substance authorization pipeline status and EU F-Gas refrigerant phase-down schedules.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity, stable elastomer supply from Asian sources, or continued brand-direct sustainability specification would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology adoption elasticity. Recalibration cycles align with material shifts in photoinitiator authorization decisions and EB curing equipment order backlogs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Stack Flexo Printing Press Market
Packaging Printing
Printed Boxes Market
Packaging Printing
Label Printing Software Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
North America Print Label Market
Packaging Printing
Laser Coders Market
Packaging Printing
Global Printing for Packaging Market
Packaging Printing
Qatar Printing and Packaging Market
Packaging Printing
Global Electrophotographic Printing in Packaging Market
Packaging Printing
Asia-Pacific Digital Printing Packaging Market
Packaging Printing
Thermal Transfer Overprinter Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Heat Transfer Press Printing Machine Market
Packaging Printing
Rotogravure Printing Machine Market
Packaging Printing
Czech Republic Printing Label Market