
 Label Printers Market | 2026-2036
Label Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Label Printers Market Outlook
Equipment leasing and managed print services are fragmenting the competitive landscape by lowering capital barriers for mid-sized logistics providers. Zebra Technologies Corporation leverages its vertical integration into print engine manufacturing to sustain margin control across industrial deployments. Brother Industries, Ltd. anchors its position through compact desktop systems that dominate small-business channels in Japan and North America.
Label printers are electromechanical devices that apply ink, thermal coating, or laser-etched pigment onto adhesive substrates at speeds typically ranging from two to twelve inches per second, producing machine-readable identifiers for supply chain tracking and consumer product marking. Desktop printers lead in unit volume across retail endpoints, while industrial thermal transfer systems capture the dominant share of margin pools in high-duty manufacturing environments. Mobile printer adoption is accelerating among field service technicians in healthcare and last-mile logistics, where portable barcode generation reduces data entry errors.
The EPA regulates volatile organic compound emissions from inkjet formulations used in domestic production facilities, while the FCC governs wireless connectivity modules integrated into mobile and industrial printer models. RoHS restrictions on hazardous substances in electronic components directly shape material selection for circuit boards and power supplies across OEM supply chains. Stakeholders must monitor evolving e-waste directives and wireless spectrum reallocation as these forces determine which product architectures retain market access.
Market Dynamics
E-commerce logistics operators are expanding automated labeling infrastructure while the EU F-Gas Regulation and RoHS directives tighten material compliance requirements for electronic printing equipment.
Growth Catalysts
- E-commerce fulfillment automation:Third-party logistics providers in Germany and the United States are deploying high-speed thermal transfer systems to meet same-day delivery commitments. Automated print-and-apply stations reduce labor touchpoints in parcel sortation hubs.
- REACH substance restrictions:European chemical compliance mandates are accelerating substitution of solvent-based inkjet formulations with water-based and UV-curable alternatives. Reformulation investments are opening premium positioning for compliant equipment vendors.
- Mobile field workforce digitization:Healthcare systems and last-mile delivery fleets are issuing portable Bluetooth-enabled printers to eliminate manual data entry. Battery chemistry improvements extend operational uptime for field technicians.
Market Restraints
- Thermal paper cost volatility:Bisphenol-A coating alternatives face supply tightness as Japanese and Chinese specialty chemical producers adjust capacity. Raw material pass-through clauses in equipment contracts limit margin protection.
- Printhead supplier concentration:Precision thermal printhead manufacturing concentrates among Japanese and South Korean component specialists. Single-source dependencies create vulnerability for industrial printer assemblers during demand surges.
- Wireless module certification friction:FCC and CE marking requirements for integrated radio frequency modules extend product launch timelines. Regional spectrum allocation differences force hardware variants that fragment production scale.
Strategic Opportunities
- India manufacturing localization:PLI scheme incentives for electronics assembly are attracting label printer OEMs to establish final assembly near pharmaceutical and textile export clusters in Gujarat and Tamil Nadu.
- Food traceability mandates:FDA Food Safety Modernization Act rules on lot-level tracking are expanding demand for washdown-rated thermal transfer systems in protein processing facilities.
- Cloud-managed print services:Subscription-based device monitoring and consumables replenishment are displacing transactional hardware sales in mid-market distribution centers.
Industry Challenges
- Embedded systems cybersecurity:Network-connected industrial printers require hardening against ransomware attacks targeting manufacturing execution system integrations.
- Legacy warehouse management system integration:Proprietary communication protocols in decade-old ERP installations force custom middleware development for automated labeling deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Label Printers Market |
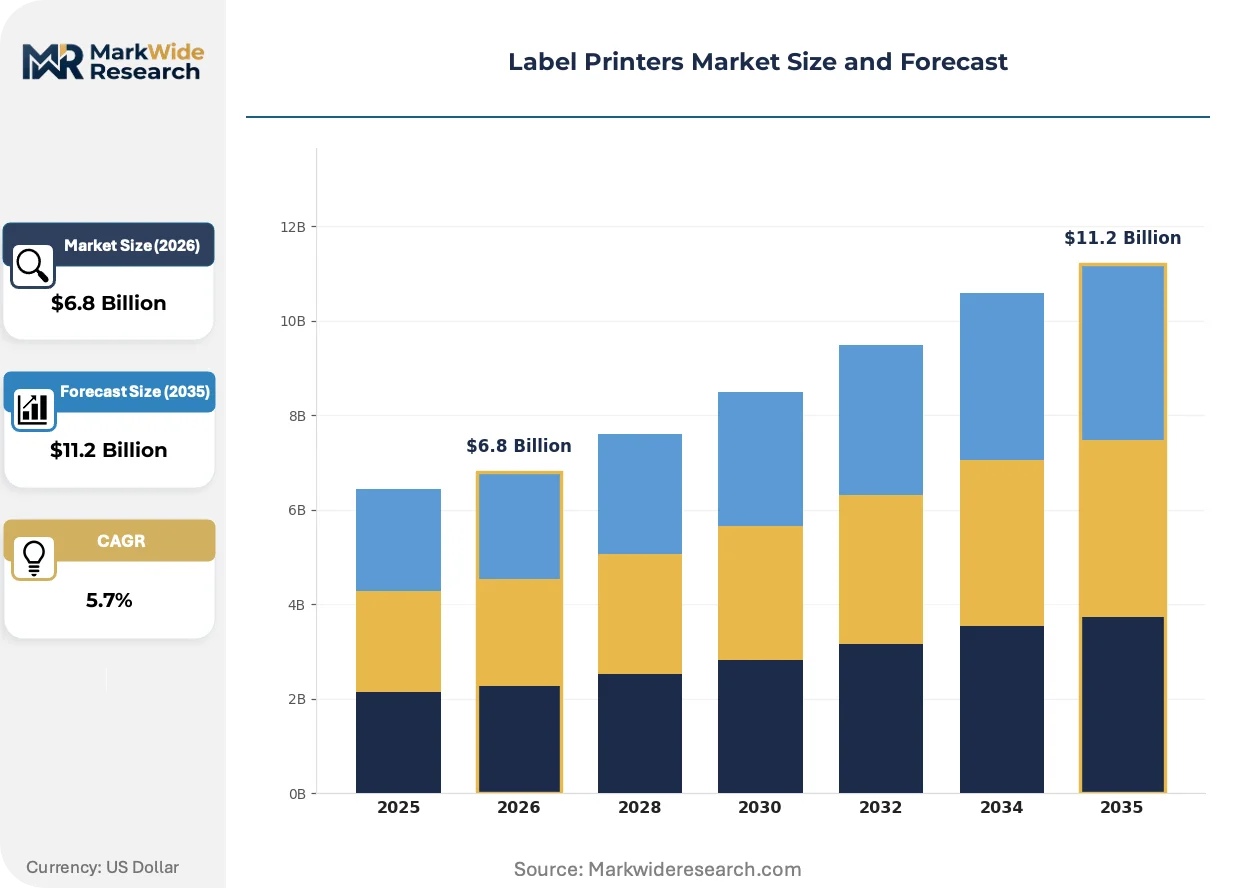
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Printers, Industrial Printers, Mobile Printers, Thermal Printers Technology: Direct Thermal, Thermal Transfer, Inkjet, Laser End User: Logistics, Retail, Healthcare, Manufacturing Application: Barcode Labeling, Shipping Labels, Inventory Labels, Product Labels |
| Companies Covered | Zebra Technologies Corporation, Honeywell International Inc., Brother Industries, Ltd., Seiko Epson Corporation, Sato Holdings Corporation, TSC Auto ID Technology Co., Ltd., Brady Corporation, HP Inc., Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Label Printers Market Strategic Shifts
Direct-to-package inkjet coding systems are compressing the addressable market for pre-printed label stock while sustainability mandates reshape substrate and ink chemistry specifications.
UV-LED curable inkjet printheads are rendering obsolete thermal transfer ribbons in high-resolution secondary packaging applications. Pharmaceutical manufacturers in Switzerland and Germany are adopting these systems to eliminate ribbon waste and enable variable-data serialization at line speeds exceeding 150 meters per minute. The technology is rendering obsolete the economics of ribbon-based coding for medium-volume production runs.
The EU F-Gas Regulation phase-down of hydrofluorocarbon propellants in aerosol-dispensed cleaning agents is forcing reformulation of printhead maintenance supplies. Industrial printer operators must now source fluorine-free cleaning solvents that meet REACH substance restrictions without degrading ceramic nozzle plate integrity. German chemical distributors are consolidating qualified supply channels to serve OEM-approved maintenance protocols.
Outcome-based service contracts are displacing break-fix maintenance arrangements in enterprise fleet deployments. Third-party logistics operators in the United States are negotiating per-label pricing models that bundle hardware, consumables, and remote monitoring into single-line-item procurement. This shift concentrates vendor selection authority among procurement functions rather than engineering departments.
Label Printers Market Segmentation
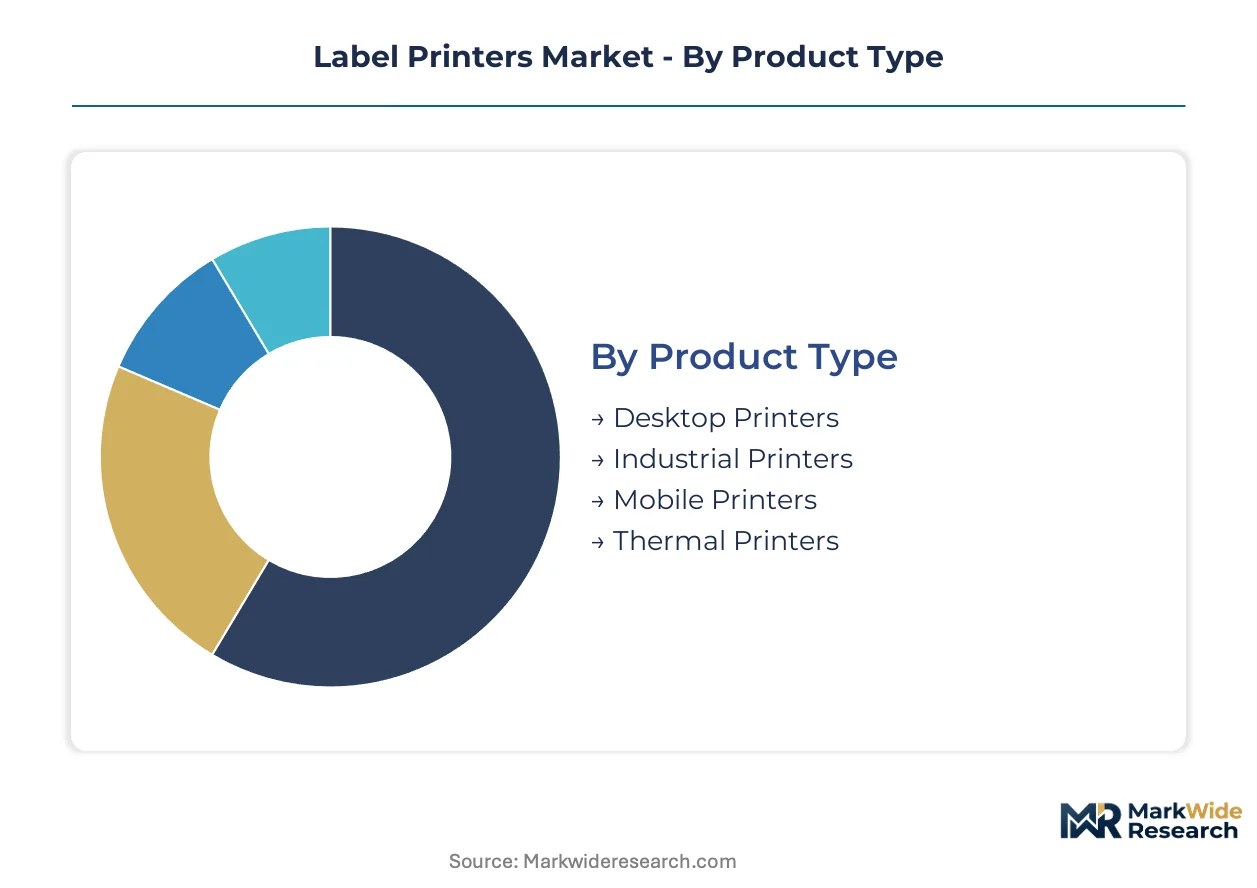
Label printer segmentation determines service contract structures and consumables replenishment cadences across deployment environments. Equipment complexity and duty cycles create divergent margin profiles that shape vendor portfolio prioritization and channel investment decisions.
Product Type:
After-sales-service intensity varies dramatically across product categories, with industrial systems demanding field engineering support while desktop units rely on depot repair and remote diagnostics.
- Industrial Printers:Heavy-duty thermal transfer and direct thermal systems engineered for continuous 24/7 operation in warehouse and production line environments. Demand concentrates among third-party logistics operators in Germany and the United States deploying automated print-and-apply stations for same-day fulfillment networks. These systems generate recurring revenue through high-volume ribbon and label stock consumption.
- Desktop Printers:Compact units designed for intermittent use in office and retail backroom settings, typically handling 1,000-5,000 labels monthly. Small-business channels in Japan and North America drive volume, with Brother Industries anchoring distribution through office supply retailers. Lower acquisition costs mask higher per-label consumables pricing.
- Mobile Printers:Battery-powered Bluetooth and Wi-Fi enabled devices for field workforce deployment. Healthcare systems and last-mile delivery fleets issue these units to eliminate manual data entry errors.
- Thermal Printers:A technology-agnostic category spanning desktop and industrial form factors that use heat-sensitive media or ribbon-based imaging.
By volume, Desktop Printers leads. By growth pace, Mobile Printers is ahead.
Technology:
Technology selection drives total cost of ownership calculations and determines compliance eligibility for regulated labeling applications.
- Thermal Transfer:Ribbon-based imaging systems producing durable, chemical-resistant labels essential for asset tracking and cold-chain logistics. Pharmaceutical manufacturers in Switzerland and Germany specify these systems for FDA-compliant lot-level serialization. The technology commands premium positioning in high-duty manufacturing environments.
- Direct Thermal:Heat-activated imaging on chemically treated substrates, eliminating ribbon costs but limiting label longevity. E-commerce sortation hubs favor these systems for short-lifecycle shipping labels where six-month durability suffices.
- Inkjet:Piezoelectric or thermal inkjet printheads depositing UV-curable or water-based formulations. Secondary packaging lines are adopting these systems to eliminate ribbon waste and enable variable-data printing at speeds exceeding 150 meters per minute.
- Laser:Electrophotographic imaging using toner cartridges, dominant in office document printing but niche for adhesive label applications requiring precise registration.
Thermal Transfer captures the dominant margin pool. Inkjet is expanding most quickly in packaging serialization.
End User:
End-user verticals exhibit distinct procurement patterns, with logistics operators favoring fleet-wide service contracts while healthcare prioritizes regulatory compliance certification.
- Logistics:Parcel carriers and third-party fulfillment providers operating high-velocity sortation infrastructure. Automated labeling investments track e-commerce volume growth in distribution clusters near Chicago, Rotterdam, and Shanghai.
- Manufacturing:Discrete and process industries requiring work-in-process tracking, finished goods identification, and compliance labeling. REACH substance restrictions are accelerating substitution of solvent-based inkjet formulations with UV-curable alternatives.
- Healthcare:Hospitals, pharmacies, and clinical laboratories demanding patient safety labeling and specimen tracking. FDA Unique Device Identification mandates and bedside medication administration protocols drive specification requirements.
- Retail:Shelf-edge pricing, promotional tagging, and omnichannel fulfillment operations. Price markdown velocity and seasonal staffing fluctuations create demand for simple, reliable desktop systems.
Logistics generates the highest equipment throughput. Healthcare commands the steepest expansion trajectory due to digitization mandates.
Application:
Application requirements determine substrate specifications, print resolution minimums, and environmental durability ratings.
- Barcode Labeling:Machine-readable symbology printing for supply chain tracking, spanning Code 128, Data Matrix, and QR formats. GS1 standards compliance is non-negotiable for retail and pharmaceutical distribution.
- Shipping Labels:Carrier-compliant formats with integrated routing codes and delivery confirmation barcodes. Amazon, DHL, and FedEx specification updates force hardware refresh cycles every 3-5 years.
- Inventory Labels:Asset identification and location tracking tags for warehouse management system integration. Proprietary communication protocols in legacy ERP installations force custom middleware development.
- Product Labels:Consumer-facing branding, ingredients disclosure, and regulatory compliance markings. FDA Food Safety Modernization Act rules on lot-level tracking are expanding demand for washdown-rated systems in protein processing.
Shipping Labels dominates unit volume. Product Labels is gaining share fastest on traceability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives in India and REACH compliance mandates in Europe are redirecting manufacturing investments toward localized assembly clusters. Distribution hubs in Germany, China, and the United States dominate equipment procurement volumes as e-commerce fulfillment networks scale automated labeling infrastructure.
United States
Third-party logistics providers deploy high-speed thermal transfer systems to meet same-day delivery commitments from Chicago and Memphis distribution clusters. The EPA regulates volatile organic compound emissions from inkjet formulations used in domestic production facilities. Automated print-and-apply stations reduce labor touchpoints in parcel sortation hubs near Atlanta and Dallas.
Germany
Pharmaceutical manufacturers specify FDA-compliant lot-level serialization systems for cold-chain logistics operations. The EU F-Gas Regulation phase-down of hydrofluorocarbon propellants forces reformulation of printhead maintenance supplies. Industrial printer OEMs consolidate qualified supply channels through chemical distributors in Baden-Württemberg to serve maintenance protocols.
China
E-commerce operators expand automated labeling infrastructure to support cross-border fulfillment volumes from Yangtze River Delta warehouses. SAMR enforcement of GB standards shapes wireless connectivity module certification for integrated radio frequency hardware. Precision thermal printhead manufacturing concentrates among component specialists in Jiangsu and Guangdong provinces.
Japan
Specialty chemical producers adjust bisphenol-A coating alternative capacity amid thermal paper cost volatility concerns. METI oversight of battery chemistry standards influences portable Bluetooth-enabled printer designs for field workforce deployment. Compact desktop systems dominate small-business channels through office supply retailers in Tokyo and Osaka metro areas.
India
Electronics assembly incentives under the PLI scheme attract label printer OEMs to establish final assembly near pharmaceutical export clusters in Gujarat and Tamil Nadu. BIS certification requirements govern power supply and circuit board material selection for domestic market access. Cloud-managed print services displace transactional hardware sales in mid-market distribution centers near Mumbai and Chennai.
Label Printers Market Competitive Environment
On the supply side, the industry is consolidating around three distinct capability tiers. Equipment leasing and managed print services fragment the competitive landscape by lowering capital barriers for mid-sized logistics providers. The vendor base separates into vertically integrated industrial specialists, compact desktop manufacturers, and mobile field-technology providers. Dominant competitive moves include backward integration into print engine manufacturing and geographic expansion through localized assembly partnerships.
Among North American-headquartered industrial specialists, Zebra Technologies Corporation and Honeywell International Inc. occupy positions within the high-duty manufacturing tier. Brother Industries, Ltd. exemplifies the compact desktop archetype through its Japan-based Co., Ltd. structure. These three entities represent the primary competitive anchors across industrial, desktop, and mobile deployment environments.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Honeywell International Inc. |
| Brother Industries, Ltd. |
| Seiko Epson Corporation |
| Sato Holdings Corporation |
| TSC Auto ID Technology Co., Ltd. |
| Brady Corporation |
| HP Inc. |
| Canon Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese thermal printhead foundries is compressing component pricing and forcing Japanese suppliers into premium-positioning strategies. This utilization gap cascades through OEM assembly tiers, where margin protection depends on backward integration into print engine manufacturing and captive consumables revenue streams.
Pricing Analysis
Certification level creates the primary spread across equipment tiers, with FDA-compliant serialization systems commanding substantial premiums over standard industrial units. Three-tier pricing structure across premium, standard, and economy levels aligns with after-sales service bundling, where cloud-managed print subscriptions displace transactional hardware sales. Cost compression in desktop segments is intensifying because Brother Industries and Seiko Epson compete for small-business channel shelf space. Mid-sized logistics providers exhibit highest price sensitivity due to capital constraints, while pharmaceutical manufacturers demonstrate lowest sensitivity given compliance mandates.
Supply Chain Analysis
Contract manufacturing concentrates among Taiwanese and Chinese EMS providers handling final assembly for Zebra Technologies and Honeywell International. Precision thermal printhead production centers on Japan and South Korea, with ceramic nozzle plate fabrication drawing from specialty chemical suppliers in Germany and Switzerland. Single-source vulnerability in piezoelectric inkjet printhead supply creates exposure during demand surges for pharmaceutical serialization equipment. Distribution runs through authorized industrial distributors in Germany and the United States, with depot repair networks supporting desktop and mobile product lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The label printers market functions as a defensive-moat industry where regulatory entrenchment protects incumbent positions. Switching costs embedded in warehouse management system integrations and consumables lock-in sustain pricing power across replacement cycles.
For Market Incumbents: Entrench position through backward integration into thermal printhead manufacturing and expansion of cloud-managed print services that bundle hardware with per-label pricing models. Counter direct-to-package inkjet substitution by emphasizing FDA-compliant serialization capabilities in pharmaceutical verticals. Prioritize certification investments for EU F-Gas Regulation and REACH substance compliance to maintain European market access. For New Entrants and Emerging Players: Pursue white-space opportunities in India manufacturing localization under PLI scheme incentives, targeting pharmaceutical export clusters in Gujarat and Tamil Nadu with cost-optimized desktop systems. Address underpenetrated mid-market distribution centers with subscription-based device monitoring offerings. Deploy channel partnerships with local system integrators to bypass entrenched distributor relationships in North America and Europe. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among industrial printer OEMs with captive consumables supply and outcome-based service contracts. Long-term viability hinges on exposure to e-commerce logistics automation and healthcare digitization mandates. Acquisition targets should display vertical integration into print engine manufacturing or established cloud-managed print platforms. Monitor quarterly certification update velocity and PLI scheme participant expansion as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Print Engine Manufacturing | Zebra Technologies sustains margin control through captive thermal printhead production for industrial deployments. |
| Cloud-Managed Print Services Launch | Subscription models displace transactional sales among mid-market logistics providers seeking operational expenditure structures. |
| India Manufacturing Localization | PLI scheme incentives attract final assembly investment near pharmaceutical export clusters in Gujarat and Tamil Nadu. |
| UV-Curable Inkjet Platform Expansion | Pharmaceutical manufacturers in Switzerland and Germany adopt systems eliminating ribbon waste at line speeds exceeding 150 meters per minute. |
| REACH-Compliant Formulation Investment | German chemical distributors consolidate qualified supply channels for fluorine-free cleaning solvents meeting EU F-Gas Regulation phase-down requirements. |
Study Parameters
Desk research of SEC 10-K filings, customs trade databases, and OEM technical specifications preceded structured interviews with warehouse operations directors, pharmaceutical packaging engineers, and industrial distributor account managers. Primary fieldwork with third-party logistics providers in Germany and the United States validated equipment deployment patterns and service contract structures. Secondary sources included EPA regulatory filings on volatile organic compound emissions, ECHA substance restriction updates, and SAMR wireless certification records. Bottom-up unit shipment estimates triangulated against top-down revenue aggregation across product categories.
Assumptions held fixed include prevailing REACH and RoHS substance restrictions, existing e-commerce fulfillment automation trajectories, and current wireless spectrum allocations for Bluetooth-enabled mobile devices. Variables incorporated tariff exposure on Chinese-manufactured components, thermal paper cost volatility from bisphenol-A coating transitions, and cloud-managed print service adoption curves across mid-market distribution centers. Segmentation modeling spanned product type, technology, end-user vertical, and application with regional production cluster overlays. CAGRs derived from logistic curve fitting to historical shipment data with adjustment for regulatory mandate timing effects.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by emerging Chinese OEMs or accelerated direct-to-package inkjet substitution would shift outcomes beyond projected ranges. Quarterly review of PLI scheme participant announcements, FDA Food Safety Modernization Act enforcement actions, and thermal printhead supplier capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Flexographic Printing Machine Market
Packaging Printing
Stack Flexo Printing Press Market
Packaging Printing
Stamping Foils Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Digital Label Printers Market
Packaging Printing
Global Electrophotographic Printing in Packaging Market
Packaging Printing
Lithographic Printing for Packaging Market
Packaging Printing
Pre-Press for Packaging Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
North America Thermal Transfer Overprinter Market
Packaging Printing
Pre-Printed Liners Market
Packaging Printing
Electrophotography Printing for Packaging Market
Packaging Printing
Printed Boxes Market
Packaging Printing
Global Printing for Packaging Market
Packaging Printing
North America Print Label Market
Packaging Printing
Flex Banner Market