
 Flex Banner Market | 2026-2036
Flex Banner Market Size, Share, and Industry Trends Forecast 2026-2036
Flex Banner Market Analysis
Event organizers are bifurcating from traditional retail buyers as the fastest-growing procurement archetype in flex banner demand. Ultraflex Systems Incorporated anchors North American distribution through specialized wide-format substrate portfolios. Cooley Group Holdings, Inc. dominates coated technical textile manufacturing with backward integration into polymer compounding. Shanghai Hanker Industrial Co. Ltd. extends cost-competitive vinyl production across Asia-Pacific export channels.
Flex banners are large-format printed substrates, typically constructed from PVC-coated polyester scrim or woven polyethylene mesh with weights ranging from 9 to 22 ounces per square yard, engineered for weather-resistant outdoor display and high-resolution graphic reproduction. Vinyl substrates command the largest installed base due to durability and print compatibility, while mesh variants capture the fastest growth in windy exterior applications where permeability reduces structural load. Digital printing technology leads value creation as on-demand, short-run production displaces analog screen methods; eco-solvent systems retain share in emerging markets where capital replacement cycles lag.
REACH restrictions on phthalate plasticizers and the EU Green Deal packaging sustainability targets compel reformulation of PVC-based banner chemistries across European supply chains. The US EPA industrial emissions framework and state-level extended producer responsibility laws in California and New York shape domestic manufacturing compliance costs. Stakeholders must monitor substrate recyclability certification schemes and regional chemical disclosure databases to preserve market access as regulatory fragmentation intensifies.
Market Dynamics
Digital printing infrastructure is compressing production lead times from weeks to hours, forcing substrate suppliers to reconfigure inventory positions and technical service capabilities around same-day fulfillment expectations.
Growth Catalysts
- EU Green Deal packaging targets:The EU Green Deal mandates recyclability benchmarks that accelerate procurement of polyethylene-based alternatives to traditional PVC banners across German and French outdoor advertising markets.
- Mesh substrate permeability:High-wind exterior installations in coastal and elevated urban environments are specifying woven polyethylene mesh to reduce structural load and permit airflow without graphic degradation.
- Experiential marketing spend:Temporary event infrastructure budgets are expanding faster than permanent retail signage, creating concentrated demand spikes for short-run, recyclable banner formats.
Market Restraints
- Phthalate plasticizer substitution costs:REACH restrictions on phthalate chemistries force reformulation of PVC coating compounds, raising raw material costs and requiring requalification of print compatibility.
- Petrochemical feedstock volatility:Ethylene and propylene price swings transmit directly to polyethylene and PVC substrate margins, compressing producer pricing power during upstream spikes.
- Alternative display technologies:LED modular screens and projection mapping systems are capturing premium outdoor advertising placements previously served by large-format printed banners.
Strategic Opportunities
- India infrastructure digitization:Smart city initiatives and highway modernization programs are creating first-time demand for weather-resistant outdoor signage in tier-2 and tier-3 urban corridors.
- Take-back and closed-loop recycling:Extended producer responsibility frameworks in California and New York are creating competitive differentiation for substrate suppliers with certified recycling partnerships.
- UV-curable ink convergence:The pairing of UV-curable digital inks with coated polyester scrim is enabling same-day production cycles that analog screen printing cannot match.
Industry Challenges
- Color management specialist scarcity:The shift from analog to digital workflows requires technicians proficient in ICC profiling and RIP software calibration, a skill set concentrated among aging screen-printing veterans.
- Multi-site certification complexity:Suppliers serving pan-European customers must maintain simultaneous REACH, CE marking, and national chemical disclosure registrations with divergent documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flex Banner Market |
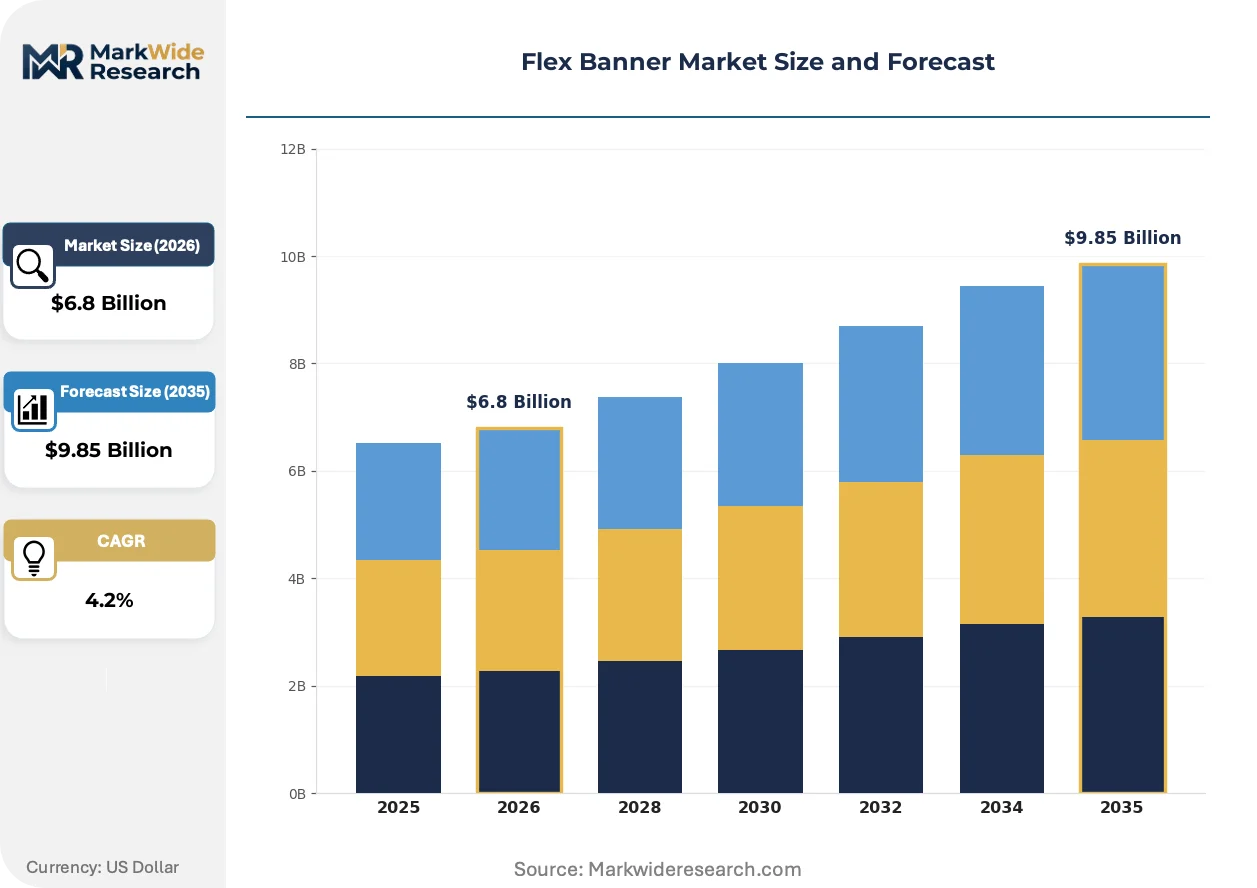
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Vinyl, Polyethylene, Polyester, Mesh Printing Technology: Digital Printing, Offset Printing, Screen Printing, Eco-Solvent Printing End User: Retail, Events, Corporate, Advertising Agencies Application: Outdoor Advertising, Trade Shows, Promotions, Point of Sale |
| Companies Covered | Qrex Flex Pvt. Ltd., Cooley Group Holdings, Inc., Ultraflex Systems Incorporated, Avery Dennison, Shanghai Hanker Industrial Co. Ltd., 3M Company, Pioneer Polyleathers Pvt Ltd., Canon Inc., LG Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flex Banner Market Emerging Trajectories
Substrate chemistry and print technology are converging to compress production cycles while regulatory pressure on polymer lifecycles intensifies material innovation priorities.
Water-based latex ink systems are supplanting solvent-based alternatives in high-volume European print houses. Brand owners and municipal buyers in Germany and the Netherlands are specifying latex-compatible coated polyester for indoor and short-term outdoor applications to eliminate volatile organic compound emissions. This chemistry shift is compressing the installed base of eco-solvent printers and forcing equipment finance decisions among mid-scale print service providers.
REACH Annex XVII restrictions on phthalate plasticizers are compelling PVC banner reformulations across European coating operations. Manufacturers are migrating to bio-based plasticizers and alternative polymer backbones to preserve market access, with compliance costs concentrated among smaller compounders lacking in-house regulatory affairs capabilities. The substitution timeline is tightest for suppliers serving French and German customers with 2025 disclosure deadlines.
Event-driven procurement models are fragmenting traditional annual contract structures. Experiential marketing agencies and festival organizers are consolidating spend with print service providers offering 48-hour turnaround and direct-to-site logistics, displacing the distributor-mediated purchasing patterns that dominate retail and corporate signage. This behavioral shift is most pronounced in North American and Western European metropolitan markets with dense event calendars.
Flex Banner Market Segmentation
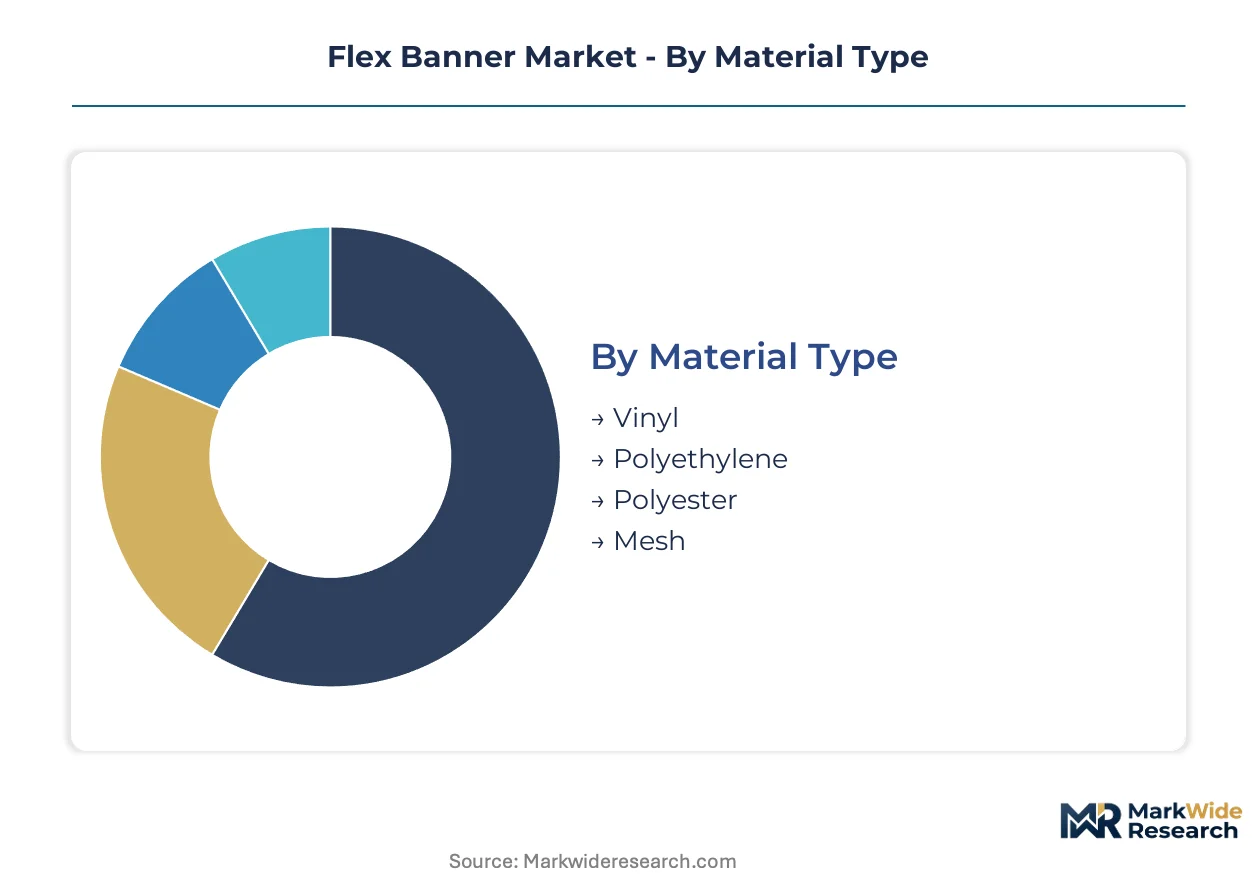
Flex banner procurement patterns diverge sharply across material chemistry, print compatibility, and end-use durability requirements. Substrate suppliers must align technical specifications with regulatory constraints and application-specific performance thresholds to capture contract value.
Material Type:
REACH Annex XVII phthalate restrictions and EU Green Deal recyclability mandates are segmenting procurement between legacy PVC formulations and compliant alternatives.
- Vinyl:PVC-coated polyester scrim delivers weather resistance and print compatibility across solvent, eco-solvent, and UV-curable ink systems. German outdoor advertising operators specify vinyl for permanent installations despite reformulation costs from plasticizer substitution requirements.
- Polyethylene:Woven or extruded PE substrates offer heat-sealed edge durability and full recyclability under EU packaging waste directives. French municipal buyers and Dutch event agencies are consolidating procurement of polyethylene banners ahead of extended producer responsibility enforcement.
- Polyester:Coated PET films provide dimensional stability for high-resolution digital reproduction in indoor and short-term outdoor applications.
- Mesh:Perforated woven structures reduce wind load coefficients for elevated or coastal installations.
Established volume favors vinyl; emerging adoption favors polyethylene.
Printing Technology:
Capital replacement cycles and emission regulations are concentrating demand toward aqueous and UV-curable systems while legacy solvent platforms retain share in cost-sensitive markets.
- Digital Printing:Piezoelectric inkjet systems enable variable-data, short-run production with turnaround times compressed to hours. North American experiential marketing agencies specify digitally printed substrates for event-driven procurement with 48-hour fulfillment requirements.
- Eco-Solvent Printing:Mild-solvent ink chemistries balance outdoor durability with reduced volatile organic compound emissions versus full-solvent alternatives. Southeast Asian print service providers maintain installed base for price-competitive outdoor advertising production.
- Screen Printing:Analog stencil methods retain share for ultra-long-run, single-graphic campaigns where amortized setup costs justify lower per-unit ink expenditure.
- Offset Printing:Lithographic transfer delivers photographic reproduction quality for premium indoor display applications with extended viewing distances.
Digital systems are climbing the fastest; eco-solvent retains defensive share in emerging markets.
End User:
Procurement behavior fragments between annual contract structures and event-driven spot purchasing with divergent logistics and sustainability requirements.
- Events:Festival organizers and experiential marketing agencies specify recyclable polyethylene formats with direct-to-site logistics. German and French event procurement is expanding faster than traditional retail channels under corporate sustainability mandates.
- Retail:Chain store operators maintain seasonal refresh programs with standardized banner dimensions and centralized distribution. North American big-box retailers negotiate volume contracts with print service providers offering national fulfillment networks.
- Corporate:Brand marketing departments source temporary installations for product launches and shareholder events with emphasis on color consistency across multiple sites.
- Advertising Agencies:Media buyers coordinate outdoor advertising campaigns with municipal permitting requirements and substrate durability specifications.
Event-driven procurement is gaining share fastest; retail maintains volume concentration.
Application:
Environmental exposure duration and structural load conditions determine substrate weight, coating chemistry, and finishing specifications.
- Outdoor Advertising:Highway and transit shelter installations demand 13-22 oz/yd² vinyl scrim with reinforced hems and grommet spacing engineered for wind load. German roadside advertising spend on sustainable substrates is expanding under municipal green procurement policies.
- Trade Shows:Temporary exhibition graphics prioritize lightweight, rollable formats with crease-resistant coatings for repeated installation cycles.
- Promotions:Limited-duration campaigns specify cost-optimized substrates with single-season UV stability.
- Point of Sale:In-store display applications emphasize lay-flat packaging and compatibility with clip-rail mounting systems.
Outdoor advertising anchors revenue; trade show applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export cost-competitive vinyl substrates to Southeast Asian event markets, while German converters supply recyclable polyethylene formats to Dutch and French municipal buyers under tightening EU packaging directives.
Germany
Outdoor advertising operators in Berlin and Hamburg are procuring reformulated PVC scrim ahead of REACH Annex XVII enforcement. The EU Green Deal packaging targets mandate recyclability benchmarks that accelerate polyethylene adoption for transit shelter installations. Bavarian coating compounders are restructuring supply chains to serve French disclosure deadlines.
United States
Experiential marketing agencies in Los Angeles and New York City demand 48-hour turnaround on digitally printed event banners. EPA industrial emissions frameworks and California extended producer responsibility laws elevate compliance costs for domestic manufacturers. Midwest print service providers are consolidating volume contracts with national retail chains.
China
Yangtze River Delta fabricators export woven polyethylene mesh to Australian and Southeast Asian wind-exposed installations. MIIT industrial standards and provincial environmental inspections pressure smaller compounders to consolidate or exit. Shanghai-based producers maintain cost advantages across Asia-Pacific export channels.
India
Smart city initiatives in Maharashtra and Karnataka generate first-time demand for weather-resistant highway signage. BIS certification requirements and DGFT export promotion schemes shape procurement specifications for domestic infrastructure projects. Gujarat chemical clusters are expanding coating capacity to serve tier-2 urban corridor modernization.
France
Municipal buyers in Paris and Lyon specify recyclable polyethylene banners for festival and public event infrastructure. ANSM chemical disclosure registrations and national extended producer responsibility frameworks enforce stricter substrate traceability than EU baseline requirements. Île-de-France print houses are migrating from eco-solvent to latex-compatible coated polyester.
Flex Banner Market Vendor Landscape
Listed leaders compete with private specialists across substrate chemistry and geographic coverage dimensions. The vendor base stratifies into three tiers: multinational material science conglomerates with captive polymer supply, regional coating specialists with backward integration into compounding, and distributed print service providers with equipment-financed substrate procurement. Consolidation pressure concentrates among mid-scale compounders lacking in-house regulatory affairs capabilities. Dominant competitive moves include strategic partnerships with recycling operators and geographic expansion through distributor acquisition.
Within the multinational tier, 3M Company and Avery Dennison occupy positions anchored by material science portfolios spanning adhesive and coating technologies. Cooley Group Holdings, Inc. exemplifies the integrated specialist archetype with backward integration into polymer compounding. Shanghai Hanker Industrial Co. Ltd. represents cost-optimized Asian manufacturing positioned for export channel penetration.
| Leading Market Players |
|---|
| Qrex Flex Pvt. Ltd. |
| Cooley Group Holdings, Inc. |
| Ultraflex Systems Incorporated |
| Avery Dennison |
| Shanghai Hanker Industrial Co. Ltd. |
| 3M Company |
| Pioneer Polyleathers Pvt Ltd. |
| Canon Inc. |
| LG Corporation |
| Others |
Supply Flow & Price Mechanics
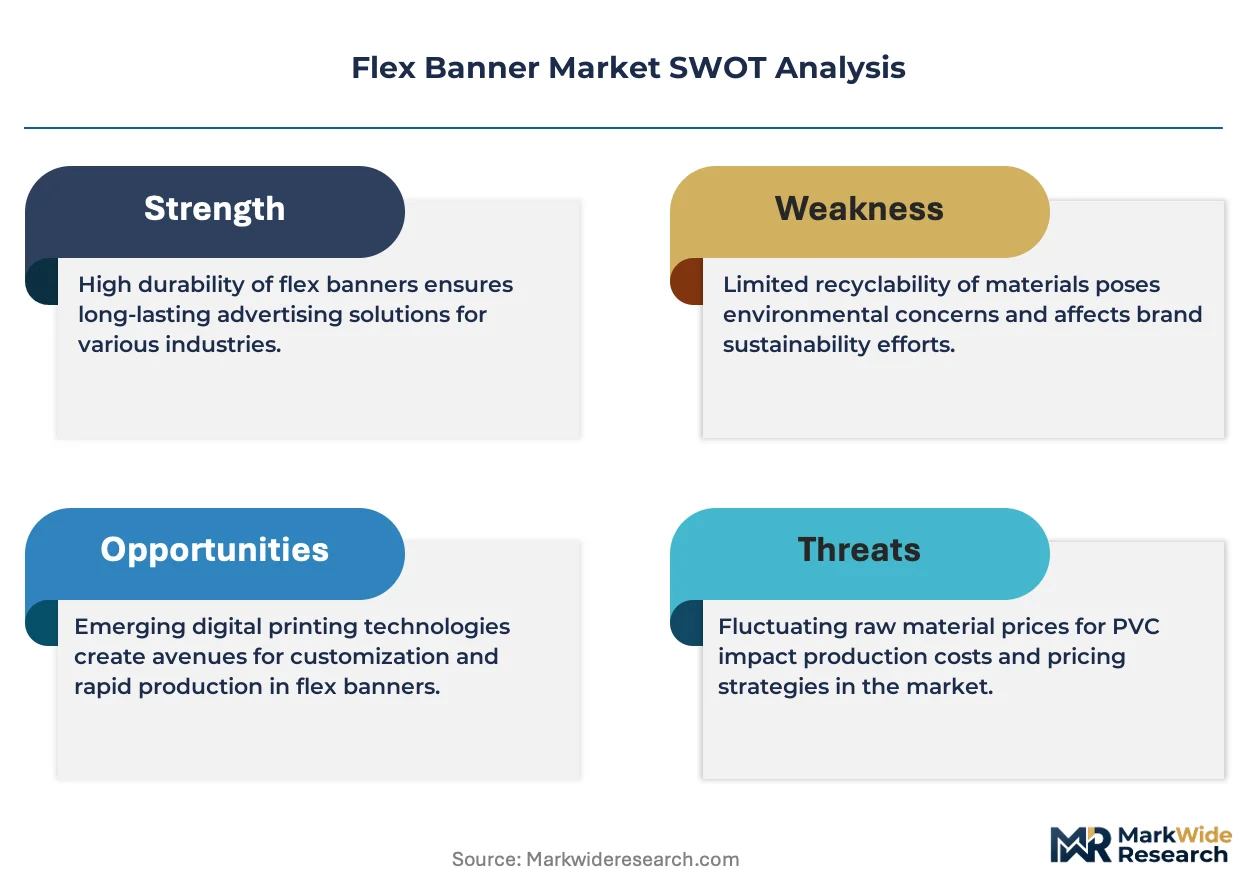
REACH Annex XVII phthalate restrictions gate both substrate qualification and price differentiation simultaneously, as German and French buyers now demand reformulation certificates alongside durability guarantees, compressing margins for non-compliant compounders while rewarding certified suppliers with contract premiums.
Pricing Analysis
Current-generation latex-compatible coated polyester commands 15-25% premiums over prior-generation eco-solvent substrates, while next-generation bio-based plasticizer formulations face upward cost pressure from raw material scarcity. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with REACH-compliant polyethylene banners priced above legacy PVC in municipal procurement. Price differentiation stems from recyclability certification and geographic delivery cost, with pricing pressure intensifying as Chinese exporters absorb freight volatility to defend Asia-Pacific share. Event-driven buyers exhibit highest price sensitivity; permanent outdoor advertising operators prioritize durability over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate among German coating compounders facing Q1 feedstock volatility, while just-in-time inventory governs North American experiential marketing fulfillment. Supply concentrates in China, Germany, and India, with Yangtze River Delta fabricators and Bavarian compounders anchoring regional output. Raw material dependencies center on ethylene and propylene feedstocks, polyester scrim, and specialty plasticizers. Single-source vulnerability from petrochemical price swings threatens margin stability. Distribution runs through converter-mediated channels for retail contracts and direct-to-site logistics for event procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flex banner market is experiencing high-growth disruption as EU Green Deal packaging targets force material chemistry transitions faster than capital replacement cycles can absorb.
For Market Incumbents: Secure backward integration into polymer compounding to capture margin from REACH-driven reformulation demand and insulate against ethylene price volatility. Defend position by acquiring certified recycling partnerships in California and New York ahead of extended producer responsibility enforcement, while consolidating distributor networks in Germany to lock out Asian exporters. For New Entrants and Emerging Players: EU Green Deal fast-track certification for polyethylene substrates opens white-space in French municipal procurement and Dutch event agency supply chains. Target tier-2 Indian urban corridors where smart city infrastructure digitization creates first-time demand for weather-resistant highway signage. Lead with direct-to-site logistics partnerships to bypass established converter networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital print service providers as equipment financing terms compress and UV-curable ink convergence reduces substrate qualification overhead. Long-term viability favors mid-scale compounders with in-house regulatory affairs capabilities serving pan-European customers. Watch for REACH disclosure deadline clustering as signal for consolidation acceleration among non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Cooley Group Holdings exemplifies margin capture from captive plasticizer supply under REACH pressure. |
| Recyclability Certification Partnership | California extended producer responsibility laws reward suppliers with closed-loop recycling infrastructure. |
| Digital Print Service Expansion | Ultraflex Systems leverages same-day fulfillment to consolidate experiential marketing agency spend. |
| Geographic Distributor Acquisition | German converters acquire Dutch and French channel partners to secure municipal polyethylene procurement. |
| Bio-Based Plasticizer R&D Investment | Bavarian compounders reformulate PVC coatings to preserve market access under 2025 disclosure deadlines. |
Methodological Framework
Cross-validation between primary interviews with coating compounders, print service providers, and event procurement managers and secondary validation through ECHA substance registrations, EU packaging waste directive filings, and customs trade data anchors the qualitative findings. Bottom-up demand modeling from substrate consumption at individual print houses triangulates against top-down market sizing from polymer feedstock consumption patterns.
Sensitivity analysis across material type, printing technology, and end-user procurement behavior segments informs the analytical framework over the projection horizon. CAGRs derive from weighted average growth assumptions across German outdoor advertising spend, Indian infrastructure digitization, and North American experiential marketing expansion. Modeled inputs include REACH compliance cost pass-through rates and digital printer installed base replacement cycles.
Decision-makers should treat outputs as directional under stable petrochemical feedstock pricing and gradual REACH enforcement timelines; material deviation would warrant model refresh. Revision becomes warranted when EU Green Deal packaging targets accelerate or ethylene price volatility exceeds historical bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Stack Flexo Printing Press Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
Heat Transfer Press Printing Machine Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
Soft Signage Market
Packaging Printing
Pre-Press for Packaging Market
Packaging Printing
North America Thermal Transfer Overprinter Market
Packaging Printing
Pigment Hot Stamping Foil Market
Packaging Printing
Global Digital Printing Packaging Market
Packaging Printing
North America Print Label Market
Packaging Printing
Europe Printed Packaging Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Digital Label Printers Market
Packaging Printing
Flexographic Printing Machine Market
Packaging Printing
Hot Foil Printing Machines Market