
 Digital Label Printing Market | 2026-2036
Digital Label Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Label Printing Market Analysis
Asset-light leasing models for digital presses is reconfiguring competitive entry barriers, allowing mid-sized converters to access production-grade inkjet systems without capital-intensive ownership. Avery Dennison Corporation leverages its materials science portfolio to dominate premium pressure-sensitive substrates. CCL Industries Inc. sustains manufacturing scale across multiple continents. Toppan Printing Co., Ltd. specializes in security-integrated label architectures for pharmaceutical clients.
Digital label printing employs non-contact imaging technologies—primarily piezoelectric inkjet and electrophotographic laser systems—to deposit variable data, graphics, and machine-readable codes directly onto substrate webs at resolutions exceeding 600 dpi, eliminating the need for physical printing plates and enabling run lengths as short as a single unit. Its primary commercial purpose centers on enabling brands to manage SKU proliferation, regional regulatory variations, and personalized marketing campaigns without the economic penalties of conventional analog setup. Pressure-sensitive labels occupy the largest value share given their ubiquity across food, pharmaceutical, and logistics applications, while shrink sleeves represent the fastest-growing product category as beverage brands pursue 360-degree graphic real estate and tamper-evident functionality. Inkjet technology leads unit installations due to its compatibility with diverse substrates and water-based ink formulations that align with tightening volatile organic compound restrictions.
The European Union's F-Gas Regulation and REACH chemical compliance frameworks constrain solvent-based ink formulations, redirecting converter investment toward UV-curable and water-based digital systems. FDA serialization requirements under the Drug Supply Chain Security Act and evolving EU MDR traceability mandates compel pharmaceutical label producers to integrate variable data capabilities that only digital platforms reliably deliver. Stakeholders must monitor how divergent regional chemical regulations reshape ink chemistry roadmaps and equipment certification requirements.

Market Dynamics
Pharmaceutical serialization mandates across the European Union and United States are compressing converter technology refresh cycles, forcing asset replacement toward digital-native platforms capable of variable-data output at production speeds.
Growth Catalysts
- EU F-Gas Regulation:The phase-down of hydrofluorocarbon propellants in solvent-based systems redirects German and French converters toward UV-curable inkjet architectures with near-zero volatile organic compound emissions.
- Pharmaceutical track-and-trace mandates:The Drug Supply Chain Security Act in the United States and EU MDR serialization requirements compel label producers to integrate machine-readable codes, variable lot numbers, and tamper-evident features that analog presses cannot execute economically.
- SKU proliferation in consumer packaged goods:Beverage and personal care brands now manage thousands of stock-keeping units with regionalized packaging, eliminating the economic viability of plate-based setup for short-run production.
Market Restraints
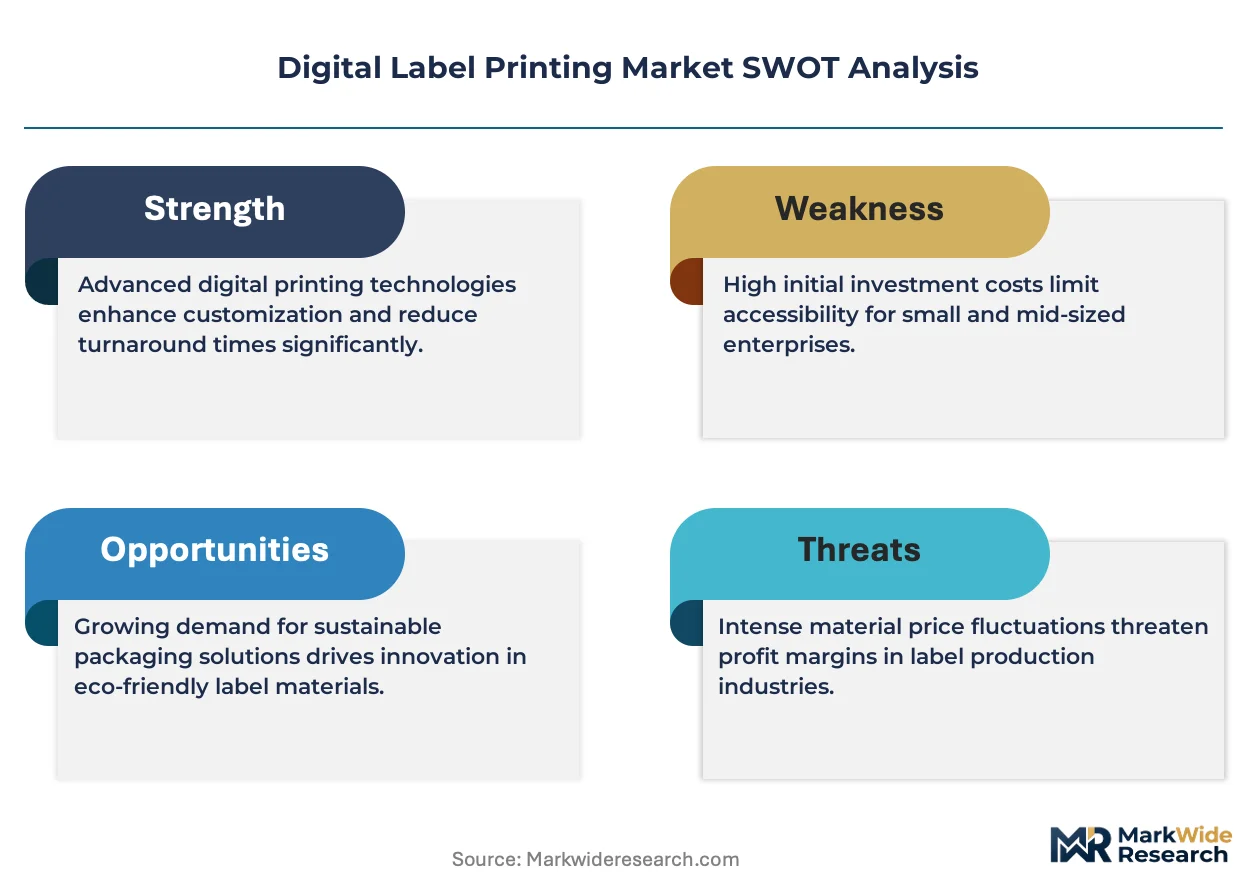
- Substrate cost volatility:Pressure-sensitive facestock prices fluctuate with petrochemical feedstock markets, compressing converter margins on digitally printed rolls where material represents 60-70 percent of job cost.
- Specialized ink supply concentration:UV-curable and water-based ink formulations for narrow-web inkjet depend on a limited supplier base concentrated in Germany, Japan, and the United States, creating vulnerability to regional supply disruptions.
- Throughput ceiling on single-pass systems:Piezoelectric inkjet arrays max out at 150-200 meters per minute on flexible packaging-grade substrates, below the 400+ meter-per-minute speeds of flexographic CI presses for long-run commodity labels.
Strategic Opportunities
- Smart label integration:Convergence of printed electronics with conventional label substrates enables NFC-enabled and RFID-inlay products for authentication and cold-chain monitoring in pharmaceutical logistics.
- India pharmaceutical export compliance:Indian generic drug manufacturers supplying regulated markets must adopt serialization-capable digital lines to meet EU and US import requirements, creating equipment demand in Ahmedabad and Hyderabad manufacturing clusters.
- Asset-light service models:Leasing structures and print-on-demand platforms allow mid-sized converters to access production-grade inkjet without capital ownership, lowering entry barriers in secondary European markets.
Industry Challenges
- Color management specialist scarcity:Digital front-end calibration, ICC profiling, and expanded-gamut ink set optimization require operators with cross-disciplinary skills in spectrophotometry and RIP software that traditional flexographic training programs do not cover.
- Legacy workflow integration:Prepress departments running Esko or Hybrid Software ecosystems face friction connecting digital press controllers to existing MIS and ERP systems without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Label Printing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Labels, Shrink Sleeves, In-Mold Labels, Hang Tags End User: Food & Beverage, Pharmaceuticals, Retail, Consumer Goods Technology: Inkjet, Laser, Thermal Transfer, Flexographic Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Toppan Printing Co., Ltd., Maverick Label, Avery Dennison Corporation, RR Donnelley & Sons Company, Constantia Flexibles Group GmbH, CCL Industries Inc., All4Labels Group GmbH, Resource Label Group, Multi-Color Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Label Printing Market Emerging Trajectories
Cloud-native production management platforms are rewiring how converters schedule jobs, manage color consistency across distributed facilities, and interface directly with brand-owner specification systems.
Single-pass inkjet arrays with fixed printbar architectures are virtualizing the prepress function entirely. Pharmaceutical contract manufacturers in New Jersey and Bavaria now receive artwork files directly from brand regulatory affairs departments, execute same-day proofing, and eliminate plate inventory. This virtualization collapses the traditional 48-72 hour prepress timeline to under four hours, enabling just-in-sequence production for clinical trial materials with unpredictable demand.
REACH chemical authorization procedures are tightening permissible photoinitiator concentrations in UV-curable inks used for food-contact applications. The European Chemicals Agency's 2023-2024 substance evaluations have flagged specific radical initiators for reproductive toxicity concerns, forcing ink formulators to requalify compliant chemistries. Converters serving the dairy and ready-meal sectors in France and the Netherlands are accelerating migration to LED-UV systems with reduced monomer content to preempt regulatory displacement.
Brand procurement teams now unbundle label specification from converter selection, maintaining approved vendor lists across multiple geographies while centralizing artwork governance. Nestlé and Unilever have implemented cloud-based specification portals where regional procurement officers select from pre-qualified digital converters based on real-time capacity and freight optimization rather than historical relationships. This pattern is most pronounced in Western Europe, where cross-border logistics integration and harmonized food-contact regulations enable multi-source strategies.
Digital Label Printing Market Segmentation
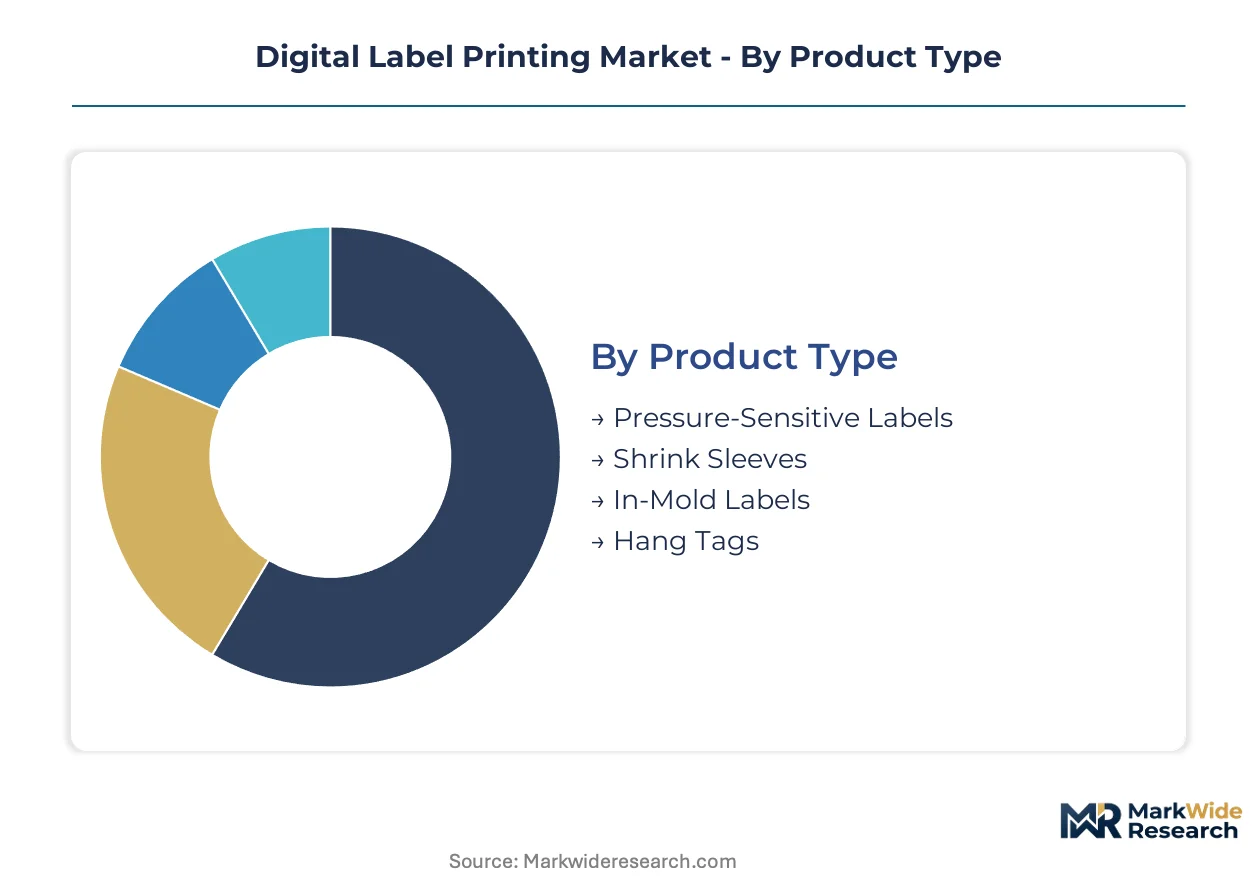
Digital label printing segments diverge sharply in margin structure and capital intensity. Product type determines substrate handling requirements, while technology choice locks converters into specific ink chemistries and regulatory compliance pathways.
Product Type:
Mature formats dominate installed capacity, yet emerging constructions are capturing premium positioning through functional differentiation.
- Pressure-Sensitive Labels:Multi-layer laminates combining facestock, adhesive, and release liner enable instant application across corrugated cases, glass bottles, and flexible pouches. German automotive parts suppliers and French dairy processors consume the highest volumes, driven by F-Gas Regulation mandates favoring solvent-free adhesive systems.
- Shrink Sleeves:Heat-activated PET or PVC films deliver 360-degree graphic coverage and tamper-evident neck bands. Beverage brands in Bavaria and the Rhône-Alpes region specify these for craft spirits and functional waters, where shelf differentiation commands price premiums.
- In-Mold Labels:Polypropylene films fused directly into injection-molded containers during forming. German personal care manufacturers favor this for recyclable mono-material packaging under EU packaging waste directives.
- Hang Tags:Cardstock or synthetic substrates with eyelets or adhesives for apparel and luxury goods. Italian fashion houses and Swiss watchmakers specify these for authentication sequences and QR-linked provenance tracking.
Pressure-Sensitive Labels retain volume leadership; Shrink Sleeves holds the steepest expansion curve.
End User:
Application-driven specifications create divergent technology requirements across verticals.
- Food & Beverage:The largest addressable base, spanning from artisanal producers to multinational CPG networks. Italian pasta manufacturers and Dutch ready-meal suppliers drive demand for migration-compliant UV inks under EFSA food-contact frameworks.
- Pharmaceuticals:Serialization-capable platforms dominate, with EU MDR and FDA DSCSA mandates forcing variable-data integration. Contract manufacturers in New Jersey and Bavaria operate the densest clusters of production-grade inkjet lines.
- Retail:Variable pricing and promotional labeling for private-label merchandise. French hypermarket chains and German drugstore networks deploy digital systems for weekly price markdowns.
- Consumer Goods:Personal care and household products with regionalized SKUs. Unilever's Rotterdam procurement hub sources from multiple digital converters based on real-time capacity.
Food & Beverage captures the broadest converter base; Pharmaceuticals generates the highest equipment specification intensity.
Technology:
Cost tiers separate entry-level systems from production platforms capable of pharmaceutical compliance.
- Inkjet:Piezoelectric drop-on-demand arrays deposit water-based, UV-curable, or solvent inks at resolutions exceeding 600 dpi. German converters favor these for REACH-compliant formulations, while Japanese suppliers dominate printhead supply.
- Laser:Electrophotographic toner systems excel at fine text and security features. Swiss pharmaceutical label specialists deploy these for clinical trial materials requiring absolute color consistency.
- Thermal Transfer:Ribbon-based imaging for variable-data overlays and logistics barcodes. Warehouse operations in the US and Germany specify these for shipping labels.
- Flexographic:Analog plate-based systems retained for ultra-long runs where setup amortization justifies tooling costs. Commodity beverage labels in high-volume markets still route through these lines.
Inkjet commands the dominant share of new installations; Laser maintains the tightest supply concentration among qualified vendors.
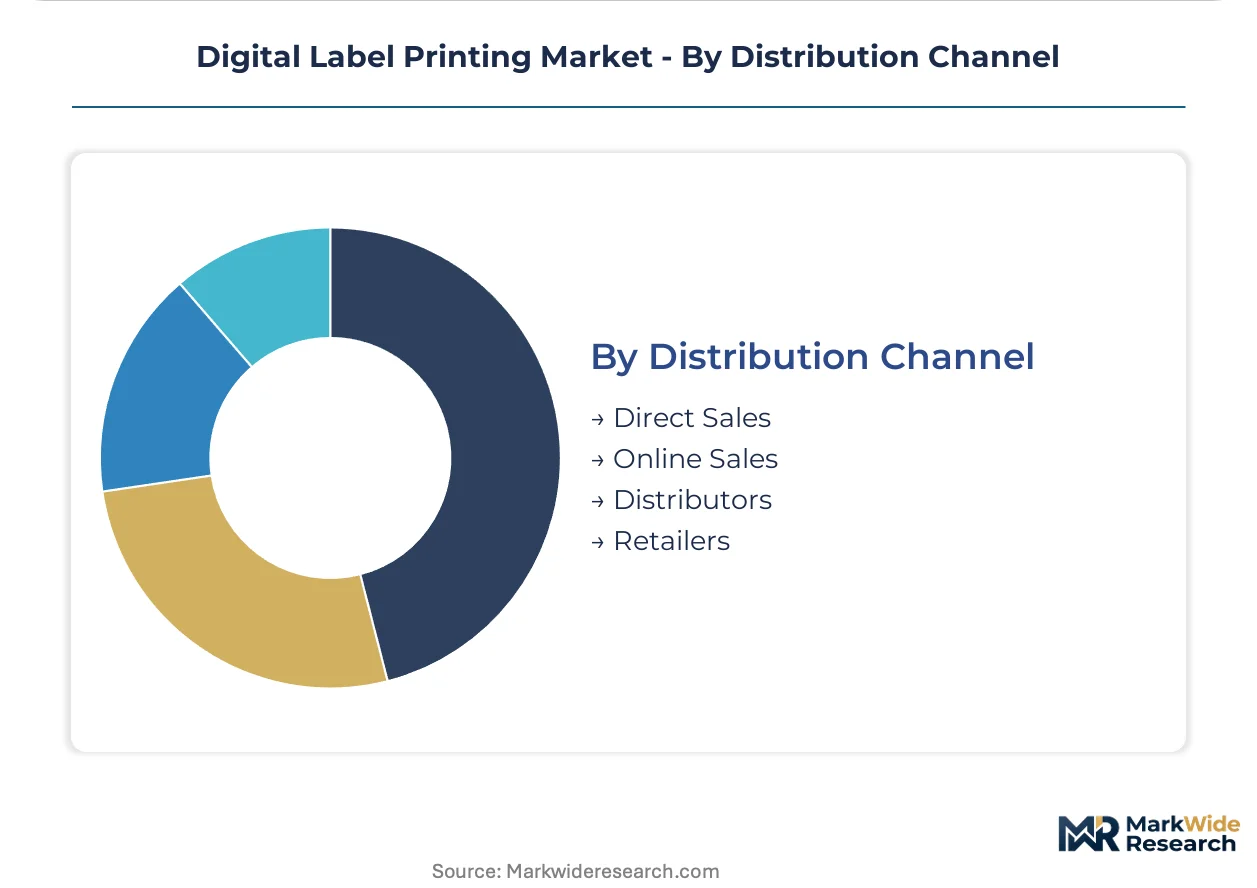
Distribution Channel:
Customer scale and specification complexity determine route-to-market economics.
- Direct Sales:OEM field engineers configure press specifications for pharmaceutical and CPG accounts. Heidelberg and Domino operate direct coverage teams across Germany, France, and the UK.
- Online Sales:Consumables, spare parts, and entry-level desktop systems. UV ink formulations and replacement printheads move through specialized B2B portals.
- Distributors:Regional inventory and technical service for mid-market converters. Benelux and Nordic markets rely heavily on distributor networks for pre- and post-sale support.
- Retailers:Limited to small-format desktop printers and supplies for in-house operations. Office supply chains carry these for micro-business label production.
Direct Sales captures the highest equipment value per transaction; Distributors provide the broadest geographic coverage for service-intensive accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation and REACH chemical frameworks redirect converter investment toward solvent-free digital systems across multiple jurisdictions. Germany anchors European demand through automotive and pharmaceutical labeling clusters. India and the United States follow distinct compliance pathways shaped by export mandates and domestic serialization requirements.
Germany
Automotive parts suppliers and dairy processors consume the highest pressure-sensitive label volumes in Europe. The F-Gas Regulation phases down hydrofluorocarbon propellants, forcing Bavarian converters toward UV-curable inkjet architectures. Heidelberg maintains dense field engineering coverage across Baden-Württemberg and North Rhine-Westphalia for pharmaceutical contract manufacturers.
United States
FDA serialization requirements under the Drug Supply Chain Security Act compress technology refresh cycles for pharmaceutical label producers. New Jersey contract manufacturers operate the densest clusters of production-grade inkjet lines for clinical trial materials. Brand procurement teams at CPG headquarters in Chicago and Cincinnati unbundle label specification from converter selection through cloud-based vendor portals.
India
Generic drug manufacturers in Ahmedabad and Hyderabad must adopt serialization-capable digital lines to meet EU and US import requirements. CDSCO alignment with international traceability standards accelerates equipment demand in western and southern manufacturing belts. Pharmaceutical exporters face tightening compliance windows as destination markets advance track-and-trace deadlines.
France
Beverage brands in the Rhône-Alpes region specify shrink sleeves for craft spirits and functional waters where shelf differentiation commands premiums. EFSA food-contact frameworks drive migration-compliant UV ink demand among dairy and ready-meal suppliers. ANSM pharmaceutical labeling requirements reinforce variable-data capabilities for domestic and export markets.
Japan
PMDA serialization mandates and premium packaging aesthetics sustain demand for high-resolution electrophotographic systems. METI chemical management frameworks constrain photoinitiator concentrations in UV-curable formulations. Printhead suppliers concentrate technical service capabilities in the Kanto and Kansai industrial corridors for narrow-web converter accounts.
Digital Label Printing Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: materials-science conglomerates with adhesive and substrate portfolios, pure-play label converters with multi-continental manufacturing footprints, and security-integrated specialists serving pharmaceutical authentication requirements. Competitive moves concentrate on geographic coverage expansion through distributor partnerships and technology licensing arrangements that lower entry barriers for mid-market converters.
Among Asia-Pacific headquartered printers, Toppan Printing Co., Ltd. occupies a position exemplifying security-integrated label architectures. Avery Dennison Corporation and CCL Industries Inc. represent the materials-science and scale-driven archetypes respectively, with the former anchoring premium pressure-sensitive substrate supply and the latter sustaining manufacturing presence across multiple continents. These three entities illustrate how competitive positioning fragments across substrate control, geographic reach, and vertical specialization rather than consolidating around unified technology platforms.
| Leading Market Players |
|---|
| Toppan Printing Co., Ltd. |
| Maverick Label |
| Avery Dennison Corporation |
| RR Donnelley & Sons Company |
| Constantia Flexibles Group GmbH |
| CCL Industries Inc. |
| All4Labels Group GmbH |
| Resource Label Group |
| Multi-Color Corporation |
| Others |
Supply Flow & Price Mechanics
Japanese printhead manufacturers and German ink formulators concentrate upstream supply, capturing margin pools downstream at pharmaceutical converters in New Jersey and Bavaria who face FDA and EU MDR serialization mandates. Pricing power flows to substrate and ink suppliers who control REACH-compliant chemistry certifications.
Pricing Analysis
Certification level (FDA-grade, CE-marked, ISO-compliant) creates the primary spread across equipment and consumable tiers. Three-tier pricing structure separates pharmaceutical-grade systems with full serialization validation from standard commercial presses and entry-level desktop units. Cost compression in mid-tier equipment is intensifying because asset-light leasing models let converters access production capacity without ownership premiums. Brand-owner procurement teams at CPG headquarters show least price sensitivity for compliance-integrated lines, while secondary market converters in Southern Europe exhibit highest sensitivity to capital expenditure.
Supply Chain Analysis
Petrochemical feedstocks for pressure-sensitive facestock draw from Saudi Arabia, South Korea, and the US Gulf Coast, with adhesive resin production concentrated in Germany and Japan. UV-curable photoinitiators and water-based pigment dispersions hinge on a limited supplier base in Germany, Japan, and the United States. Single-source vulnerability in narrow-web inkjet printhead supply creates exposure to regional logistics disruptions. Distribution runs through OEM direct sales for pharmaceutical accounts and regional distributors for mid-market converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native production management platforms are reconfiguring this market toward platform-economics dynamics where interoperability between brand specification systems and converter scheduling software determines competitive survival.
For Market Incumbents: Harden software ecosystem lock-in by deepening API integrations with Esko and Hybrid Software prepress environments. Secure captive supply of REACH-compliant photoinitiator formulations through backward integration or long-term offtake agreements with German and Japanese chemical suppliers. Defend against asset-light entrants by bundling predictive maintenance analytics with equipment leases.
For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical export compliance, where Ahmedabad and Hyderabad generic manufacturers must adopt serialization-capable lines for EU and US market access. Target asset-light service models for secondary European converters who lack capital for press ownership. Lead with cloud-based color management subscriptions that bypass legacy workflow integration friction.
For Investors and Strategic Acquirers: Capital is best deployed toward security-integrated label specialists with pharmaceutical authentication capabilities and established PMDA or FDA regulatory pathways. Long-term viability favors converters who control both substrate supply and variable-data software layers. Watch for inflection when brand procurement teams centralize artwork governance through cloud-based specification portals.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Production Platform Integration | Enables real-time capacity sharing between Nestlé and Unilever procurement teams across multiple geographies. |
| REACH-Compliant Ink Chemistry Certification | Secures market access for converters serving EFSA-regulated dairy and ready-meal sectors in France and the Netherlands. |
| Asset-Light Leasing Structure Expansion | Lowers entry barriers for mid-sized converters in Benelux and Nordic markets without capital-intensive ownership. |
| Smart Label Electronics Convergence | Creates NFC-enabled authentication products for pharmaceutical cold-chain monitoring in Bavaria and New Jersey logistics hubs. |
| Indian Pharmaceutical Export Compliance Buildout | Positions equipment suppliers to capture CDSCO-aligned serialization demand in Ahmedabad and Hyderabad manufacturing clusters. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with converter operations managers, OEM field engineers, brand procurement leads, and ink formulation chemists were synthesized with ECHA substance evaluations, FDA DSCSA guidance documents, and EU MDR implementation timelines. Bottom-up equipment installation tracking and top-down addressable market sizing were reconciled across the analysis window.
Calibration against historical technology refresh cycles in pharmaceutical labeling informs the projection framework. Segmentation dimensions modeled include product type, end-use vertical, technology platform, and geographic regulatory cluster. CAGRs were derived from unit economics analysis of run-length thresholds where digital displaces analog, incorporating substrate cost volatility and compliance deadline acceleration as sensitivity inputs.
Stress conditions across photoinitiator supply disruptions, F-Gas Regulation phase-down acceleration, and pharmaceutical serialization deadline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization and equipment replacement elasticity. Cross-checking against customs data for narrow-web press imports and CDSCO facility registration trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Stamping Foils Market
Packaging Printing
North America Thermal Transfer Overprinter Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
Europe Printed Packaging Market
Packaging Printing
Flexographic Printing Machine Market
Packaging Printing
Rotogravure Printing Machine Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Heat Transfer Press Printing Machine Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Thermal Transfer Overprinter Market
Packaging Printing
Laser Coders Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Printed Boxes Market
Packaging Printing
Label Printers Market