
 North America Print Label Market | 2026-2036
North America Print Label Market Size, Share, and Industry Trends Forecast 2026-2036
North America Print Label Market Analytics
Pharmaceutical end-use is recalibrating North America print label procurement priorities as serialization deadlines tighten. Avery Dennison Corporation anchors its position through advanced adhesive R&D for temperature-sensitive drug applications. CCL Industries Inc. dominates specialty pharmaceutical and healthcare label segments with extensive North American manufacturing scale. Brady Corporation differentiates via industrial safety and identification labels for chemical and electrical equipment markets.
Print labels are pressure-sensitive, shrink sleeve, in-mold, or RFID-enabled substrates, typically 50-100 micron caliper, affixed to products for identification, branding, regulatory compliance, or supply chain tracking; flexography and digital printing constitute the dominant conversion methods across the region. Pressure-sensitive labels sustain the largest volume share due to universal compatibility with automatic applicators in food and beverage packaging lines. RFID labels represent the fastest-expanding product category as retailers mandate item-level inventory visibility. Polyester and polypropylene materials command premium positioning in electronics and durable goods applications where moisture and chemical resistance prove essential.
The US FDA enforces pharmaceutical labeling standards through the Drug Supply Chain Security Act, while EPA regulations govern adhesive volatile organic compound emissions in converting operations. Health Canada and PMRA coordinate parallel requirements for bilingual drug labels and agricultural chemical identification across the Canadian market. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York that will reshape substrate selection and recycling infrastructure investment.
Market Dynamics
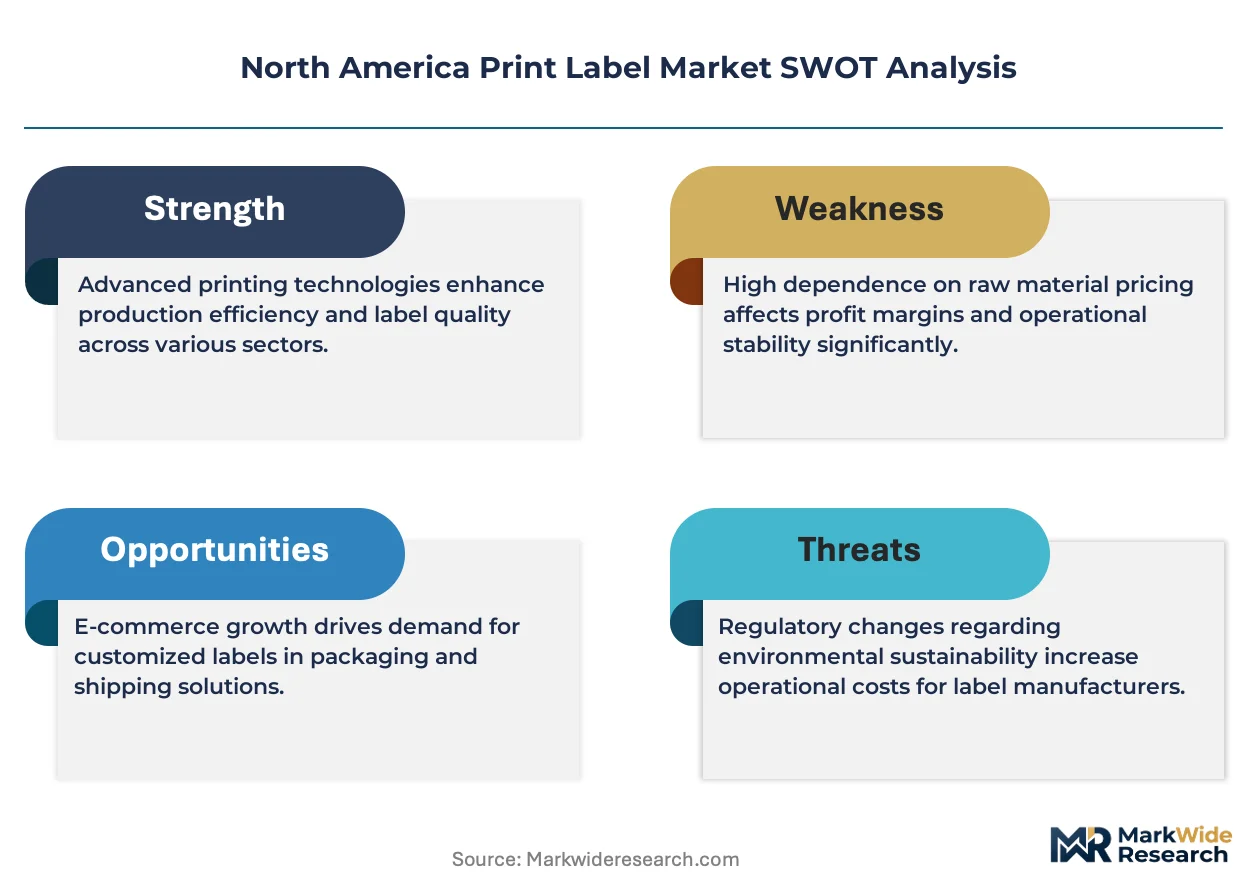
Pharmaceutical serialization mandates under the US Drug Supply Chain Security Act are forcing label converters to retool entire production lines for track-and-trace compliance, compressing margins while elevating technical barriers to entry across the North American supply base.
Growth Catalysts
- US Drug Supply Chain Security Act mandates:Track-and-trace requirements for prescription drugs are driving replacement demand for RFID-enabled and serialized labels in pharmaceutical packaging operations.
- Food processing cluster expansion:High-volume contract label consumption concentrates in Georgia and the Carolinas, where protein processing and beverage bottling facilities sustain dedicated regional supply agreements.
- Digital inkjet adoption:Short-run variable data printing is enabling just-in-time inventory models for craft beverage and nutraceutical brands seeking rapid SKU proliferation without plate costs.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyester resin prices fluctuate with crude oil benchmarks, squeezing converter margins on fixed-price annual contracts with CPG customers.
- Adhesive supply concentration:Specialty acrylic and hot-melt adhesive formulations depend on a narrow base of domestic chemical suppliers, creating single-source vulnerability during force majeure events.
- Extended producer responsibility laws:California and New York state legislation is mandating recyclable or compostable substrate transitions before adequate regional reprocessing infrastructure exists.
Strategic Opportunities
- Mexican nearshoring acceleration:Automotive and electronics manufacturers relocating from Asia are importing North American label specifications, expanding addressable demand for temperature-resistant and chemical-resistant substrates.
- Smart label convergence:Integration of NFC chips and printed sensors with traditional pressure-sensitive constructions is opening premium positioning in cold-chain pharmaceutical logistics.
- USDA bio-preferred procurement:Federal purchasing guidelines favoring biobased content are creating specification advantages for converters with certified sustainable adhesive and facestock portfolios.
Industry Challenges
- Serialization validation timelines:FDA compliance deadlines for lot-level and package-level tracking require simultaneous hardware, software, and substrate qualification cycles that strain quality assurance bandwidth.
- Skilled press operator scarcity:Flexographic and digital hybrid equipment demands cross-trained technicians proficient in color management, die-cutting, and inline inspection systems that vocational programs rarely cover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Print Label Market |
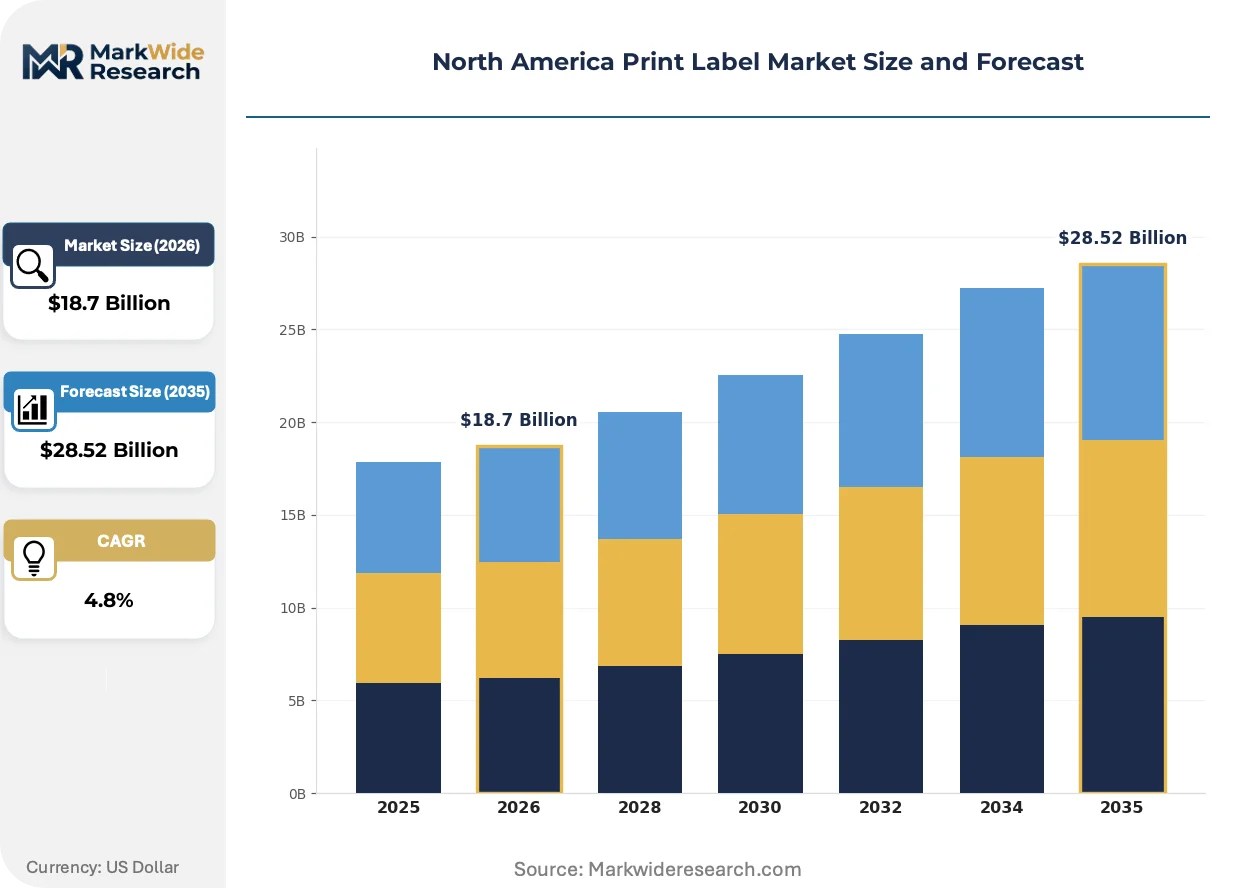
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Labels, Shrink Sleeves, In-Mold Labels, RFID Labels Material: Paper, Vinyl, Polyester, Polypropylene End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Printing Technology: Digital Printing, Flexography, Gravure, Letterpress |
| Companies Covered | WestRock Company, Mondi plc, Avery Dennison Corporation, Cenveo Worldwide Limited, Ahlstrom-Munksjö Oyj, CCL Industries Inc., Multi-Color Corporation, UPM-Raflatac Oy, Brady Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Print Label Market Evolving Landscape
Digital printing architectures and intelligent substrate integration are converging to compress production lead times while embedding compliance and traceability functions directly into label constructions.
Digital hybrid press configurations are modularizing converter capabilities across the North American supply base. Mid-tier packaging suppliers in Ohio and Pennsylvania are adopting single-pass inkjet-flexo systems to bridge the gap between high-volume flexographic runs and variable-data digital jobs. This technology is modularizing the traditional volume threshold between analog and digital economics, enabling profitable production at quantities previously reserved for plate-based methods.
Health Canada and PMRA bilingual labeling requirements for pharmaceutical and agricultural chemical products are mandating dual-language text specifications that exceed US domestic standards. Canadian market entry now demands dedicated artwork workflows and larger label face dimensions that complicate cross-border SKU rationalization. Specialty pharmaceutical label converters with established Health Canada validation protocols are capturing disproportionate share of US-Canada integrated supply agreements.
Brand owners in craft beverage and organic food verticals are compressing supplier rosters to favor converters with integrated design-to-dispatch digital workflows. Legacy broker-mediated procurement models are yielding to direct platform relationships where cloud-based proofing and inventory dashboards replace quarterly business reviews. This concentration is most pronounced in Pacific Northwest and Northeast urban markets where local sourcing preferences intersect with sustainability certification requirements.
North America Print Label Market Segmentation
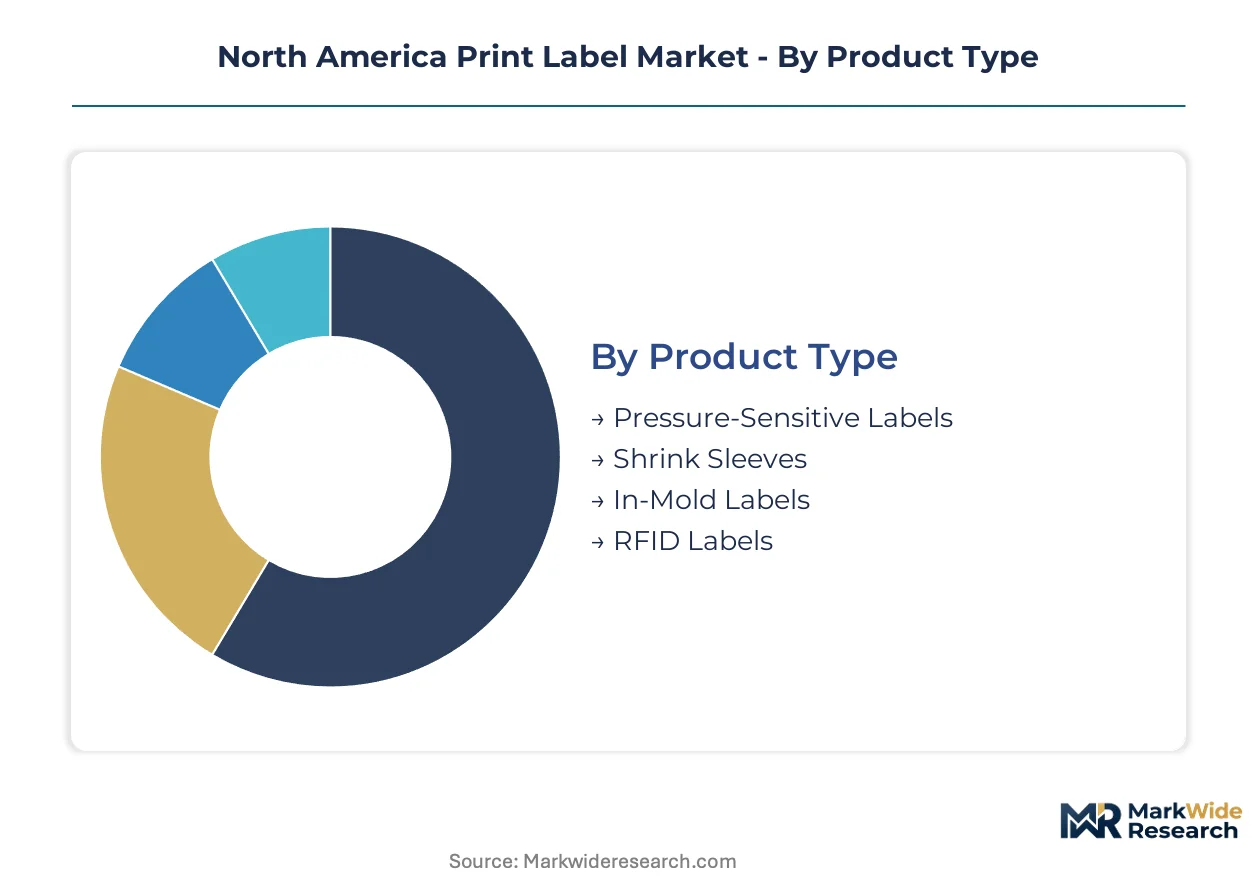
Print label segmentation in North America reflects divergent capital deployment strategies across substrate technologies, material science tiers, and regulatory compliance requirements. Converters must match equipment investments to specific end-use validation protocols rather than pursuing universal platform coverage.
Product Type:
Capital intensity varies sharply across adhesive application systems and substrate conversion lines, with serialization-ready platforms commanding premium upfront outlays.
- Pressure-Sensitive Labels:Self-adhesive constructions with release liner substrates dominate automatic applicator compatibility in high-speed food and beverage packaging. Georgia and Carolina protein processing clusters sustain dedicated regional supply agreements for cold-tack acrylic formulations.
- RFID Labels:Inlays embedding UHF chips for item-level inventory tracking require specialized antenna placement and encoding validation equipment. Retailer mandates for supply chain visibility are accelerating converter investment in hybrid digital-RFID production lines.
- Shrink Sleeves:Heat-contractable polyester films conforming to contoured containers demand dedicated seaming and perforation systems.
- In-Mold Labels:Polypropylene films fused during blow-molding operations require IML-compatible mold retrofits and static-control handling.
Most installed capacity flows through pressure-sensitive platforms. Expansion is steepest in RFID-enabled constructions.
Material:
Raw material selection determines margin stability and regulatory qualification burden across pharmaceutical and durable goods applications.
- Polyester:Caliper-controlled PET films deliver moisture and chemical resistance for electronics and industrial equipment identification. California extended producer responsibility legislation is forcing substrate transitions before regional reprocessing infrastructure matures.
- Polypropylene:Oriented PP films balance stiffness and conformability for in-mold and wraparound label applications. Petrochemical feedstock volatility tied to crude benchmarks squeezes converter margins on fixed-price CPG contracts.
- Paper:Uncoated and coated facestocks dominate short-run craft beverage and organic food verticals where sustainability certification drives procurement.
- Vinyl:Flexible PVC constructions persist in outdoor durable goods and chemical drum labeling where UV resistance outweighs environmental concerns.
Polyester and polypropylene command premium positioning in validated pharmaceutical applications. Paper substrates are gaining specification share fastest in sustainability-focused procurement.
End User:
Customer concentration patterns shape regional production footprints and technical service requirements across the value chain.
- Pharmaceuticals:Serialization mandates under the US Drug Supply Chain Security Act require track-and-trace labels with unique identifiers at package and case levels. FDA compliance deadlines strain quality assurance bandwidth across the converter supply base.
- Food & Beverage:High-volume contract consumption concentrates in Georgia and Carolinas protein processing and beverage bottling corridors. Digital inkjet adoption enables just-in-time inventory models for craft brands pursuing rapid SKU proliferation.
- Consumer Goods:Beauty and household product labels demand decorative finishing and tactile coatings for shelf differentiation.
- Electronics:Temperature-resistant and chemical-resistant substrates serve automotive and electronics manufacturers relocating production to Mexico under nearshoring acceleration.
Food and beverage anchors regional volume concentration. Pharmaceuticals drive the steepest technology upgrade cycle.
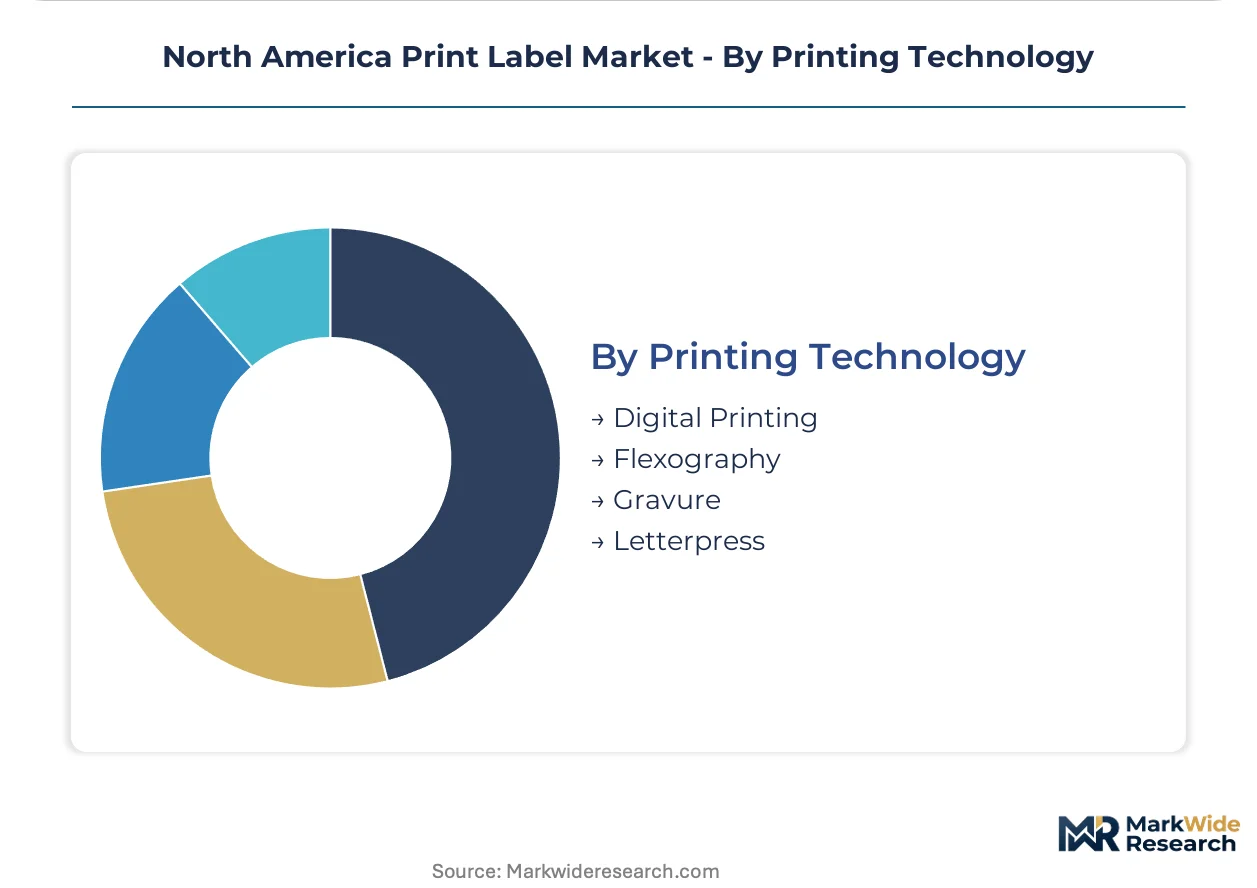
Printing Technology:
Equipment selection determines run-length economics and variable data capabilities across converter customer portfolios.
- Flexography:Rotary letterpress platforms with photopolymer plates dominate high-volume food and beverage runs where color consistency across long impressions proves critical. Skilled press operator scarcity for color management and die-cutting proficiency constrains capacity expansion.
- Digital Printing:Single-pass inkjet and toner systems enable economical short runs with variable data for serialization and regional versioning. Ohio and Pennsylvania mid-tier suppliers are adopting hybrid inkjet-flexo configurations to bridge analog-digital volume thresholds.
- Gravure:Cylinder-based intaglio methods persist in ultra-high-volume tobacco and spirits applications where plate longevity amortizes tooling costs.
- Letterpress:Relief printing with raised plates maintains niche positioning in wine and specialty food labels requiring tactile impression depth.
Flexography retains the largest installed base. Digital platforms are climbing the fastest as variable-data requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Georgia and Carolina protein processing corridors anchor North American print label demand through high-volume contract consumption tied to food and beverage packaging automation.
United States
Pharmaceutical serialization mandates under the FDA's Drug Supply Chain Security Act drive track-and-trace label replacement demand across prescription drug packaging operations. EPA regulations govern adhesive volatile organic compound emissions in converting operations, particularly affecting flexographic and digital production facilities. The US Southeast sustains dedicated regional supply agreements where Georgia and Carolina protein processing and beverage bottling clusters consume cold-tack acrylic formulations at scale.
Canada
Bilingual pharmaceutical and agricultural chemical labeling requirements under Health Canada and PMRA coordination create specification complexity exceeding US domestic standards. The Canadian regulator mandates dual-language text and larger label face dimensions that complicate cross-border SKU rationalization. Ontario and Quebec manufacturing corridors host specialty converters with established Health Canada validation protocols capturing disproportionate share of integrated US-Canada supply agreements.
Mexico
Automotive and electronics manufacturers relocating production from Asia under nearshoring acceleration import North American label specifications for temperature-resistant and chemical-resistant substrates. The country's national industrial development programs support manufacturing zone expansion along the northern border and central Bajío region. Nuevo León and Mexico City Metro industrial corridors are absorbing converter investment to serve relocated Tier 1 and Tier 2 supplier networks.
North America Print Label Market Competitive Landscape
Portfolio diversification dominates the current landscape as converters balance pharmaceutical compliance investments against food and beverage volume stability. The supply base exhibits tiered concentration with multinational material science conglomerates occupying premium validated segments while regional specialists serve commodity food packaging. Three archetypes define competitive positioning: integrated material-converter hybrids, pure-play label specialists with regulatory validation depth, and diversified packaging conglomerates with label divisions. M&A activity and capacity expansion in RFID-enabled and digital hybrid production lines constitute the dominant competitive moves reshaping facility footprints.
Within the integrated material science tier, Avery Dennison Corporation and CCL Industries Inc. exemplify archetypes combining substrate R&D with converting scale. Brady Corporation occupies a distinct position exemplifying industrial safety and identification specialization. These three anchors demonstrate how competitive positioning flows from end-use concentration rather than universal platform coverage.
| Leading Market Players |
|---|
| WestRock Company |
| Mondi plc |
| Avery Dennison Corporation |
| Cenveo Worldwide Limited |
| Ahlstrom-Munksjö Oyj |
| CCL Industries Inc. |
| Multi-Color Corporation |
| UPM-Raflatac Oy |
| Brady Corporation |
| Others |
Value Network & Pricing Analysis
Skilled press operator scarcity in the US Midwest and Southeast widens labor-cost differentials between premium pharmaceutical-grade converters and commodity food-packaging suppliers. This workforce concentration compresses margins at the economy tier while validated serialization-ready facilities command sustained pricing power.
Pricing Analysis
Input-cost pass-through from polypropylene and polyester resin volatility squeezes converter margins on fixed-price annual contracts with CPG customers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical specialists from regional food-packaging suppliers and import-dependent commodity brokers. Price differentiation hinges on certification grade and volume scale, with serialization compliance adding qualification premiums. Price erosion runs through the standard tier as digital inkjet adoption democratizes short-run variable data capabilities.
Supply Chain Analysis
Single-source vulnerability sits with domestic specialty acrylic and hot-melt adhesive formulators concentrated in Texas and Ohio chemical corridors. Raw material flows draw from Saudi and Qatari petrochemical feedstocks, Canadian pulp mills for release liners, and German coating equipment suppliers. Tariff exposure on Chinese-sourced RFID inlays and antenna substrates threatens hybrid digital-RFID production expansion. Distribution runs through converter-direct relationships with protein processing clusters in Georgia and the Carolinas, supplemented by broker-mediated procurement for craft beverage micro-brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America print label market functions as a regulatory compounder where pharmaceutical serialization mandates under the US Drug Supply Chain Security Act generate recurring replacement demand for track-and-trace infrastructure.
For Market Incumbents: Lock in serialization validation protocols ahead of FDA lot-level tracking deadlines to capture integrated US-Canada supply agreements. Defend margin position by securing captive supply of temperature-sensitive adhesive formulations from domestic chemical suppliers. Capacity addition in Nuevo León serves nearshoring automotive and electronics manufacturers importing North American label specifications. For New Entrants and Emerging Players: Enter via RFID-enabled cold-chain pharmaceutical logistics where retailer mandates for item-level inventory visibility outpace converter investment. White-space concentration sits with craft beverage and organic food verticals in Pacific Northwest and Northeast urban markets where local sourcing preferences intersect with sustainability certification requirements. Go-to-market angle: cloud-based proofing and inventory dashboards replacing legacy broker-mediated procurement. For Investors and Strategic Acquirers: Material science conglomerates with label divisions are the most active acquirer in this space, seeking regulatory validation depth to complement substrate R&D capabilities. Long-term viability favors pure-play specialists with Health Canada protocols and hybrid digital-flexo equipment portfolios. Watch for inflection when California and New York extended producer responsibility enforcement triggers substrate transition capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Platform Investment | FDA Drug Supply Chain Security Act compliance deadlines force track-and-trace hardware and software qualification cycles. |
| Hybrid Digital-Flexo Capacity Expansion | Ohio and Pennsylvania mid-tier suppliers bridge analog-digital volume thresholds for profitable short-run production. |
| Mexican Nearshoring Footprint | Automotive and electronics manufacturers relocating from Asia import North American specifications for temperature-resistant substrates. |
| RFID Inlay Integration | Retailer mandates for supply chain visibility accelerate converter investment in hybrid digital-RFID production lines. |
| Biobased Adhesive Certification | USDA BioPreferred procurement guidelines create specification advantages for converters with certified sustainable portfolios. |
Research Methodology
Direct dialogue with flexographic press operators, pharmaceutical packaging engineers, CPG procurement managers, and adhesive R&D directors grounded qualitative findings in operational reality. Secondary validation drew from FDA Drug Supply Chain Security Act guidance documents, EPA volatile organic compound emission standards, Health Canada bilingual labeling requirements, and customs trade data on polypropylene resin imports. Bottom-up and top-down triangulation cross-checked converter capacity estimates against end-use demand projections.
Bottom-up modeling aggregated individual converter equipment configurations and validation statuses across the North American supply base. Segmentation dimensions included product type, material science tier, end-use vertical, and printing technology platform. CAGR derivation incorporated raw material price elasticity, regulatory compliance cost pass-through, and digital adoption curves across the analysis window. Industry-specific inputs encompassed pharmaceutical serialization timeline enforcement and retailer RFID mandate rollout patterns.
Inputs from FDA guidance releases and Health Canada regulatory bulletins were available through the study window; gaps in real-time converter capacity utilization data introduce uncertainty bands around near-term supply-demand balance assumptions. Forecasts reflect documented assumptions on petrochemical feedstock price trajectories and state-level extended producer responsibility implementation schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Pad Printing Machine Market
Packaging Printing
Global Digital Printing Packaging Market
Packaging Printing
Qatar Printing and Packaging Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Mexico Print Label Market
Packaging Printing
Czech Republic Printing Label Market
Packaging Printing
Lithographic Printing for Packaging Market
Packaging Printing
Thermal Transfer Overprinter Market
Packaging Printing
LAMEA Label Printing Software Market
Packaging Printing
North America Thermal Transfer Overprinter Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
Soft Signage Market
Packaging Printing
Digital Label Printers Market
Packaging Printing
Laser Coders Market
Packaging Printing
Stamping Foils Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market