
 Pigment Hot Stamping Foil Market | 2026-2036
Pigment Hot Stamping Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Pigment Hot Stamping Foil Market Outlook
Polyester substrates is restructuring cost-performance tradeoffs across the pigment hot stamping foil sector as converters seek thinner gauges with equivalent opacity. KURZ leverages vertical integration from pigment synthesis to reel finishing to sustain margin control across European supply chains. Crown Roll Leaf Inc. anchors North American distribution through dedicated slitting and warehousing operations in the Midwest. OIKE & Co. Ltd specializes in heat-resistant formulations that compete in automotive interior applications where thermal cycling durability matters.
Pigment hot stamping foil consists of a carrier film coated with a pigment release layer, an adhesive sizing, and a heat-activated bonding stratum that transfers decorative color under pressure and temperature typically between 80°C and 200°C. The technology serves primarily for permanent, abrasion-resistant surface decoration on plastics, paper, and coated substrates without liquid ink systems. Polyester dominates product type volumes due to dimensional stability during high-speed rotary stamping, while specialty films capture disproportionate margin pools in security and anti-counterfeit applications. Labeling leads application demand from pharmaceutical and spirits sectors, whereas packaging applications in premium consumer goods represent the fastest-growing consumption category as matte finishes displace conventional metallization.
REACH governs chemical substance registration and restricts hazardous pigment constituents across European manufacturing and import channels. ECHA classification criteria for pigment intermediates directly shape formulation R&D priorities and raw material qualification timelines. FDA indirect food contact regulations constrain adhesive and pigment selections for packaging applications in the United States. Stakeholders must monitor evolving substance restriction proposals in both jurisdictions to anticipate reformulation costs and secure alternative pigment supply before compliance deadlines tighten.
Market Dynamics
REACH compliance is forcing pigment reformulation across European supply chains as ECHA substance restrictions tighten on heavy metal constituents and halogenated intermediates, compelling converters to qualify alternative colorant systems ahead of sunset dates.
Growth Catalysts
- Luxury cosmetics packaging:Premium beauty brands in France and Italy are abandoning metallic foils for matte pigment finishes that signal understated sophistication and align with clean beauty positioning.
- REACH substance registration:The EU chemicals framework is accelerating R&D investment in compliant pigment architectures as manufacturers pre-empt SVHC candidate list expansions.
- Heat-resistant adhesive chemistry:Automotive interior specifications for thermal cycling durability above 120°C are opening specification wins in dashboard and trim applications.
Market Restraints
- Petrochemical feedstock volatility:Polyester carrier film costs fluctuate with purified terephthalic acid pricing, compressing converter margins during upstream spikes.
- German supply concentration:Advanced metallization and coating infrastructure clusters around Stuttgart and Munich, creating single-source vulnerability for just-in-time European converters.
- Digital inkjet substitution:UV-curable ink systems achieve comparable matte aesthetics on short runs without tooling costs, threatening foil volumes in label prototyping.
Strategic Opportunities
- Indian pharmaceutical labeling:CDSCO serialization mandates and export packaging upgrades are creating first-mover openings for compliant pigment foil suppliers.
- Anti-counterfeit feature integration:Covert pigment signatures combined with micro-optical elements address brand protection demand in spirits and tobacco.
- US sustainable packaging procurement:California's extended producer responsibility frameworks and retailer sustainability scorecards favor recyclable mono-material structures over metallized laminates.
Industry Challenges
- Color matching for brand equity:Cosmetic and spirits clients demand batch-to-batch consistency within Delta E thresholds below 1.0, requiring spectrophotometric calibration investments and skilled color technicians.
- REACH pre-registration timelines:New pigment intermediate qualification cycles extend 18-24 months, delaying product launches and freezing formulation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pigment Hot Stamping Foil Market |
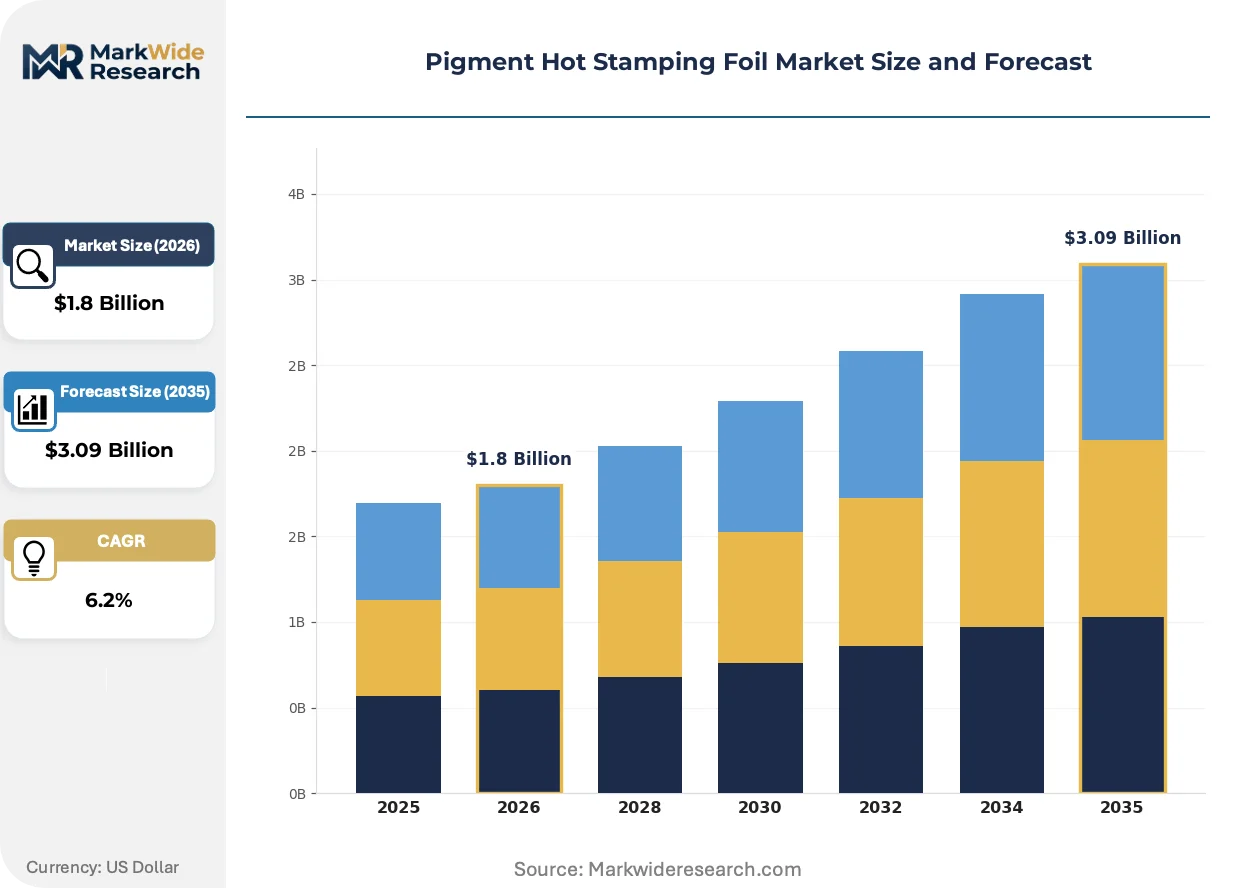
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.09 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polypropylene, PVC, Specialty Films Application: Labeling, Packaging, Decoration, Branding Industry Vertical: Consumer Goods, Automotive Components, Electronics, Textile Delivery Mode: Rolls, Sheets, Custom Sizes, Pre-Cut |
| Companies Covered | KURZ, Crown Roll Leaf Inc., OIKE & Co. Ltd, UNIVACCO Foils Inc., K Laser, Nakai Industrial Co. Ltd, Foilco Limited, Infinity Foils Incorporated, CFC International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pigment Hot Stamping Foil Market Strategic Shifts
Formulation chemistry and substrate engineering are converging to enable thinner, more sustainable pigment transfer systems that maintain opacity at reduced material intensity.
Ultra-thin polyester carrier films below 12 microns are unifying cost reduction with sustainability targets in high-volume label applications. German converters are adopting these gauges for spirits and pharmaceutical runs above 10 million impressions annually. The technology is unifying material efficiency mandates with rotary stamping speed requirements previously thought incompatible with reduced caliper.
REACH Annex XVII restrictions on cadmium and lead pigments are compelling substitution with complex inorganic colorants and high-performance organic alternatives. ECHA classification criteria for pigment intermediates are extending qualification timelines and raising formulation costs. Pharmaceutical and food-contact packaging segments are responding by consolidating supplier bases to favor vertically integrated pigment manufacturers with captive toxicology data.
Brand owner sustainability scorecards are compressing specification cycles as procurement teams rebalance aesthetic requirements against recyclability credentials. Spirits and cosmetics houses are replacing metallized structures with pigment-based mono-material solutions that pass FTIR sortation testing. This pattern is most visible in Nordic markets where retailer take-back schemes and deposit systems create tangible financial incentives for design-for-recycling compliance.
Pigment Hot Stamping Foil Market Segmentation
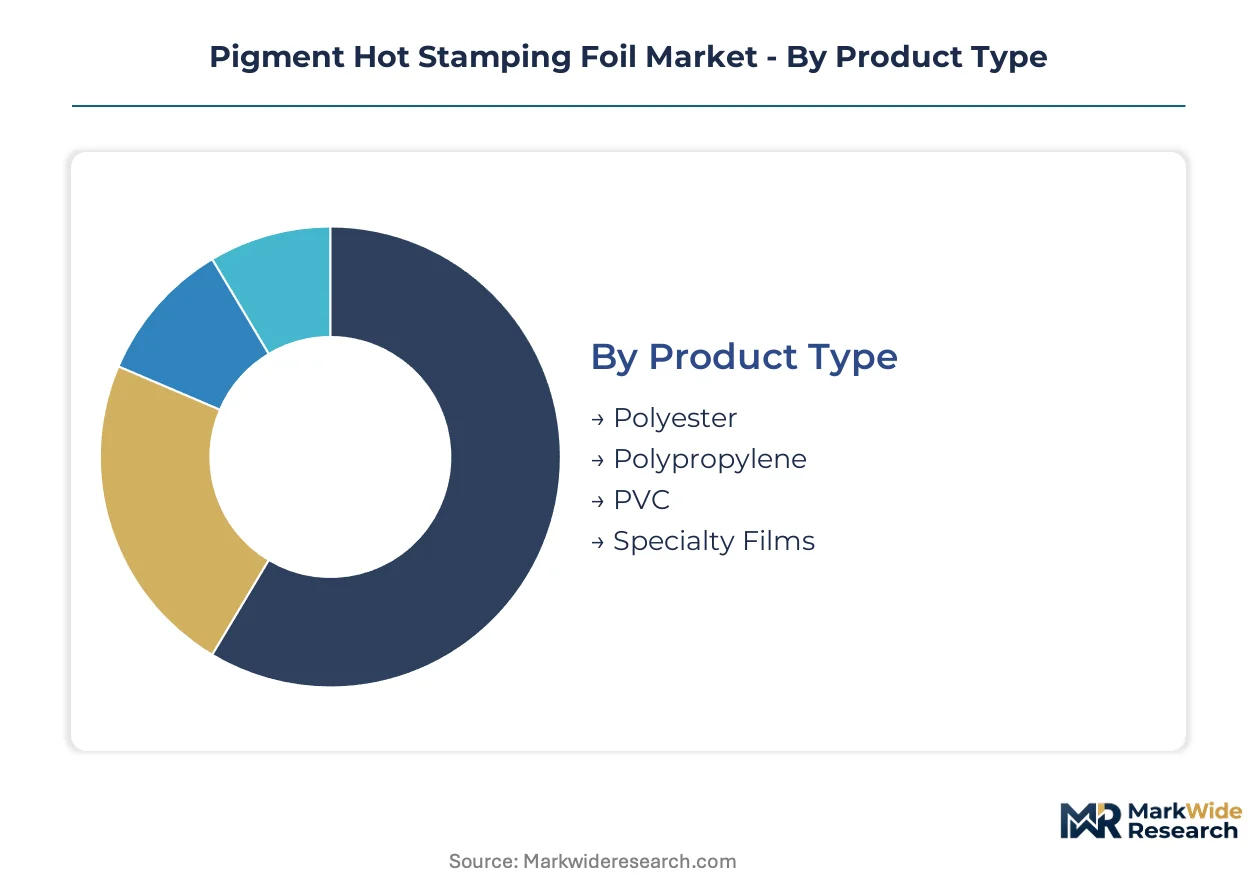
Pigment hot stamping foil selection hinges on substrate compatibility with stamping equipment and end-use durability requirements. Brand owners specify carrier film chemistry and adhesive systems based on thermal profiles and surface energy of target materials.
Product Type:
Converters prioritize dimensional stability during high-speed rotary operations when selecting carrier substrates.
- Polyester:PET films deliver exceptional tensile strength and heat resistance for sustained rotary stamping at 150°C-plus operating temperatures. Spirits and pharmaceutical labeling in Germany and France specify 12-micron gauges for runs exceeding 10 million impressions annually.
- Specialty Films:Security-grade substrates integrate micro-optical elements and covert pigment signatures for anti-counterfeit applications in tobacco and premium spirits. These command disproportionate margin pools despite lower unit volumes.
- Polypropylene:Lower density and cost position PP for price-sensitive decorative applications on flexible packaging.
- PVC:Legacy presence in textile heat-transfer applications where pliability dominates over thermal tolerance.
Volume sits with polyester; growth tilts toward specialty films.
Application:
End-use functional requirements separate permanent decoration from removable or prototype-grade solutions.
- Packaging:Matte pigment finishes on rigid boxes and folding cartons serve luxury cosmetics houses in Italy and France seeking understated sophistication aligned with clean beauty positioning. REACH-compliant mono-material structures pass FTIR sortation testing for Nordic retailer take-back schemes.
- Labeling:Pharmaceutical serialization mandates and spirits tax stamp requirements demand abrasion-resistant permanent bonding on glass and coated paper substrates.
- Decoration:Point-of-sale displays and promotional items utilize shorter-run formats with faster color changeover.
- Branding:Corporate identity applications on electronics and automotive components emphasize batch-to-batch color consistency within Delta E thresholds below 1.0.
Labeling commands current volume; packaging gains share fastest.
Industry Vertical:
Thermal cycling specifications and surface chemistry dictate adhesive formulation choices across end-use sectors.
- Consumer Goods:Premium beauty and spirits packaging in France and Italy drives specification of REACH-compliant pigment architectures.
- Automotive Components:Dashboard and interior trim applications above 120°C thermal cycling require heat-resistant adhesive chemistry from Japanese and German tier suppliers.
- Electronics:Device branding and control panel decoration demand precision registration on engineering plastics.
- Textile:Heat-transfer applications on synthetic fabrics utilize PVC and polypropylene carriers for wash durability.
Consumer goods anchors present volume; automotive opens specification expansion.
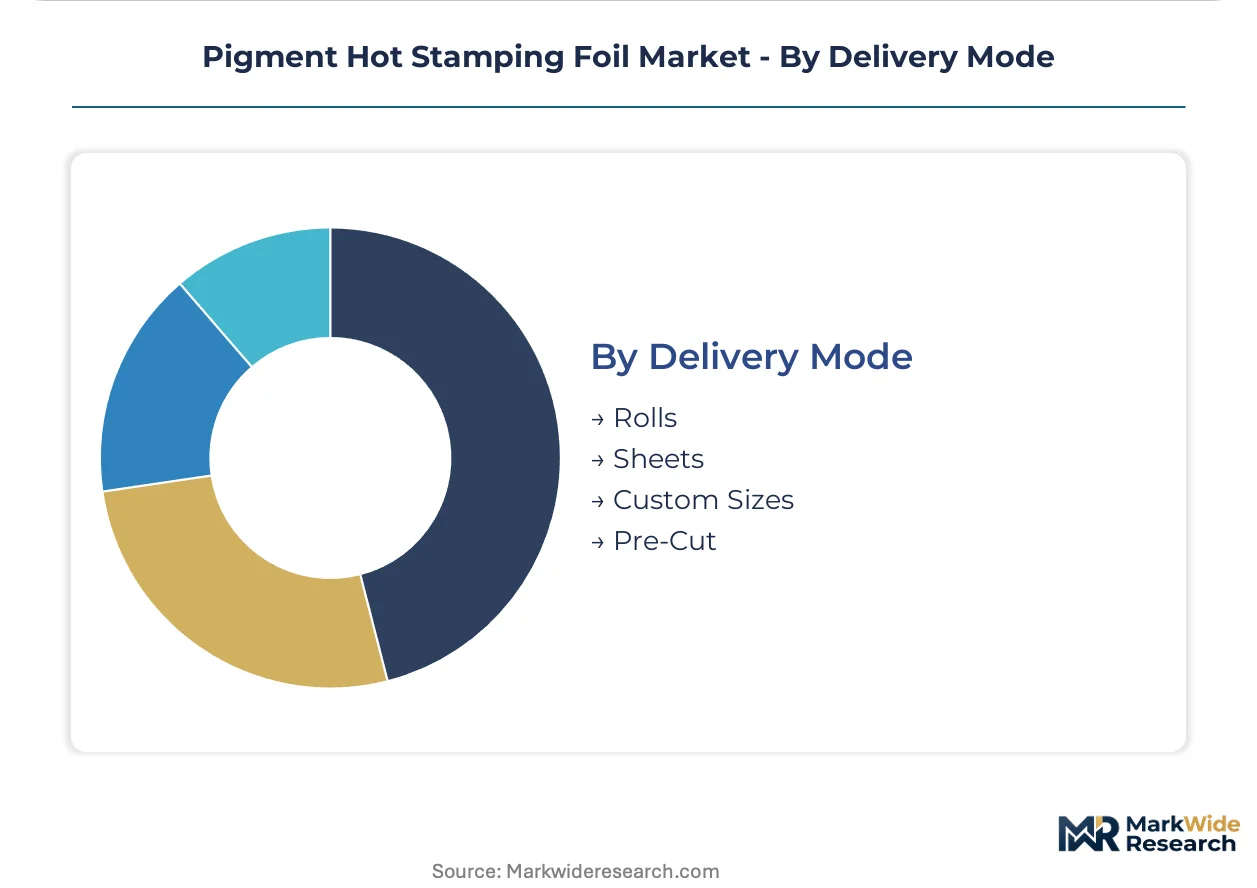
Delivery Mode:
Converter equipment configurations and inventory velocity determine format preferences.
- Rolls:Standard widths serve high-speed rotary stamping lines with minimal changeover downtime.
- Sheets:Flatbed stamping equipment in prototyping and short-run decoration favors cut-sheet feeding.
- Custom Sizes:Dedicated slitting operations accommodate proprietary die dimensions for security applications.
- Pre-Cut:Pre-dimensioned segments reduce make-ready time for specialized branding campaigns.
Rolls dominate production volume; custom sizes capture security segment premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters most densely in Germany where KURZ maintains headquarters and advanced manufacturing infrastructure for rotary stamping equipment. France and Italy drive specification trends through luxury cosmetics packaging. India and the United States represent emerging volume frontiers with distinct regulatory pathways.
Germany
Spirits and pharmaceutical labeling above 10 million impressions annually sustain demand for 12-micron polyester gauges. ECHA substance restrictions under REACH Annex XVII are accelerating reformulation of cadmium and lead pigment alternatives. Stuttgart and Munich host concentrated metallization infrastructure that converters depend on for just-in-time supply.
France
Premium beauty brands specify REACH-compliant matte pigment finishes as they abandon metallic foils for understated sophistication. ANSM pharmaceutical packaging regulations reinforce traceability requirements for serialized labels. The Île-de-France corridor anchors specification design for European export markets.
Italy
Clean beauty positioning drives cosmetic houses toward mono-material pigment structures that pass FTIR sortation testing. EU Green Deal packaging waste directives are compressing specification cycles for recyclable designs. Lombardy-based converters serve spirits and luxury goods exporters across Mediterranean trade routes.
India
CDSCO serialization mandates and pharmaceutical export packaging upgrades are creating first-mover openings for compliant pigment foil suppliers. BIS quality certification requirements extend qualification timelines for imported colorant systems. Maharashtra and Gujarat host expanding slitting and warehousing operations for regional distribution.
United States
FDA indirect food contact regulations constrain adhesive and pigment selections for premium consumer goods packaging. California extended producer responsibility frameworks favor recyclable mono-material structures over metallized laminates. Midwest slitting operations anchor North American distribution networks for high-volume label converters.
Pigment Hot Stamping Foil Market Competitive Environment
Backward integration into pigment synthesis dominates the current landscape as manufacturers seek captive control over REACH-compliant colorant supply. The vendor base stratifies across three tiers: vertically integrated European specialists with in-house toxicology data, Asia-Pacific scale producers serving cost-sensitive decorative applications, and regional slitting operations that manage inventory velocity for just-in-time converters. M&A activity concentrates on pigment intermediate capabilities while capacity expansion targets ultra-thin polyester substrate lines below 12 microns.
Among the integrated specialists, KURZ exemplifies the archetype of upstream control from pigment formulation through reel finishing. Crown Roll Leaf Inc. occupies a position within North American distribution-focused operations. OIKE & Co. Ltd represents heat-resistant formulation capabilities that address automotive thermal cycling specifications above 120°C.
| Leading Market Players |
|---|
| KURZ |
| Crown Roll Leaf Inc. |
| OIKE & Co. Ltd |
| UNIVACCO Foils Inc. |
| K Laser |
| Nakai Industrial Co. Ltd |
| Foilco Limited |
| Infinity Foils Incorporated |
| CFC International |
| Others |
Value Chain & Pricing Dynamics
Specialized color technicians in Stuttgart and Munich command wage premiums that translate directly into pricing-tier spreads across European pigment foil supply. Labor-cost differentials between German formulation specialists and Asian scale producers separate premium REACH-compliant grades from economy decorative tiers.
Pricing Analysis
Volume sits with standardized polyester carriers while margin concentrates in security-grade specialty films with covert pigment signatures. Pricing stratifies across premium REACH-certified tiers, standard industrial grades, and economy decorative foils based on toxicology data depth and batch-to-batch Delta E consistency. Cost compression in standard gauges intensifies as purified terephthalic acid feedstock volatility squeezes converter margins. Pharmaceutical and spirits buyers demonstrate lowest price sensitivity due to brand equity protection requirements, while flexible packaging converters face acute pressure from digital inkjet alternatives.
Supply Chain Analysis
ECHA REACH pre-registration timelines function as certification gates that extend pigment intermediate qualification cycles and consolidate supplier bases toward vertically integrated manufacturers. Supply concentrates in Germany, Japan, and India, with Stuttgart hosting advanced metallization infrastructure, Japanese specialists anchoring heat-resistant adhesive chemistry, and Maharashtra emerging as a regional slitting hub. Raw material dependencies center on purified terephthalic acid for polyester carriers, complex inorganic colorants for heavy metal substitutions, and heat-resistant acrylic adhesives for automotive specifications. Single-source vulnerability around Stuttgart-Munich coating clusters creates geographic concentration risk. Distribution runs through dedicated slitting operations in the US Midwest and regional warehousing networks serving just-in-time label converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pigment hot stamping foil has become a vertical-integration race as REACH compliance costs and qualification timelines favor players with captive pigment synthesis and toxicology data capabilities. Incumbents and challengers alike must secure upstream colorant control or downstream channel anchoring to defend position.
For Market Incumbents: Anticipate ECHA SVHC list expansions by accelerating alternative pigment qualification ahead of sunset dates. Secure backward integration into complex inorganic colorant production or exclusive supply agreements with qualified intermediate suppliers. Defend against digital inkjet substitution by embedding anti-counterfeit micro-optical features that UV-curable systems cannot replicate. Prioritize capacity addition in ultra-thin polyester substrate lines below 12 microns to capture sustainability-driven specification shifts in Nordic and Californian markets. For New Entrants and Emerging Players: Launch via regional slitting and warehousing partnerships in Maharashtra and Gujarat to serve CDSCO-mandated pharmaceutical serialization demand without full formulation infrastructure. Target Indian pharmaceutical export packaging as the most penetrable vertical given BIS certification gaps and first-mover openings for compliant pigment suppliers. Enter through toll-coating arrangements with established European converters to bypass 18-24 month REACH pre-registration barriers while building qualification track records. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-tier specialists with captive toxicology databases given REACH-driven supplier consolidation. Long-term viability hinges on pigment intermediate capabilities rather than downstream slitting assets, as ECHA classification criteria extend formulation pipelines and raise barriers. Target acquisition archetypes include German and Japanese specialists with in-house colorant synthesis and existing automotive thermal cycling qualifications. Watch for CDSCO enforcement acceleration and California extended producer responsibility implementation as inflection signals for regional demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | Captive REACH-compliant colorant supply secures margin control against ECHA restriction timelines. |
| Ultra-Thin Polyester Capacity Expansion | Sub-12 micron gauges unify material efficiency mandates with rotary stamping speed requirements. |
| Heat-Resistant Adhesive R&D Investment | Thermal cycling durability above 120°C opens automotive dashboard and interior trim specifications. |
| Regional Slitting Footprint in India | Maharashtra and Gujarat warehousing addresses CDSCO serialization mandates with localized inventory velocity. |
| Anti-Counterfeit Feature Integration | Covert pigment signatures combined with micro-optical elements capture brand protection premiums in spirits and tobacco. |
Study Parameters
Document review covered ECHA substance restriction databases, FDA indirect food contact guidance, and BIS quality certification frameworks, complemented by interviews with plant managers at European coating facilities, procurement leads at spirits and pharmaceutical label converters, distribution channel partners in North American Midwest networks, and technical R&D directors specializing in heat-resistant adhesive chemistry. Secondary validation drew from customs and trade flow data, SEC filings of listed packaging material suppliers, and industry association reports from European foil and specialty film associations. Bottom-up demand modeling across end-use verticals was cross-referenced with top-down supply-side capacity assessments.
Historical volume trajectories were cross-referenced against panel input from converter procurement heads and OEM specification engineers to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include carrier film chemistry, adhesive thermal performance tier, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from slope analysis of fitted trend lines adjusted for known qualification cycle disruptions and feedstock cost inflection points. Industry-specific forecast inputs incorporated REACH Annex XVII sunset date schedules and CDSCO serialization mandate rollout pacing.
Feedstock cost volatility, ECHA substance restriction acceleration, and digital printing technology substitution are the dominant revision risks that could compress pigment foil demand or accelerate specification shifts. Stakeholders should weight assumptions against their own operating context and qualification pipeline status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Global Printing for Packaging Market
Packaging Printing
North America Thermal Transfer Overprinter Market
Packaging Printing
Global Electrophotographic Printing in Packaging Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Electrophotography Printing for Packaging Market
Packaging Printing
Label Printers Market
Packaging Printing
North America Print Label Market
Packaging Printing
Flexographic Printing Machine Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Qatar Printing and Packaging Market
Packaging Printing
Mexico Print Label Market
Packaging Printing
Flex Banner Market
Packaging Printing
Digital Label Printers Market
Packaging Printing
Laser Coders Market
Packaging Printing
Stack Flexo Printing Press Market