
 Carton Erecting Machinery Market | 2026-2036
Carton Erecting Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Carton Erecting Machinery Market Analytics
Preventive maintenance contracts is hardening into the core revenue stream for carton erecting machinery vendors. Bosch Packaging Technology leverages its global service footprint to lock in multi-year agreements. ProMach Inc. sustains competitiveness through vertical integration into controls engineering. Marchesini Group anchors its position with pharmaceutical-grade validation protocols.
Carton erecting machinery forms, folds, and seals flat carton blanks into three-dimensional containers at speeds reaching 500 units per minute, serving primary and secondary packaging operations across consumer goods manufacturing. Automatic machine types command the largest installed base due to throughput requirements in high-volume beverage bottling lines. Robotic configurations represent the fastest-expanding category as collaborative arms reduce changeover times for personal care brands running multiple SKUs. Corrugated material handling generates concentrated margin pools because heavy-duty erecting systems require reinforced framing and precision tension control.
CE marking under the EU Machinery Directive governs safety interlocks and emergency stop architectures for equipment sold across Europe. FDA validation requirements for pharmaceutical packaging lines in the United States elevate documentation burdens and extend qualification timelines for erecting machinery suppliers. ISO 9001 quality management certification functions as a baseline qualifier for tier-one food manufacturer procurement teams. Stakeholders must weigh total cost of ownership against throughput flexibility when specifying erecting systems for evolving e-commerce fulfillment formats.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing changeover windows for carton erecting systems as brands scramble to meet material recovery targets without sacrificing line throughput. Equipment suppliers now face simultaneous pressure for speed flexibility and circularity compliance.
Growth Catalysts
- Food and beverage throughput mandates:Bottling lines in Germany and the Netherlands require erecting speeds above 400 units per minute to match filler output, pulling demand for servo-driven folding architectures.
- REACH chemical compliance:Adhesives and coatings used in carton sealing must meet restricted substance lists, forcing machinery OEMs to validate cold-seal and mechanical-lock alternatives.
- Pharmaceutical serialization:Track-and-trace requirements under the EU Falsified Medicines Directive necessitate integrated carton printing and verification stations on erecting lines.
Market Restraints
- Steel and aluminum input volatility:Framing and tension-roll materials face commodity price swings that erode fixed-price contract margins for machinery builders.
- German supplier concentration:Precision gearbox and servo motor vendors cluster around Stuttgart, creating single-source vulnerability for tier-two OEMs outside the region.
- Corrugated substrate weight limits:Heavy-duty erecting systems for bulk liquid packaging cannot reliably process below 400 gsm board without jam rates spiking.
Strategic Opportunities
- Polish manufacturing expansion:Greenfield beverage plants near Wrocław and Poznań lack established local machinery service networks, opening territory for preventive maintenance contract capture.
- Robotic-cobot convergence:Collaborative arms paired with machine vision enable SKU-mix flexibility for personal care contract packagers running 50-plus format variants.
- CSRD disclosure requirements:The EU Corporate Sustainability Reporting Directive creates audit-grade documentation demand that machinery vendors can productize as compliance-as-a-service modules.
Industry Challenges
- Mechatronics technician scarcity:Servo tuning and HMI programming skills concentrate among aging workforces in Bavaria and Baden-Württemberg, constraining field service scaling.
- CE-MDR dual certification timelines:Pharmaceutical erecting systems must satisfy both Machinery Directive safety audits and Medical Device Regulation quality system reviews, extending qualification by four to six months.
- Legacy PLC integration friction:Brownfield packaging halls running Siemens S7-300 architectures resist Ethernet-IP retrofit without complete control cabinet replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carton Erecting Machinery Market |
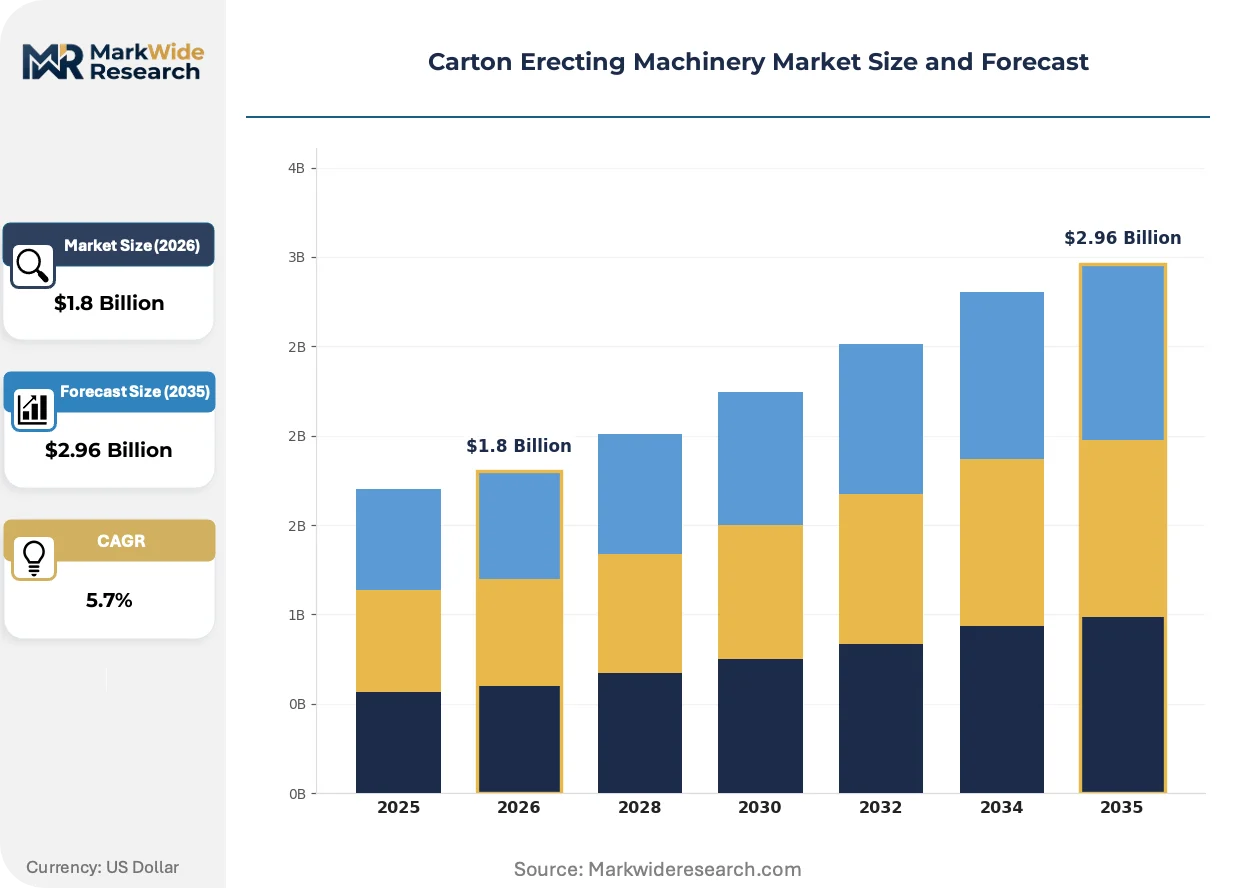
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Automatic, Semi-Automatic, Manual, Robotic End User: Food & Beverage, Pharmaceuticals, Personal Care, Electronics Packaging Material: Cardboard, Corrugated, Paperboard, Fiberboard Technology: Mechanical, Pneumatic, Hydraulic, Electrical |
| Companies Covered | Bosch Packaging Technology, ProMach Inc., Marchesini Group, Wexxar Bel, Combi Packaging Systems, KHS GmbH, Packsize International LLC, BluePrint Automation (BPA), HARTNESS International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carton Erecting Machinery Market Evolving Landscape
Servo-electric motion control is displacing pneumatic actuation across folding and sealing stations, driven by energy efficiency mandates and precision requirements for thin-board handling.
Brushless servo motors with integrated drives are electrifying the secondary packaging layer. Personal care manufacturers in the Netherlands and Belgium adopt these systems to eliminate compressed-air infrastructure and cut changeover times from forty minutes to under eight. The technology is electrifying competitive positioning for mid-cap OEMs that lack pneumatic service networks.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in climate-controlled glue melters and adhesive conditioning units. Machinery suppliers must redesign thermal management around CO2 or hydrocarbon alternatives, adding engineering cost but opening differentiation for early movers. Pharmaceutical packaging lines in Ireland and Denmark face the tightest compliance deadlines.
Subscription-based performance contracts are displacing traditional equipment purchase models for mid-volume food manufacturers. Contract packagers in northern Italy now pay per thousand cartons erected rather than capitalizing machinery, transferring uptime risk to vendors. This shift concentrates most visibly among private-label snack brands with seasonal demand spikes.
Carton Erecting Machinery Market Segmentation
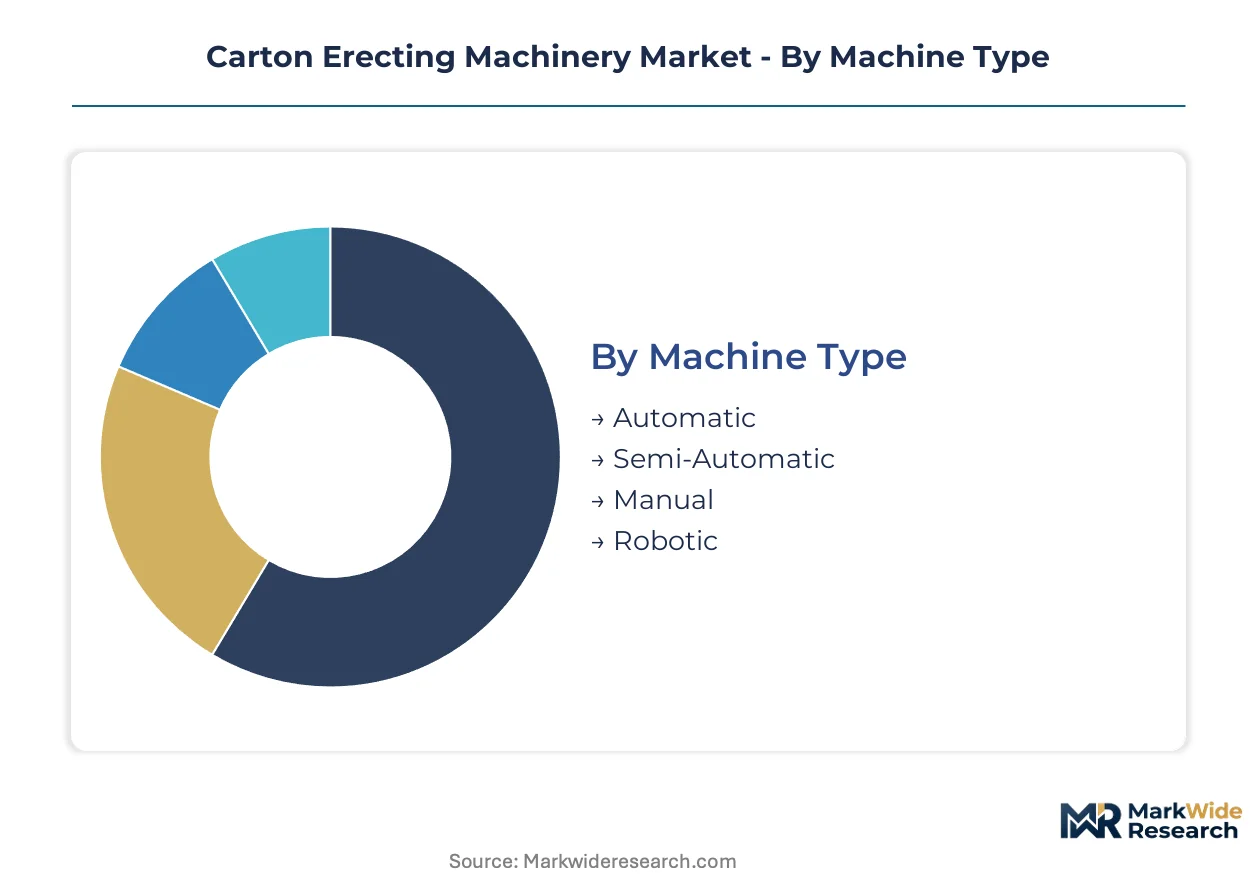
Carton erecting machinery segments fragment sharply between high-throughput standalone systems and modular units embedded within integrated packaging lines. Equipment buyers weigh capital intensity against SKU flexibility when mapping segment selection to operational requirements.
Machine Type:
Integration depth varies dramatically across this category, with standalone systems dominating beverage bottling halls while robotic configurations embed into flexible contract packaging operations.
- Automatic:Servo-driven architectures process 400-plus units per minute with minimal operator intervention. German beverage bottlers in Bavaria and North Rhine-Westphalia anchor demand as filler line speeds mandate synchronized erecting throughput.
- Robotic:Collaborative arms with machine vision enable sub-ten-minute changeovers for personal care brands running 50-plus SKUs. Dutch and Belgian contract packagers adopt these systems fastest as lot sizes shrink and format variety expands.
- Semi-Automatic:Hybrid configurations suit mid-volume food manufacturers balancing labor costs against capital constraints.
- Manual:Bench-top units serve micro-breweries and artisan food producers with output below 50 units per minute.
Automatic equipment leads volumes today; robotic configurations are gaining share fastest.
End User:
Cost tier stratification shapes procurement patterns, with pharmaceutical-grade validation commanding premium pricing against standard food-industry specifications.
- Food & Beverage:High-volume bottling and snack packaging lines demand 24/7 reliability with mean time between failures exceeding 8,000 hours. CE marking compliance under the EU Machinery Directive is non-negotiable for European dairy and brewery installations.
- Pharmaceuticals:FDA validation requirements and EU Falsified Medicines Directive track-and-trace mandates elevate documentation burdens. Irish and Danish packaging lines face the tightest compliance deadlines for serialization-integrated erecting systems.
- Personal Care:Frequent format changes for seasonal SKU rotations favor quick-change tooling and recipe-driven HMI interfaces.
- Electronics:ESD-sensitive handling requirements and compact footprint constraints distinguish this segment from bulk consumer goods applications.
Food and beverage absorbs the largest equipment volumes; pharmaceuticals deliver the steepest margin premiums.
Packaging Material:
Application-specific material properties dictate machine architecture, from lightweight board handling to heavy-duty structural packaging.
- Corrugated:Double-wall and triple-wall boards above 400 gsm require reinforced framing and precision tension control for bulk liquid packaging. German OEMs cluster specialized engineering expertise around Stuttgart for these heavy-duty systems.
- Cardboard:Folding carton stock between 200-350 gsm serves pharmaceutical and cosmetic primary packaging with tight dimensional tolerances.
- Paperboard:Bleached sulfate grades dominate premium food packaging with high-quality print surfaces.
- Fiberboard:Recycled-content structural boards face growing adoption under EU Packaging and Packaging Waste Regulation recovery targets.
Corrugated commands the deepest installed base; fiberboard is climbing the fastest on circularity mandates.
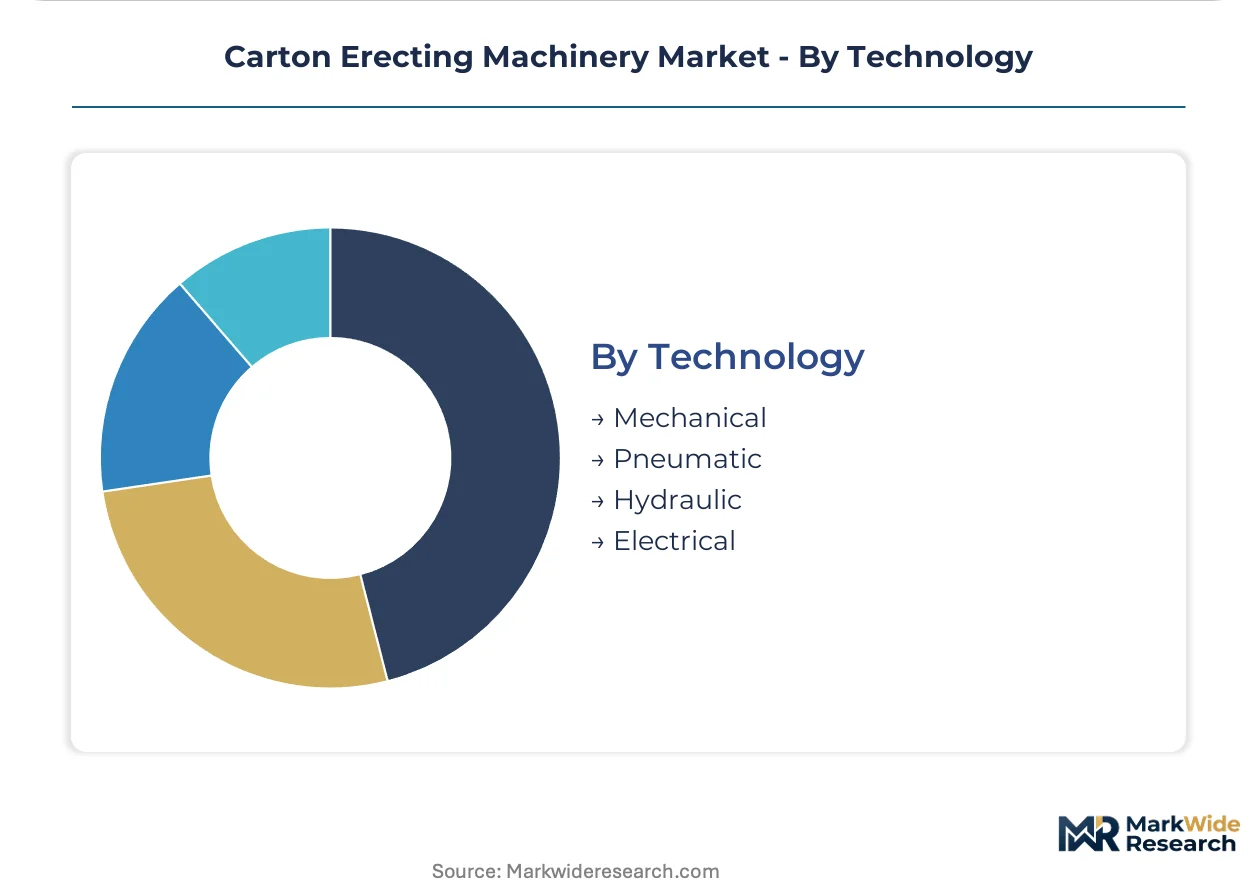
Technology:
Supply concentration for precision motion components is accelerating technology migration decisions across machinery OEMs.
- Electrical:Brushless servo motors with integrated drives eliminate compressed-air infrastructure and cut energy consumption by 30-40 percent. Netherlands-based personal care manufacturers lead adoption to reduce changeover windows from forty minutes to under eight.
- Pneumatic:Legacy installations remain prevalent in brownfield packaging halls running established compressed-air networks.
- Mechanical:Cam-driven architectures persist in high-speed beverage applications where simplicity trumps flexibility.
- Hydraulic:Heavy-tonnage forming operations for industrial bulk packaging retain niche deployment.
Electrical systems are displacing legacy alternatives fastest; mechanical architectures retain volume leadership in mature beverage markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the deepest installed base of carton erecting systems, while the Netherlands leads adoption velocity for robotic configurations serving contract packaging networks.
Germany
Bavarian beverage bottlers and North Rhine-Westphalian dairy processors drive demand for servo-driven architectures exceeding 400 units per minute. CE marking under the EU Machinery Directive governs safety interlocks for all European-bound equipment. Stuttgart and Düsseldorf host dense clusters of precision gearbox and servo motor vendors, creating engineering ecosystems that tier-two OEMs outside the region struggle to replicate.
Netherlands
Personal care contract packagers in Randstad corridors adopt collaborative robotic arms to compress changeover windows below eight minutes. The EU F-Gas Regulation forces thermal management redesigns for adhesive conditioning units, with Dutch installations facing accelerated compliance timelines. Eindhoven-based automation integrators specialize in machine vision integration for SKU-mix flexibility.
Poland
Greenfield beverage plants near Wrocław and Poznań lack established local machinery service networks, creating territory capture opportunities for preventive maintenance providers. REACH chemical compliance restricts adhesives and coatings used in carton sealing, validating cold-seal alternatives. The country's central location positions it as a distribution hub for eastern European packaging operations.
United States
Pharmaceutical packaging lines in New Jersey and North Carolina face FDA validation requirements that extend qualification timelines for erecting machinery suppliers. Serialization mandates under track-and-trace regulations necessitate integrated carton printing and verification stations. Midwestern brownfield packaging halls running legacy PLC architectures resist Ethernet-IP retrofit without complete control cabinet replacement.
Italy
Northern Italian contract packagers pioneer subscription-based performance contracts, paying per thousand cartons erected rather than capitalizing machinery. The EU Corporate Sustainability Reporting Directive generates audit-grade documentation demand that machinery vendors productize as compliance-as-a-service modules. Lombardy-based food manufacturers anchor demand for mid-volume hybrid configurations balancing labor costs against capital constraints.
Carton Erecting Machinery Market Competitive Landscape
Top-tier vendors anchor precision-engineered premium tiers, while mid-cap specialists occupy flexibility-focused segments. The vendor base stratifies across three functional layers: integrated packaging line builders, standalone machinery specialists, and robotic automation integrators. Strategic archetypes include servo-electric technology leaders, pharmaceutical-grade validation specialists, and subscription-model pioneers. Competitive moves concentrate on backward integration into controls engineering and geographic expansion through field service network densification.
Within the pharmaceutical-grade tier, Marchesini Group exemplifies validation-intensive positioning, while Bosch Packaging Technology anchors global service footprint strategies. ProMach Inc. occupies the vertical integration archetype through in-house controls engineering capabilities. These three entities represent distinct competitive vectors: regulatory documentation depth, multi-year preventive maintenance lock-in, and upstream component supply control.
| Leading Market Players |
|---|
| Bosch Packaging Technology |
| ProMach Inc. |
| Marchesini Group |
| Wexxar Bel |
| Combi Packaging Systems |
| KHS GmbH |
| Packsize International LLC |
| BluePrint Automation (BPA) |
| HARTNESS International |
| Others |
Value Network & Pricing Analysis
EU Packaging and Packaging Waste Regulation material recovery targets gate qualified supply access and premium-tier pricing power for carton erecting machinery vendors serving circularity-compliant packaging lines.
Pricing Analysis
Capacity additions in Poland are reshaping price floors for mid-tier automatic systems as greenfield beverage plants near Wrocław and Poznań absorb volume. Pricing stratifies across pharmaceutical-grade validation tiers, CE-marked food-industry specifications, and standard packaging configurations. Cost compression in the standard tier is intensifying because steel and aluminum input volatility erodes fixed-price contract margins. Contract packagers running seasonal SKU rotations exhibit highest price sensitivity; pharmaceutical serialization-integrated lines show lowest.
Supply Chain Analysis
Precision gearbox and servo motor supply rests on German engineering clusters around Stuttgart and Düsseldorf, with secondary sourcing from Italian motion control specialists. Steel framing, brushless servo motors, and machine vision components constitute critical input dependencies. Single-source vulnerability concentrates around Baden-Württemberg precision component vendors. Distribution runs through OEM-direct sales for large beverage bottlers and specialized automation integrators serving contract packaging networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Falsified Medicines Directive functions as a regulatory compounder, driving demand for serialization-integrated erecting systems across pharmaceutical packaging corridors in Ireland and Denmark.
For Market Incumbents: Cement multi-year preventive maintenance lock-in across Polish greenfield installations before local service networks mature. Deepen backward integration into servo drive engineering to offset precision component supply concentration in Stuttgart. Counter robotic-cobot convergence threats from Dutch automation integrators through accelerated machine vision capability acquisition.
For New Entrants and Emerging Players: Begin with subscription-based performance contracts for northern Italian contract packagers seeking to transfer uptime risk. The most penetrable segment comprises mid-volume food manufacturers balancing capital constraints against seasonal demand spikes. Lead with per-thousand-carton pricing models rather than equipment capitalization to bypass incumbent installed base advantages.
For Investors and Strategic Acquirers: Roll-up economics work for pharmaceutical-grade validation specialists because CE-MDR dual certification timelines extend qualification windows and deepen customer switching costs. Five-to-ten year viability hinges on regulatory documentation depth rather than hardware differentiation alone. Watch F-Gas Regulation thermal management redesign adoption rates as inflection indicator for adhesive conditioning unit replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controls Engineering | Captive servo drive production insulates margin structures from Stuttgart supplier concentration. |
| Preventive Maintenance Network Expansion | Polish greenfield territory capture locks in recurring revenue before local competitors establish presence. |
| Robotic-Cobot Convergence Development | Collaborative arm integration with machine vision addresses Dutch personal care SKU-mix flexibility requirements. |
| Cold-Seal Technology Validation | REACH-compliant adhesive alternatives open pharmaceutical and food packaging lines to restricted substance mandates. |
| Compliance-as-a-Service Module Launch | CSRD audit-grade documentation productization captures Italian sustainability reporting demand. |
Research Methodology
Multiple input streams — machinery OEM engineering directors, beverage plant maintenance managers, pharmaceutical packaging line qualification specialists, and contract packager operations heads — were reconciled against secondary validation from EU Machinery Directive technical documentation, FDA 483 inspection observations, REACH substance restriction databases, and customs trade flow records. Bottom-up equipment shipment tallies and top-down packaging line investment surveys were triangulated to anchor volume estimates.
Historical capacity utilization patterns were cross-referenced against expert panel inputs on format changeover compression trends. Segmentation dimensions modeled span machine type integration depth, end-user validation tier, packaging material gsm specifications, and technology actuation architecture. CAGRs were derived from slope consensus across projection scenarios. Industry-specific forecast inputs include servo-electric displacement rates and F-Gas Regulation compliance deadline clustering.
Several conditions sit outside the modeled scope, including speculative raw material price trajectories and unannounced regulatory amendments. Forecasts reflect documented assumptions about technician workforce availability and brownfield PLC retrofit friction. A small set of named triggers warrants ongoing watch: German precision component supply disruptions, Polish service network maturation velocity, and pharmaceutical serialization mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
Packaging Conveyors Market
Packaging Machinery
Labeling Machines Market
Packaging Machinery
Global Filling Machines Market
Packaging Machinery
Toilet Roll Converting Lines Market
Packaging Machinery
Shrink Wrapping Machines Market
Packaging Machinery
Cup Fill and Seal Machine Market
Packaging Machinery
Blow Fill Seal (BFS) Technology Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
Barcode Labeller Machine Market
Packaging Machinery
Foil Embossing Machine Market
Packaging Machinery
Automatic Auger Fillers Market
Packaging Machinery
LAMEA Printing Machinery Market
Packaging Machinery
Bag in Box Packaging Machine Market
Packaging Machinery
Paper Embossing Machine Market