
 Global Pre Print Flexo Press Market | 2026-2036
Global Pre Print Flexo Press Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pre Print Flexo Press Market Foresight
Buyer concentration across packaging converters is broadening as mid-tier flexible packaging houses in India, Vietnam, and Poland enter the pre-print flexo segment for the first time. Bobst leverages its integrated die-cutting and flexo platform to anchor premium corrugated pre-print lines in Western Europe. Mark Andy competes aggressively in narrow-web label applications through its dedicated flexo press architecture. Gallus sustains technology leadership in hybrid flexo-digital configurations for pharmaceutical and security label converters.
A pre print flexo press is a web-fed rotary printing system employing flexible photopolymer plates mounted on cylinders, typically operating at line speeds between 300 and 600 meters per minute with repeat lengths ranging from 250 mm to 1,600 mm depending on gear specification. The equipment executes high-volume graphic reproduction on corrugated board, flexible films, and paper substrates prior to downstream converting, serving brand owners who require cost-efficient, food-contact-compliant packaging with shorter lead times than gravure alternatives. Central impression presses occupy the highest margin pool in flexible packaging due to their superior registration accuracy for thin-gauge films. Water-based flexo technology leads volume shipments in corrugated applications where recyclability mandates dominate buyer specifications. UV flexo segments command premium positioning in label and shrink sleeve work where substrate versatility and instant curing deliver measurable throughput advantages.
EPA regulations on volatile organic compound emissions from printing operations in the United States restrict solvent flexo configurations and redirect capital toward water-based and UV-cured press platforms. REACH compliance across the European Union imposes substance restrictions on photoinitiators and ink constituents, compelling OEMs to certify press-ink-substrate combinations for food contact migration limits. China's MEE enforces wastewater and air emission standards that elevate total cost of ownership for solvent-dependent lines. Stakeholders must monitor evolving Extended Producer Responsibility frameworks in Germany, France, and California, as these jurisdictions increasingly tie packaging recyclability to the printing process itself.
Market Dynamics
Equipment replacement cycles across corrugated and flexible packaging converters are compressing as EU REACH substance restrictions and China's MEE air emission standards force solvent-dependent gravure lines into early obsolescence. This regulatory pressure is redirecting capital toward water-based and UV-cured flexo configurations at unprecedented velocity.
Growth Catalysts
- EU REACH compliance deadlines:Photoinitiator and ink constituent restrictions are compelling food-contact packaging converters in Germany and Italy to certify press-ink-substrate combinations, accelerating equipment refresh timelines.
- Flexible packaging demand rotation:Mid-tier converters in India and Vietnam are entering pre-print flexo for the first time as brand owners demand shorter lead times than gravure alternatives.
- Central impression press architecture:Superior registration accuracy for thin-gauge films is displacing stack-type configurations in high-margin flexible packaging applications.
Market Restraints
- Photopolymer plate cost volatility:Raw material concentration among Asian suppliers creates input price instability for converters operating narrow-web label lines.
- Technical speed-ceiling limitations:Water-based ink drying constraints cap line speeds below UV-cured alternatives, restricting throughput in corrugated board applications.
- Substitution threat from digital hybrid:Pharmaceutical and security label converters are piloting Gallus-style flexo-digital configurations that reduce run-length thresholds for pure flexo economics.
Strategic Opportunities
- Poland converter base expansion:Underpenetrated mid-web flexible packaging houses are acquiring first-generation central impression presses as EU funding flows into packaging modernization.
- Extended Producer Responsibility tailwinds:Germany and France are tying packaging recyclability mandates directly to printing process certification, creating preference for water-based flexo workflows.
- UV LED curing convergence:Instant curing technology is integrating with narrow-web architectures to enable substrate versatility in shrink sleeve applications previously dominated by solvent gravure.
Industry Challenges
- Flexographic operator skill scarcity:Registration control and anilox maintenance expertise concentrates among aging workforces in the United States and Italy, constraining capacity utilization at new installations.
- Press-ink-substrate certification timelines:FDA food contact migration testing and EFSA compliance documentation extend commissioning cycles by four to eight months for export-oriented converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pre Print Flexo Press Market |
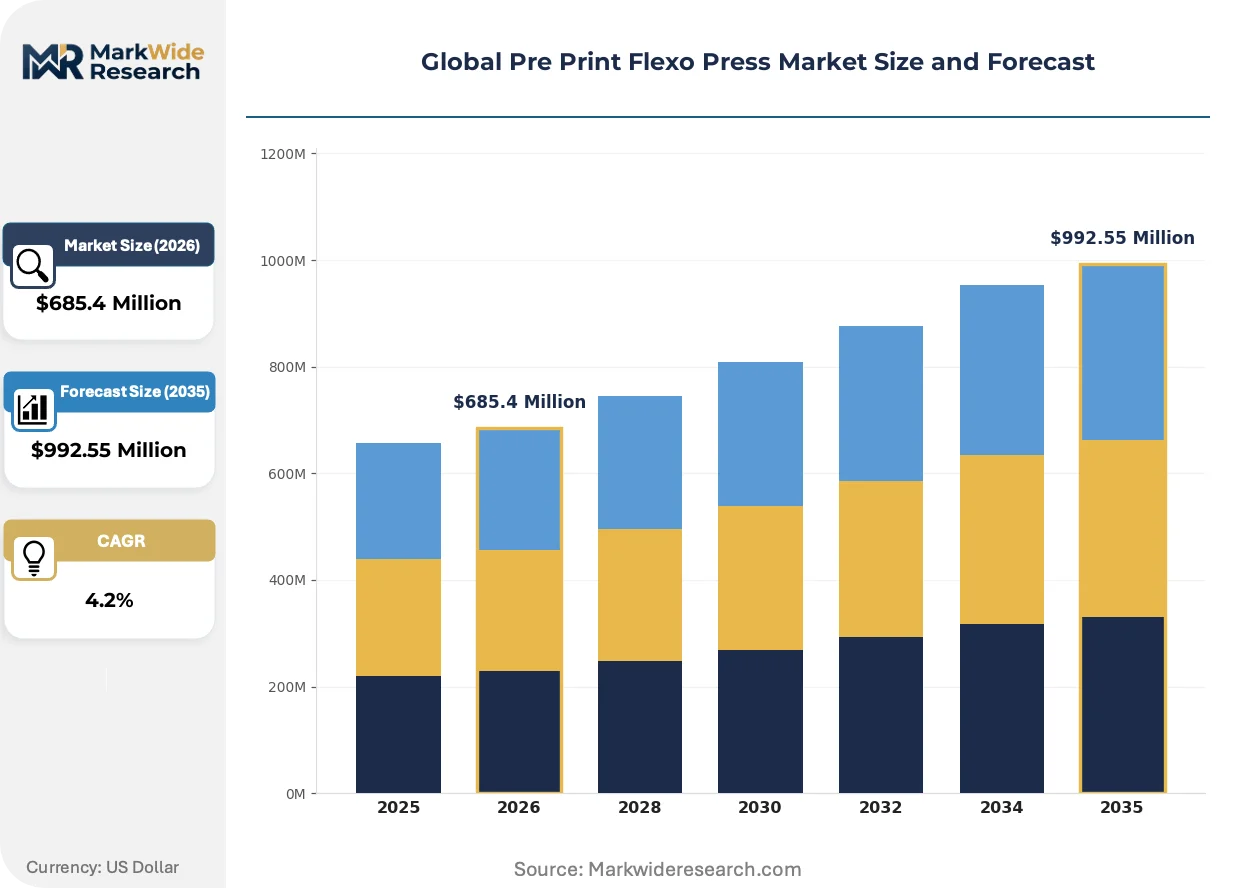
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stack Type, Central Impression, Inline Type, Stack Type Clamshell, Turret Type Technology: UV Flexo, Solvent Flexo, Water-Based Flexo, Digital Flexo, LED Flexo Application: Flexible Packaging, Label Printing, Corrugated Carton, Paper Bags, Shrink Sleeves End User: Packaging Manufacturers, Printing Houses, Specialty Converters, Label Producers |
| Companies Covered | Bobst, Mark Andy, Gallus, MPS Systems, Nilpeter, OMET, Comexi Group, Uteco Converting, Koenig & Bauer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pre Print Flexo Press Market Shifts & Advancements
Automation layers and closed-loop color management are compressing make-ready times while regulatory substance restrictions are rewriting equipment specification sheets. These forces are converging to redefine competitive differentiation among press OEMs.
Artificial vision-based print inspection is integrating with inline densitometry to enable autonomous color correction during production runs. Flexible packaging converters in Germany are deploying these systems at mid-web installations to reduce waste rates. The technology is integrating quality assurance directly into the production workflow, eliminating offline sampling delays.
China's MEE wastewater discharge standards are forcing solvent flexo operators to install thermal oxidizers or migrate to water-based platforms. Corrugated pre-print facilities in Shandong and Guangdong provinces face the steepest compliance costs. The regulation is compressing the viable equipment configuration set, privileging OEMs with certified water-based process packages.
Converter procurement of press capacity is fragmenting across equipment-as-service models and performance-guarantee contracts. Mid-tier buyers in India are unbundling after-sales support from capital acquisition, purchasing maintenance separately through third-party specialists. This behavioral shift is visible most acutely in Maharashtra and Gujarat, where converter clusters lack in-house technical depth.
Global Pre Print Flexo Press Market Segmentation
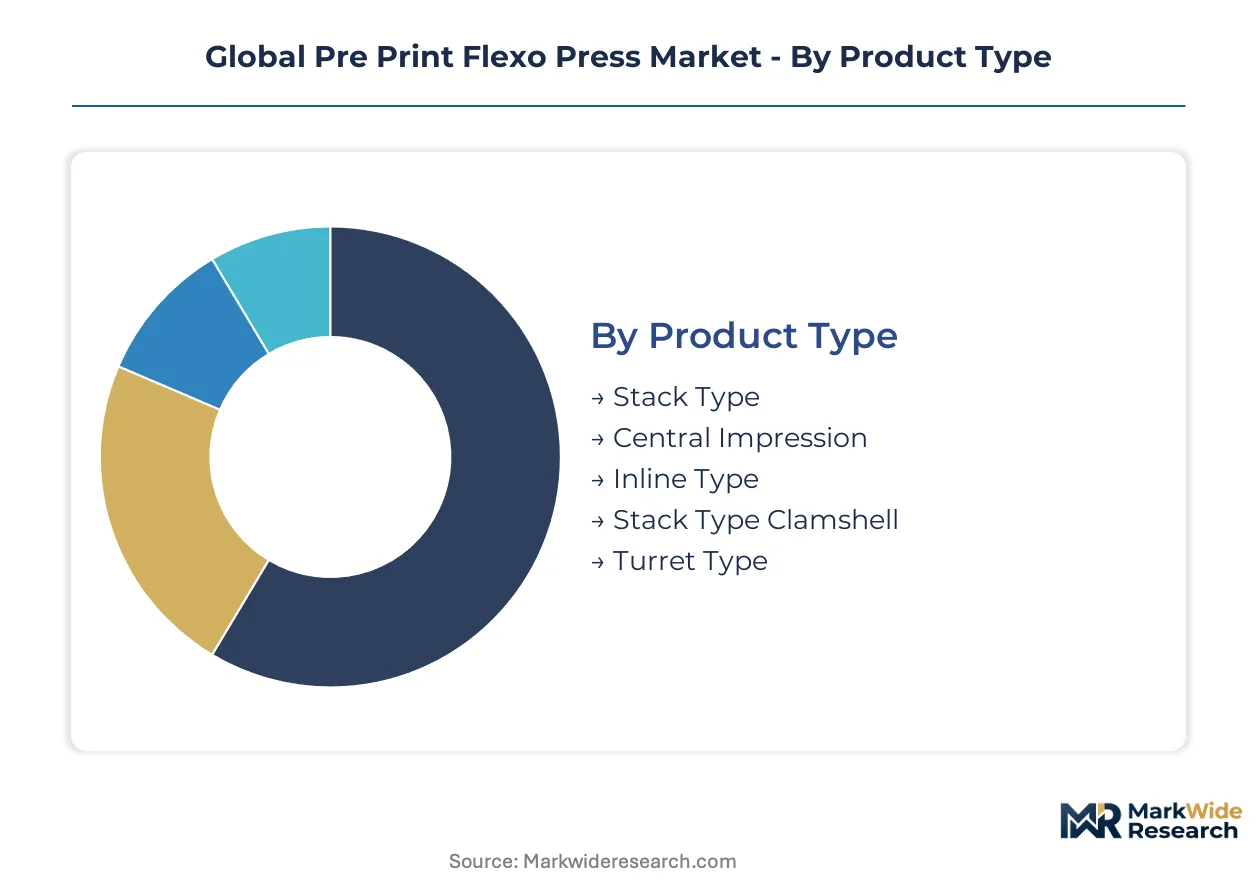
Pre-print flexo press procurement varies sharply by converter scale, substrate specialization, and regulatory exposure. Equipment specifications diverge across corrugated board, flexible film, and label applications, with ink curing technology and press architecture serving as primary selection criteria.
Product Type:
Converter margin profiles and registration tolerances dictate press architecture selection, with high-volume flexible packaging houses prioritizing precision over entry-level corrugated operations.
- Central Impression:Cylindrical drum configuration maintains superior registration accuracy across thin-gauge films through synchronized plate cylinder rotation. German and Italian flexible packaging converters deploy these systems for food-contact laminate production where micron-level tolerance prevents seal failure. EU REACH compliance deadlines accelerate replacement of aging stack-type lines in these markets.
- Stack Type:Vertical tower arrangement of independent print units enables quick color sequence changes and compact floor footprint. Corrugated pre-print facilities in India's Maharashtra and Gujarat states favor this architecture for short-run kraft liner work where capital constraints limit initial outlay. Water-based ink drying requirements cap effective line speeds versus central impression alternatives.
- Inline Type:Horizontal unit arrangement suits integration with downstream die-cutting and folder-gluer systems for finished carton production.
- Stack Type Clamshell:Hinged upper frame design permits rapid plate cylinder access for narrow-web label converters with frequent job changeovers.
- Turret Type:Dual unwind/rewind stations enable non-stop roll changes for continuous high-volume flexible packaging operations.
Central Impression leads volumes today; Stack Type is gaining share fastest among first-time buyers in emerging converter markets.
Technology:
Emission regulations and substrate versatility requirements are fragmenting technology adoption curves across geographic markets.
- Water-Based Flexo:Aqueous ink systems with thermal or infrared drying dominate corrugated applications where recyclability mandates from Germany's Extended Producer Responsibility framework and California's packaging laws drive specification. Shandong and Guangdong province converters face China's MEE wastewater discharge standards that privilege these configurations. Drying energy consumption and speed ceilings remain operational constraints versus UV alternatives.
- UV Flexo:Photoinitiator-cured ink chemistry enables instant polymerization and superior substrate adhesion for shrink sleeve and metallized film applications. Label converters in the United States deploy these systems for pharmaceutical serialization work where FDA food contact migration limits apply. REACH photoinitiator restrictions are compressing formulation flexibility in EU markets.
- Solvent Flexo:Volatile organic compound-based systems retreat to specialized applications as EPA regulations and China's air emission standards elevate compliance costs.
- LED Flexo:Narrow-wavelength UV curing reduces energy consumption and heat load compared to conventional mercury arc systems.
- Digital Flexo:Hybrid configurations combining fixed imaging with rotary flexo units target variable data and short-run security label segments.
Water-Based Flexo commands the largest installed base; UV Flexo climbs the fastest in premium label and shrink sleeve applications.
Application:
End-use shelf-life requirements and graphic complexity determine press specification, with food-contact packaging imposing the strictest compliance burdens.
- Flexible Packaging:Multi-layer film and pouch printing for snack, pet food, and pharmaceutical applications requires central impression architecture with solvent-free or water-based workflows. German converter clusters around Munich and Hamburg lead equipment refresh cycles as EFSA migration limits tighten. Down-gauging trends in polyethylene films demand enhanced registration systems.
- Corrugated Carton:Pre-print linerboard for retail-ready secondary packaging favors stack-type presses with water-based ink sets. Poland's emerging converter base is acquiring first-generation systems as EU cohesion funding flows into packaging modernization. E-commerce shipment volume sustains demand for branded shipping containers.
- Label Printing:Pressure-sensitive and wet-glue label production spans narrow-web to mid-web press formats.
- Shrink Sleeves:PETG and OPS film printing for contoured container decoration requires UV curing for heat-sensitive substrates.
- Paper Bags:Kraft and white-top liner printing for retail and food service packaging operates at lower complexity thresholds.
Flexible Packaging dominates revenue contribution; Corrugated Carton is expanding most quickly among mid-tier converters entering pre-print for the first time.
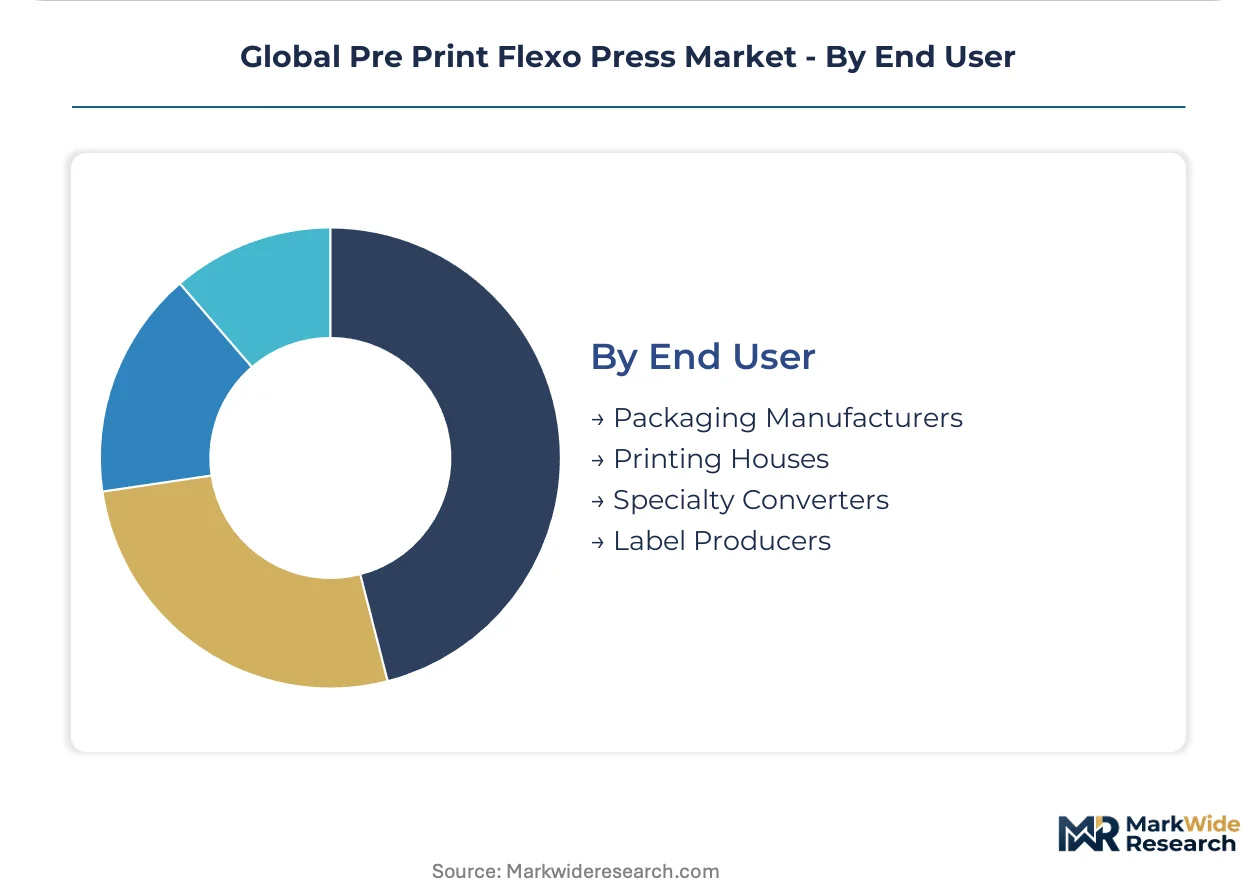
End User:
Technical sophistication and in-house maintenance capability separate integrated packaging manufacturers from outsourced print service providers.
- Packaging Manufacturers:Vertically integrated converters with captive printing operations specify high-availability presses with automated make-ready systems. Italian flexible packaging houses around Bologna maintain dedicated technical teams for anilox maintenance and color management. These buyers prioritize total cost of ownership over initial capital outlay.
- Printing Houses:Commercial print service providers entering packaging diversification lack substrate-specific expertise and demand extensive OEM training packages. India's mid-tier flexible packaging entrants in Vietnam and Poland exhibit this profile, unbundling after-sales support from equipment procurement.
- Specialty Converters:Niche players in security printing, pharmaceutical labeling, and tamper-evident packaging require hybrid flexo-digital configurations.
- Label Producers:Narrow-web specialists serving beverage and personal care brands concentrate in regional clusters around Chicago, São Paulo, and Jakarta.
Packaging Manufacturers represent the largest equipment procurement segment; Printing Houses are ascending fastest as brand owners outsource pre-print conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and India present contrasting demand profiles, with German converters replacing aging gravure infrastructure under REACH deadlines while Indian mid-tier packaging houses acquire first-generation flexo systems for corrugated pre-print entry.
United States
EPA volatile organic compound restrictions on solvent flexo configurations redirect capital toward water-based and UV-cured press platforms. FDA food contact migration testing extends commissioning cycles by four to eight months for export-oriented converters. Chicago-area narrow-web label clusters concentrate pharmaceutical serialization capacity serving domestic brand owners.
Germany
EFSA migration limits tighten certification requirements for food-contact laminate producers around Munich and Hamburg. Extended Producer Responsibility frameworks tie packaging recyclability mandates directly to printing process certification. Bologna-corridor Italian flexible packaging houses maintain technical teams for anilox maintenance and color management sophistication.
China
MEE wastewater discharge standards and air emission regulations compress viable equipment configurations for Shandong and Guangdong province corrugated facilities. Dual carbon goals accelerate thermal oxidizer installation or platform migration decisions. Pearl River Delta converters face steepest compliance cost escalation among domestic production bases.
India
Maharashtra and Gujarat converter clusters unbundle after-sales support from capital acquisition, purchasing maintenance separately through third-party specialists. FSSAI food safety compliance drives equipment specification for flexible packaging entrants. Mid-tier houses in Vietnam and Poland exhibit parallel procurement fragmentation as brand owners outsource pre-print conversion.
Poland
EU cohesion funding flows into packaging modernization, enabling underpenetrated mid-web flexible packaging houses to acquire first-generation central impression presses. REACH substance restrictions compress replacement timelines for aging stack-type configurations. Warsaw-region converter investments concentrate on water-based workflows meeting German export market requirements.
Global Pre Print Flexo Press Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment tiers, producing a bifurcated structure where integrated platform vendors anchor premium corrugated lines and narrow-web architects dominate label applications. Market concentration clusters around Swiss-German engineering heritage and Italian mechanical specialization. Strategic archetypes include full-line packaging platform providers, dedicated narrow-web specialists, and hybrid flexo-digital configurators. Competitive moves center on geographic expansion into emerging converter markets and technology licensing partnerships for UV LED curing integration.
Within the full-line platform tier, Bobst exemplifies integrated die-cutting and flexo architecture anchoring premium corrugated pre-print lines in Western Europe. Mark Andy occupies a position among narrow-web specialists competing aggressively through dedicated flexo press architectures for label applications. Gallus represents hybrid flexo-digital configuration leadership serving pharmaceutical and security label converter segments with variable data capabilities.
| Leading Market Players |
|---|
| Bobst |
| Mark Andy |
| Gallus |
| MPS Systems |
| Nilpeter |
| OMET |
| Comexi Group |
| Uteco Converting |
| Koenig & Bauer |
| Others |
Supply & Pricing Matrix
Flexographic operator skill scarcity in the United States and Italy feeds labor-cost differentials that widen pricing-tier spreads between premium OEM service bundles and economy third-party maintenance arrangements.
Pricing Analysis
Capacity additions in Poland and India are reshaping price floors for first-generation central impression presses. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated service packages from unbundled equipment procurement with third-party support. Price differentiation hinges on certification grade for EU REACH compliance and after-sales bundling intensity. Pricing pressure stems from mid-tier converters in Maharashtra and Gujarat unbundling maintenance from capital acquisition, compressing margins on service-inclusive contracts.
Supply Chain Analysis
Photopolymer plate supply rests on Japanese and South Korean specialty chemical producers with concentrated raw material sourcing. Photopolymer resin, laser imaging equipment, and sleeve cylinder substrates draw from Germany, Italy, and Japan. Single-source vulnerability in photoinitiator formulations for UV flexo creates exposure to REACH substance restrictions. Distribution runs through converter cluster networks around Bologna, Chicago, and Mumbai with direct OEM technical service overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU REACH compliance deadlines and China's MEE enforcement are accelerating equipment replacement cycles beyond natural obsolescence curves.
For Market Incumbents: Anticipate digital hybrid substitution threats from Gallus-style flexo-digital configurations in pharmaceutical and security label segments. Deepen backward integration into anilox roll manufacturing to capture aftermarket service margins. Anchor premium positioning through certified water-based process packages that satisfy German Extended Producer Responsibility mandates.
For New Entrants and Emerging Players: Digital-channel routes through equipment-as-service models bypass capital barriers for mid-tier converters in Vietnam and Poland. Target corrugated pre-print first-time buyers in India's Gujarat cluster with stack-type architectures and unbundled maintenance options. Lead with performance-guarantee contracts that shift technical risk from converter to supplier.
For Investors and Strategic Acquirers: Valuations sit cheapest among narrow-web label specialists lacking UV LED curing integration. Five-to-ten-year viability favors OEMs with certified press-ink-substrate combinations for food-contact migration limits. Watch UV LED curing adoption rates in shrink sleeve applications as the inflection signal for technology leadership transitions.
| Strategic Initiative | Industry Significance |
|---|---|
| UV LED Curing Integration | Reduces energy consumption and heat load for shrink sleeve converters facing REACH photoinitiator limits. |
| Equipment-as-Service Launch | Captures mid-tier buyers in Maharashtra and Gujarat lacking in-house technical depth. |
| REACH Certification Investment | Locks in German and Italian flexible packaging converters under EFSA migration deadlines. |
| Central Impression Capacity Addition | Targets Poland's EU cohesion-funded packaging modernization with first-generation press placements. |
| Hybrid Flexo-Digital Development | Defends against substitution in pharmaceutical serialization where FDA food contact rules apply. |
Research Methodology
Multiple input streams — primary interviews with press OEM technical directors, flexible packaging converter operations managers, and regulatory compliance officers; secondary validation through ECHA substance restriction databases, EPA emission standard filings, and MEE discharge compliance records; plus customs data on photopolymer plate trade flows — were reconciled through bottom-up equipment shipment tallies and top-down market sizing triangulation.
Historical capacity utilization patterns across the analysis window were cross-referenced against panel input from converter procurement heads to derive segment-level CAGRs. Modeled dimensions span press architecture type, ink curing technology, substrate application, and regional regulatory cluster. Forecast inputs incorporated EU REACH implementation timelines and China's dual carbon policy enforcement intensity as demand accelerators.
The model assumes a particular technology adoption path; alternative pathways for UV LED curing penetration would alter the outlook for mercury arc system residual value. Forecasts reflect assumptions about regulatory enforcement consistency and raw material supply stability. A small set of named triggers — MEE standard tightening, REACH substance list expansion, and photopolymer plate raw material disruptions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
North America Thermal Transfer Overprinter Market
Packaging Printing
Stamping Foils Market
Packaging Printing
North America Print Label Market
Packaging Printing
Printed Boxes Market
Packaging Printing
Global Digital Printing Packaging Market
Packaging Printing
Laser Coders Market
Packaging Printing
Pre-Printed Liners Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
Label Printing Software Market
Packaging Printing
Digital Label Printing Market
Packaging Printing
Czech Republic Printing Label Market
Packaging Printing
Electrophotography Printing for Packaging Market
Packaging Printing
Lithographic Printing for Packaging Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Pad Printing Machine Market