
 Label Printing Software Market | 2026-2036
Label Printing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Label Printing Software Market Analysis
Subscription-based maintenance tiers is realigning how vendors monetize label printing software, shifting perpetual licenses toward recurring revenue streams with embedded compliance updates. TEKLYNX leverages deep integration with enterprise resource planning systems to anchor its position in regulated manufacturing environments. Esko specializes in prepress workflow connectivity, sustaining premium pricing through color-accurate label design tools. Loftware dominates cloud-native deployments, extending its reach through multi-tenant architectures that reduce customer IT overhead.
Label printing software comprises applications that generate, design, and manage printable label formats through barcode symbologies, RFID encoding engines, and variable-data composition at resolutions typically ranging from 203 to 600 dots per inch. These systems serve industrial and commercial purposes by ensuring product traceability, regulatory compliance, and supply-chain visibility across physical goods movement. Cloud-based deployment leads in new customer acquisition due to lower upfront capital requirements and automatic regulatory template updates, while on-premises installations retain strongholds in defense and classified-material environments where data sovereignty overrides convenience. Compliance labeling functionality commands the highest margin pools as pharmaceutical and food-contact regulations tighten documentation requirements.
The FDA's Unique Device Identification rule and the EU's MDR labeling requirements shape product development roadmaps, forcing vendors to embed validation-ready audit trails and electronic signature workflows. ISO 15415 and GS1 standards further constrain barcode print quality tolerances, creating technical barriers for entrants lacking optical character verification partnerships. Stakeholders must monitor how FDA enforcement discretion periods expire and whether EU member states harmonize national serialization repositories, as these determinations will dictate R&D allocation between compliance-engineering and design-tool innovation.
Market Dynamics
Pharmaceutical serialization mandates are compressing deployment timelines across the label printing software value chain, forcing vendors to reengineer validation workflows and audit-trail architectures ahead of regulatory enforcement deadlines.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization requirements for prescription medicines are compelling pharmaceutical manufacturers to upgrade legacy labeling infrastructure with track-and-trace capabilities.
- Cloud-native architectures:Third-party logistics providers are adopting browser-based label management platforms to achieve real-time inventory synchronization across distributed warehouse networks.
- German automotive exports:Cross-border trade compliance is driving GS1-certified label stream investments among component suppliers serving OEM assembly plants.
Market Restraints
- Optical character verification hardware costs:ISO 15415 compliance requires capital-intensive inline inspection systems that strain mid-tier converter budgets.
- Data sovereignty requirements:Defense and classified-material environments in the United States and select European jurisdictions block cloud migration regardless of security certifications.
- Legacy ERP integration complexity:Proprietary communication protocols in installed manufacturing execution systems extend deployment cycles and inflate professional services costs.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO serialization alignment with global standards creates upgrade demand among contract manufacturers serving regulated markets.
- RFID-NFC convergence:Combined passive RFID encoding with near-field communication authentication is opening smart packaging applications in luxury goods and medical devices.
- Subscription compliance bundles:Automatic regulatory template updates embedded in recurring revenue contracts reduce customer churn while capturing mandate-driven refresh cycles.
Industry Challenges
- Validation engineering talent scarcity:FDA 21 CFR Part 11 compliant software development requires specialized quality assurance personnel in short supply across the vendor base.
- Multi-site template synchronization:Enterprise deployments struggle to maintain label format consistency across geographically dispersed production facilities with varying equipment vintages.
- Cross-standard harmonization friction:Divergent national serialization repository implementations in EU member states complicate single-platform rollout strategies.
Report Scope
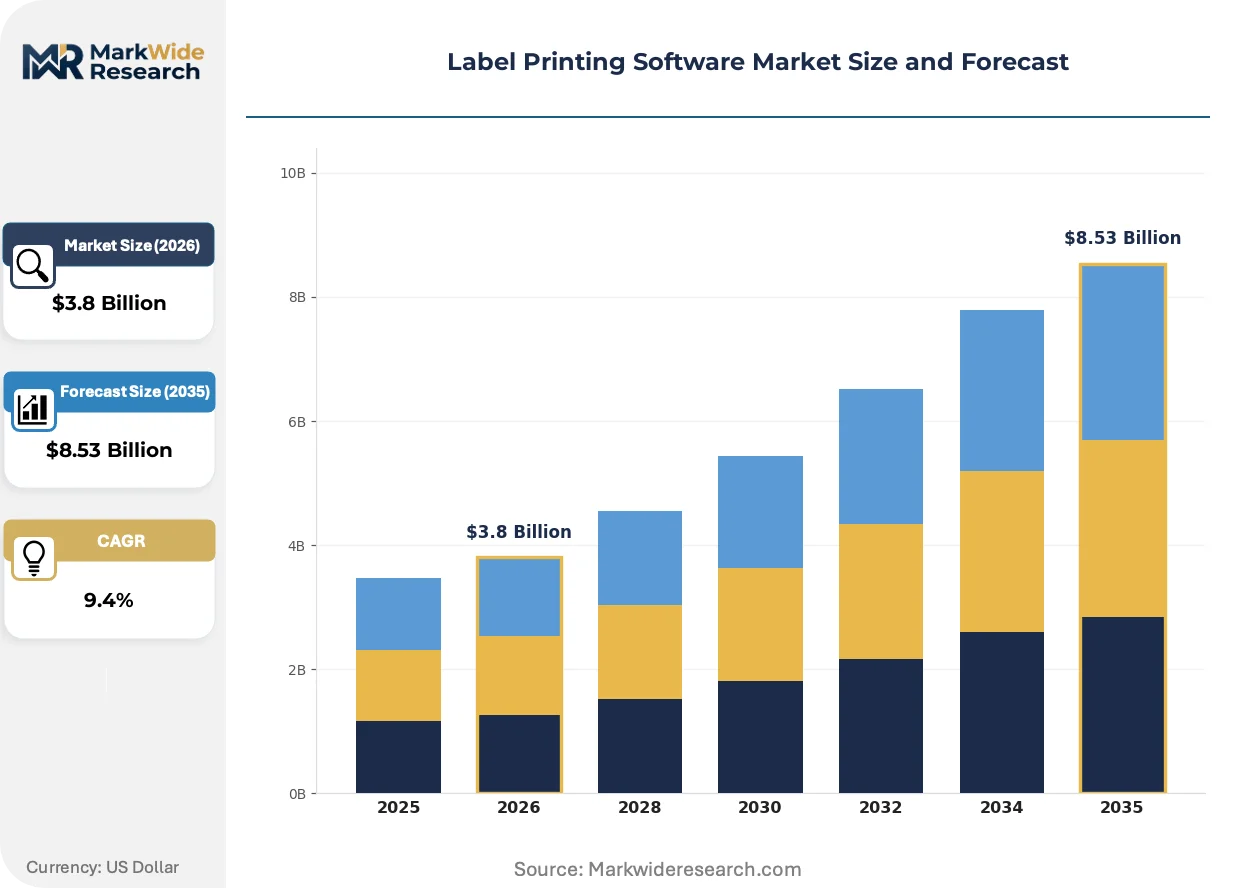
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Label Printing Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Application: Retail, Manufacturing, Logistics, Healthcare End User: Small Businesses, Enterprises, Government, Non-Profit Functionality: Barcode Generation, RFID Printing, Design Tools, Compliance Labeling |
| Companies Covered | TEKLYNX, Esko, Loftware, MarkMagic, CYBRA Corporation, Label LIVE, DynamicsPrint, Avery Design & Print, Shippo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Label Printing Software Market Emerging Trajectories
Label printing software is undergoing architectural transformation as regulatory complexity, cloud economics, and supply-chain digitization converge to reshape vendor roadmaps and customer procurement criteria.
AI-powered preflight engines are automating barcode quality verification prior to production release. Pharmaceutical contract manufacturers in Germany and Switzerland are deploying these systems to reduce print-run rejections and regulatory audit findings. The technology is unifying design validation with production execution, collapsing quality gates that previously required separate software modules.
REACH chemical labeling amendments are expanding hazard communication requirements for industrial chemical shipments into and within the European Union. Manufacturers must regenerate safety data sheet-linked label templates to accommodate new pictogram combinations and supplemental hazard statements. Specialty chemical producers in Belgium and the Netherlands are prioritizing template management platforms with automated regulatory update pipelines.
Label procurement centralization is consolidating purchasing authority from plant-level operations to corporate supply-chain functions. Food and beverage multinationals are mandating enterprise license agreements with standardized design libraries to ensure brand consistency and compliance traceability. This concentration is most pronounced among North American CPG conglomerates with extensive private-label portfolios spanning multiple co-manufacturing partners.
Label Printing Software Market Segmentation
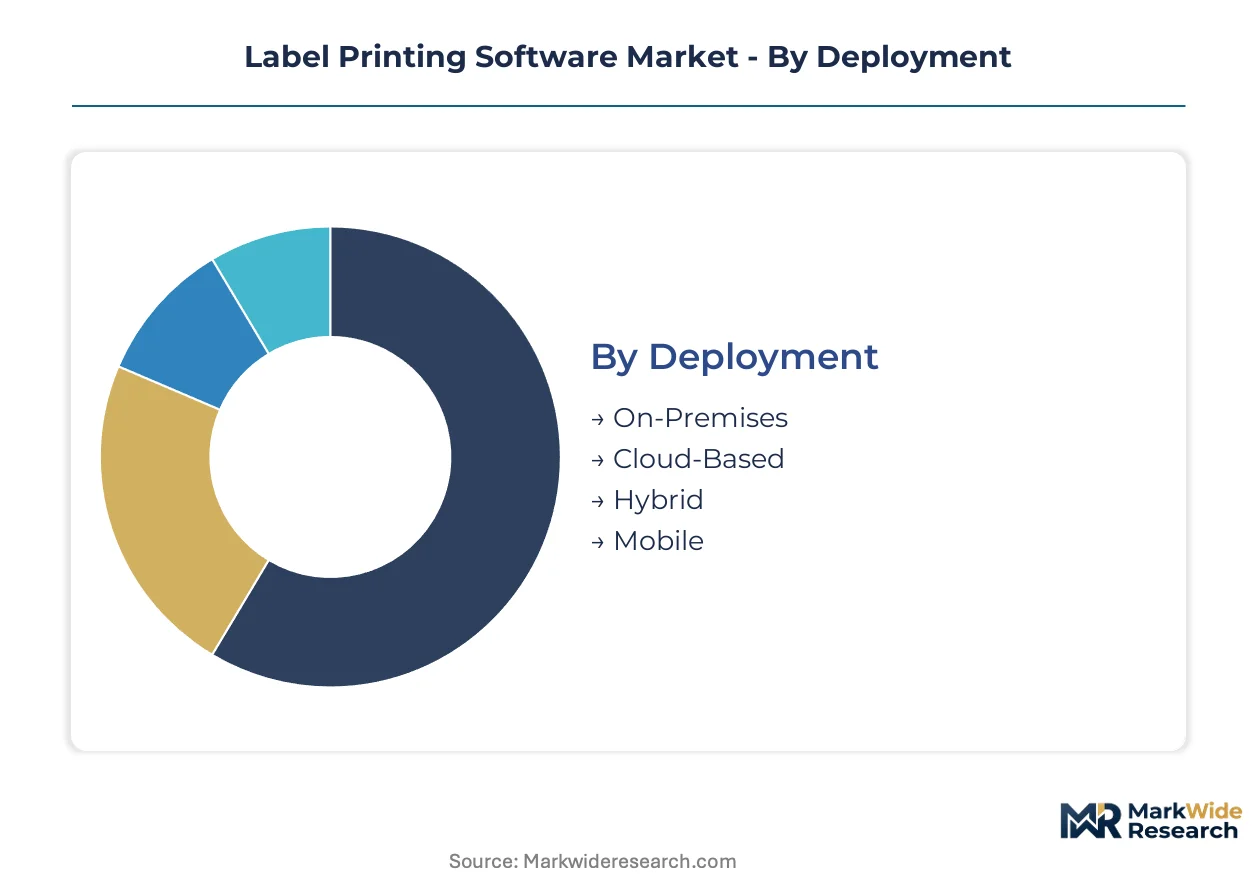
Label printing software vendors structure product portfolios around deployment economics, regulatory intensity, and operational scale. Segmentation reveals where margin pools concentrate and which customer profiles drive platform roadmap investments.
Deployment:
Supply concentration in cloud infrastructure is reshaping how vendors allocate engineering resources between subscription architectures and perpetual license maintenance.
- On-Premises:Installed software running within customer data centers supports environments requiring air-gapped networks and localized data retention. Defense contractors and classified-material handlers in the United States retain this model despite higher total cost of ownership.
- Cloud-Based:Browser-accessible platforms with multi-tenant architectures eliminate server maintenance burdens while delivering automatic regulatory template updates. Third-party logistics providers in Germany and the Netherlands are migrating warehouse operations to these systems for real-time inventory synchronization.
- Hybrid:Split deployments keep sensitive design data on local servers while pushing production execution to cloud instances. Pharmaceutical manufacturers with both validated and non-validated labeling workflows favor this architecture.
- Mobile:Native applications for handheld devices enable floor-level label generation without fixed workstation dependency. Field service technicians and pop-up retail operations deploy these for event-based or remote printing scenarios.
On-premises deployments absorb the bulk of installed capacity; cloud-based solutions are expanding most quickly.
Application:
Regulatory enforcement intensity varies sharply across use cases, concentrating vendor specialization in segments with mandatory audit trails.
- Retail:Point-of-sale label generation for pricing, promotions, and inventory management. Omnichannel retailers in France and the United Kingdom require shelf-edge consistency between physical and digital channels.
- Manufacturing:Work-in-process tracking and finished goods identification with GS1-compliant symbologies. Automotive suppliers in Germany embed these systems directly into production line PLCs for component traceability.
- Logistics:Shipping documentation, parcel routing, and cross-dock manifesting across distributed warehouse networks. Express carriers in Belgium and the Netherlands prioritize scan-rate optimization through high-contrast barcode formatting.
- Healthcare:Patient identification, specimen tracking, and pharmaceutical serialization under FDA and EMA mandates. Hospital networks in Switzerland and contract manufacturers in India are upgrading legacy systems to meet evolving compliance requirements.
Manufacturing commands the deepest installed base; healthcare is climbing the fastest on regulatory mandate timelines.
End User:
Procurement authority concentration determines whether vendors pursue enterprise license agreements or volume-tiered subscription models.
- Small Businesses:Entry-level design tools with template libraries and limited printer driver support. Independent retailers and craft producers in Spain and Italy purchase through reseller channels with minimal implementation services.
- Enterprises:Centralized template management with role-based access controls and integration APIs for ERP systems. Food and beverage conglomerates in North America mandate standardized design libraries across co-manufacturing partner networks.
- Government:Security-hardened deployments with FIPS 140-2 encryption and FedRAMP authorization where applicable. Federal logistics operations and state healthcare agencies in the United States require these certifications.
- Non-Profit:Discounted licensing for humanitarian supply chain operations and donor tracking. International relief organizations operating across multiple jurisdictions prioritize multi-language label support.
Enterprises generate the majority of recurring revenue; small businesses represent the largest addressable account volume.
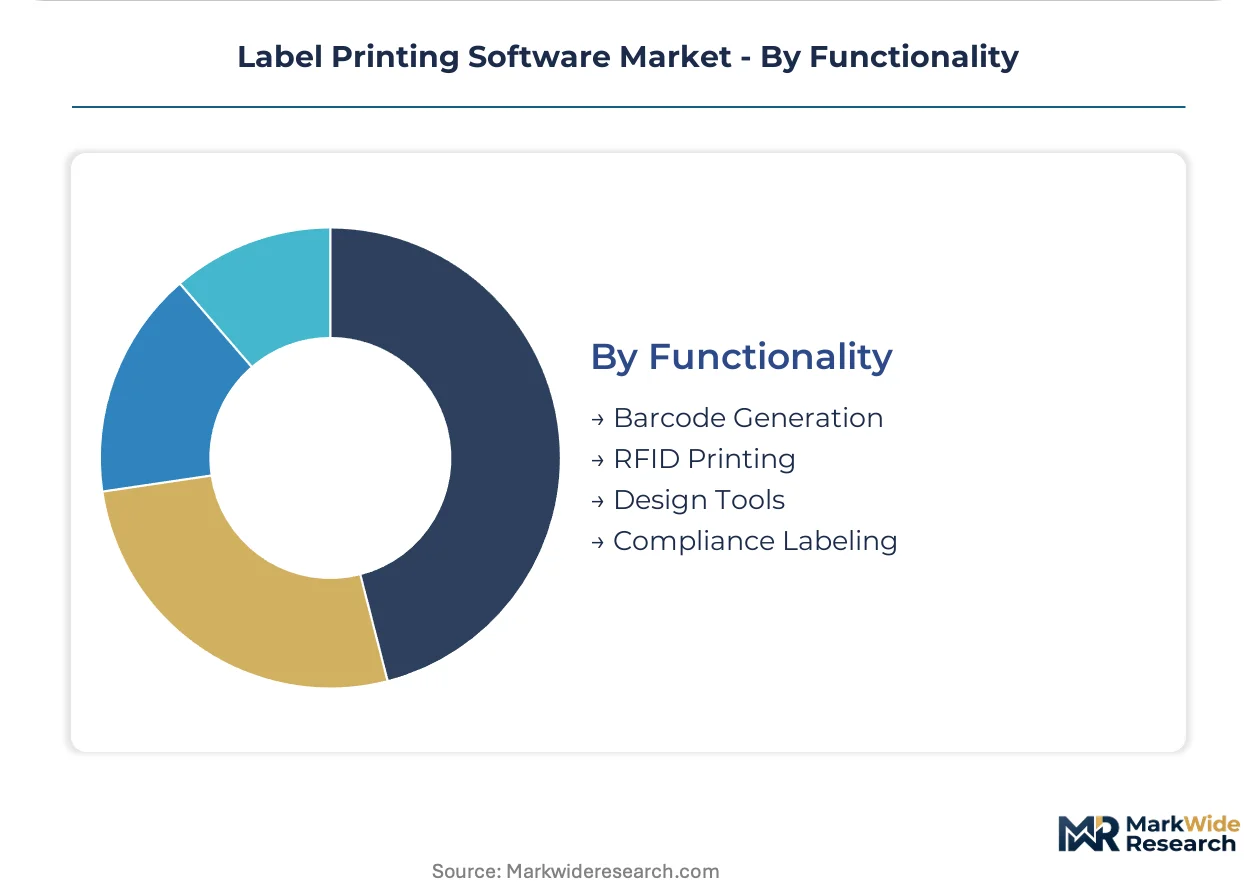
Functionality:
Margin capture follows regulatory complexity, with compliance-engineering modules commanding premium pricing over design-centric tools.
- Barcode Generation:Symbology encoding engines supporting linear and two-dimensional formats with ISO 15415 quality verification. Industrial converters in Germany integrate these with inline optical character recognition systems for automotive component shipments.
- RFID Printing:Passive and active tag encoding with EPC Gen2 compliance for item-level tracking. Luxury goods manufacturers in France and medical device producers in Switzerland deploy these for authentication and anti-counterfeiting.
- Design Tools:Vector-based label composition with color management and prepress workflow connectivity. Specialty chemical producers in Belgium require REACH-aligned hazard pictogram libraries.
- Compliance Labeling:Validation-ready audit trails, electronic signature workflows, and regulatory template repositories. Pharmaceutical contract manufacturers in Germany and India prioritize automatic update pipelines for FDA and EMA mandate alignment.
Compliance labeling captures the highest margin per seat; barcode generation remains the most widely deployed functional module.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and the United States where automotive and pharmaceutical exporters drive compliance-labeling investments, while consumption expands fastest among third-party logistics networks in the Netherlands and India seeking cloud-native inventory visibility.
United States
Defense contractors and classified-material handlers sustain on-premises deployment demand through FedRAMP-authorized and FIPS 140-2 hardened systems. FDA's Unique Device Identification rule compresses validation timelines for medical device manufacturers in Minnesota and Massachusetts. Boston-area hospital networks upgrade legacy patient identification systems to meet evolving HIPAA documentation requirements.
Germany
Automotive component suppliers embed label printing software directly into production line PLCs for GS1-certified traceability serving OEM assembly plants. EU Falsified Medicines Directive serialization mandates force pharmaceutical contract manufacturers in Baden-Württemberg to reengineer audit-trail architectures. Stuttgart industrial clusters prioritize inline optical character verification systems for cross-border component shipments.
India
Contract pharmaceutical manufacturers serving regulated export markets accelerate CDSCO serialization alignment with global standards. The country's national pharmaceutical regulator tightens documentation requirements for active pharmaceutical ingredient tracking. Mumbai-Pune pharmaceutical corridors invest in validation-ready software to maintain European and North American market access.
Netherlands
Rotterdam-Antwerp port logistics operators adopt browser-based label management platforms for real-time inventory synchronization across distributed warehouse networks. REACH chemical labeling amendments expand hazard communication requirements for industrial chemical shipments. Specialty chemical producers in Belgium and the Netherlands prioritize automated regulatory template update pipelines.
Switzerland
Luxury goods manufacturers and medical device producers deploy RFID-NFC convergence systems for authentication and anti-counterfeiting applications. Swissmedic mandates tighten validation requirements for pharmaceutical labeling workflows. Basel pharmaceutical clusters integrate electronic signature capabilities to satisfy evolving compliance documentation standards.
Label Printing Software Market Vendor Landscape
Top-tier vendors anchor enterprise compliance deployments, while mid-tier specialists occupy niche connectivity segments and entry-level providers serve small-business template libraries. The vendor base arranges across three strategic archetypes: ERP-integrated compliance platforms, prepress workflow connectivity tools, and cloud-native multi-tenant architectures. Dominant competitive moves include strategic partnerships with optical character verification hardware suppliers and portfolio diversification into RFID encoding engines.
Within the ERP-integrated tier, TEKLYNX represents deep manufacturing system connectivity archetypes. Esko occupies a position among prepress workflow specialists serving color-accurate label design requirements. Loftware anchors cloud-native deployment models that reduce customer IT overhead through multi-tenant architectures. These three exemplify how vendor specialization aligns with regulatory intensity and operational scale demands across pharmaceutical, automotive, and logistics verticals.
| Leading Market Players |
|---|
| TEKLYNX |
| Esko |
| Loftware |
| MarkMagic |
| CYBRA Corporation |
| Label LIVE |
| DynamicsPrint |
| Avery Design & Print |
| Shippo |
| Others |
Supply Flow & Price Mechanics
Enterprise pharmaceutical manufacturers and third-party logistics providers concentrate procurement authority, anchoring subscription-based SaaS pricing as the dominant model across compliance-intensive deployments. This buyer archetype consolidation enables vendors to embed automatic regulatory template updates within recurring revenue contracts, reducing churn while capturing mandate-driven refresh cycles.
Pricing Analysis
Margin tightening in mid-tier converter segments reflects ISO 15415 optical character verification hardware requirements that strain capital budgets. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation-ready audit trail depth and ERP integration complexity. Pricing pressure stems from cloud-native entrants undercutting perpetual license maintenance fees. Small businesses exhibit highest price sensitivity, while defense contractors accept premium tiers for air-gapped network compliance.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical corridors and data sovereignty requirements in United States defense environments are reshaping sourcing toward localized development centers. Engineering talent concentrates in Germany, the United States, and India. Software development draws from optical character verification hardware partnerships, cloud infrastructure providers, and specialized validation engineering labor pools. Single-source vulnerability in optical inspection equipment creates procurement risk. Distribution runs through direct enterprise sales teams and authorized reseller networks serving small-business segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into optical character verification hardware partnerships and compliance-engineering talent pools is reshaping competitive positioning, as vendors seek captive control over validation-ready audit trail components.
For Market Incumbents: Cement dominance in regulated manufacturing environments through deeper ERP system integration and preemptive certification investments for emerging FDA enforcement discretion expirations. Acquire specialized validation engineering capabilities to address talent scarcity constraining competitor roadmaps. Lock in pharmaceutical contract manufacturers with embedded electronic signature workflow modules. For New Entrants and Emerging Players: CDSCO serialization alignment in India opens a window for cloud-native deployments among contract manufacturers serving European and North American export markets. Target small-business segments in Spain and Italy with template-library-centric offerings distributed through reseller channels. Pursue white-label partnerships with third-party logistics providers seeking rapid warehouse network deployment. For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-engineering specialists with FDA 21 CFR Part 11 validation expertise in German pharmaceutical clusters. Long-term viability hinges on recurring revenue contract penetration rather than perpetual license conversion. Monitor EU member state harmonization of national serialization repositories as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance-Engineering Acquisition | Captures scarce FDA validation talent in Baden-Württemberg pharmaceutical corridors. |
| Cloud-Native Platform Launch | Targets Rotterdam-Antwerp logistics operators requiring real-time inventory synchronization. |
| RFID-NFC Convergence Partnership | Opens Swiss luxury goods authentication and medical device anti-counterfeiting applications. |
| Optical Character Verification Integration | Secures inline inspection supply for German automotive component traceability mandates. |
| Regulatory Template Pipeline Investment | Automates REACH hazard pictogram updates for Belgian specialty chemical producers. |
Methodological Framework
Independent corroboration across primary interviews with software engineering directors, pharmaceutical quality assurance leads, third-party logistics IT procurement officers, and optical character verification hardware suppliers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EMA regulatory guidance documents, GS1 implementation standards, and customs trade data for label printing equipment. Bottom-up deployment modeling triangulates against top-down market sizing across cloud-native and on-premises architectures.
Comparable-period anchoring to historical perpetual license conversion rates and subscription renewal patterns structures the projection horizon. Segmentation dimensions span deployment model, organization size tier, vertical regulatory intensity, ERP integration complexity, and regional adoption pattern. CAGRs derive from weighted average of vendor revenue disclosures and end-user procurement cycle analysis. Cloud infrastructure capex trajectories and pharmaceutical serialization mandate timelines feed industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for AI-powered preflight engines would alter the outlook. Forecasts reflect assumptions regarding EU member state repository harmonization and FDA enforcement discretion expiration sequencing. Regulatory delay or accelerated cloud migration among defense contractors would revise trajectory boundaries. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Printed Boxes Market
Packaging Printing
Thermal Transfer Overprinter Market
Packaging Printing
Europe Printed Packaging Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
Global Digital Printing Packaging Market
Packaging Printing
Pigment Hot Stamping Foil Market
Packaging Printing
Global Printing for Packaging Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Laser Coders Market
Packaging Printing
Global Pre Print Flexo Press Market
Packaging Printing
Digital Label Printing Market
Packaging Printing
Flexographic Printing Market
Packaging Printing
Czech Republic Printing Label Market
Packaging Printing
Label Printers Market
Packaging Printing
Rotogravure Printing Machine Market