
 Water Turbine Market | 2026-2036
Water Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
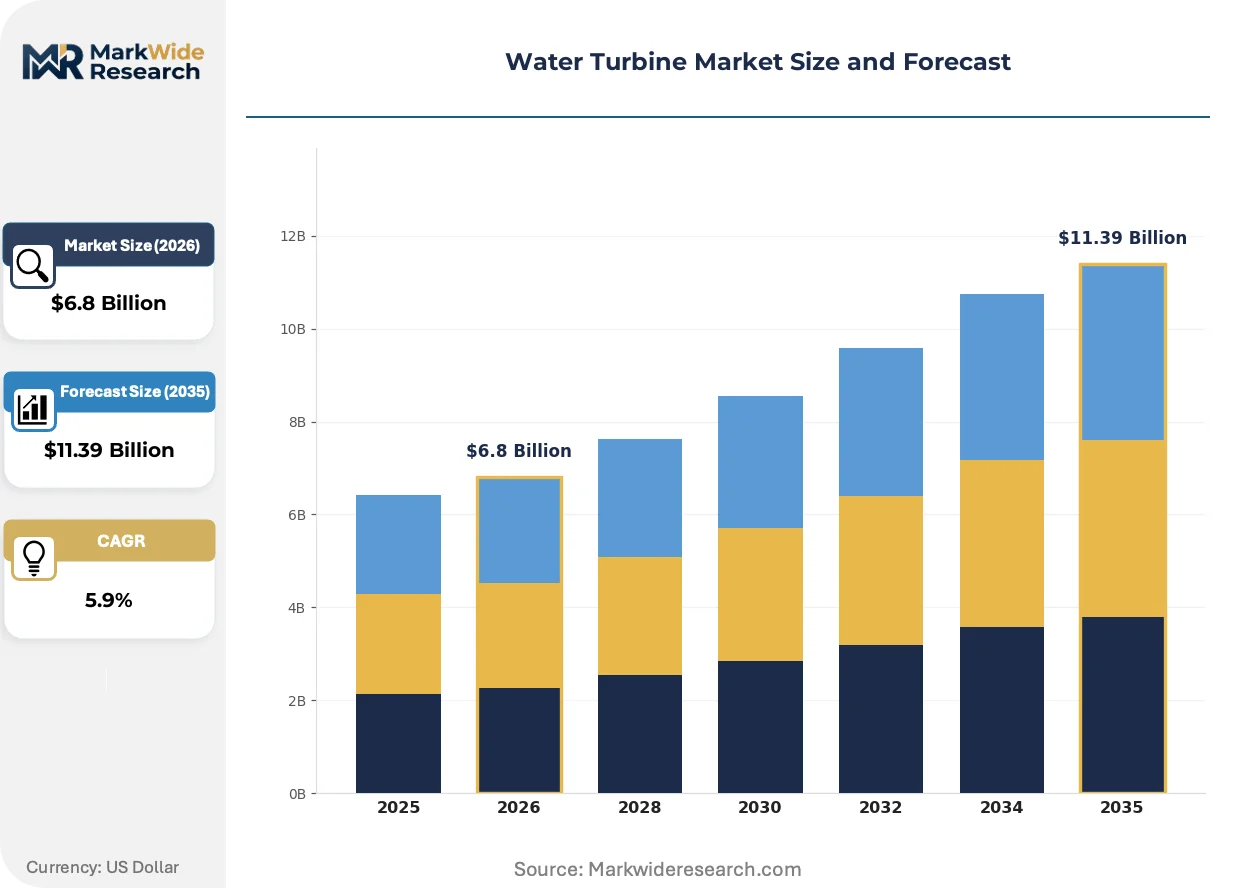
Water Turbine Market Outlook
The municipal water management vertical is broadening its share of water turbine procurement as cities upgrade aging distribution infrastructure. Toshiba Corporation leverages its century-long hydroelectric heritage to dominate high-head impulse turbine contracts across Asia. Andritz AG sustains European market presence through specialized Kaplan turbine designs optimized for low-head river installations. Siemens Energy AG competes on integrated digital control systems that extend turbine lifecycle performance.
A water turbine converts hydraulic energy into rotational mechanical power through precisely engineered blade geometry, typically operating at head pressures ranging from two meters to over two thousand meters depending on turbine classification. Its primary commercial purpose centers on electricity generation at hydropower facilities and mechanical drive applications in industrial water management systems. Reaction turbines capture the largest installed base due to their efficiency across variable flow conditions, while Pelton turbines retain premium positioning in high-head mountainous installations where margin pools concentrate among specialized forged-bucket suppliers. The less than 1 MW capacity bracket is expanding fastest as distributed generation policies incentivize small-scale run-of-river developments.
The EU Green Deal and F-Gas Regulation are mandating stricter efficiency benchmarks for new hydroelectric equipment across Europe, while the EPA enforces Clean Water Act provisions that constrain turbine siting in US watersheds. China's MEE applies dual carbon goals to hydro project approvals, accelerating domestic demand for advanced runner designs. Stakeholders must monitor how evolving national carbon accounting rules treat reservoir-based versus run-of-river hydroelectricity when allocating capital across turbine technology portfolios.
Market Dynamics
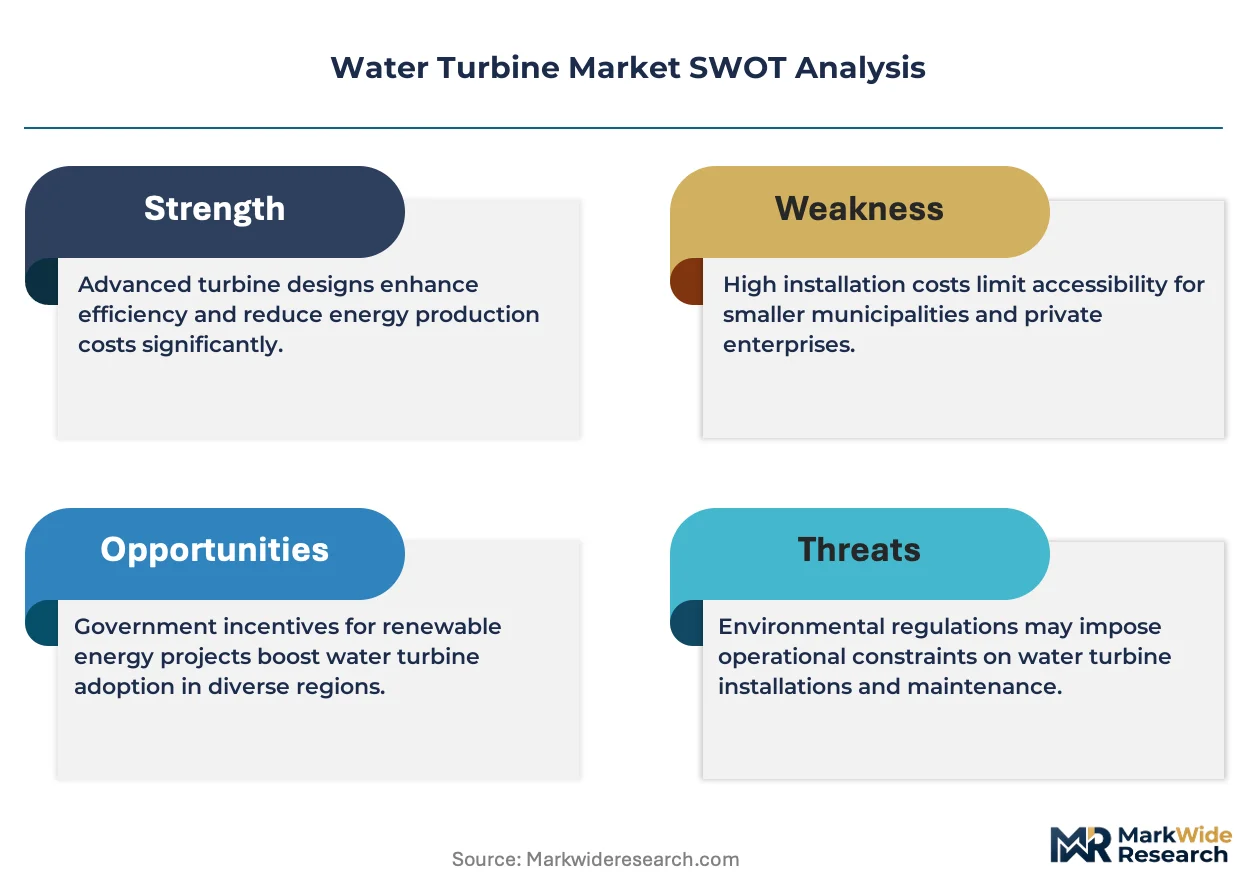
Retrofit mandates on aging hydropower infrastructure across Europe and Brazil are forcing turbine procurement cycles to compress, while efficiency standards under the EU F-Gas Regulation and Brazil's ANVISA environmental streamlining reshape supplier qualification requirements.
Growth Catalysts
- EU F-Gas Regulation:Equipment efficiency mandates are accelerating replacement demand for modern reaction turbines across member states with aging dam infrastructure.
- Run-of-river licensing:Brazil's ANVISA and national energy regulator streamlining is unlocking distributed generation projects under 1 MW capacity.
- Digital control integration:Siemens Energy AG and competitors are bundling lifecycle performance monitoring into new turbine contracts, extending service revenue streams.
Market Restraints
- Forged-bucket supply concentration:High-head Pelton turbine manufacturing depends on specialized metallurgical suppliers concentrated in Central European and Japanese forging clusters.
- EPA Clean Water Act constraints:US watershed siting restrictions limit greenfield project development in environmentally sensitive river basins.
- Reservoir carbon accounting uncertainty:Evolving national methodologies for measuring reservoir methane emissions create financing hesitation for large-scale impoundment projects.
Strategic Opportunities
- Small-scale distributed generation:India's CEA and state-level renewable purchase obligations are incentivizing sub-1 MW run-of-river installations in Himalayan foothill states.
- Kaplow-head optimization:Andritz AG's specialized runner designs for low-head river installations address untapped potential in European canal systems and Asian irrigation networks.
- Digital twin convergence:Integration of computational fluid dynamics with IoT sensor networks enables predictive maintenance contracts that capture recurring revenue from municipal water management operators.
Industry Challenges
- Computational fluid dynamics expertise scarcity:Runner blade optimization requires specialized simulation talent that turbine OEMs struggle to retain against aerospace and automotive competitors.
- Legacy control system integration:Municipal water management operators face technical debt when retrofitting digital monitoring onto decades-old mechanical governors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Turbine Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impulse Turbines, Reaction Turbines, Kaplan Turbines, Pelton Turbines End User: Hydropower Plants, Industrial Applications, Irrigation Systems, Municipal Water Management Installation Type: Onshore, Offshore, Portable, Fixed Capacity: Less than 1 MW, 1 MW to 5 MW, 5 MW to 20 MW, More than 20 MW |
| Companies Covered | Toshiba Corporation, Harbin Electric Corporation, General Electric Company, Hitachi Mitsubishi Hydro Corporation, Power Machines, Andritz AG, Dongfang Electric Corporation, Siemens Energy AG, Voith GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Turbine Market Strategic Shifts
Additive manufacturing of turbine runners is compressing prototyping cycles and enabling geometry optimizations previously impossible with conventional casting. Material science advances and digital fabrication methods are reshaping how suppliers compete on lead time and customization.
Computational fluid dynamics-optimized runner blade geometries are consolidating competitive advantage for suppliers with in-house simulation capabilities. Municipal utilities and independent power producers are specifying CFD-validated designs in procurement tenders to maximize efficiency across variable flow conditions. This capability gap is compressing margins for smaller fabricators dependent on empirical design rules.
China's MEE dual carbon goals are tightening hydro project approval criteria, accelerating domestic demand for advanced runner designs that minimize ecological flow disruption. Domestic turbine manufacturers are responding with fish-friendly blade profiles and aeration-enhancing draft tube configurations. The regulatory pressure is displacing conventional fixed-blade propeller turbines in new project pipelines.
After-sales service unbundling is fragmenting traditional OEM revenue models as independent service providers capture refurbishment and spare parts markets. Third-party specialist firms are acquiring diagnostic capabilities and reverse-engineering proprietary runner designs to compete on lifecycle cost. This channel shift is most visible in Brazil and India where distributed generation asset ownership concentrates among non-utility investors seeking operational flexibility.
Water Turbine Market Segmentation
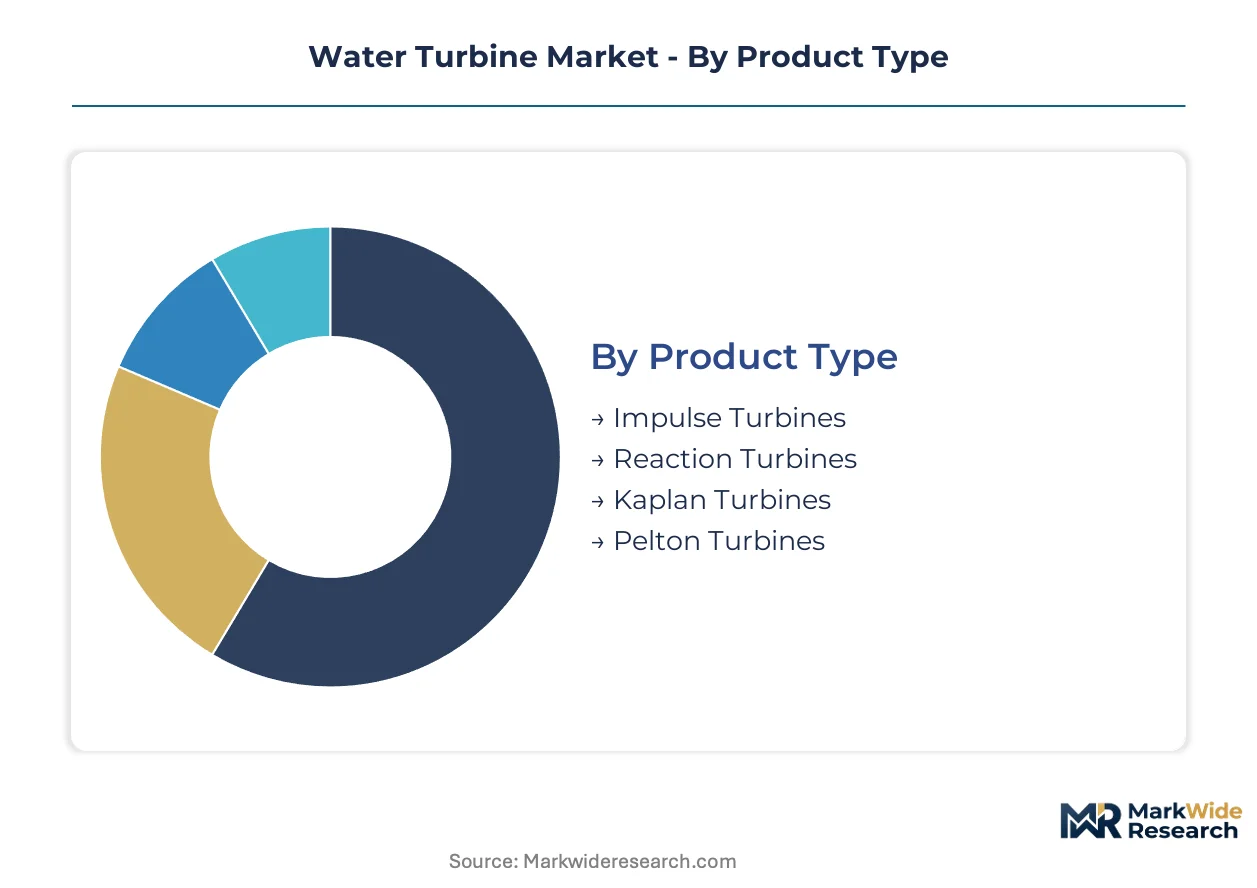
Water turbine procurement patterns diverge sharply across product architectures, end-use applications, and capacity brackets. Capital allocation decisions hinge on head pressure characteristics, grid connection requirements, and regulatory treatment of reservoir versus run-of-river configurations.
Product Type:
Capital intensity varies dramatically across turbine architectures, with high-head impulse designs demanding specialized forging infrastructure while reaction turbines scale through standardized casting operations.
- Impulse Turbines:These units convert kinetic energy through high-velocity jets striking bucket-shaped runners, requiring precision-forged components from specialized metallurgical suppliers in Central European and Japanese clusters. Demand concentrates in Himalayan and Andean high-head installations where margin pools reward premium bucket geometry.
- Reaction Turbines:Pressure differential across fully submerged runners enables efficient energy extraction across variable flow conditions. Hydropower plant operators in Europe and Brazil are retrofitting aging infrastructure with modern reaction designs as the EU F-Gas Regulation tightens efficiency mandates.
- Kaplan Turbines:Adjustable blade angles optimize performance in low-head river installations common to European canal networks and Asian irrigation systems.
- Pelton Turbines:Horizontal or vertical shaft configurations with double-jet arrangements dominate mountainous terrain above 500 meters head pressure.
Reaction turbines absorb the bulk of installed capacity; Pelton configurations are expanding most quickly in high-altitude distributed generation projects.
End User:
Customer archetypes span from centralized utilities with century-long asset horizons to municipal operators prioritizing operational flexibility over capital efficiency.
- Hydropower Plants:Large-scale electricity generators operate turbines across the full capacity spectrum, with procurement cycles accelerating as Brazil's ANVISA streamlines environmental licensing for run-of-river developments.
- Industrial Applications:Pulp and paper, mining, and chemical processors deploy mechanical drive turbines for process water management and captive power generation.
- Irrigation Systems:Agricultural water districts integrate small-scale turbines into gravity-fed canal infrastructure, particularly across India's Himalayan foothill states where the CEA incentivizes sub-1 MW installations.
- Municipal Water Management:Cities upgrading aging distribution infrastructure specify integrated digital control systems that extend turbine lifecycle performance and reduce operational headcount.
Hydropower plants command the dominant share of turbine procurement value; municipal water management is climbing the fastest as urban infrastructure retrofit mandates proliferate.
Installation Type:
Site configuration determines civil engineering requirements, foundation specifications, and maintenance accessibility over multi-decade operational horizons.
- Onshore:Land-based installations anchored to bedrock or engineered foundations represent the conventional deployment model for utility-scale projects across river basins worldwide.
- Offshore:Tidal and marine current turbines operate in corrosive saltwater environments requiring specialized materials and remote monitoring capabilities.
- Portable:Containerized or skid-mounted units enable rapid deployment for emergency power, military applications, and temporary industrial sites.
- Fixed:Permanent civil structures with integrated powerhouse facilities dominate large-capacity installations above 20 MW.
Fixed installations retain the largest cumulative capacity base; portable configurations are gaining share fastest in distributed generation and disaster response applications.
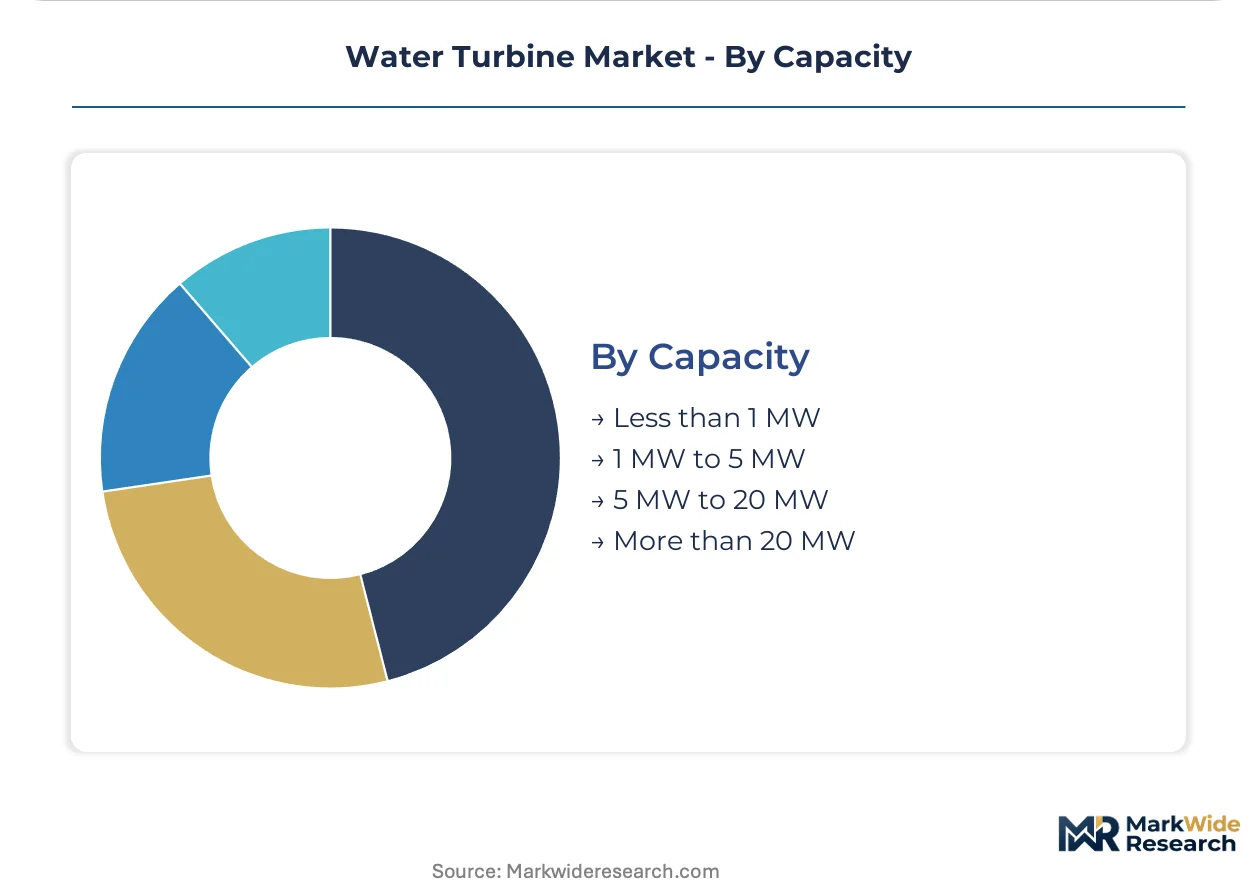
Capacity:
Scale thresholds align with grid connection standards, environmental review pathways, and financing structures available to project developers.
- Less than 1 MW:Run-of-river micro-hydro units bypass lengthy licensing procedures in multiple jurisdictions, with Brazil and India actively streamlining approvals for distributed generation assets.
- 1 MW to 5 MW:Small-scale commercial projects balance economies of scale against siting flexibility, often serving industrial offtakers or rural electric cooperatives.
- 5 MW to 20 MW:Mid-size installations face intensifying carbon accounting scrutiny as reservoir methane measurement methodologies evolve, creating financing hesitation for impoundment-based designs.
- More than 20 MW:Large-scale facilities require multi-year development timelines, extensive environmental impact assessments, and long-term power purchase agreements with creditworthy offtakers.
Above-20 MW installations retain the greatest cumulative capacity; sub-1 MW systems are expanding most quickly as distributed generation policies reshape developer incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of water turbine components while Brazil and India absorb expanding procurement volumes for distributed generation. European retrofit demand concentrates in Alpine and Nordic river basins where aging infrastructure requires efficiency upgrades.
China
Domestic hydropower developers source reaction turbines for the Yangtze and Yellow River basins under MEE dual carbon goals that tighten ecological flow requirements. The MIIT promotes advanced runner designs through industrial upgrading funds. Sichuan-Chongqing manufacturing clusters produce precision-forged components for both domestic installation and export to Southeast Asian dam projects.
Brazil
ANVISA and the national energy regulator accelerated environmental licensing timelines for run-of-river developments under 1 MW capacity. The country's renewable auction mechanism guarantees offtake prices for small hydro independent power producers. Equipment procurement concentrates in Minas Gerais and Paraná where cascading river systems support distributed generation portfolios.
Germany
The EU F-Gas Regulation mandates efficiency benchmarks that force replacement of pre-2000 turbine installations in Bavarian and Baden-Württemberg hydropower fleets. Federal network agency rules prioritize grid stability services from existing run-of-river assets. The Rhine-Main industrial corridor hosts specialized forging suppliers that serve Alpine high-head projects across Austria and Switzerland.
India
CEA renewable purchase obligations and state-level feed-in tariffs incentivize sub-1 MW installations across Himalayan foothill states. The Ministry of Power streamlines clearances for micro-hydro through single-window approval mechanisms. Tamil Nadu and Karnataka textile clusters deploy mechanical drive turbines for captive power in water-intensive processing operations.
United States
EPA Clean Water Act constraints limit greenfield development in Pacific Northwest salmon recovery watersheds while FERC licensing reforms accelerate conduit hydropower on existing dams. Municipal utilities in California and the Northeast specify digital control retrofits for century-old infrastructure. Colorado and Washington state programs fund fish-friendly turbine upgrades at irrigation district facilities.
Water Turbine Market Competitive Environment
Top-tier vendors anchor high-head impulse and large reaction turbine contracts, while mid-tier fabricators compete on standardized Kaplan and Francis runner production. The vendor base stratifies across three tiers: integrated energy conglomerates with century-long hydroelectric heritage, specialized hydraulic machinery divisions of industrial groups, and regional fabricators serving sub-5 MW distributed generation. Strategic archetypes include forged-bucket specialists capturing premium margins in mountainous terrain, digital-integrated full-service providers bundling predictive maintenance, and cost-optimized casting houses supplying emerging market utilities. Competitive moves concentrate on backward integration into precision forging capacity and technology licensing partnerships for fish-friendly runner designs.
Within the integrated conglomerate tier, Toshiba Corporation and General Electric Company exemplify vendors with diversified energy portfolios that span nuclear, gas, and renewable generation alongside hydroelectric equipment. Siemens Energy AG occupies a position emphasizing digital control system integration rather than standalone mechanical supply. Among Asia-Pacific-based manufacturers, Harbin Electric Corporation and Dongfang Electric Corporation represent state-linked entities with captive domestic demand from national hydropower expansion programs. European specialists Andritz AG and Voith GmbH & Co. KGaA anchor positions in low-head optimization and pumped-storage configurations respectively.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Harbin Electric Corporation |
| General Electric Company |
| Hitachi Mitsubishi Hydro Corporation |
| Power Machines |
| Andritz AG |
| Dongfang Electric Corporation |
| Siemens Energy AG |
| Voith GmbH & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
Brazil's ANVISA environmental licensing streamlining for sub-1 MW run-of-river projects is compressing procurement cycles and forcing suppliers to choose between premium pricing for rapid delivery or margin erosion from inventory carrying costs. This demand-side acceleration is reshaping how forged-bucket specialists and casting houses calibrate their contract structures across the capacity spectrum.
Pricing Analysis
Lead-time premiums dominate contract negotiations as hydropower developers facing retrofit mandates pay 15-30 percent above baseline for six-month delivery windows versus standard twelve-month schedules. Three-tier pricing structure across premium, standard, and economy levels separates forged-bucket Pelton turbines from cast reaction designs and standardized Kaplan runners. Cost compression in the sub-1 MW bracket is intensifying because India's CEA incentives are drawing commodity-grade fabricators into distributed generation procurement. Municipal water management operators exhibit the lowest price sensitivity due to lifecycle performance monitoring requirements, while independent power producers in Brazil and India drive aggressive spot-market negotiations.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and China anchor hub-and-spoke patterns that position precision-forged components near Alpine, Himalayan, and Andean high-head installations. Sichuan-Chongqing manufacturing clusters draw from captive metallurgical suppliers for runner castings, while Central European forging houses rest on specialized alloy feedstock from Scandinavian mills. Single-source vulnerability concentrates in precision-forged Pelton buckets where Japanese and German suppliers command irreplaceable metallurgical expertise. Distribution runs through EPC contractor networks that bundle turbine supply with civil works, compressing direct OEM channel access in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forged-bucket manufacturing capacity constraints in Central Europe and Japan are propping pricing power for high-head turbine suppliers despite accelerating demand from distributed generation retrofits. This supply bottleneck favors incumbents with captive forging relationships over new entrants dependent on spot metallurgical procurement.
For Market Incumbents: Lock in long-term offtake agreements with Brazilian and Indian IPPs before ANVISA and CEA licensing reforms saturate the sub-1 MW channel with commodity competitors. Secure backward integration into precision forging capacity in Germany or Japan to defend margin position against Chinese casting houses expanding into reaction turbine exports. Prioritize digital twin integration contracts with European municipal utilities facing EU F-Gas Regulation efficiency mandates. For New Entrants and Emerging Players: Municipal water management operators in the US Northeast and California represent an underserved buyer archetype seeking fish-friendly runner retrofits without legacy OEM pricing premiums. Target India's Himalayan foothill states where CEA renewable purchase obligations are outpacing established supplier service capacity. Pursue technology licensing partnerships with European specialists for Kaplan low-head optimization rather than competing head-to-head on reaction turbine casting scale. For Investors and Strategic Acquirers: The window for entry favors mid-cap fabricators with established CFD simulation teams and dormant forging relationships that can be reactivated under demand surge. Acquisition targets should demonstrate installed base visibility in Brazil's Minas Gerais or Paraná river basins where ANVISA streamlining is concentrating project pipelines. Monitor EPA Clean Water Act enforcement intensity in Pacific Northwest salmon recovery watersheds as a signal for US greenfield development viability versus retrofit-focused capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Forging Capacity Expansion | Captures premium margins in high-head Pelton contracts across Alpine and Himalayan terrain. |
| Digital Twin Platform Integration | Enables recurring service revenue from European municipal utilities under F-Gas efficiency mandates. |
| Fish-Friendly Runner Licensing | Addresses EPA Clean Water Act constraints in US salmon recovery watersheds. |
| Sub-1 MW Distributed Generation Partnership | Secures volume anchor in Brazil's ANVISA-streamlined licensing environment. |
| CFD Simulation Talent Acquisition | Closes capability gaps against aerospace and automotive competitors for runner optimization. |
Study Parameters
Trade association filings, customs export records, and national energy regulator licensing databases formed the secondary backbone for capacity and procurement flow analysis. Primary interviews with hydropower plant engineering directors, EPC contractor procurement leads, municipal water utility maintenance managers, and precision forging supplier sales executives validated installation timelines and contract structure evolution. Bottom-up turbine shipment tracking by capacity bracket and head pressure classification was cross-referenced against top-down national hydropower development announcements from China's MEE, Brazil's ANVISA, and India's CEA.
Bottom-up modeling aggregated individual project announcements across run-of-river and reservoir configurations, while top-down validation applied national renewable energy targets and retrofit mandates from the EU F-Gas Regulation. Segmentation dimensions included turbine architecture, capacity bracket, installation type, and regional regulatory cluster. CAGRs were derived from slope analysis of year-over-year procurement value trajectories, incorporating lead-time compression effects from Brazil's licensing reforms and carbon accounting uncertainty impacts on reservoir project financing.
Revisions become necessary when reservoir methane measurement methodologies stabilize, when China's MEE tightens ecological flow requirements beyond current dual carbon goal baselines, or when EPA Clean Water Act enforcement shifts toward conduit hydropower exemptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Wireless Power Receiver Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Electric Arc Furnaces Market
Power
Power Sled Market
Power
Europe Solar Inverter Market
Power
Russian Federation Power Market
Power
Brunei Power Market
Power
Critical Power Market
Power
Sudan Power Market
Power
Recloser Control Market
Power
Residential Portable Inverter Generator Market
Power
Modular PSA Nitrogen Generator Market
Power
United States Power Market
Power
Portugal Power Market
Power
Power Shelf Market
Power
Power Rental Market