
 Rotating Phase Converter Market | 2026-2036
Rotating Phase Converter Market Size, Share, and Industry Trends Forecast 2026-2036
Rotating Phase Converter Market Analytics
Market Dynamics
The capital-intensity divergence between integrated manufacturers and assembly-focused competitors is rotating competitive dynamics across the sector. American Rotary leverages captive motor-winding capabilities to sustain margin structures that pure distributors cannot match. RONK anchors its position through decades of field-proven designs in agricultural duty cycles. Power Systems & Controls differentiates via military-grade build standards that extend product lifespan in harsh environments.
Technology and Segmentation
A rotating phase converter is an electromechanical device that uses a single-phase electric motor to drive a three-phase generator, producing balanced three-phase power from single-phase utility service for industrial equipment. Rotary units dominate installed base volumes due to proven tolerance of motor-start surges and minimal harmonic distortion, while digital control segments attract premium pricing from precision CNC and medical imaging applications. Manufacturing end-use absorbs the largest share of power-rated units, though agriculture represents the fastest-growing application as farmers retrofit irrigation pumps and grain handling systems.
Regulatory Environment
NEMA MG-1 motor efficiency standards and IEEE 519 power quality limits shape product design thresholds across the US market, while OSHA electrical safety regulations mandate enclosure ratings and disconnect provisions for commercial installations. The EPA's focus on standby generator emissions indirectly affects hybrid converter-genset configurations. Stakeholders must monitor state-level rural electrification grant programs and evolving harmonics compliance for grid-tied distributed generation.
Market Dynamics
The US Midwest's agricultural electrification gap is concentrating demand for three-phase conversion equipment among rural equipment operators retrofitting legacy single-phase infrastructure.
Growth Catalysts
- NEMA MG-1 Efficiency Mandates:Tightening motor efficiency standards are forcing equipment replacements that require three-phase power, expanding the addressable base for rotary converters in industrial settings.
- Agricultural Mechanization:US grain handling and irrigation pump upgrades are accelerating adoption as farmers deploy larger three-phase machinery without utility line extensions.
- IEEE 519 Compliance:Power quality guidelines for harmonic distortion are favoring rotary technology over electronic alternatives in precision manufacturing environments.
Market Restraints
- Copper and Laminated Steel Volatility:Raw material cost swings in motor core components compress margin predictability for manufacturers without captive supply arrangements.
- Utility Infrastructure Investment:Rural electric cooperative three-phase extension programs in Iowa and Nebraska threaten substitution for standalone converter installations.
- Electronic Converter Performance:Digital phase conversion technology is narrowing the harmonic distortion gap at lower price points in sub-10 horsepower applications.
Strategic Opportunities
- OSHA Electrical Safety Compliance:Mandated enclosure ratings and disconnect provisions for commercial installations create specification consulting revenue streams.
- Hybrid Converter-Genset Configurations:EPA standby generator emission standards are opening integrated power quality and backup power solutions for critical agricultural operations.
- State Rural Electrification Grants:Wisconsin and Minnesota programs subsidizing three-phase infrastructure create co-funding pathways for converter-plus-line-extension hybrid projects.
Industry Challenges
- Motor Winding Specialist Shortage:The decline of US-based electrical trades training programs constrains captive manufacturing capabilities for integrated producers.
- NEMA Certification Timelines:Extended laboratory testing cycles for new efficiency tier products delay product launch windows by 8-14 months.
- Legacy Single-Phase Infrastructure Integration:Voltage stability requirements for sensitive CNC and medical imaging loads demand site-specific engineering that complicates standardized product offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotating Phase Converter Market |
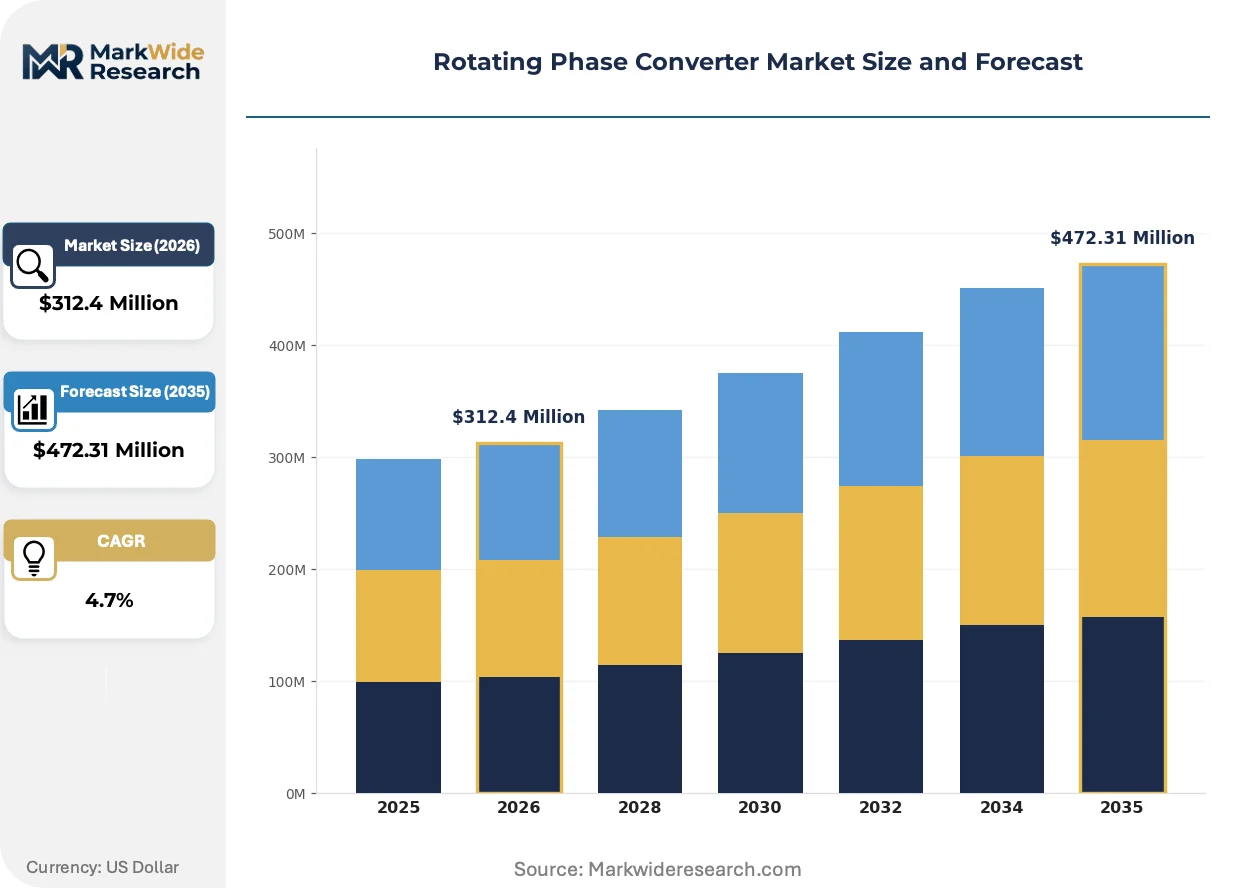
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Static, Rotary, Digital, Hybrid Application: Manufacturing, Agriculture, Construction, Commercial End User: Small Businesses, Large Enterprises, Contractors, Service Providers Power Rating: 5 HP, 10 HP, 15 HP, 20 HP |
| Companies Covered | Steelman, RONK, Phase A Matic, Power Systems & Controls, NAPCES, American Rotary, Georator, Transwave, Harman Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotating Phase Converter Market Evolving Landscape
Power electronics and electromechanical architectures are diverging into distinct competitive arenas, with digital control segments capturing precision applications while rotary units defend motor-start tolerance positions.
Digital signal processor-based voltage regulation is bifurcating the precision power quality segment from traditional rotary architectures. CNC machine shops and medical imaging facilities are adopting closed-loop converter systems at three times the rate of general industrial buyers. This technology is compressing the addressable market for premium rotary units above 15 horsepower while expanding total category revenue through higher unit pricing.
OSHA's updated electrical safety regulations for commercial installations are mandating NEMA 3R minimum enclosure ratings and visible blade disconnects on all new converter deployments. Equipment manufacturers must redesign legacy open-frame models or exit the commercial segment entirely. Agricultural duty cycle products face the steepest redesign costs due to dust-tight sealing requirements.
Equipment procurement through rural electric cooperative rebate programs is displacing traditional distributor channels in the US Midwest. Farmers in Illinois and Indiana now source converters through utility-sponsored energy efficiency initiatives rather than agricultural equipment dealers. This channel shift concentrates volume with manufacturers holding cooperative-approved vendor status while marginalizing independent distributors.
Rotating Phase Converter Market Segmentation
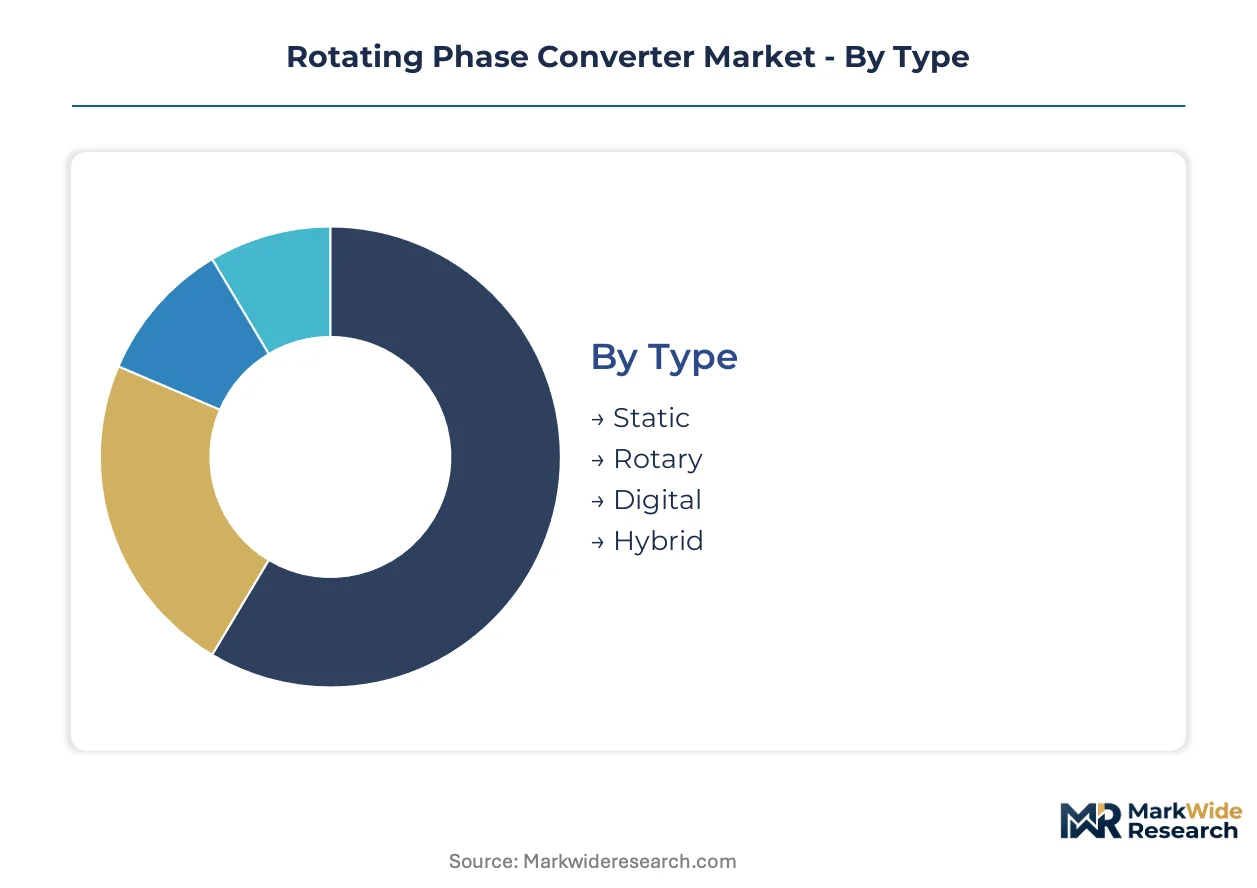
Segmentation in rotating phase converters reveals how technology choice maps to power quality requirements and installation economics. Distinct buyer profiles emerge across agricultural mechanization, precision manufacturing, and commercial infrastructure verticals.
Type:
Electronic substitutes are pressuring legacy electromechanical segments most aggressively in sub-15 horsepower applications where harmonic tolerance requirements remain relaxed.
- Rotary:An electromechanical architecture using a single-phase motor to drive a three-phase generator, delivering balanced output with proven tolerance of motor-start surges. Demand concentrates among Iowa and Nebraska grain elevator operators retrofitting irrigation pumps and handling equipment, driven by IEEE 519 compliance requirements that favor rotary harmonic performance over electronic alternatives.
- Digital:Closed-loop converter systems employing digital signal processors for voltage regulation, capturing specification in CNC machine shops and medical imaging facilities at three times the rate of general industrial buyers. Wisconsin and Minnesota precision manufacturers drive adoption as voltage stability requirements for sensitive loads outstrip rotary unit capabilities.
- Static:Solid-state phase conversion using capacitors and switching electronics, serving cost-sensitive applications with limited motor-start frequency.
- Hybrid:Integrated converter-genset configurations addressing EPA standby generator emission standards for critical agricultural operations requiring backup power.
Rotary units retain volume leadership; Digital holds the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive permanent installations from mobile equipment serving intermittent duty cycles.
- Manufacturing:Absorbs the largest share of power-rated units across metal fabrication, plastics processing, and assembly operations requiring continuous three-phase supply.
- Agriculture:Grain handling system upgrades and center-pivot irrigation retrofits in Illinois and Indiana drive specification, with farmers deploying larger three-phase machinery without utility line extensions.
- Construction:Mobile phase conversion for temporary power at remote job sites, prioritizing portability over power quality precision.
- Commercial:HVAC, elevator, and food service equipment installations subject to OSHA electrical safety regulations mandating NEMA 3R enclosures and visible blade disconnects.
Manufacturing dominates revenue contribution; Agriculture gains share fastest.
End User:
Customer type determines procurement channel and specification authority, with rural electric cooperative programs displacing traditional distribution for agricultural buyers.
- Small Businesses:Machine shops, repair services, and light manufacturing operations sourcing 5-10 HP units through electrical contractors and farm supply dealers.
- Large Enterprises:Industrial facilities with in-house engineering staff specifying 15-20 HP systems for production line integration and power quality compliance.
- Contractors:Electrical and agricultural equipment installers serving as specification gatekeepers for end-user retrofit projects across the US Midwest.
- Service Providers:Maintenance and rental companies holding rotating inventory for emergency replacement and temporary capacity expansion.
Large Enterprises command specification authority; Contractors control the steepest volume growth pathway.
Power Rating:
Volume concentration at lower ratings reflects agricultural mechanization patterns, while premium ratings serve industrial motor-start demands.
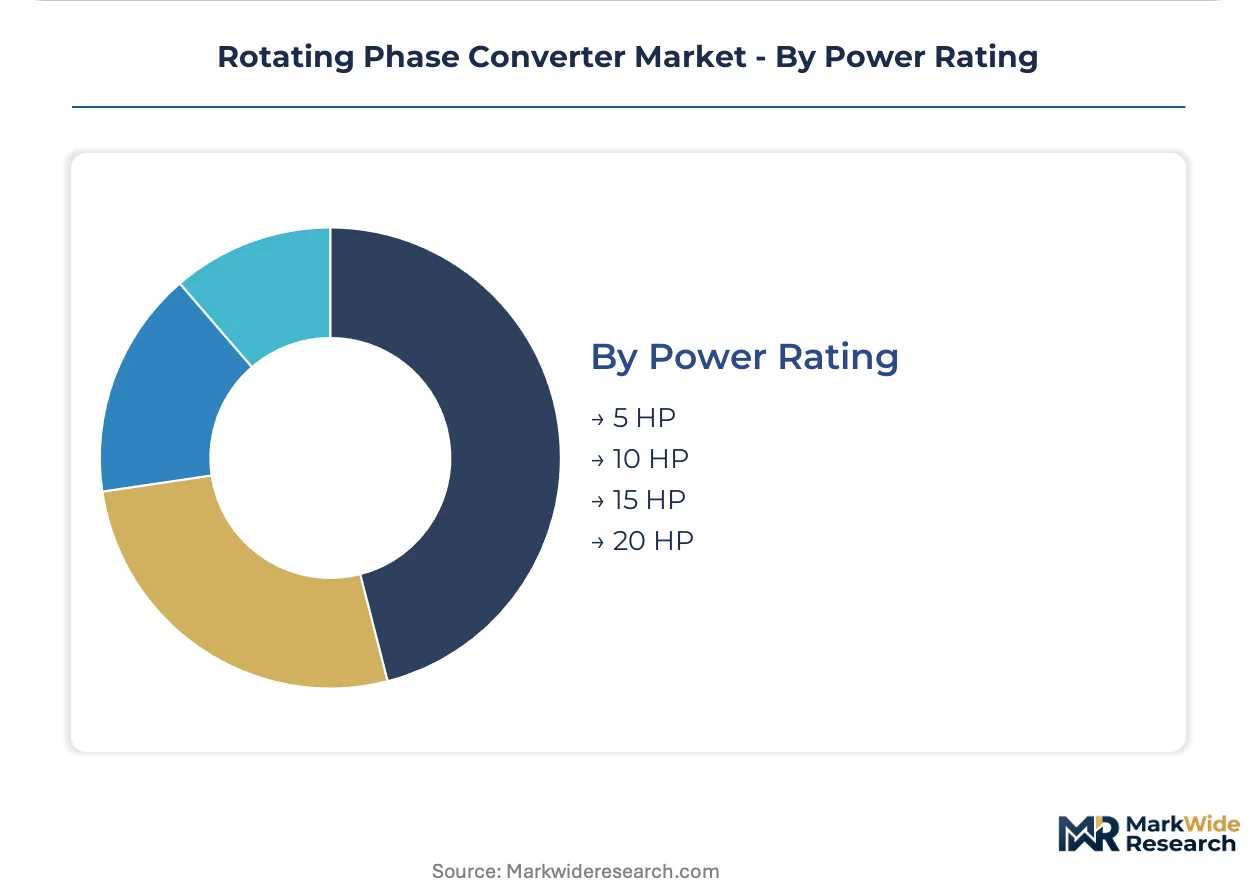
- 5 HP:Entry-level segment serving small machine shops, residential-scale agricultural equipment, and light commercial HVAC retrofits.
- 10 HP:Mid-range specification for grain handling systems, medium machine tools, and irrigation pump clusters across Midwest farm operations.
- 15 HP:Industrial threshold where digital control segments begin displacing rotary architectures in precision manufacturing environments.
- 20 HP:Heavy-duty rating for large motor-start applications in manufacturing and agricultural processing facilities requiring sustained three-phase capacity.
10 HP ratings anchor volume deployment; 15 HP segments climb the fastest as precision manufacturing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the US Midwest exhibit the lowest price elasticity as rural electrification gaps force premium payments for three-phase conversion, while cost-sensitive agricultural operators in developing markets drive volume through basic static units.
United States
Grain elevator operators across Iowa and Nebraska are retrofitting irrigation pumps and handling systems with rotary phase converters as utility three-phase extensions face multi-year backlogs. OSHA electrical safety regulations mandate NEMA 3R enclosures and visible blade disconnects for all commercial installations. Chicago-area precision manufacturers drive digital converter adoption for CNC voltage stability requirements.
Canada
Prairie province farmers in Saskatchewan and Alberta deploy rotary units for center-pivot irrigation expansion without awaiting cooperative infrastructure builds. The country's national electrical safety regulator enforces CSA C22.2 standards for industrial equipment enclosures and disconnect provisions. Ontario machine shops in the Kitchener-Waterloo corridor specify closed-loop digital systems for medical device component manufacturing.
Germany
Baden-Württemberg automotive suppliers require IEEE 519-compliant rotary units for legacy production line motor-start applications amid three-phase grid stability concerns. The EU Green Deal's industrial efficiency directives accelerate motor replacement cycles requiring phase conversion equipment. Munich-area precision engineering firms drive premium digital converter specification for metrology and semiconductor test equipment.
China
Yangtze River Delta manufacturing clusters deploy hybrid converter-genset configurations to address dual carbon goals and backup power requirements amid grid reliability challenges. The Ministry of Industry and Information Technology enforces GB standards for motor efficiency and power quality in industrial settings. Shenzhen electronics fabricators specify DSP-based voltage regulation for SMT line equipment requiring sub-1% voltage fluctuation tolerance.
India
Gujarat textile processors and Tamil Nadu pump manufacturers adopt static phase converters for sub-10 horsepower applications where harmonic tolerance permits cost minimization. The Bureau of Indian Standards mandates IS 12615 efficiency compliance for three-phase motor installations. Maharashtra agricultural equipment dealers in Nashik and Pune districts report accelerating rotary converter demand as farmers mechanize grape and sugarcane processing operations.
Rotating Phase Converter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive motor-winding capabilities separating margin-sustainable producers from assembly-dependent competitors. The middle tier contains regional fabricators serving agricultural duty cycles through field-proven designs. Three archetypes dominate: integrated manufacturers controlling core component production, distribution-focused assemblers sourcing wound motors externally, and military-grade specialists commanding premium positioning through harsh-environment certifications. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms address raw material volatility and certification timeline pressures.
Within the integrated manufacturing tier, American Rotary and RONK occupy positions distinguished by captive production capabilities and agricultural market anchoring respectively. Power Systems & Controls exemplifies the military-grade specialist archetype. Among these, American Rotary represents backward integration into motor winding, RONK anchors decades of field deployment in grain handling applications, and Power Systems & Controls sits within the premium segment through extended lifespan specifications for demanding environments.
| Leading Market Players |
|---|
| Steelman |
| RONK |
| Phase A Matic |
| Power Systems & Controls |
| NAPCES |
| American Rotary |
| Georator |
| Transwave |
| Harman Electric |
| Others |
Value Network & Pricing Analysis
Copper-to-aluminum winding substitution in motor core production simultaneously redraws procurement geography toward Southeast Asian coil suppliers and compresses unit economics for mid-range rotary converter tiers. This material transition rewards manufacturers with captive metallurgy capabilities while exposing assembly-dependent competitors to volatile LME pricing spreads.
Pricing Analysis
After-sales service contracts and spare rotor assemblies generate lifetime value multiples exceeding initial equipment margins by substantial ratios. Three-tier pricing structure across NEMA premium efficiency, standard duty, and agricultural economy levels segments buyer willingness-to-pay by certification grade and enclosure rating. Pricing pressure stems from electronic converter encroachment in sub-15 horsepower applications where harmonic tolerance requirements remain relaxed. Small machine shops and residential agricultural operators exhibit highest price sensitivity, while large industrial facilities with CNC voltage stability demands accept substantial premiums for closed-loop digital systems.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Busan port congestion have elevated landed costs for laminated steel cores and precision bearings sourced from East Asian foundries. Motor winding operations concentrate in Mexico, China, and domestic US facilities with NEMA certification capabilities. Supply chains draw from copper cathode markets in Chile and Peru, electrical steel from Japanese and Korean mills, and aluminum alloys from domestic smelters. Single-source vulnerability in precision bearing supply creates chokepoint exposure for high-horsepower rotary units. Distribution runs through rural electric cooperative rebate programs and agricultural equipment dealer networks across the US Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rotating phase converter market sits in early-cycle expansion as agricultural mechanization accelerates three-phase equipment deployment without utility infrastructure parity. NEMA efficiency mandates and IEEE power quality standards extend replacement demand beyond initial installation cycles.
For Market Incumbents: Shield installed base relationships through captive motor-winding capacity expansion and NEMA MG-1 certification pipeline investment. Digital converter substitution in precision manufacturing segments threatens premium rotary unit margins above 15 horsepower. Vertical integration into aluminum winding metallurgy and dust-tight enclosure fabrication defends margin structures against raw material volatility. For New Entrants and Emerging Players: Aftermarket service coverage gaps in remote agricultural counties present white-space entry points for mobile repair and emergency replacement networks. Wisconsin and Minnesota precision manufacturing clusters offer lowest competitive density for DSP-based voltage regulation systems. Contractor certification programs and rural electric cooperative vendor approval pathways accelerate channel access faster than traditional distributor relationships. For Investors and Strategic Acquirers: The market sits at an infrastructure-lag phase that favors integrated manufacturers with captive component production and field-proven agricultural duty cycle designs. Five-to-ten year viability hinges on NEPA and state-level rural electrification grant program continuity supporting hybrid converter-line-extension deployments. Monitor Iowa and Nebraska utility three-phase extension backlog clearance rates as demand substitution inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Winding | Captive coil production insulates margin structures from copper volatility and NEMA certification delays. |
| NEMA MG-1 Efficiency Tier Certification | Laboratory validation unlocks specification in OSHA-mandated commercial installations and utility rebate programs. |
| Hybrid Converter-Genset Development | EPA standby generator compliance integration addresses critical agricultural backup power requirements in grid-reliability-constrained regions. |
| Rural Electric Cooperative Partnership | Approved vendor status redirects procurement volume from independent distributors toward manufacturer-direct channels. |
| Digital Signal Processor Platform Launch | Voltage regulation precision captures CNC machine shop and medical imaging specifications beyond rotary unit capabilities. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at grain handling facilities, electrical contractors serving agricultural retrofit projects, OEM procurement teams at CNC machine tool manufacturers, and aftermarket service managers at rotating equipment distributors, then refined through secondary validation against NEMA MG-1 technical standards, IEEE 519 power quality documentation, OSHA electrical safety enforcement records, and rural electric cooperative grant program filings. Bottom-up equipment shipment data triangulated against top-down utility infrastructure investment forecasts.
Variance decomposition across technology type, power rating tier, application vertical, and regional electrification gap intensity structured the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by NEMA efficiency mandate compliance deadlines and agricultural mechanization investment cycles. Forecast inputs incorporated copper and electrical steel price trajectory assumptions, utility three-phase extension backlog projections, and electronic converter performance improvement rates.
Forecasts assume regulatory continuity in NEPA environmental review processes, state rural electrification grant programs, and OSHA electrical safety enforcement; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Denmark Power Market
Power
Power Purchase Agreement Market
Power
Gas Freeing Fan Market
Power
Resonant Power Converters Market
Power
Sudan Power EPC Market
Power
Europe Power Purchase Agreement Market
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
Residential Micro Inverter Market
Power
Static Synchronous Compensator (STATCOM) Market
Power
Saudi Arabia Power Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Middle-East and Africa Power Market
Power
Global Ancillary Services Power Market
Power
Germany Solar Inverter Market
Power
Japan Power Market
Power
Marine Thermal Fluid Heaters Market