
 Asia-Pacific Power Purchase Agreement Market | 2026-2036
Asia-Pacific Power Purchase Agreement Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Power Purchase Agreement Market Analytics
China's dual carbon goals is rebalancing the cost-of-entry calculus for new renewable developers, forcing capital allocation toward grid-scale storage co-location. State Grid Corporation of China leverages its transmission monopoly to secure preferential dispatch for contracted renewable capacity. Tata Power Company anchors its competitive position through backward integration into solar module manufacturing and captive land banks. Korea Electric Power Corporation navigates regulatory uncertainty around the K-RE100 initiative by diversifying its PPA origination across both utility-scale and commercial off-takers.
A power purchase agreement constitutes a long-term contract between a power generator and a buyer, typically spanning 10-25 years, specifying price terms, delivery points, and renewable energy certificate transfer mechanisms for electricity generated from solar, wind, hydro, or biomass assets. Corporate PPAs now dominate transaction volume as multinational manufacturers seek price hedges against volatile wholesale electricity markets, while virtual PPAs attract financial institutions desiring renewable exposure without physical delivery obligations. Utility PPAs retain structural importance in markets with single-buyer models, though margin pools increasingly concentrate in short-term and rolling contract structures that offer flexibility to grid operators managing intermittency.
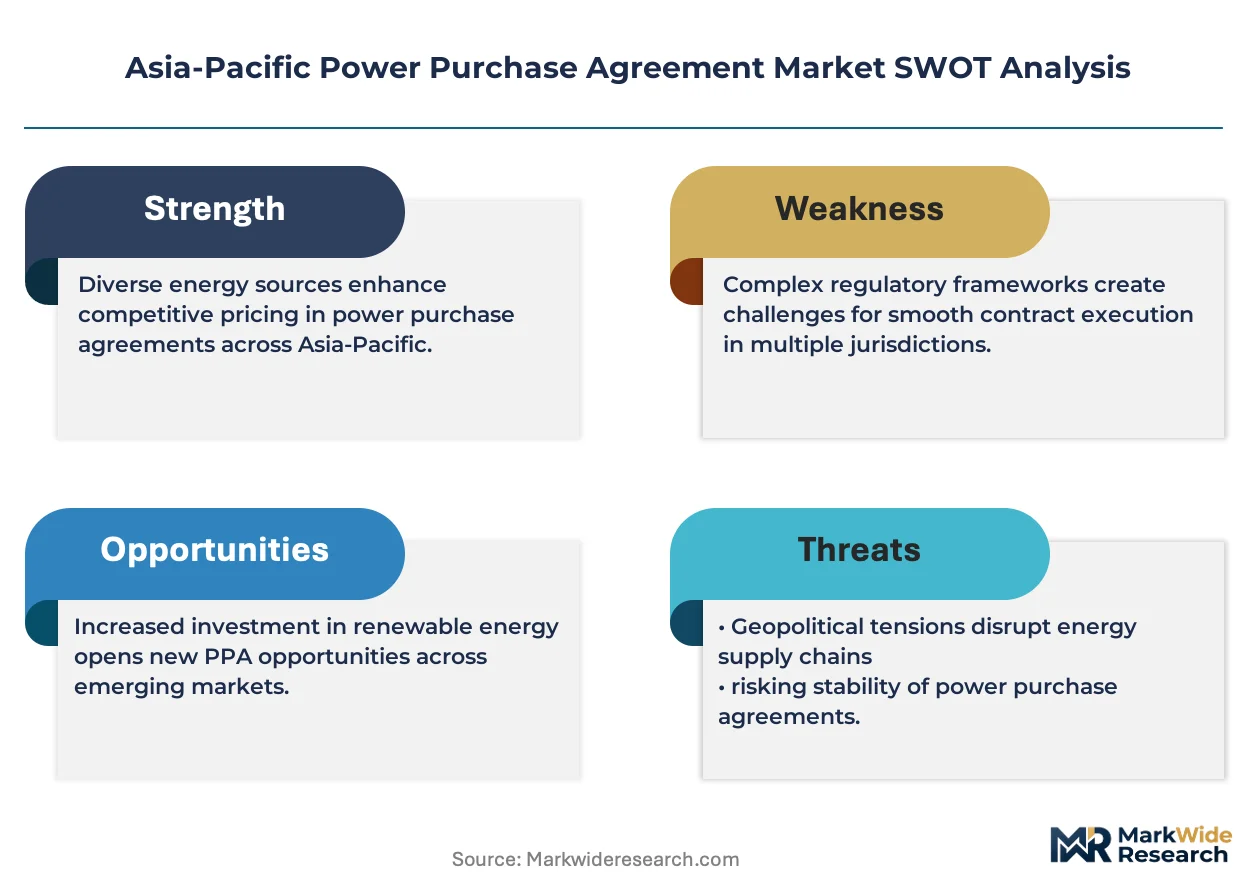
India's CEA mandates renewable purchase obligations that state distribution companies must fulfill through PPAs or face penalties, while China's MEE enforces provincial emission intensity targets that indirectly compel industrial users into clean energy contracting. Japan's METI feed-in-tariff transition to market-based procurement is forcing developers to negotiate corporate offtake before financial close. Stakeholders must monitor how evolving grid codes across the region treat curtailment risk allocation, as this clause increasingly determines bankability and pricing outcomes.
Market Dynamics
China's dual carbon goals are compressing project timelines and forcing developers to co-locate grid-scale storage with renewable assets before interconnection approval. This structural pressure cascades across procurement contracts, pricing benchmarks, and offtake negotiation strategies throughout the region.
Growth Catalysts
- Renewable Purchase Obligations:India's CEA mandates that state distribution companies secure minimum clean energy shares through PPAs or face financial penalties, compelling contract origination.
- Corporate Carbon Neutrality Pledges:Technology and electronics manufacturers across Taiwan, South Korea, and Vietnam are signing long-term corporate PPAs to hedge against volatile wholesale electricity markets.
- Provincial Emission Intensity Targets:China's MEE enforces binding clean energy consumption ratios for industrial users in eastern coastal provinces, redirecting procurement toward contracted renewable capacity.
Market Restraints
- Polysilicon Supply Concentration:Module production relies on polysilicon refining capacity concentrated in Xinjiang and Inner Mongolia, exposing developers to input cost volatility and trade compliance risks.
- Single-Buyer Model Rigidity:State-owned distribution companies in several Southeast Asian markets retain monopoly procurement rights, limiting direct corporate PPA structures and compressing developer margins.
- Grid Interconnection Queues:Transmission upgrade backlogs in India's renewable-rich western states delay project energization and extend revenue recognition timelines beyond financial model assumptions.
Strategic Opportunities
- Vietnam's Direct Power Purchase Mechanism:The pilot program allowing industrial consumers to contract directly with renewable generators bypasses the single-buyer constraint and opens private offtake channels.
- Green Hydrogen Production:Electrolyzer offtake agreements tied to dedicated renewable supply are emerging as a new PPA application class in Australia's Pilbara and Queensland regions.
- Virtual PPA Structures:Financial institutions and multinational corporates without physical load in the region are seeking synthetic exposure to renewable price benchmarks without delivery obligations.
Industry Challenges
- Grid Code Harmonization:Evolving technical standards for frequency response and reactive power across Japan's regional utilities create certification complexity for equipment suppliers and project developers.
- Curtailment Risk Allocation:Negotiating force majeure and economic dispatch clauses that satisfy lender requirements while remaining acceptable to offtakers demands specialized legal expertise scarce in emerging markets.
- Land Acquisition and Conversion:Securing contiguous parcels with clear title and permissible use for utility-scale solar in India's Maharashtra and Rajasthan states faces bureaucratic delays and litigation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Power Purchase Agreement Market |
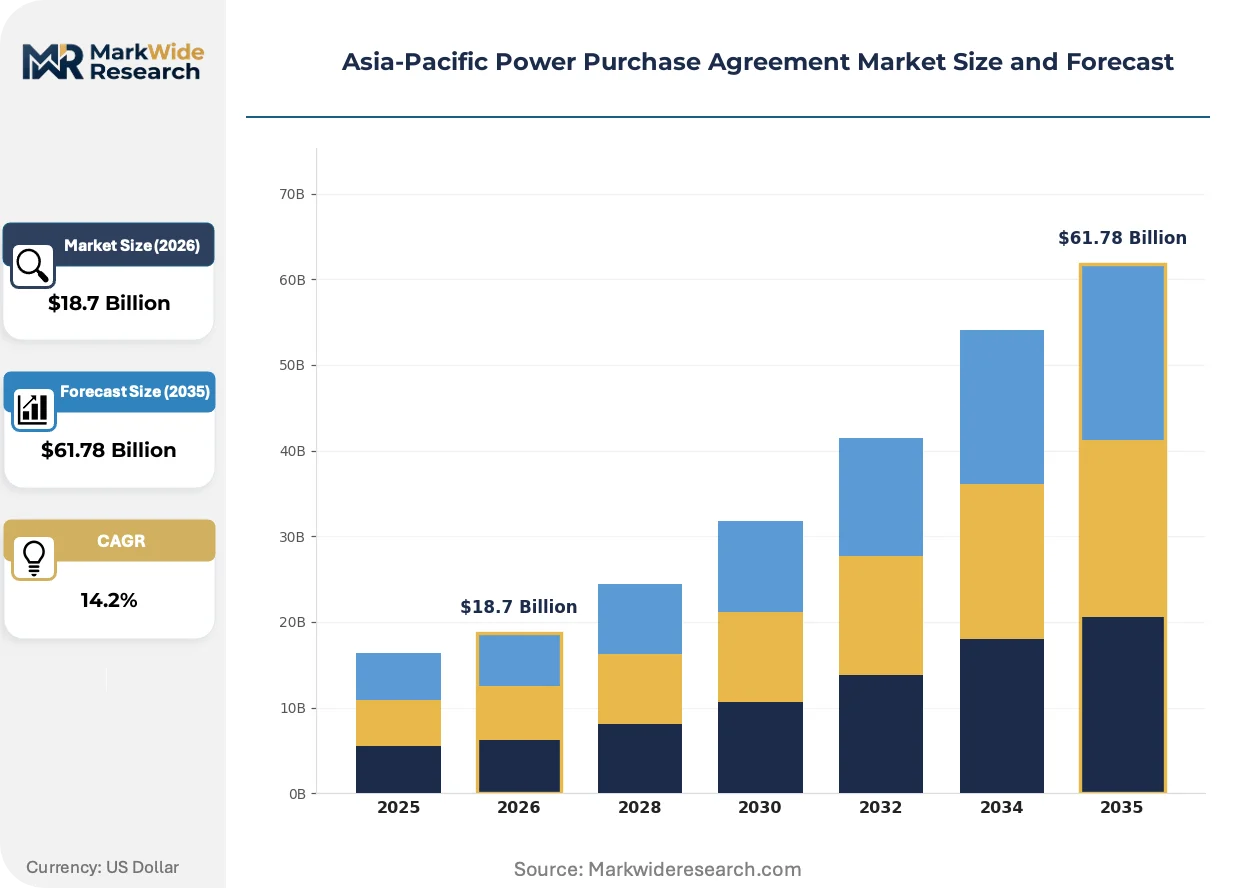
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transaction Type: Corporate PPA, Utility PPA, Virtual PPA, Physical PPA Power Source: Solar Energy, Wind Energy, Hydropower, Biomass Energy Contract Duration: Short-term, Medium-term, Long-term, Rolling Contract End User Sector: Manufacturing, Commercial, Residential, Government |
| Companies Covered | State Grid Corporation of China, Power Construction Corporation of China, National Thermal Power Corporation Limited, China Huaneng Group, China Huadian Corporation, Tata Power Company, Korea Electric Power Corporation, Tokyo Electric Power Company Holdings, Trina Solar, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Power Purchase Agreement Market Evolving Landscape
Battery energy storage systems are becoming standard co-located infrastructure rather than optional add-ons, reshaping how developers structure revenue stacks and offtake contracts. This hardware convergence is compressing traditional boundaries between generation and grid services.
Co-located battery energy storage is consolidating the revenue model for utility-scale solar projects in China and Australia. Industrial offtakers with 24-hour load profiles are demanding firm capacity guarantees that only hybrid configurations can deliver. This technology bundling is compressing standalone solar project bankability and redirecting capital toward integrated asset classes.
Japan's METI feed-in-tariff transition to market-based procurement is forcing developers to secure corporate offtake agreements before financial close. The policy sunset eliminates guaranteed pricing for new projects and redirects risk to private contract negotiation. Developers are responding by front-loading origination teams and shortening exclusivity periods with landowners.
Long-term contract tenors are shortening as buyers seek flexibility to adapt to evolving carbon accounting standards and load growth uncertainty. Technology companies with aggressive net-zero deadlines are displacing traditional 20-year structures with 10-12 year agreements plus renewal options. This compression is most visible in South Korea's K-RE100 procurement clusters around Seoul and Busan.
Asia-Pacific Power Purchase Agreement Market Segmentation
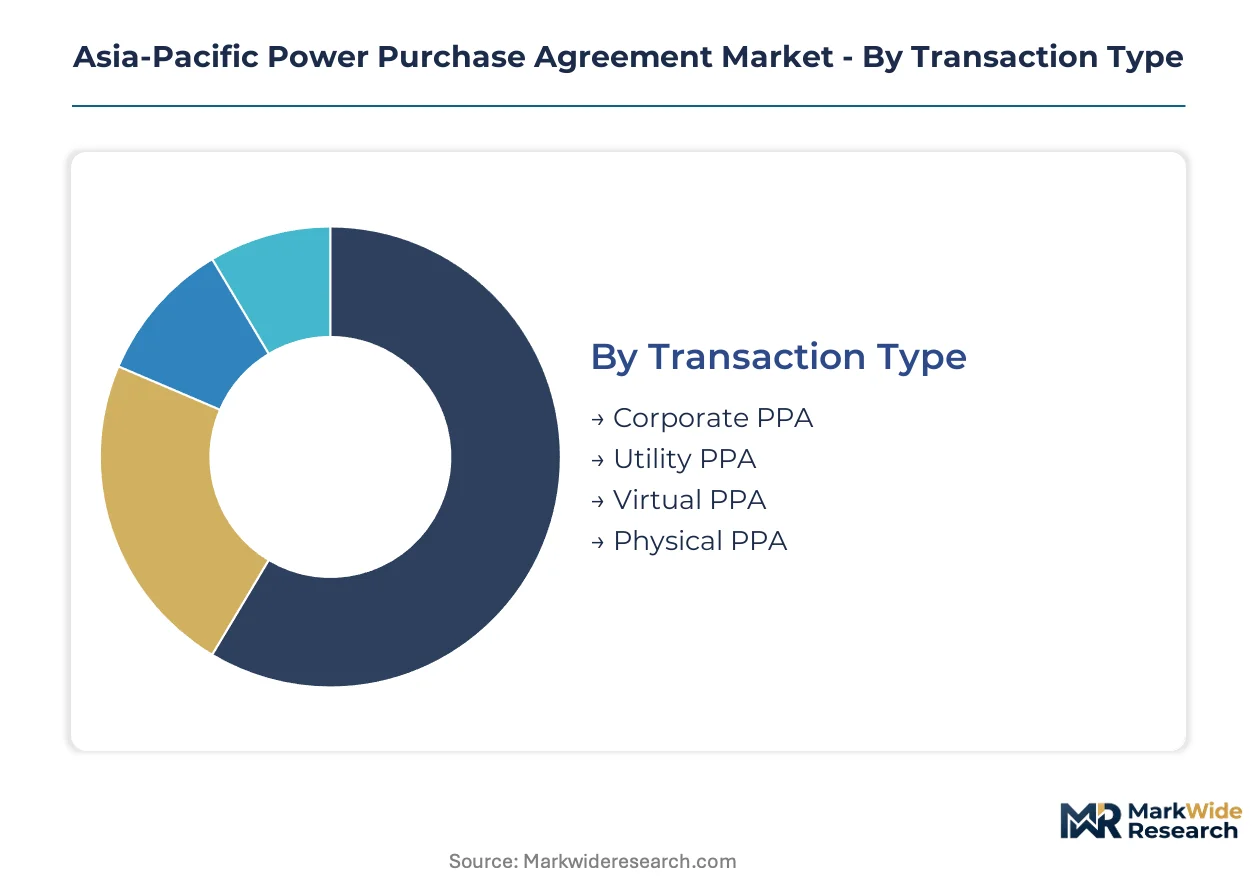
PPA market segmentation reveals how capital allocation, risk appetite, and regulatory exposure vary across contract structures and generation technologies. Each dimension carries distinct bankability requirements and offtake negotiation dynamics that reshape developer strategies across the Asia-Pacific region.
Transaction Type:
Capital intensity varies sharply across transaction structures, with physical delivery contracts demanding grid interconnection investments that synthetic arrangements bypass entirely.
- Corporate PPA:Direct bilateral contracts between renewable generators and industrial or commercial consumers, typically featuring fixed-price escalators and renewable energy certificate transfer clauses. Demand concentrates among semiconductor and electronics manufacturers in Taiwan and South Korea seeking price hedges against volatile wholesale markets, driven by supply chain decarbonization mandates from multinational parent companies.
- Utility PPA:Long-term procurement agreements with state-owned distribution companies in single-buyer markets, often incorporating take-or-pay obligations and regulated tariff benchmarks. India's state discoms anchor volume through renewable purchase obligations enforced by CEA, though payment security mechanisms and late payment surcharges remain contested negotiation points.
- Virtual PPA:Financial contracts providing price exposure to renewable generation without physical delivery, executed as contracts-for-difference against regional power benchmarks.
- Physical PPA:Contracts with explicit scheduling and delivery obligations, requiring grid interconnection and transmission access rights.
Most installed capacity flows through Utility PPA structures. Expansion is steepest in Corporate PPA origination.
Power Source:
Technology selection tracks resource endowment, land availability, and dispatch profile requirements across diverse Asia-Pacific geographies.
- Solar Energy:Photovoltaic and concentrated solar power installations dominating new capacity additions, with module supply chains increasingly localized under India's PLI scheme and China's manufacturing scale. Deployment clusters in India's Rajasthan and Gujarat states, driven by high irradiance and available wasteland parcels.
- Wind Energy:Onshore and offshore turbine installations providing higher capacity factors but facing longer development timelines and environmental clearance complexities. China's eastern coastal provinces and Vietnam's Mekong Delta region concentrate demand, propelled by provincial renewable portfolio standards and offshore seabed lease auctions.
- Hydropower:Run-of-river and reservoir-based generation with long asset lifespans and limited intermittency.
- Biomass Energy:Agricultural residue and dedicated energy crop combustion with baseload dispatch characteristics.
Solar Energy carries the dominant share of contracted capacity. Offshore Wind Energy is gaining share fastest among new PPA signings.
Contract Duration:
Tenor selection reflects the tension between lender requirements for long revenue visibility and buyer preferences for operational flexibility.
- Short-term:Agreements under five years, typically serving as bridge financing or merchant exposure vehicles.
- Medium-term:Five-to-ten year structures balancing bankability with buyer flexibility, increasingly favored by technology sector offtakers with uncertain load growth trajectories.
- Long-term:Fifteen-to-twenty-five year contracts with fixed or escalating price schedules, standard for utility-scale solar and wind projects seeking project finance. Japanese developers are front-loading origination before METI feed-in-tariff expiration forces market-based pricing.
- Rolling Contract:Automatically renewing agreements with periodic price renegotiation clauses.
Long-term contracts still dominate utility-scale project finance. Medium-term structures are climbing fastest in corporate origination.
End User Sector:
Sectoral demand patterns map directly to emission intensity profiles and carbon disclosure pressures across industrial supply chains.
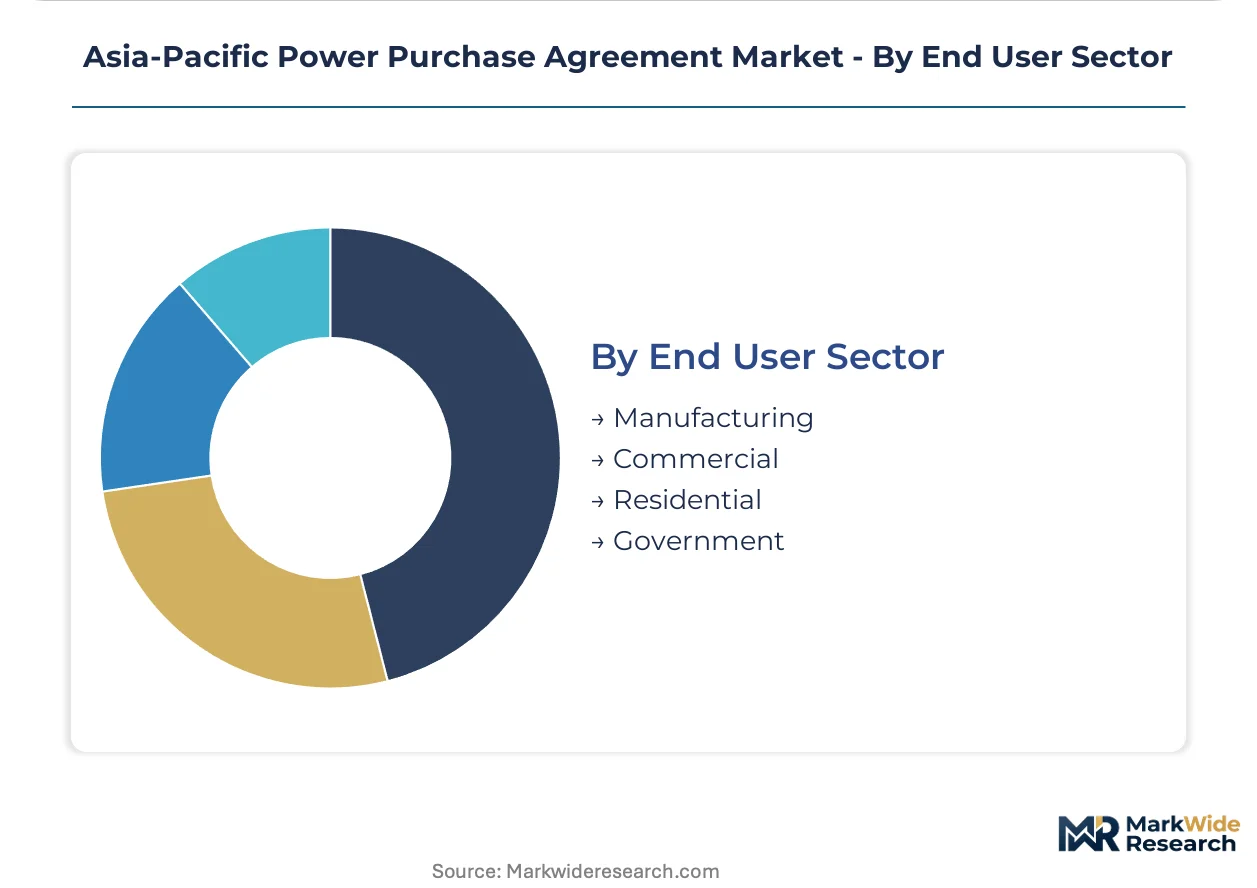
- Manufacturing:Energy-intensive industrial facilities including steel, cement, chemicals, and electronics assembly with 24-hour baseload requirements. South Korea's K-RE100 procurement clusters around Seoul and Busan manufacturing zones, driven by export market access conditions requiring renewable energy verification.
- Commercial:Office buildings, retail chains, and data centers with daytime-peaking load profiles well-matched to solar generation. Singapore and Hong Kong commercial landlords are signing aggregated PPAs to meet building efficiency mandates and tenant sustainability requirements.
- Residential:Individual household and apartment complex procurement through community solar or green tariff programs.
- Government:Public sector facilities and state-owned enterprise load centers with procurement subject to public tender regulations.
Manufacturing absorbs the largest share of contracted volume. Commercial sector origination is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools concentrated in Shanghai, Bangalore, and Seoul anchor the region's renewable origination capacity. Developer teams with grid interconnection expertise command premium compensation. Local regulatory knowledge determines contract structuring speed.
China
Provincial renewable portfolio standards in Jiangsu and Zhejiang compel industrial users into clean energy contracting. The MEE enforces binding emission intensity targets that redirect procurement toward contracted capacity. State Grid Corporation leverages its transmission monopoly to secure preferential dispatch for renewable assets in the Yangtze River Delta manufacturing belt.
India
State distribution companies in Maharashtra and Gujarat face renewable purchase obligations mandated by the CEA. The PLI scheme for solar manufacturing redirects procurement toward domestic module supply chains. Rajasthan's high irradiance and available wasteland parcels concentrate utility-scale solar deployment in the western renewable corridor.
Japan
Technology manufacturers with aggressive net-zero deadlines drive corporate PPA origination around Tokyo and Osaka. METI's feed-in-tariff transition to market-based procurement forces developers to secure offtake before financial close. Kyushu and Hokkaido host emerging offshore wind clusters seeking interconnection agreements.
South Korea
Semiconductor and electronics manufacturers in Seoul and Busan sign long-term contracts to hedge against volatile wholesale electricity markets. The K-RE100 initiative creates procurement clusters around manufacturing zones driven by export market access conditions. KEPCO navigates regulatory uncertainty by diversifying origination across utility-scale and commercial offtakers.
Australia
Mining operations in the Pilbara and Queensland seek dedicated renewable supply for green hydrogen production electrolyzer offtake agreements. State-level renewable energy targets in New South Wales and Victoria accelerate grid-scale storage co-location requirements. Financial institutions without physical load seek synthetic exposure through virtual PPA structures.
Asia-Pacific Power Purchase Agreement Market Competitive Landscape
The competitive structure tilts toward state-backed integrated utilities with transmission control and captive generation portfolios. Market concentration reflects the dominance of national champions in single-buyer electricity markets. Three archetypes prevail: transmission-owning utilities securing preferential dispatch, vertically integrated developers controlling module supply chains, and renewable pure-plays specializing in corporate origination. Capacity expansion and strategic partnerships dominate competitive moves as players race to secure interconnection rights and land positions.
Among state-backed Chinese utilities, State Grid Corporation of China and China Huaneng Group occupy positions reflecting transmission monopoly advantages and generation scale. Tata Power Company exemplifies the vertically integrated archetype through backward integration into solar module manufacturing and captive land banks. Korea Electric Power Corporation sits within the transmission-utility tier navigating procurement diversification across multiple offtake channels.
| Leading Market Players |
|---|
| State Grid Corporation of China |
| Power Construction Corporation of China |
| National Thermal Power Corporation Limited |
| China Huaneng Group |
| China Huadian Corporation |
| Tata Power Company |
| Korea Electric Power Corporation |
| Tokyo Electric Power Company Holdings |
| Trina Solar |
| Others |
Value Network & Pricing Analysis
Sovereign-backed utilities with transmission monopolies anchor pricing discipline across the Asia-Pacific PPA landscape. State Grid Corporation of China's preferential dispatch rights and Korea Electric Power Corporation's diversified origination channels compress margins for private developers while stabilizing long-term contract benchmarks.
Pricing Analysis
Bundled firm capacity guarantees command premiums over unbundled energy-only contracts as industrial offtakers seek 24-hour dispatch certainty. Price differentiation rests on storage co-location requirements and renewable certificate transfer clauses, with technology companies showing lowest sensitivity due to carbon-neutral pledges while state distribution companies resist escalation clauses. Cost compression in utility-scale solar PPAs is intensifying because India's PLI scheme expands domestic module supply. Merchant-exposed developers face the sharpest pricing pressure from interconnection queue delays.
Supply Chain Analysis
Freight and logistics costs from Xinjiang and Inner Mongolia polysilicon refining centers to coastal module assembly plants feed directly into PPA pricing floors. Module production draws from polysilicon ingots, EVA encapsulant films, and aluminum framing systems concentrated in China, South Korea, and Vietnam. Single-source vulnerability to Xinjiang-origin material trade compliance risks threatens developer procurement timelines. Distribution runs through state-owned transmission monopolies in single-buyer markets and bilateral direct-wire arrangements in liberalized jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific PPA market offers margin expansion through co-located storage premiums and shortened corporate contract tenors that accelerate capital recovery. Module supply chain localization under India's PLI scheme and China's manufacturing scale creates cost-down runway for integrated developers.
For Market Incumbents: Deploy grid-scale storage co-location as the primary defensive lever against standalone solar margin erosion. State-backed utilities should secure additional interconnection rights in India's western renewable corridor before queue backlogs worsen. Vertically integrated developers must defend position through captive polysilicon offtake arrangements that insulate against Xinjiang trade compliance disruptions. For New Entrants and Emerging Players: Capture Vietnam's direct power purchase mechanism pilot as the most penetrable regulatory opening, bypassing single-buyer constraints in Southeast Asian markets. Green hydrogen electrolyzer offtake agreements in Australia's Pilbara region represent uncrowded white-space. A specialized legal advisory go-to-market angle addressing curtailment risk allocation bankability gaps commands premium positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among renewable pure-plays lacking transmission ownership or module manufacturing integration. Long-term viability over the coming decade hinges on corporate origination capabilities and storage technology bundling expertise. Watch for METI feed-in-tariff transition completion as the signal indicating Japanese market-based pricing normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Storage Co-location Buildout | Hybrid solar-plus-battery configurations satisfy firm capacity demands from 24-hour industrial offtakers. |
| Corporate PPA Origination | Direct bilateral contracts with semiconductor manufacturers hedge against volatile wholesale electricity benchmarks. |
| Module Supply Integration | Backward integration into solar manufacturing captures PLI scheme incentives and insulates input cost volatility. |
| Virtual PPA Structuring | Synthetic exposure instruments attract financial institutions without physical load in the region. |
| Green Hydrogen Offtake Tying | Electrolyzer agreements in Australia's Pilbara create new PPA application classes with dedicated renewable supply. |
Research Methodology
Coverage spans China, India, Japan, South Korea, and Australia, with primary inputs from each market's regulatory and development stakeholders. The analysis combines interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators alongside secondary validation through EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity and contract tracking triangulates against top-down regulatory mandate analysis.
Rate-of-change decomposition separates volume growth from pricing evolution across the projection horizon. The analytical framework models segmentation by transaction type, power source, contract duration, and end-user sector alongside regional grid type and regulatory framework clustering. CAGRs derive from installed capacity pipelines, renewable purchase obligation enforcement trajectories, and corporate procurement commitment tracking.
Policy implementation delays, grid interconnection queue extensions, and polysilicon trade restriction escalations are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Europe Microturbine Market
Power
Green UPS Market
Power
Existent Gum Steam Generator Market
Power
Electric Power Sports Market
Power
Global UPS Market
Power
Vietnam Power Market
Power
Iran Power Market
Power
Power Capacitors Market
Power
Distributed Buoyancy Modules Market
Power
Uzbekistan Power Market
Power
Digital Power Utility Market
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
Global Diesel Power Engine Market
Power
Kuwait Power Market
Power
Italy Power EPC Market
Power
United States Power Market