
 Equatorial Guinea Power Market | 2026-2036
Equatorial Guinea Power Market Size, Share, and Industry Trends Forecast 2026-2036
Equatorial Guinea Power Market Foresight
ISO 50001 energy management certification is rotating the competitive field, favoring operators with verified efficiency systems. Wärtsilä Oyj Abp leverages its dual-fuel engine portfolio to anchor gas-to-power installations near hydrocarbon infrastructure. Sociedad de Electricidad de Guinea Ecuatorial sustains grid monopoly through transmission assets spanning Bioko and Río Muni. Segesa competes on rural electrification concessions, while TotalEnergies controls upstream gas supply that feeds thermal generation feedstock.
Equatorial Guinea power encompasses electricity production, transmission, and distribution infrastructure serving a market where thermal plants operate at 30-40% efficiency due to aging steam cycles and fuel quality variability. The system exists primarily to convert domestic gas reserves into grid-stable voltage for industrial and residential loads. Thermal generation dominates installed capacity, though solar represents the fastest-growing type as distributed PV displaces diesel in off-grid clusters. Gas turbine technology leads the technology mix, aligning with available feedstock from the Alba and Zafiro fields. Industrial application commands the largest share of delivered megawatt-hours, driven by methanol and LNG plant offtake agreements.
The Ministry of Mines and Hydrocarbons governs upstream gas allocation and power purchase frameworks, while the national electricity regulator sets tariff bands and connection standards. These bodies shape market access by conditioning generation licenses on domestic supply obligations and grid code compliance. Stakeholders must monitor how gas reserve depletion timelines interact with renewable procurement mandates to determine optimal asset positioning.
Market Dynamics
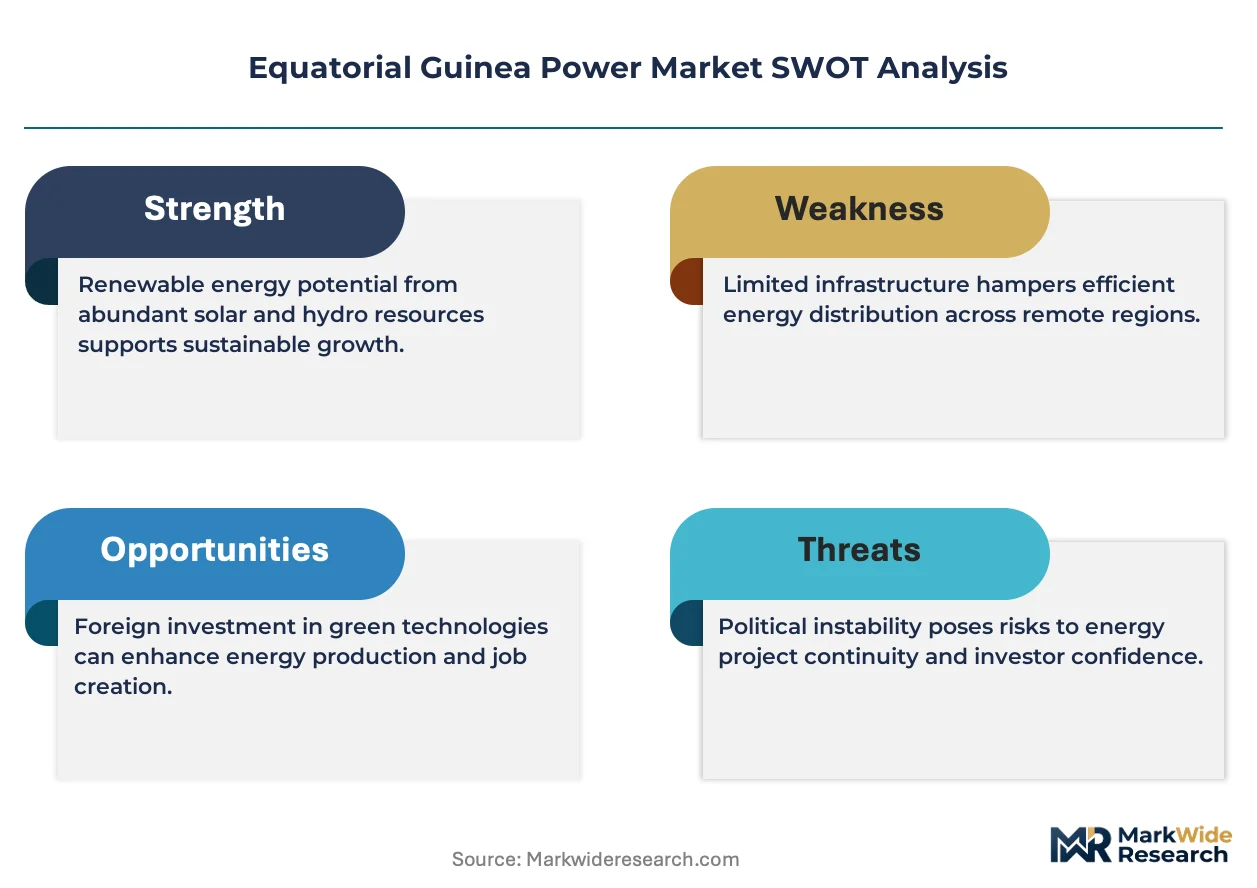
Gas reserve depletion timelines are compressing investment horizons across Equatorial Guinea's thermal-heavy generation base, forcing operators to front-load renewable procurement decisions ahead of regulatory mandates.
Growth Catalysts
- Domestic Gas Supply Obligations:The Ministry of Mines and Hydrocarbons mandates upstream producers to allocate feedstock for power generation, ensuring captive fuel access for thermal plants near Alba and Zafiro infrastructure.
- Industrial Captive Demand:Methanol and LNG facility offtakers seek dedicated generation capacity, creating anchor loads that justify transmission upgrades across Bioko Island.
- Solar-Diesel Hybrid Systems:Distributed PV installations are displacing diesel gensets in off-grid clusters across Río Muni, reducing fuel import dependency for remote commercial loads.
Market Restraints
- Single-Grid Architecture:Sociedad de Electricidad de Guinea Ecuatorial's transmission monopoly creates structural barriers for independent power producers seeking wheeling arrangements.
- Reserve Depletion Risk:Proven gas field timelines constrain long-term power purchase agreement tenors, limiting project finance availability for greenfield thermal assets.
- Aging Steam Cycle Efficiency:Existing thermal plants operate at 30-40% thermal efficiency due to dated turbine technology and fuel quality variability, capping output per unit of feedstock.
Strategic Opportunities
- Río Muni Electrification Gap:Continental region grid penetration lags Bioko Island, creating concession opportunities for distributed generation and mini-grid operators.
- ISO 50001 Certification Premium:Energy management system verification is rotating competitive positioning, favoring operators with documented efficiency protocols in industrial offtake tenders.
- Dual-Fuel Engine Retrofits:Wärtsilä Oyj Abp's technology portfolio enables fuel-switching capability, allowing plants to pivot between gas and liquid fuels as domestic supply fluctuates.
Industry Challenges
- Grid Code Compliance Timelines:Connection standards for intermittent renewable sources lack clear certification pathways, delaying solar project commissioning.
- Specialized Technician Scarcity:Gas turbine maintenance and high-voltage substation operations require skills concentrated in Malabo, constraining Río Muni expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equatorial Guinea Power Market |
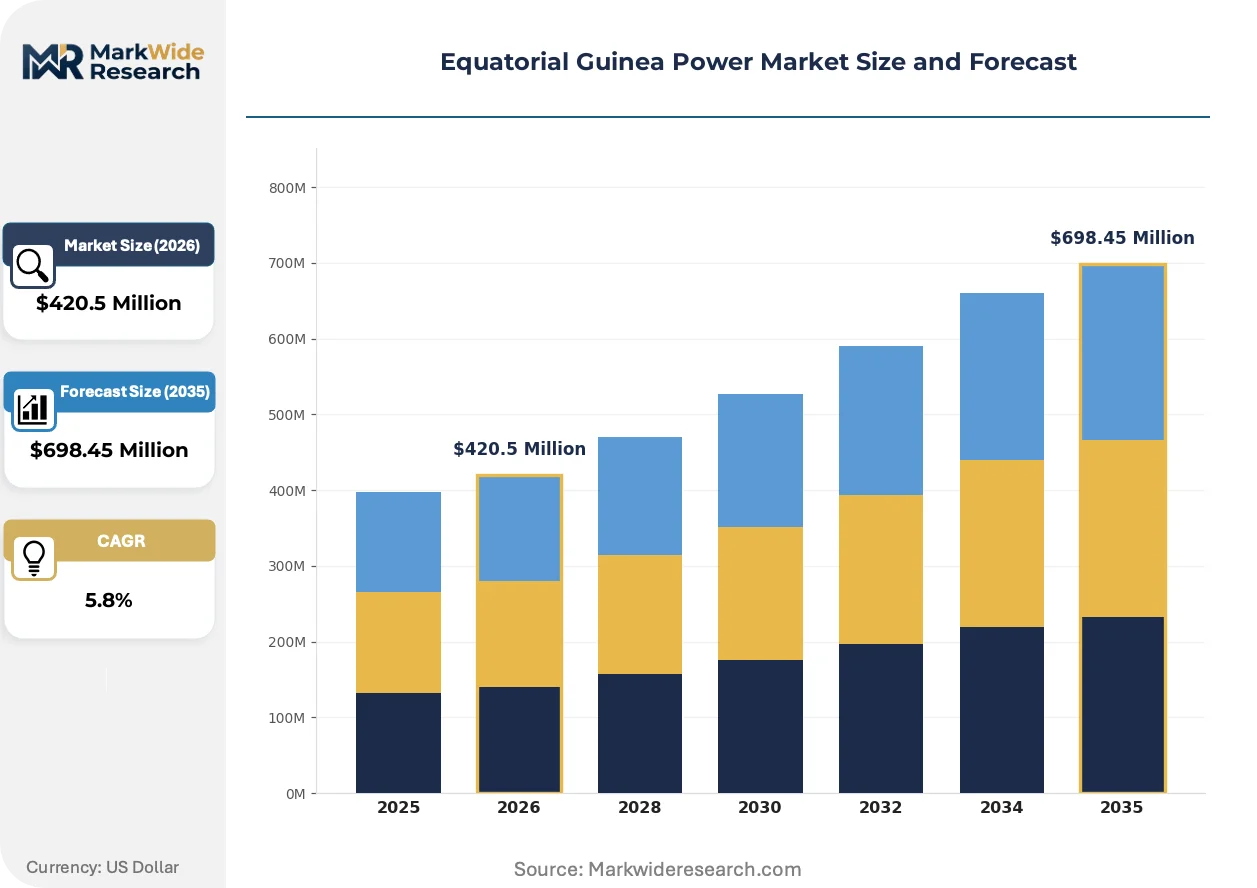
| Market Size in 2026 | $420.5 Million |
| Market Size in 2035 | $698.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Solar, Wind, Thermal, Hydro Technology: Gas Turbine, Steam Turbine, Biomass, Hydroelectric Application: Residential, Commercial, Industrial, Agricultural Service Type: Generation, Transmission, Distribution, Maintenance |
| Companies Covered | Wärtsilä Oyj Abp, Power Construction Corporation of China, Sociedad de Electricidad de Guinea Ecuatorial, Indra Sistemas, Segesa, TotalEnergies, ExxonMobil Corporation, Ophir Energy, Elenilto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equatorial Guinea Power Market Shifts & Advancements
Distributed generation architectures are redrawing the competitive map, eroding the centralized grid monopoly that has defined Equatorial Guinea's power sector for decades.
Containerized solar-plus-storage systems are fragmenting the traditional utility-scale procurement model. Remote mining and agricultural operations in Río Muni are adopting modular PV-battery configurations that bypass transmission infrastructure entirely. This technology is fragmenting revenue pools that previously consolidated around Sociedad de Electricidad de Guinea Ecuatorial's distribution network.
The Ministry of Mines and Hydrocarbons is tightening domestic supply obligation enforcement under national petroleum frameworks. This regulatory pressure is accelerating gas-to-power project development timelines as upstream operators seek to secure offtake agreements before reserve reclassification. Thermal generators with proximity to Alba field infrastructure are repositioning to capture preferential feedstock allocation.
Industrial offtakers are unbundling energy procurement from integrated service contracts. Methanol and LNG plants are negotiating direct generation agreements with independent producers, bypassing traditional utility intermediaries. This pattern concentrates in Bioko Island's load center where large thermal loads command bargaining leverage unavailable to smaller commercial consumers.
Equatorial Guinea Power Market Segmentation
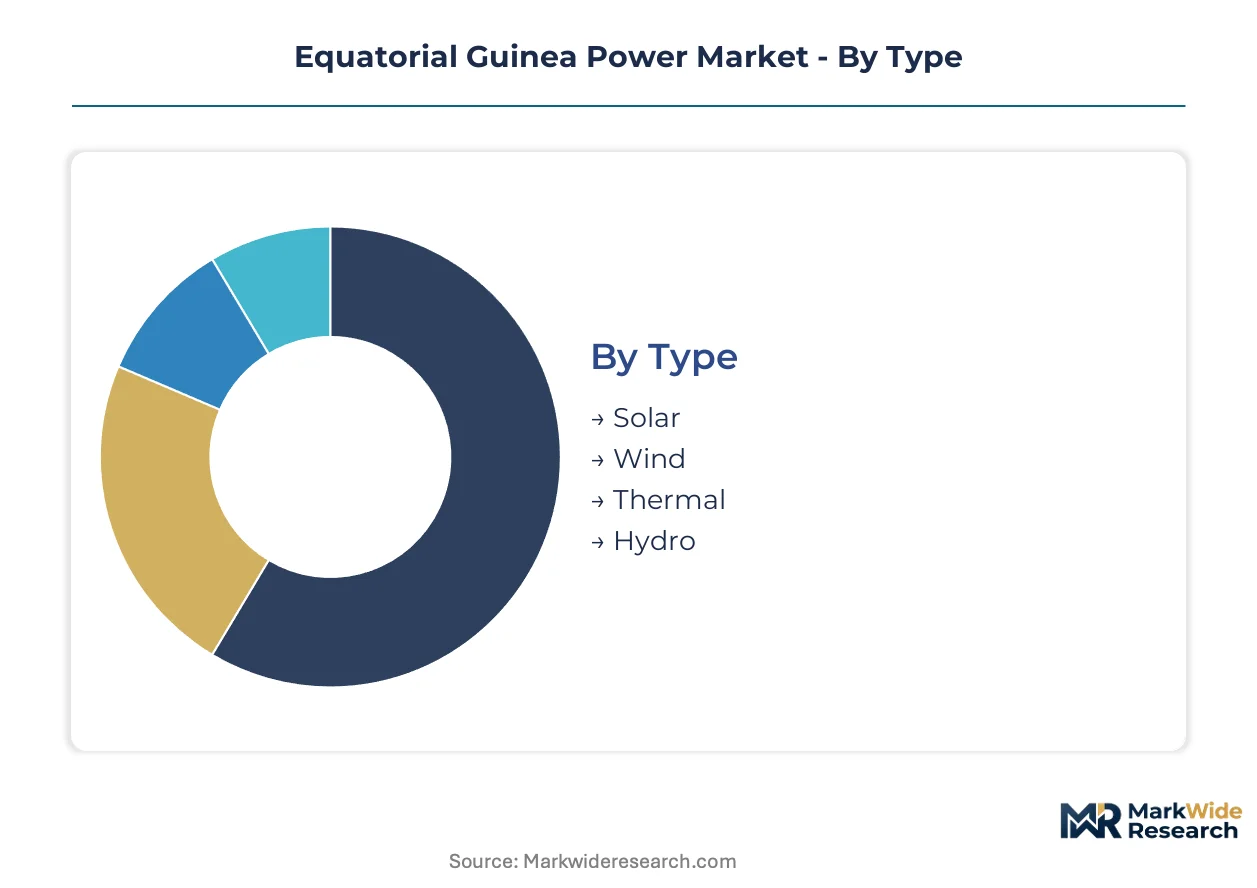
Segmentation reveals how Equatorial Guinea's power infrastructure aligns with regulatory mandates and resource endowments. The Ministry of Mines and Hydrocarbons conditions licensing on technology choices and application types, creating distinct competitive arenas across generation and grid services.
Type:
The Ministry of Mines and Hydrocarbons applies differentiated domestic supply obligations across generation types, conditioning feedstock access on technology classification.
- Thermal:Gas-fired plants convert domestic Alba and Zafiro field output into grid-stable baseload. Methanol and LNG facility offtakers on Bioko Island anchor demand for this segment despite reserve depletion timelines compressing long-term contract tenors.
- Solar:Distributed PV installations are displacing diesel gensets across Río Muni's off-grid clusters. Remote mining and agricultural operations adopt modular configurations that bypass Sociedad de Electricidad de Guinea Ecuatorial's transmission network entirely.
- Wind:Coastal and island sites on Bioko hold technical potential for small-scale generation, though development remains nascent without dedicated grid code certification pathways.
- Hydro:Run-of-river projects on Río Muni's continental rivers offer seasonal peaking capacity, constrained by sediment load variability and limited transmission reach to load centers.
Established volume favors thermal; emerging adoption favors solar.
Technology:
Technology selection determines fuel flexibility and efficiency certification eligibility under national petroleum frameworks.
- Gas Turbine:Open-cycle and combined-cycle configurations dominate Bioko Island's generation base, leveraging pipeline proximity to Alba field infrastructure. Dual-fuel capable units from Wärtsilä Oyj Abp enable switching between gas and liquid fuels as domestic supply fluctuates.
- Steam Turbine:Aging steam cycles operate at 30-40% thermal efficiency due to dated turbine technology and fuel quality variability, capping output per unit of feedstock and driving ISO 50001 certification pressure for efficiency verification.
- Hydroelectric:Small run-of-river installations on Río Muni's river systems provide seasonal peaking, though sediment management and transmission distance limit commercial scale.
- Biomass:Agricultural residue-fired units remain experimental, lacking established feedstock supply chains and grid connection standards for intermittent renewable sources.
Gas turbine technology commands current capacity share; dual-fuel retrofits are climbing the fastest.
Application:
Application-based segmentation tracks how unbundled procurement is reshaping traditional utility intermediation.
- Industrial:Methanol and LNG plants negotiate direct generation agreements with independent producers, bypassing Sociedad de Electricidad de Guinea Ecuatorial. Large thermal loads on Bioko Island command bargaining leverage unavailable to smaller consumers.
- Commercial:Hotels, banking, and retail operations in Malabo's load center prioritize reliability over cost, accepting premium tariffs for grid stability.
- Residential:Urban electrification on Bioko approaches saturation while Río Muni's continental regions lag, creating concession opportunities for distributed generation and mini-grid operators.
- Agricultural:Remote plantations and processing facilities adopt solar-diesel hybrid systems to reduce fuel import dependency, fragmenting revenue pools that previously consolidated around centralized distribution.
Industrial offtake dominates delivered megawatt-hours; agricultural distributed generation is gaining share fastest.
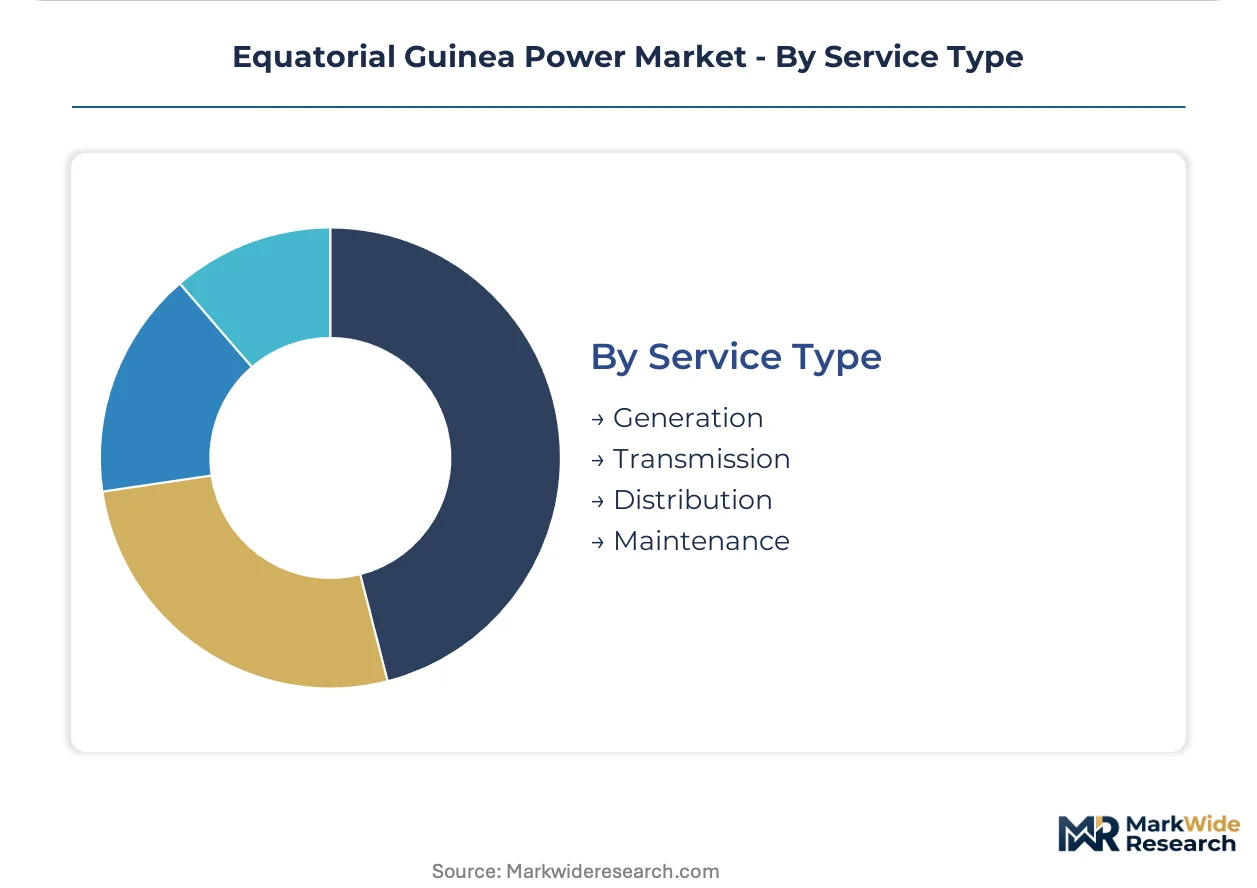
Service Type:
Service type segmentation exposes structural barriers from Sociedad de Electricidad de Guinea Ecuatorial's integrated monopoly.
- Generation:Independent producers face licensing conditioned on domestic supply obligations and grid code compliance, with unclear certification pathways delaying solar project commissioning.
- Transmission:Single-grid architecture spanning Bioko and Río Muni creates structural barriers for independent power producers seeking wheeling arrangements, concentrating control with the incumbent utility.
- Distribution:Last-mile infrastructure remains concentrated in Malabo and Bata, with rural electrification concessions awarded to Segesa competing against containerized solar-plus-storage bypass solutions.
- Maintenance:Gas turbine maintenance and high-voltage substation operations require skills concentrated in Malabo, constraining Río Muni expansion and creating technician scarcity premiums.
Transmission monopoly preserves incumbent control; maintenance services show steepest expansion trajectory as aging assets require specialized intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ministry of Mines and Hydrocarbons mandates domestic supply obligations for upstream gas allocation, directing investment toward Bioko Island's load centers and Río Muni's electrification gaps. These policy frameworks concentrate development around Malabo's industrial corridor while creating concession opportunities in continental regions.
Bioko Island
Methanol and LNG facility offtakers anchor thermal generation demand near Alba field infrastructure. The national petroleum framework conditions licensing on grid code compliance for producers seeking connection to Sociedad de Electricidad de Guinea Ecuatorial's transmission network. Malabo's load center drives voltage stability investments and specialized technician concentration for gas turbine maintenance.
Río Muni Continental Region
Remote mining and agricultural operations adopt solar-diesel hybrid systems to bypass centralized distribution infrastructure. Rural electrification concessions awarded to Segesa compete against containerized solar-plus-storage solutions that fragment traditional utility revenue pools. Bata serves as the primary grid-connected load center, though penetration rates lag Bioko Island significantly.
Annobón Province
Island isolation necessitates standalone microgrid architectures powered by diesel gensets and emerging solar installations. The Ministry of Mines and Hydrocarbons has limited enforcement reach here, creating regulatory gaps for distributed generation operators. Small-scale commercial loads in San Antonio de Palé drive modest demand for reliability-focused power solutions.
Corisco Bay Area
Offshore oil infrastructure and coastal settlements generate concentrated demand for modular generation systems. Dual-fuel capable units from Wärtsilä Oyj Abp enable fuel-switching as domestic gas supply fluctuates across this peripheral zone. Limited transmission reach preserves captive generation economics for industrial facilities operating near hydrocarbon extraction sites.
Equatorial Guinea Power Market Competitive Landscape
Player mix skews toward integrated utility incumbents and specialized technology providers rather than pure-play independent generators. The market structure concentrates transmission control with a single grid operator while fragmenting generation between captive industrial facilities and emerging distributed solar operators. Strategic archetypes include dual-fuel engine specialists, rural electrification concessionaires, and upstream-integrated thermal developers. Competitive moves center on fuel-flexibility retrofits and concession bidding for unserved regions.
Within the technology-provider tier, Wärtsilä Oyj Abp represents dual-fuel engine capability that enables gas-to-power installations near hydrocarbon infrastructure. Power Construction Corporation of China occupies a position among engineering-procurement-construction specialists capable of delivering integrated generation and grid assets. Sociedad de Electricidad de Guinea Ecuatorial anchors the incumbent utility archetype through transmission asset control spanning Bioko and Río Muni.
| Leading Market Players |
|---|
| Wärtsilä Oyj Abp |
| Power Construction Corporation of China |
| Sociedad de Electricidad de Guinea Ecuatorial |
| Indra Sistemas |
| Segesa |
| TotalEnergies |
| ExxonMobil Corporation |
| Ophir Energy |
| Elenilto |
| Others |
Supply & Pricing Matrix
Containerized solar-plus-storage substitution for diesel gensets is redrawing procurement geography across Río Muni while compressing delivered energy costs for remote commercial loads. This displacement dynamic simultaneously fragments centralized utility revenue pools and establishes modular pricing benchmarks independent of Sociedad de Electricidad de Guinea Ecuatorial's tariff bands.
Pricing Analysis
Certification level (ISO 50001 energy management) creates the primary spread between premium and standard service tiers, with verified efficiency protocols commanding tariff premiums in industrial offtake tenders. Contract-based long-term offtake agreements dominate thermal generation, while solar-diesel hybrid systems price on modular project scopes with shorter tenors. Price differentiation stems from fuel-flexibility certification and grid-code compliance status, with margins tightening for aging steam-cycle assets facing efficiency verification pressure. Agricultural operations in Río Muni exhibit highest price sensitivity, while methanol and LNG facilities on Bioko Island prioritize reliability over cost.
Supply Chain Analysis
Inventory lead times for gas turbine spare parts and high-voltage substation equipment concentrate technical dependencies in Malabo, constraining Río Muni expansion timelines. Supply geography anchors in Finland (Wärtsilä dual-fuel engines), China (EPC contractors, solar module assembly), and Spain (grid automation systems). Critical inputs include Alba field natural gas, containerized lithium-ion battery systems, and specialized gas turbine rotors. Single-source vulnerability runs through Finnish engine technology for fuel-flexible generation. Distribution runs through Sociedad de Electricidad de Guinea Ecuatorial's transmission monopoly for grid-connected loads, with direct-to-site delivery bypassing centralized infrastructure for distributed solar operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equatorial Guinea's power sector represents a high-growth disruption as distributed generation architectures erode decades of centralized utility control, accelerated by the Ministry of Mines and Hydrocarbons' tightening domestic supply obligation enforcement.
For Market Incumbents: Compound transmission asset control with strategic concession acquisitions in Río Muni's electrification gaps before distributed solar operators fragment rural revenue pools entirely. Defend against unbundled industrial procurement by embedding efficiency verification services into long-term service agreements, leveraging ISO 50001 certification as a retention lever. For New Entrants and Emerging Players: Lead with solar-diesel hybrid configurations targeting agricultural processing facilities and remote mining operations in Río Muni's unserved regions, where grid penetration lags create immediate addressable demand. Position around fuel-switching capability and bypass infrastructure to capture premium pricing for reliability-focused commercial loads outside Malabo's transmission reach. For Investors and Strategic Acquirers: Capital is best deployed toward dual-fuel engine specialists with retrofit capability and distributed generation operators holding rural electrification concessions. Long-term viability hinges on gas reserve depletion timelines intersecting with renewable procurement mandates, making fuel-flexibility technology the critical inflection signal for asset positioning across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Engine Retrofit Program | Wärtsilä technology enables gas-to-liquid fuel pivot as Alba field supply fluctuates. |
| Río Muni Rural Concession Bid | Segesa competes against containerized solar for unserved continental load centers. |
| ISO 50001 Certification Investment | Verified efficiency protocols unlock premium industrial offtake tender positioning. |
| Solar-Diesel Hybrid Deployment | Modular PV-battery systems bypass Sociedad de Electricidad de Guinea Ecuatorial entirely. |
| Gas-to-Power Project Development | Upstream operators secure offtake agreements ahead of reserve reclassification. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists; and secondary validation through EIA data, IEA reports, FERC-equivalent regulatory filings, and project development databases. Bottom-up capacity installation tracking and top-down macroeconomic triangulation anchored volume estimates across the modeling period.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning fuel source, generation capacity tier, project scale, and regional grid type. CAGRs were derived from regression analysis against reserve depletion timelines and renewable procurement mandate trajectories. Key forecast inputs included gas field output curves and solar irradiance mapping for Río Muni distributed generation economics.
The analysis sits within stated boundaries; outcomes outside sustained Ministry of Mines and Hydrocarbons enforcement of domestic supply obligations or accelerated reserve reclassification would require recalibration. Forecasts reflect documented assumptions regarding regulatory continuity and technology cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Global Ancillary Services Power Market
Power
Substation Automation System Market
Power
Power Sled Market
Power
Distributed Buoyancy Modules Market
Power
Argentina Power Market
Power
Italy Power EPC Market
Power
Canada Thermal Power Market
Power
Rotating Phase Converter Market
Power
Water Turbine Market
Power
Single-Phase Microinverter Market
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
Europe Frequency Converter Market
Power
Global UPS Market
Power
Critical Power Market
Power
India Power Market
Power
Portugal Power Market