
 United Kingdom Offshore Oil and Gas Decommissioning Market | 2026-2036
United Kingdom Offshore Oil and Gas Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Offshore Oil and Gas Decommissioning Market Analytics
Buyer concentration among North Sea operators is shifting as supermajors divest mature assets to smaller independents and private-equity backed firms, fragmenting procurement across less capitalized owners. Petrofac leverages its integrated engineering-procurement-construction expertise to sustain long-term platform removal contracts. Wood Group anchors its position through specialized well abandonment and late-life asset management capabilities. Saipem competes with heavy-lift vessel fleets purpose-built for single-lift platform removals.
United Kingdom offshore oil and gas decommissioning encompasses the engineered dismantlement, removal, and environmental restoration of subsea production infrastructure including steel-jacket platforms, topside modules, subsea wells, and export pipelines, with operations typically conducted in water depths of 90 to 150 meters under harsh North Sea metocean conditions. Well plugging dominates service expenditure due to regulatory mandates for permanent zonal isolation using cement and mechanical barriers. Platform removal commands premium margins where single-lift heavy-lift vessels reduce offshore exposure days. Robotic systems and ROV solutions represent the fastest-growing technology cluster as operators substitute remote intervention for diver-dependent operations in deeper, higher-pressure fields.
The North Sea Transition Authority enforces decommissioning programme approvals under the Petroleum Act 1998, while the Offshore Petroleum Regulator for Environment and Decommissioning monitors environmental compliance and offshore discharge permits. The UK's Climate Change Committee recommendations and evolving offshore electrification policies are reshaping liability timelines and abandonment cost estimates. Stakeholders must monitor regulatory adjustments to the OSPAR 98/3 derogation criteria and carbon-accounting rules for steel recycling versus offshore disposal.
Market Dynamics
Asset fragmentation across the UK North Sea is restructuring decommissioning procurement, as supermajors offload mature fields to private-equity backed independents with thinner balance sheets and shorter operational horizons.
Growth Catalysts
- Petroleum Act 1998 liability framework:Statutory deadlines for decommissioning programme submission are compressing operator timelines and forcing early contractor engagement for well plugging campaigns.
- Heavy-lift vessel specialization:Purpose-built crane ships capable of single-lift platform removals are reducing offshore exposure from months to days, accelerating project sanctioning.
- Central North Sea field maturation:Water injection platforms and early production systems installed during the 1970s-1980s construction wave now exceed design life, triggering systematic dismantlement.
Market Restraints
- Steel price volatility:Jacket fabrication and module lifting frame costs fluctuate with global scrap metal markets, distorting fixed-price removal contract economics.
- Heavy-lift vessel scarcity:Only a handful of crane ships exceed 3,000-tonne lift capacity globally, creating queue congestion for UK North Sea slots.
- OSPAR 98/3 derogation uncertainty:Regulatory ambiguity around offshore disposal exemptions for large steel jackets delays final investment decisions on removal methods.
Strategic Opportunities
- West of Shetland frontier:Ultra-deepwater fields approaching end-of-life will require novel well abandonment technologies, opening specialist contractor niches.
- Electrification policy alignment:The North Sea Transition Authority's offshore power-from-shore mandates create bundled decommissioning-electrification procurement opportunities.
- ROV-diver substitution:Autonomous underwater vehicles converging with machine vision inspection systems are penetrating deeper, higher-pressure reservoirs previously inaccessible to human divers.
Industry Challenges
- Wellsite abandonment engineering shortage:Experienced petroleum engineers capable of designing cement barrier systems for HPHT reservoirs are retiring faster than training pipelines replenish.
- Legacy pipeline corridor complexity:Commingled export systems with multiple ownership fractions complicate liability apportionment and synchronized removal scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Offshore Oil and Gas Decommissioning Market |
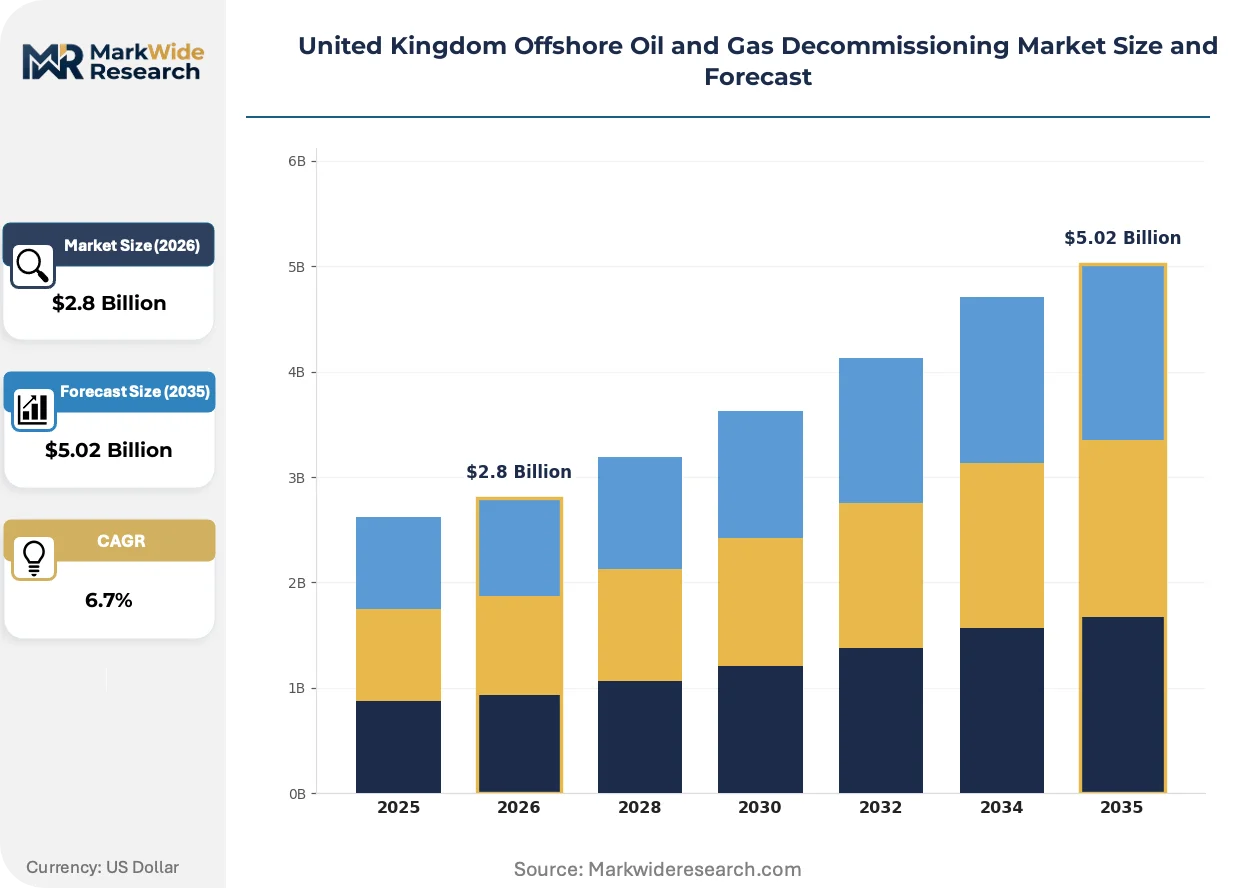
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Well Plugging, Platform Removal, Pipeline Decommissioning, Site Remediation Application: North Sea Operations, Shelf Operations, Decommissioning Projects, Environmental Restoration Technology: Robotic Systems, Subsea Tools, ROV Solutions, Decommissioning Vessels End User: Oil Companies, Contractors, Regulatory Bodies, Environmental Agencies |
| Companies Covered | Veolia Environnement S.A., Petrofac, Wood Group, Halliburton, Saipem, Allseas Group, Derrick Services (UK) Ltd, Perenco SA, Ramboll Group A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Offshore Oil and Gas Decommissioning Market Evolving Landscape
Remote intervention technologies are displacing conventional diver-dependent operations across the UK North Sea, while regulatory carbon-accounting rules reshape material disposal economics. These forces are compressing project timelines and reconfiguring contractor capability requirements.
Robotic well intervention systems are automating zonal isolation verification and plug setting in subsea completions previously requiring saturation diving. North Sea operators with mature central North Sea portfolios are deploying these systems at accelerating pace to mitigate weather window risks. The technology is automating inspection and maintenance cycles that once consumed 40% of offshore vessel days.
The Offshore Petroleum Regulator for Environment and Decommissioning has tightened offshore discharge permit thresholds for drilling fluids and produced water, extending environmental monitoring obligations through post-removal site surveys. This regulatory shift elevates documentation burdens for platform removal contractors. Well plugging specialists are responding by integrating real-time cement bond logging with regulatory submission workflows.
Buyer concentration among UK North Sea operators has fragmented as private-equity backed independents acquire divested assets, dispersing procurement authority across smaller entities with limited in-house project management capacity. Engineering-procurement-construction contractors are capturing larger scopes to fill this capability gap. Scotland's Aberdeen cluster remains the primary locus for this outsourcing pattern.
United Kingdom Offshore Oil and Gas Decommissioning Market Segmentation
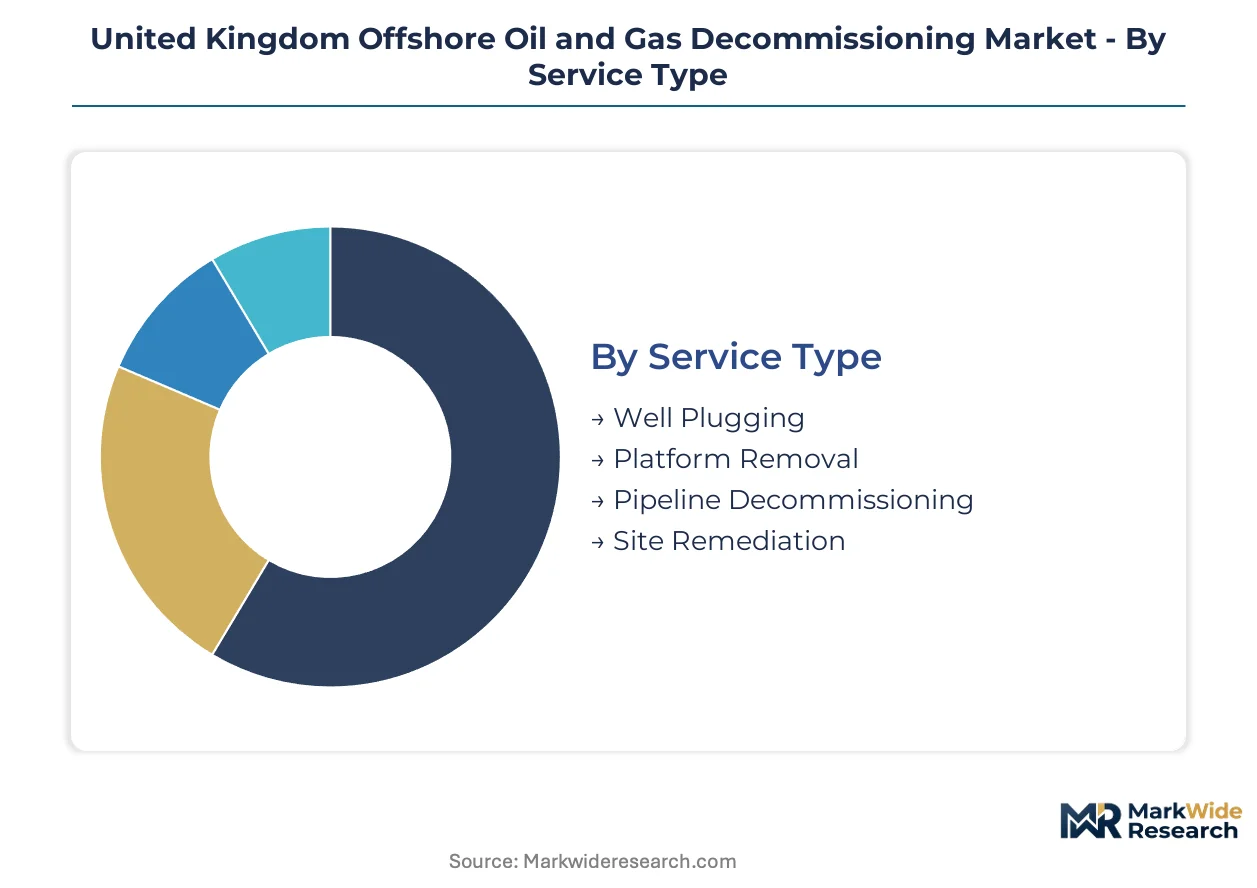
Decommissioning procurement in the UK North Sea fragments across service specializations, water depth applications, and technology maturity tiers. Understanding segment interdependencies helps contractors align vessel fleets, engineering capabilities, and regulatory compliance resources against operator liability timelines.
Service Type:
Standalone well plugging contracts dominate early-phase procurement, while platform removal and site remediation typically bundle into integrated engineering-procurement-construction scopes.
- Well Plugging:Permanent zonal isolation using cement and mechanical barriers accounts for the largest share of decommissioning expenditure. The North Sea Transition Authority mandates this as the first executed phase, compressing contractor mobilization windows for HPHT reservoir specialists.
- Platform Removal:Single-lift heavy-lift vessel operations command premium day-rates due to global crane ship scarcity. Northern North Sea operators prioritize this method to minimize offshore exposure during harsh winter metocean conditions.
- Pipeline Decommissioning:Commingled export systems require synchronized liability apportionment across multiple ownership fractions before removal scheduling.
- Site Remediation:Post-removal seabed surveys and environmental monitoring obligations extend contractor engagement timelines under tightened Offshore Petroleum Regulator discharge thresholds.
Well Plugging leads volumes today; Platform Removal is gaining share fastest as single-lift vessel availability improves.
Application:
Water depth and regulatory jurisdiction shape procurement patterns across UK continental shelf zones.
- North Sea Operations:Mature central and northern sector fields installed during the 1970s-1980s construction wave now exceed design life. Water depths of 90-150 meters require purpose-built heavy-lift vessels and saturation diving alternatives.
- Shelf Operations:Southern North Sea gas field decommissioning proceeds at slower pace due to extended production optimization and different metocean risk profiles.
- Decommissioning Projects:Integrated programme management spans multiple asset clusters under single procurement umbrellas as private-equity backed independents outsource project execution.
- Environmental Restoration:Post-removal habitat monitoring and seabed verification surveys now extend through multi-year obligations under evolving OSPAR compliance frameworks.
North Sea Operations anchor current expenditure; West of Shetland frontier fields will expand the addressable application base.
Technology:
Technology selection hinges on diver substitution economics and reservoir pressure characteristics rather than standalone capability demonstrations.
- Robotic Systems:Autonomous well intervention platforms automate plug setting and barrier verification in HPHT completions. Aberdeen engineering clusters are deploying these systems to mitigate weather window risks that once consumed 40% of offshore vessel days.
- Subsea Tools:Specialized cutting and lifting equipment for conductor removal and pile severing operates across water depths where diver access is impractical.
- ROV Solutions:Work-class remotely operated vehicles with manipulator arms handle inspection and maintenance cycles previously requiring human intervention.
- Decommissioning Vessels:Heavy-lift crane ships exceeding 3,000-tonne capacity command queue positions years in advance due to global fleet scarcity.
ROV Solutions dominate installed base; Robotic Systems are climbing the fastest as machine vision and autonomous navigation mature.
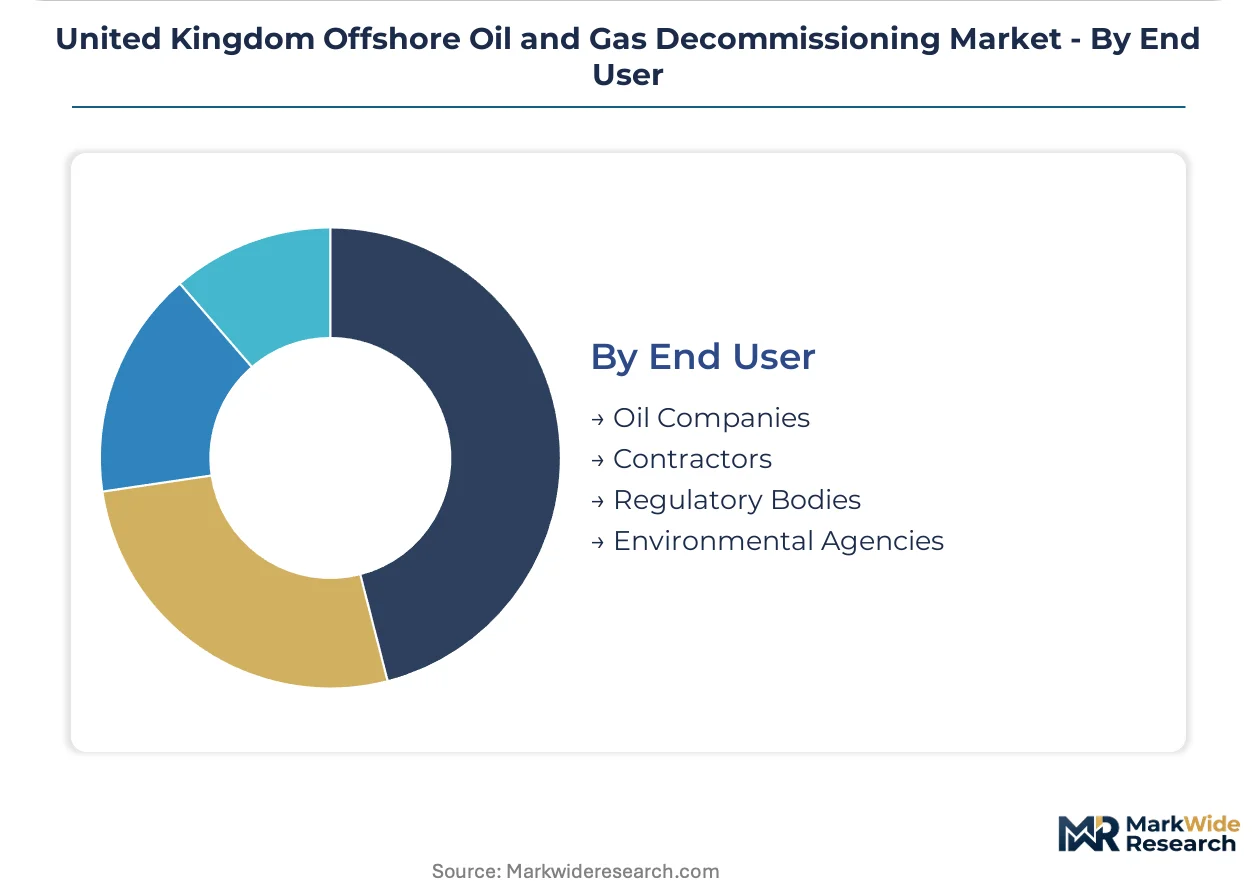
End User:
Procurement authority has fragmented as asset ownership concentrates among entities with varying in-house project management depth.
- Oil Companies:Supermajors retain well abandonment engineering expertise while divesting mature fields to independents with thinner balance sheets and shorter operational horizons.
- Contractors:Engineering-procurement-construction firms capture expanding scopes to fill capability gaps left by fragmented buyer structures across the Aberdeen cluster.
- Regulatory Bodies:The North Sea Transition Authority enforces Petroleum Act 1998 programme approval timelines that compress operator-contractor engagement cycles.
- Environmental Agencies:The Offshore Petroleum Regulator monitors discharge permits and post-removal site survey obligations that elevate documentation burdens for removal contractors.
Oil Companies drive procurement volume today; Contractors are expanding their share of total project value through integrated scope capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aberdeen's concentrated decommissioning engineering workforce anchors UK capability, with specialist petroleum engineers, marine contractors, and regulatory compliance consultants clustering around North Sea operational demand. This talent concentration draws procurement authority from London-based operator headquarters and international asset holders seeking execution expertise.
Scotland
Central and northern North Sea mature fields drive decommissioning procurement, with platforms installed during the 1970s-1980s construction wave now exceeding design life. The North Sea Transition Authority enforces Petroleum Act 1998 programme approval timelines that compress operator-contractor engagement cycles. Aberdeen maintains its position as the primary engineering cluster, with Petrofac and Wood Group anchoring integrated project delivery from city-based offices.
England
Southern North Sea gas field decommissioning proceeds at measured pace due to extended production optimization and different metocean risk profiles. The Offshore Petroleum Regulator for Environment and Decommissioning monitors discharge permits and post-removal site survey obligations from its London base. Humberside ports support vessel mobilization for heavy-lift operations, with Teesside fabrication yards handling module dismantlement.
Norway
Adjacent North Sea fields share technical service requirements with UK operations, with Norwegian heavy-lift vessel operators competing for UK contract awards. The Norwegian Petroleum Directorate coordinates cross-border regulatory alignment on OSPAR 98/3 derogation criteria. Stavanger-based engineering houses supply well abandonment specialists to UK projects facing workforce shortages.
Netherlands
Southern North Sea pipeline corridor complexity creates synchronized decommissioning challenges spanning UK and Dutch continental shelf boundaries. The State Supervision of Mines oversees environmental compliance that mirrors UK regulatory frameworks. Rotterdam heavy-lift terminals provide alternative vessel staging for North Sea removal campaigns.
Denmark
Danish North Sea mature assets follow comparable decommissioning timelines to UK fields, with shared contractor pools creating competition for specialist resources. The Danish Energy Agency administers programme approvals under parallel OSPAR obligations. Esbjerg port infrastructure supports cross-regional vessel deployment for platform removal campaigns.
United Kingdom Offshore Oil and Gas Decommissioning Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across UK North Sea decommissioning procurement. The market structure reflects moderate consolidation, with engineering-procurement-construction firms capturing integrated scopes while niche contractors retain well plugging and heavy-lift segments. Three archetypes dominate: integrated project managers, well abandonment specialists, and heavy-lift vessel operators. Competitive positioning hinges on M&A-driven capability expansion and strategic partnerships to secure queue positions for scarce crane ship capacity.
Among UK-based integrated service providers, Petrofac and Wood Group exemplify the project management archetype, occupying positions that bundle engineering, procurement, and construction execution for fragmented buyer bases. Saipem represents the heavy-lift specialization vector, with vessel-based capabilities that command premium positioning for single-lift platform removals. These three anchors illustrate how contractor structures align against operator procurement patterns shaped by asset divestment and liability timeline compression.
| Leading Market Players |
|---|
| Veolia Environnement S.A. |
| Petrofac |
| Wood Group |
| Halliburton |
| Saipem |
| Allseas Group |
| Derrick Services (UK) Ltd |
| Perenco SA |
| Ramboll Group A/S |
| Others |
Value Network & Pricing Analysis
Aberdeen's saturation diving specialists and HPHT petroleum engineers command wage premiums that widen spreads between integrated project rates and standalone well plugging contracts. Labor-cost differentials between unionized offshore crews and remote-robotics technicians are compressing margins on diver-dependent services while elevating pricing for autonomous intervention capabilities.
Pricing Analysis
Bundled engineering-procurement-construction contracts for platform removal command premium pricing against unbundled well plugging services, with three-tier pricing structure across premium, standard, and economy levels differentiating by heavy-lift vessel availability and project management depth. Price differentiation hinges on crane ship queue position and regulatory compliance bundling, with supermajors least sensitive to rate escalation due to balance-sheet capacity while private-equity backed independents drive aggressive tender competition. Pricing pressure stems from heavy-lift vessel scarcity inflating day-rates for single-lift operations, though cost compression in standard-tier well plugging is intensifying because robotic substitution reduces offshore exposure days.
Supply Chain Analysis
Direct-to-operator channels handle supermajor procurement for integrated decommissioning programmes, while tiered subcontractor networks serve fragmented independents through Aberdeen-based engineering clusters. Heavy-lift vessel supply concentrates in Norway, the Netherlands, and Singapore, with jacket fabrication and module dismantlement drawing from Teesside yards and Rotterdam terminals. Raw material dependencies include high-strength steel plate, subsea wellhead components, and specialized cement blends for zonal isolation. Supply chain risk centers on single-source vulnerability for crane ships exceeding 3,000-tonne capacity, with only a handful of operators controlling global fleet deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK offshore decommissioning market operates as a regulatory compounder, where Petroleum Act 1998 liability deadlines and OSPAR 98/3 derogation rulings continuously reset operator procurement cycles and contractor engagement timelines.
For Market Incumbents: Anchor long-term platform removal contracts through heavy-lift vessel queue partnerships with Norwegian and Dutch operators, defending against emerging pure-play robotic intervention specialists. Deepen backward integration into well abandonment engineering capabilities to offset workforce retirement attrition in HPHT reservoir design. Prioritize certification investment for autonomous underwater vehicle operations as diver substitution accelerates across central North Sea fields. For New Entrants and Emerging Players: Begin with West of Shetland frontier fields where ultra-deepwater well abandonment technologies remain underpenetrated by established contractors. Target private-equity backed independents lacking in-house project management capacity, offering bundled decommissioning-electrification procurement aligned with North Sea Transition Authority offshore power mandates. Deploy machine vision inspection systems as the primary go-to-market wedge against legacy ROV operators. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap well plugging specialists with HPHT engineering benches and regulatory submission workflows. Long-term viability over the next decade rests on contractor positioning for West of Shetland field maturation and robotic intervention adoption curves. Monitor OSPAR 98/3 derogation criteria adjustments as the critical inflection signal for jacket removal method economics and heavy-lift vessel demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Heavy-Lift Vessel Partnership | Queue position agreements with Allseas or Saipem secure single-lift capacity for northern North Sea platform removals. |
| Robotic Systems Integration | Machine vision and autonomous navigation capabilities displace 40% of offshore vessel days previously consumed by diver operations. |
| Well Abandonment Engineering Acquisition | HPHT petroleum engineering talent pools in Aberdeen address workforce retirement faster than training pipelines replenish. |
| Decommissioning-Electrification Bundling | North Sea Transition Authority offshore power mandates create combined procurement scopes for private-equity backed independents. |
| OSPAR Compliance Certification | Offshore Petroleum Regulator discharge permit expertise elevates documentation burdens into competitive differentiation. |
Research Methodology
Direct dialogue with decommissioning project managers, well abandonment engineers, heavy-lift vessel operators, and North Sea Transition Authority regulatory leads grounded qualitative findings in operational reality. Secondary validation drew from Petroleum Act 1998 programme approvals, OSPAR convention submissions, Offshore Petroleum Regulator discharge permits, and Aberdeen engineering cluster employment data. Bottom-up contractor capacity assessments and top-down operator liability timelines were triangulated against vessel fleet deployment records.
Segmentation outputs across service type, water depth application, technology tier, and end-user procurement authority were generated over the projection horizon. CAGRs were derived from well plugging campaign scheduling, platform removal sanctioning rates, and robotic intervention adoption curves modeled against regulatory deadline compression. Forecast inputs incorporated heavy-lift vessel queue dynamics, HPHT reservoir complexity distributions, and private-equity asset acquisition velocity.
Several conditions sit outside the modeled scope, including unannounced supermajor divestiture transactions, OSPAR 98/3 derogation rulings on specific jacket structures, and breakthrough autonomous vehicle capabilities. Forecasts reflect assumptions around regulatory timeline adherence, vessel fleet availability, and workforce replenishment rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
Floating Production Systems (FPS) Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Norway Oil and Gas Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Asia Pacific Offshore Seismic Services Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market