
 Floating Production Storage and Offloading Market | 2026-2036
Floating Production Storage and Offloading Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Production Storage and Offloading Market Intelligence
Modular topside integration is repositioning buyer choice toward configurable lease arrangements rather than bespoke newbuild contracts. SBM Offshore N.V. leverages its Fast4Ward hull program to compress delivery timelines and reduce capital exposure for clients. MODEC Inc. anchors its competitiveness through proprietary mooring and turret systems that sustain operational uptime in harsh environments.
A Floating Production Storage and Offloading unit is a marine vessel that receives hydrocarbons from nearby platforms or subsea wells, processes them through separation and treatment systems, and stores crude oil in integrated tanks typically exceeding one million barrels before offloading to shuttle tankers. FPSO configurations dominate contract awards due to their combined processing-storage-offloading functionality, while FSRU vessels represent the fastest-expanding subsegment as coastal LNG import infrastructure proliferates. Deepwater exploration applications command premium dayrates owing to complex subsea architecture requirements, whereas conventional production assignments face margin compression from standardized vessel availability.
The International Maritime Organization's greenhouse gas strategy and the EU F-Gas Regulation constrain refrigerant and flare management systems aboard newbuild units, elevating engineering compliance costs. Brazil's national petroleum regulator, the ANP, mandates local content thresholds that reshape supply chain sourcing for vessels operating in its pre-salt fields. Stakeholders must weigh charter duration commitments against technology obsolescence risks as electrification and carbon capture retrofit compatibility become decisive bid criteria.
Market Dynamics
Modular hull fabrication and standardized topside packages are compressing vessel delivery timelines from 36 months toward 24 months, forcing incumbent yards to retool capacity or cede share to Asian fabricators with Fast4Ward-compatible lines.
Growth Catalysts
- Pre-salt reservoir development:Brazil's ANP production-sharing frameworks and local content mandates sustain long-term charter demand for high-capacity units in ultra-deepwater blocks.
- EU F-Gas Regulation:Refrigerant phase-down schedules are accelerating retrofits of closed-loop flare recovery systems aboard existing vessels, creating replacement cycle pull-through.
- Subsea tieback architecture:Standardized subsea manifolds and riser systems reduce field development costs, enabling marginal fields to achieve economic breakeven under FPSO lease structures.
Market Restraints
- Steel plate and specialized alloy input volatility:Hull-grade steel and corrosion-resistant alloys face price swings tied to scrap metal flows and nickel supply disruptions from Indonesian export restrictions.
- Converter and switchgear supply concentration:High-voltage electrical systems for electrified topsides depend on a narrow German-Japanese supplier base with 18-month order backlogs.
- IMO greenhouse gas strategy compliance:Carbon intensity indicator thresholds and impending well-to-wake fuel standards impose engineering uncertainty on newbuild propulsion specifications.
Strategic Opportunities
- Guyana-Suriname basin emergence:ExxonMobil-operated Stabroek block expansions and neighboring Shell discoveries create demand for third and fourth FPSO deployments through 2030.
- Carbon capture readiness integration:Pre-installed deck space and utility interfaces for post-combustion capture modules differentiate bids as ANP and UK's North Sea Transition Authority advance storage licensing frameworks.
- Hybrid power architectures:Battery-turbine integration and shore-power connection capability align with Norway's NOx fund incentives and emerging low-carbon charter premiums.
Industry Challenges
- Subsea installation vessel scarcity:Heavy-lift and pipelay asset availability constrains field hookup schedules, compressing revenue recognition timelines for charterers.
- Classification society rule harmonization:Divergent ABS, DNV, and Lloyd's Register interpretations of dynamic positioning redundancy and station-keeping reliability extend design approval cycles.
- Cross-functional engineering talent gaps:Integration of process safety, marine systems, and subsea controls expertise within single project teams remains difficult to staff at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Production Storage and Offloading Market |
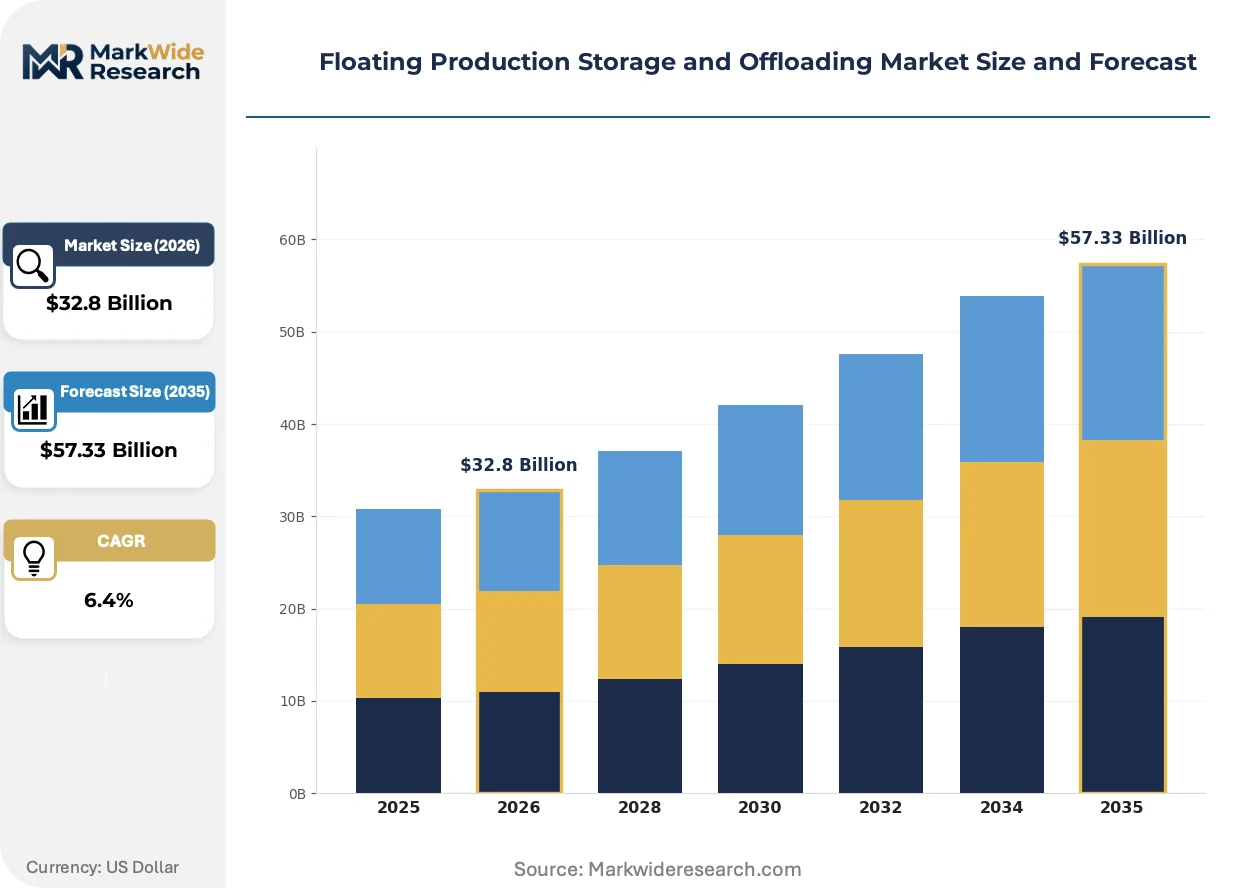
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: FPSO, FSOs, FPSS, FSRU Application: Deepwater Exploration, Production, Storage, Offloading End User: National Oil Companies, Independents, Service Providers, Multinational Corporations Technology: Subsea, Floating Facilities, Processing Systems, Anchor Systems |
| Companies Covered | Yinson Holdings Berhad, Teekay Corporation, SBM Offshore N.V., Samsung Heavy Industries, Petróleo Brasileiro S.A., MODEC Inc., Bumi Armada Berhad, Bluewater Energy Services B.V., BW Offshore Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Production Storage and Offloading Market Strategic Shifts & Innovations
Digital twin deployment and predictive maintenance algorithms are redefining operational uptime guarantees, shifting contractor risk allocation from time-based penalties toward availability-linked performance contracts.
Electrified topside designs with shore-power connection capability are absorbing capital allocation from conventional gas-turbine configurations. Norwegian operators in the North Sea and select Brazilian pre-salt leaseholders are specifying hybrid-ready architectures in 70% of new tender documents. This technology shift is absorbing engineering hours previously dedicated to fuel gas treatment and exhaust ducting, reallocating them toward high-voltage distribution and battery safety systems.
The EU F-Gas Regulation's hydrofluorocarbon quota phase-down is compelling refrigerant conversions in existing process cooling loops. Vessel operators face retrofit deadlines or charter rate penalties for non-compliance on European routes. FPSO units with carbon dioxide cascade or ammonia-based refrigeration systems command preference in ANP-regulated Brazilian waters and North Sea fields subject to UK's Environmental Permitting Regulations.
Charterers are consolidating procurement authority toward integrated lease-operate-maintain contracts with 15-20 year tenors. National oil companies in Brazil and emerging African basins now bundle subsea installation, drilling support, and offtake logistics under single counterparty arrangements. This pattern concentrates vendor qualification requirements and is most visible in Petrobras's Búzios and Mero field development sequences, where three-vessel master service agreements replaced discrete project tenders.
Floating Production Storage and Offloading Market Segmentation
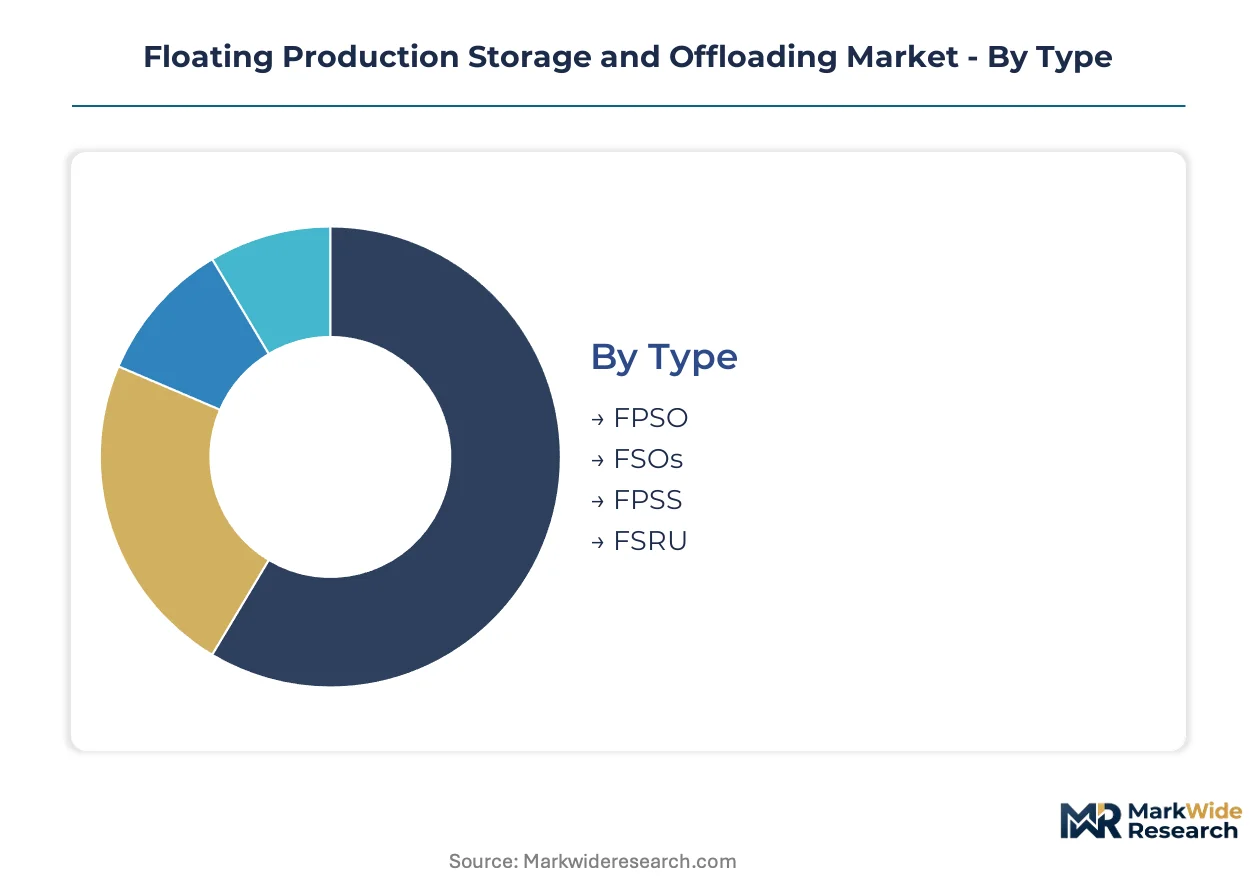
FPSO vessel classification determines regulatory pathways across IMO, classification societies, and basin-specific regulators. Segment boundaries reshape procurement authority, with ANP local content rules and EU F-Gas compliance creating divergent specification requirements for identical hull platforms.
Type:
Certification burden concentrates on dynamic positioning systems and station-keeping reliability, with DNV, ABS, and Lloyd's Register imposing divergent redundancy standards that extend design approval timelines for high-capacity units.
- FPSO:Combined processing-storage-offloading functionality dominates contract awards through integrated topside separation, treatment, and tankage exceeding one million barrels. Brazil's pre-salt basins sustain charter demand for ultra-deepwater units under ANP production-sharing frameworks with stringent local content mandates.
- FSRU:Coastal LNG import infrastructure proliferation drives fastest-expanding subsegment deployment, with shore-power connection capability and hybrid-ready architectures specified in North Sea and select Brazilian tenders. EU F-Gas refrigerant phase-down accelerates retrofits of closed-loop flare recovery systems aboard existing vessels.
- FSOs:Dedicated storage-offloading configurations serve mature fields with stable production profiles, reducing capital exposure through stripped-down topside packages.
- FPSS:Floating production semi-submersibles anchor harsh-environment operations through enhanced motion characteristics in North Atlantic and Norwegian waters.
FPSO sits at the top of the volume ranking, with FSRU climbing the fastest.
Application:
Cost tier stratification separates premium dayrate deepwater assignments from margin-compressed conventional production, with subsea architecture complexity determining economic breakeven thresholds.
- Deepwater Exploration:Complex subsea manifold and riser requirements command premium dayrates, with standardized tieback architectures reducing field development costs for marginal fields. Guyana-Suriname basin emergence through ExxonMobil-operated Stabroek block expansions creates demand for third and fourth unit deployments.
- Production:Sustained operational uptime in harsh environments depends on proprietary mooring and turret systems, with Fast4Ward-compatible hull programs compressing delivery timelines toward 24 months. Charter duration commitments now span 15-20 year tenors as national oil companies consolidate procurement authority.
- Storage:Integrated tankage specifications face IMO greenhouse gas strategy constraints on carbon intensity indicators and impending well-to-wake fuel standards.
- Offloading:Shuttle tanker interface protocols vary across UK Environmental Permitting Regulations and ANP operational requirements.
Deepwater Exploration captures the highest margin tier, with Production anchoring baseline volume.
End User:
Customer type determines contracting structure, with integrated lease-operate-maintain arrangements replacing discrete project tenders among capital-constrained independents.
- National Oil Companies:Petrobras's Búzios and Mero field development sequences demonstrate three-vessel master service agreements bundling subsea installation, drilling support, and offtake logistics under single counterparty arrangements. ANP local content thresholds reshape supply chain sourcing for pre-salt field operations.
- Independents:Margin compression from standardized vessel availability forces configurable lease arrangements over bespoke newbuild contracts, with Fast4Ward hull programs reducing capital exposure.
- Service Providers:Technical expertise integration across process safety, marine systems, and subsea controls faces staffing scale constraints.
- Multinational Corporations:Cross-functional engineering talent gaps complicate project team assembly for electrified topside and carbon capture readiness specifications.
National Oil Companies dominate charter tenor length, with Independents gaining share through lease flexibility.
Technology:
Supply concentration in high-voltage electrical systems creates 18-month order backlogs for German-Japanese converter and switchgear suppliers, delaying electrified topside deployment.
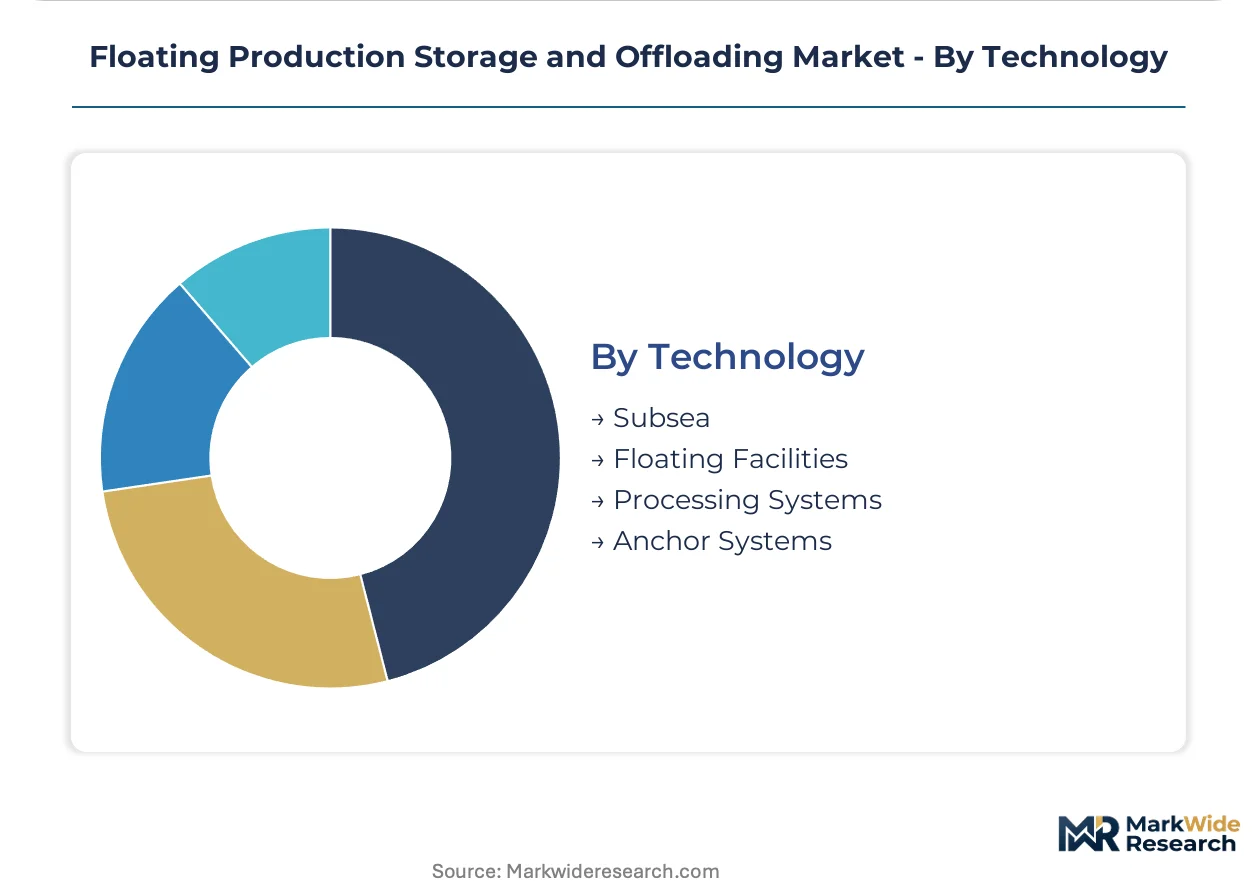
- Subsea:Standardized manifolds and riser systems enable marginal field economic breakeven under FPSO lease structures, though heavy-lift and pipelay asset scarcity constrains field hookup schedules. Subsea installation vessel availability compresses revenue recognition timelines for charterers.
- Floating Facilities:Modular hull fabrication and standardized topside packages retool incumbent yard capacity or cede share to Asian fabricators with Fast4Ward-compatible lines. Hull-grade steel and corrosion-resistant alloy price volatility tied to Indonesian nickel export restrictions elevates input cost uncertainty.
- Processing Systems:Ammonia-based and carbon dioxide cascade refrigeration systems command preference in ANP-regulated Brazilian waters and North Sea fields subject to UK Environmental Permitting Regulations.
- Anchor Systems:Proprietary mooring and turret configurations differentiate contractor competitiveness in harsh-environment station-keeping reliability.
Floating Facilities anchors installed base volume, with Processing Systems expanding most quickly on refrigerant conversion cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FPSO industry traces its commercial origins to North Sea oil developments during the 1970s, when Shell deployed the first purpose-built unit off Spain. Brazil subsequently scaled the sector through pre-salt basin discoveries, establishing the dominant demand geography for ultra-deepwater charter contracts.
Brazil
Petrobras-operated Búzios and Mero fields sustain charter demand for high-capacity units exceeding two million barrels of storage. ANP local content thresholds mandate domestic sourcing percentages that reshape supply chain configurations for foreign contractors. The Santos Basin cluster near Rio de Janeiro concentrates fabrication yard activity and subsea equipment integration.
Norway
North Sea electrification mandates drive specification of shore-power connection capability and battery-turbine hybrid architectures. The NOx fund incentive program reduces capital costs for low-emission propulsion retrofits on existing vessels. Stavanger and Bergen anchor engineering design centers for harsh-environment mooring and turret systems.
United States
Gulf of Mexico deepwater lease sales in the Mississippi Canyon and Walker Ridge areas sustain demand for high-specification units. Bureau of Safety and Environmental Enforcement regulations govern dynamic positioning redundancy and station-keeping reliability standards. Houston hosts the primary procurement and project management functions for ExxonMobil-operated developments.
South Korea
Asian fabricators leverage Fast4Ward-compatible hull lines to compress delivery timelines and capture market share from European yards. Korean Register classification rules and government shipbuilding subsidies support cost-competitive newbuild construction. The Geoje shipyard complex specializes in modular topside integration for export-bound FPSO contracts.
United Kingdom
North Sea Transition Authority carbon storage licensing frameworks elevate carbon capture readiness as a bid evaluation criterion. UK Environmental Permitting Regulations constrain refrigerant selection and flare management systems aboard units operating in British waters. Aberdeen maintains subsea engineering expertise clusters despite declining indigenous production volumes.
Floating Production Storage and Offloading Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology differentiation and charter duration commitments. The vendor base organizes around three strategic archetypes: integrated lease-operate-maintain contractors, specialized mooring and turret system providers, and scale-driven Asian fabricators. Consolidation pressure intensifies as national oil companies bundle procurement authority under master service agreements spanning multiple vessel deployments.
Within the integrated contractor tier, SBM Offshore N.V. and MODEC Inc. exemplify business models combining proprietary hull programs with long-term operational responsibility. Yinson Holdings Berhad occupies a position among emerging challengers competing through lease flexibility and regional partnership structures. Samsung Heavy Industries anchors the fabrication-centric segment, representing the Asian yard capacity that compresses delivery timelines through standardized hull platforms.
| Leading Market Players |
|---|
| Yinson Holdings Berhad |
| Teekay Corporation |
| SBM Offshore N.V. |
| Samsung Heavy Industries |
| Petróleo Brasileiro S.A. |
| MODEC Inc. |
| Bumi Armada Berhad |
| Bluewater Energy Services B.V. |
| BW Offshore Limited |
| Others |
Cost & Logistics Intelligence
Captive hull fabrication through Fast4Ward-compatible yard lines anchors both supply security and charter rate bargaining power for integrated contractors serving Brazil's ANP-regulated pre-salt developments. This vertical control over standardized hull platforms compresses delivery timelines while insulating against steel plate volatility from Indonesian nickel export restrictions.
Pricing Analysis
Long-term lease-operate-maintain contracts with 15-20 year tenors dominate transaction structures, with pricing stratifying across premium, standard, and economy tiers based on storage capacity specifications and local content compliance levels. Premium dayrates attach to ultra-deepwater units with carbon capture readiness and hybrid power architectures, while standardized vessel availability compresses margins for conventional production assignments. Cost compression in the standard tier intensifies as Asian fabricators expand Fast4Ward-compatible capacity, though national oil companies show lowest price sensitivity due to production-sharing framework economics.
Supply Chain Analysis
Dual-sourcing mandates from ANP and major charterers require qualified hull fabrication across South Korea, Singapore, and China, with topside integration splitting between European specialists and emerging Asian yards. Critical inputs draw from Indonesian nickel for corrosion-resistant alloys, German-Japanese high-voltage electrical systems, and Norwegian mooring component suppliers. Single-source vulnerability concentrates in converter and switchgear suppliers carrying 18-month order backlogs. Distribution runs through integrated contractors managing end-to-end field development logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FPSO market functions as a regulatory compounder where EU F-Gas refrigerant phase-down deadlines and ANP local content mandates continuously reshape vessel specifications and charter economics.
For Market Incumbents: Anchor competitiveness through proprietary mooring and turret system patents that sustain operational uptime premiums in harsh-environment North Sea and Brazilian pre-salt assignments. Defend against Asian fabricator encroachment by deepening backward integration into hull-grade steel sourcing partnerships that buffer Indonesian export restriction exposure. Prioritize certification investment in carbon capture readiness interfaces to capture ANP and UK North Sea Transition Authority licensing preference.
For New Entrants and Emerging Players: Enter via lease flexibility structures targeting capital-constrained independents in Guyana-Suriname basin expansions where ExxonMobil-operated discoveries create third and fourth unit demand. The most penetrable white space sits in hybrid-ready architecture retrofits for existing vessels facing EU F-Gas compliance deadlines. Pursue regional partnership models with Brazilian fabrication yards to satisfy ANP local content thresholds without captive yard investment.
For Investors and Strategic Acquirers: Roll-up economics work for specialized mooring and turret system providers because station-keeping reliability differentiation commands persistent charter rate premiums across harsh-environment basins. Long-term viability hinges on electrified topside and carbon capture readiness technology portfolios. Watch subsea installation vessel availability as the inflection signal—scarcity here compresses field hookup schedules and delays revenue recognition for charterers, reshaping valuation multiples for integrated contractors.
| Strategic Initiative | Industry Significance |
|---|---|
| Fast4Ward Hull Program Expansion | SBM Offshore's standardized platform compresses delivery timelines from 36 months toward 24 months for Brazilian pre-salt contracts. |
| Carbon Capture Readiness Integration | Pre-installed deck space for post-combustion modules differentiates bids under ANP and UK North Sea Transition Authority frameworks. |
| Hybrid Power Architecture Deployment | Battery-turbine integration aligns with Norway's NOx fund incentives and emerging low-carbon charter premiums. |
| Refrigerant System Retrofit | Ammonia-based and carbon dioxide cascade conversions command preference in EU F-Gas regulated waters. |
| Master Service Agreement Consolidation | Petrobras's three-vessel bundles concentrate procurement authority and reshape vendor qualification requirements. |
Research Approach
Multiple input streams — charter contract documentation, yard capacity utilization data, and regulatory filing analysis — were reconciled across primary interviews with FPSO project directors, ANP regulatory compliance officers, subsea installation contractors, and topside engineering leads. Secondary validation drew from IMO greenhouse gas strategy publications, ANP local content decrees, classification society rule updates, and customs records of hull-grade steel imports. Bottom-up vessel deployment tallies and top-down basin development capex estimates were triangulated to anchor market sizing.
Data-stream reconciliation across the projection horizon applied segment-specific growth assumptions for FPSO, FSRU, FSO, and FPSS vessel categories by water depth tier, storage capacity band, and end-user contracting structure. CAGRs were derived from charter tenor trends, local content compliance cost trajectories, and electrification capital allocation shifts. Industry-specific forecast inputs incorporated subsea tieback architecture adoption rates and heavy-lift vessel availability constraints.
Inputs from ANP production-sharing frameworks and EU F-Gas implementation timelines were available through the study window; gaps in proprietary charter rate disclosures and yard cost structures introduce uncertainty bands around margin projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Netherlands Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Enhanced Oil Recovery Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
South Sudan Oil and Gas Upstream Market
Offshore Oil and Gas
Indonesia Oil and Gas Upstream Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Brazil Oil and Gas Downstream Market