
 Subsea Equipment Market | 2026-2036
Subsea Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Equipment Market Intelligence
Aftermarket services for subsea equipment is fragmenting the traditional integrated project revenue model. TechnipFMC plc leverages its integrated engineering, procurement, and construction (iEPC) model to secure long-term contracts. Aker Solutions ASA specializes in complex subsea production systems for harsh environments, particularly in the North Sea. Oceaneering International, Inc. dominates the provision of specialized Remote Operated Vehicles and related services for inspection and maintenance.
Subsea equipment refers to the hardware, tools, and infrastructure placed on the seabed for offshore energy extraction. This includes components like subsea trees, which are engineered from high-strength alloys to manage hydrocarbon flow at pressures exceeding 15,000 psi. Subsea Trees and Control Systems constitute the highest value segments within product types, driven by new deepwater field developments. Within technology, the deployment of advanced Remote Operated Vehicles is essential for Installation and Maintenance applications, representing a critical service-based revenue stream.
Compliance with ISO 13628 standards for subsea production systems is a mandatory requirement for market access. Regulatory bodies such as Brazil's ANP and the US Environmental Protection Agency (EPA) enforce stringent environmental and safety protocols on offshore operations, influencing equipment design. Stakeholder focus is now on developing equipment compatible with carbon capture and storage infrastructure and emerging hydrogen production facilities.
Market Dynamics
The central dynamic in the subsea equipment market is the dual-track development pressure from both traditional deepwater oil extraction and emerging new energy systems, forcing manufacturers to innovate for both high-pressure hydrocarbon and low-carbon applications simultaneously.
Growth Catalysts
- Offshore Wind Projects:Demand from the offshore wind energy sector for subsea power cables, scour protection, and foundation monitoring systems provides a significant and expanding revenue stream separate from hydrocarbon markets.
- Deepwater Field Sanctioning:New project approvals in deepwater basins, particularly Brazil's pre-salt fields, directly drive orders for high-specification subsea trees, manifolds, and control systems engineered for high-pressure environments.
- Carbon Storage Infrastructure:Government initiatives supporting carbon capture, utilization, and storage (CCUS) are creating demand for subsea pipelines, injection wells, and monitoring equipment compliant with new environmental frameworks.
Market Restraints
- Volatile Input Costs:The price of high-strength, corrosion-resistant alloys like nickel-based superalloys, essential for manufacturing equipment rated for over 15,000 psi, introduces significant cost uncertainty for fabricators.
- Technical Limits in Harsh Environments:Equipment deployed in ultra-deepwater or Arctic conditions faces extreme pressure, low temperatures, and material fatigue, which limits operational life and increases the risk of costly failures.
- Long Project Lead Times:The extended timeline from project sanctioning to equipment delivery, often spanning several years, exposes manufacturers to risks of cancellation or deferment due to commodity price fluctuations and shifting capital priorities.
Strategic Opportunities
- Subsea Data Centers:Adapting subsea power and cooling technology for the development of underwater data centers offers a novel application, leveraging expertise in pressure vessel design and remote power distribution.
- Seabed Mineral Exploration:The modification of existing Remote Operated Vehicle (ROV) and trenching technologies for deep-sea mining of critical minerals like polymetallic nodules presents a diversification opportunity beyond energy.
- Offshore Hydrogen Production:Developing subsea electrolyzers, storage solutions, and dedicated pipelines to support emerging green hydrogen production facilities located near offshore wind farms opens a new market vertical.
Industry Challenges
- Specialized Talent Shortages:A scarcity of qualified subsea engineers, data scientists, and experienced ROV pilots capable of managing complex, digitally-enabled deepwater projects creates execution bottlenecks and drives up labor costs.
- System Integration Complexity:Integrating new digital and all-electric equipment with legacy hydraulic systems on existing brownfield sites presents significant technical and operational hurdles for asset operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Equipment Market |
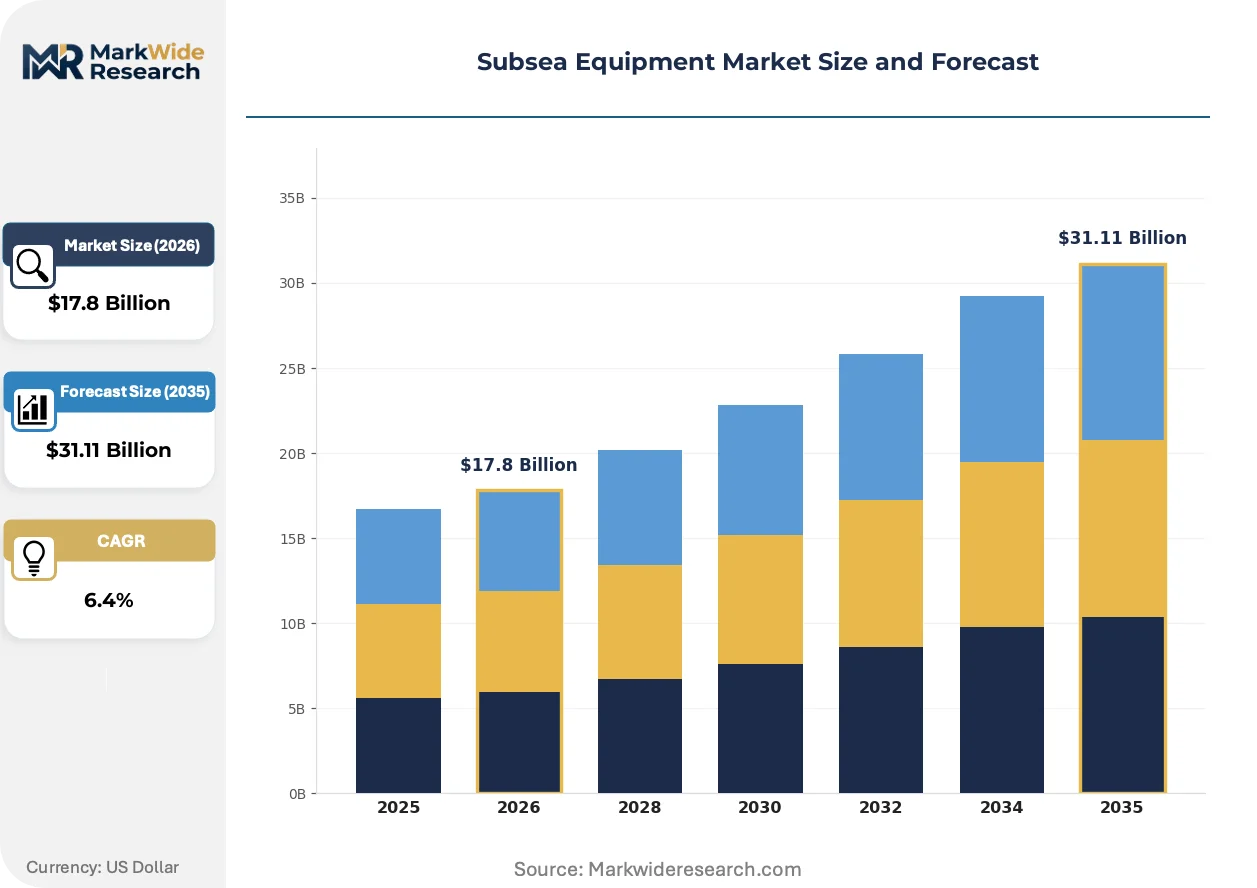
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Subsea Trees, Control Systems, Umbilicals, Sensors Application: Offshore Exploration, Production, Installation, Maintenance End User: Oil & Gas Companies, EPC Contractors, Research Institutions, Environmental Agencies Technology: Remote Operated Vehicles, Submersible Pump, Acoustic Systems, Imaging Devices |
| Companies Covered | Schlumberger Limited, Oceaneering International, Inc., TechnipFMC plc, Halliburton Energy Services, Inc., Saipem S.p.A., Subsea 7 S.A., Baker Hughes Company, Dril-Quip, Inc., Aker Solutions ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Equipment Market Strategic Shifts & Innovations
Technological evolution in the subsea sector is focused on increasing remote operational capability and reducing environmental footprints. Innovations are driven by the need for greater efficiency in deepwater projects and the adaptation of core technologies for new energy applications.
All-electric subsea systems provide control and power to wellheads and processing units using electrical actuators instead of hydraulic fluids. Major field operators are adopting this technology for new greenfield projects to enhance control precision and simplify umbilical designs. This technological shift is collapsing the traditional supply chain for hydraulic fluids and related maintenance services, reducing both operational complexity and potential environmental spill risk.
Regulatory mandates from bodies like Brazil's ANP are influencing equipment design and local supply chain development. These regulations often require specific levels of local content in manufacturing and assembly, forcing international vendors to establish partnerships or facilities within the country. Subsea manifold and pipeline manufacturers are most affected, reconfiguring their global fabrication and procurement strategies to ensure market access in key growth regions.
Operator procurement models are evolving from purchasing discrete hardware components to contracting for long-term production availability. This unbundles equipment sales from lifecycle services, creating openings for independent specialists in inspection, maintenance, and repair (IMR). The trend is most advanced in mature basins like the North Sea, where asset owners prioritize operational expenditure optimization over large initial capital outlays.
Subsea Equipment Market Segmentation
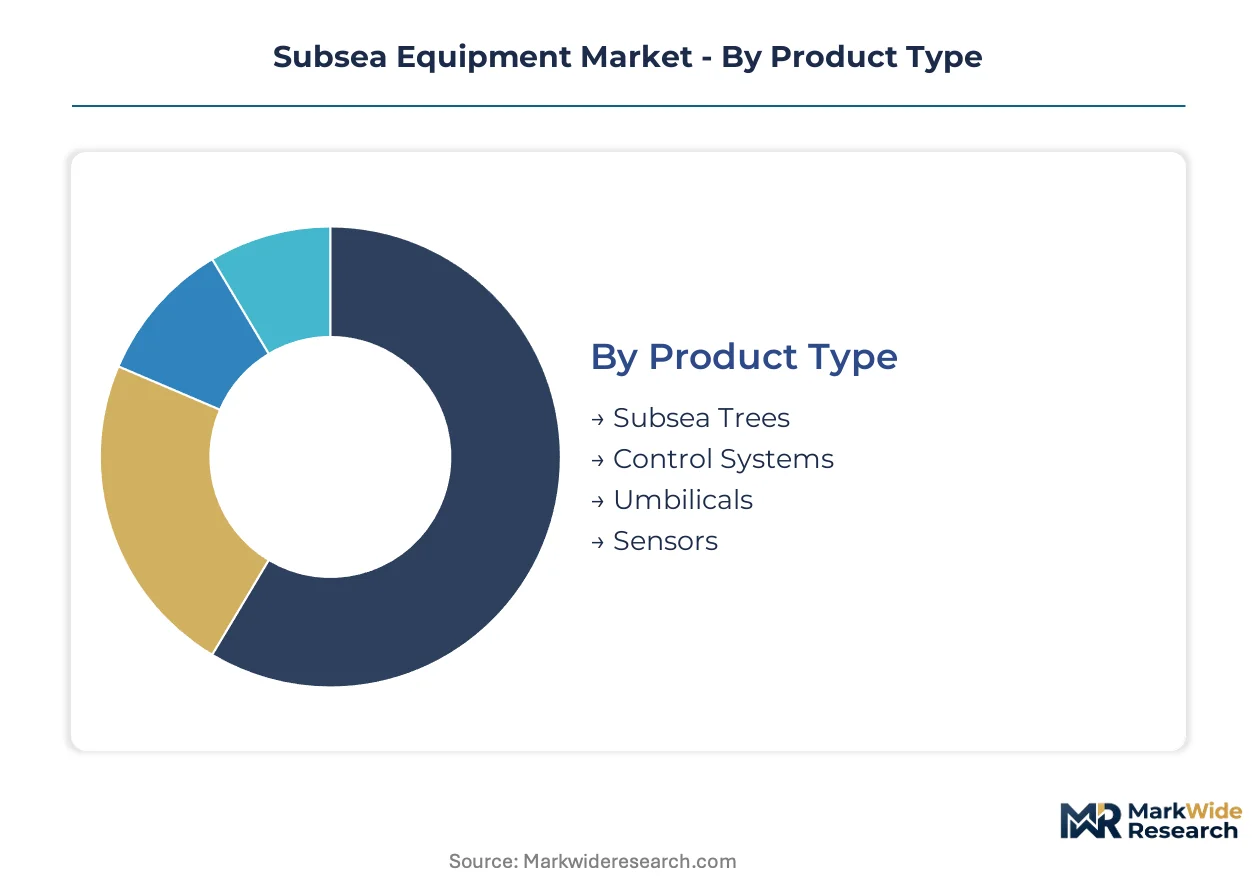
The subsea equipment market segmentation reflects the diverse technological requirements and operational demands across offshore energy projects. This detailed breakdown highlights the specialized hardware and services crucial for both hydrocarbon extraction and emerging renewable energy applications. Understanding these segments is essential for strategic market positioning and resource allocation.
Product Type:
The product type segment showcases a mix of mature, established components and evolving systems critical for deepwater operations.
- Subsea Trees:These complex assemblies are engineered from high-strength alloys to manage hydrocarbon flow at pressures exceeding 15,000 psi directly at the wellhead. New deepwater field developments in regions like Brazil's pre-salt basins drive significant demand for these high-specification units.
- Control Systems:These sophisticated electronic and hydraulic systems regulate the functions of subsea equipment, ensuring precise operation and safety in extreme environments. Advancements in all-electric subsea systems are enhancing control precision and simplifying umbilical designs for greenfield projects.
- Umbilicals:These composite cables provide power, communication, and hydraulic fluid delivery to subsea equipment from surface facilities.
- Sensors:Subsea sensors monitor pressure, temperature, flow, and other critical parameters for operational integrity and performance optimization.
Subsea Trees retains volume leadership; Control Systems holds the steepest expansion curve.
Application:
Application segments delineate where subsea equipment is deployed, spanning the full lifecycle from resource discovery to long-term asset management.
- Production:This application involves equipment designed for the extraction and processing of hydrocarbons or other resources from subsea wells. Deepwater oil extraction projects, especially in challenging pre-salt environments, are primary drivers for high-pressure production systems.
- Installation:This segment encompasses the deployment of subsea infrastructure, including trees, manifolds, and pipelines, onto the seabed. Specialized Remote Operated Vehicles are essential for precise placement and connection of components during complex deepwater installations.
- Offshore Exploration:Equipment in this area supports the identification and evaluation of potential hydrocarbon or mineral reserves on the seabed.
- Maintenance:This application focuses on the ongoing inspection, repair, and upkeep of installed subsea assets to ensure operational longevity and safety.
The market prioritizes Production for revenue generation, while Installation remains foundational for new project execution.
End User:
End user categories highlight the primary stakeholders procuring and utilizing subsea equipment, each with distinct operational requirements and procurement models.
- Oil & Gas Companies:These entities are the primary purchasers, investing in subsea equipment for offshore hydrocarbon exploration and production projects. Their procurement models are evolving towards long-term production availability contracts, optimizing operational expenditure.
- EPC Contractors:Engineering, Procurement, and Construction contractors integrate various subsea components into complete project solutions for field operators. Companies like TechnipFMC plc leverage integrated models to secure extensive long-term contracts.
- Research Institutions:These organizations utilize subsea equipment for scientific studies, environmental monitoring, and technology development in marine environments.
- Environmental Agencies:Regulatory bodies and environmental agencies deploy subsea sensors and monitoring systems to enforce compliance and assess ecological impact.
Oil & Gas Companies drive the bulk of capital expenditure, with EPC Contractors central to project delivery and integration.
Technology:
Technology segments reflect the specialized tools and systems enabling subsea operations, with innovation often driven by demands for increased remote capability and efficiency.
- Remote Operated Vehicles:ROVs are unmanned underwater vehicles controlled remotely, essential for deepwater inspection, maintenance, and complex installation tasks. Oceaneering International, Inc. dominates the provision of these specialized vehicles and their related services.
- Submersible Pump:These pumps are designed for deployment subsea, often used for boosting hydrocarbon flow from wells or for water injection. Their robust design allows operation in high-pressure, low-temperature deepwater environments.
- Acoustic Systems:These technologies use sound waves for navigation, communication, and imaging in underwater environments, crucial for surveying and positioning.
- Imaging Devices:Subsea imaging devices provide visual data for inspection, mapping, and monitoring of underwater infrastructure and seabed conditions.
Remote Operated Vehicles innovations are transforming operational capabilities, supported by Submersible Pump advancements for critical fluid management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global subsea equipment market exhibits varied demand patterns across key regions. Deepwater hydrocarbon extraction drives significant capital expenditure in some areas, while others prioritize subsea infrastructure for renewable energy projects. This dual focus necessitates adaptable technologies and localized supply chain strategies.
Brazil
Brazil's pre-salt basins drive substantial demand for high-specification subsea trees and control systems. Brazil's ANP enforces stringent local content rules, influencing manufacturing and assembly strategies. The offshore support industry around Rio de Janeiro concentrates engineering and fabrication capabilities for deepwater projects.
Norway
Norway continues to invest in complex subsea production systems for its mature North Sea fields and new frontier areas. The Norwegian Petroleum Directorate (NPD) mandates rigorous safety and environmental protocols for all offshore installations. The Stavanger-Bergen corridor hosts a robust cluster of subsea technology developers and specialized service providers.
United States
Deepwater oil and gas developments in the US Gulf of Mexico sustain a consistent demand for subsea equipment. The US Environmental Protection Agency (EPA) dictates strict environmental compliance for offshore operations, impacting equipment design. Houston, Texas, serves as a major hub for subsea engineering, manufacturing, and project management expertise.
Australia
Australia's expanding offshore gas projects, particularly off Western Australia, require advanced subsea processing and pipeline infrastructure. The National Offshore Petroleum Safety and Environmental Management Authority (NOPSEMA) oversees environmental and safety compliance for all offshore activities. Perth, Western Australia, functions as a critical operational base for subsea development and maintenance services.
India
India's drive for energy independence fuels deepwater exploration and production activities in its eastern and western offshore basins. The Directorate General of Hydrocarbons (DGH) outlines regulatory frameworks for offshore project execution and equipment specifications. Major ports like Mumbai and Chennai support the logistics and maintenance requirements for subsea installations.
Subsea Equipment Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the subsea equipment market. The market structure features a blend of large, integrated engineering, procurement, and construction (EPC) firms alongside highly specialized technology providers. A third archetype comprises agile service companies focusing on inspection, maintenance, and repair. Strategic partnerships and targeted portfolio diversification are common competitive moves among these players.
Among the integrated solution providers, TechnipFMC plc occupies a position leveraging its combined engineering, procurement, and construction capabilities for long-term project contracts. Aker Solutions ASA exemplifies specialization in complex subsea production systems, particularly for harsh operating environments like the North Sea. Oceaneering International, Inc. anchors the specialized services segment, providing advanced Remote Operated Vehicles and related inspection and maintenance expertise. These entities demonstrate varied approaches to securing market share and addressing diverse client needs.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Oceaneering International, Inc. |
| TechnipFMC plc |
| Halliburton Energy Services, Inc. |
| Saipem S.p.A. |
| Subsea 7 S.A. |
| Baker Hughes Company |
| Dril-Quip, Inc. |
| Aker Solutions ASA |
| Others |
Cost & Logistics Intelligence
The concentration of high-strength alloy production in specific global foundries directly influences the margin structures for subsea equipment manufacturers, particularly for high-pressure components like subsea trees.
Pricing Analysis
Long-term project-based contracts dominate subsea equipment pricing, often bundled with lifecycle services for production availability. Price differentiation stems from the customization level required for deepwater applications and adherence to stringent ISO 13628 certification standards. Pricing pressure intensifies for standardized components due to increased competition and global sourcing. Oil & Gas companies exhibit lower price sensitivity for critical deepwater production systems but greater sensitivity for routine inspection and maintenance services.
Supply Chain Analysis
Extended payment terms and specialized supply-chain finance facilities are common for large-scale subsea equipment procurement. Geographic supply concentration for specialized fabrication centers on Norway, Brazil, and the US Gulf Coast. The supply chain draws heavily on raw materials like nickel-based superalloys and advanced electronic components. Commodity price volatility for these specialized alloys represents a significant structural risk. Distribution for heavy subsea equipment primarily involves direct shipments from manufacturers to project sites or integration yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The subsea equipment market is undergoing a buyer-power shift, driven by the evolving procurement strategies of major Oil & Gas companies towards integrated solutions and long-term service contracts.
For Market Incumbents: Harden core capabilities in integrated engineering, procurement, and construction (iEPC) models to secure extensive long-term project contracts. Invest significantly in research and development for all-electric subsea systems to mitigate the long-term threat from hydraulic system obsolescence. Expand offerings for carbon capture and storage infrastructure to diversify beyond traditional hydrocarbon extraction. Focus on increasing regional manufacturing capabilities to meet local content requirements in key growth markets like Brazil.
For New Entrants and Emerging Players: Build out specialized service capabilities for emerging energy sectors like offshore wind and subsea hydrogen production. Target niche applications in advanced subsea data analytics and remote monitoring, leveraging expertise in digital integration. The provision of specialized Remote Operated Vehicle (ROV) services for inspection and maintenance in new energy projects represents a penetrable segment. Strategic partnerships with established offshore developers can provide crucial market access and pilot project opportunities.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized subsea technology providers and independent service companies, offering attractive acquisition targets in a market with long-term viability. Focus on companies with proprietary technologies in all-electric systems, advanced sensors, or specialized ROV capabilities. A key signal to watch is the increased sanctioning of deepwater carbon capture and storage projects, indicating a broader market shift beyond traditional oil and gas. Evaluate firms with strong intellectual property in subsea hardware compatible with hydrogen production facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| All-Electric System R&D | Enhances operational efficiency and reduces environmental risk for deepwater projects. |
| iEPC Model Expansion | Secures long-term revenue streams and strengthens client relationships for integrated providers. |
| Offshore Wind ROV Services | Diversifies service offerings into the rapidly expanding renewable energy infrastructure market. |
| Subsea Hydrogen JV | Positions companies for a new market vertical supporting green energy production facilities. |
| Advanced Sensor Development | Improves monitoring and control capabilities for complex subsea production systems. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews with subsea engineers, project managers at Oil & Gas companies, EPC procurement leads, and experienced ROV pilots. These insights were rigorously validated against secondary data sources including regulatory filings from Brazil's ANP and the US EPA, ISO 13628 standards, and company financial reports. The analysis employed both bottom-up and top-down triangulation to ensure comprehensive market coverage.
The calibration approach involved developing a robust analytical framework to project market trends across the analysis window. Segmentation dimensions modeled included product type, application, end user, technology, and regional deepwater activity. Compound annual growth rates were derived from a careful assessment of historical trends and projected market drivers. Key forecast inputs included global offshore wind project pipelines and deepwater field sanctioning rates across major basins.
Practitioners should monitor commodity price volatility for high-strength alloys and shifts in geopolitical stability for early signals of market change. Forecasts reflect a comprehensive set of assumptions regarding technological adoption and regulatory evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
Offshore Equipment Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
Egypt Oil and Gas Downstream Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Middle East and Africa Offshore Energy Market
Offshore Oil and Gas
Floating Production Storage and Offloading Market
Offshore Oil and Gas
Offshore Contract Drilling Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market