
 North America FLNG Market | 2026-2036
North America FLNG Market Size, Share, and Industry Trends Forecast 2026-2036
North America FLNG Market Analytics
The Inflation Reduction Act is expanding the cost-of-entry calculus for North America FLNG developers through methane emissions penalties and clean energy tax credit eligibility. ExxonMobil leverages its Permian Basin gas position to anchor feedstock supply for prospective Gulf Coast projects. Shell sustains technology leadership through its Prelude-class experience transferred to North American engineering studies. Golar LNG competes with its Hilli Episeyo conversion model, demonstrating lower capital intensity for mid-scale deployments.
North America FLNG refers to floating liquefied natural gas infrastructure—vessel-mounted or platform-based systems that chill natural gas to minus 162 degrees Celsius for transport—enabling monetization of offshore or stranded gas reserves without onshore terminal construction. Membrane containment systems dominate newbuild specifications due to higher cargo capacity and lower hull weight compared to Moss-type spherical tanks. Industrial end users represent the fastest-growing demand segment as Gulf Coast petrochemical complexes seek direct LNG offtake to bypass pipeline congestion. Engineering services command the deepest margin pools given the scarcity of contractors qualified for cryogenic marine design under US Coast Guard and BSEE dual jurisdiction.
FERC oversees onshore export authorization and interconnect permitting, while BSEE governs offshore safety and environmental compliance for floating production systems. EPA methane regulations under the Clean Air Act are forcing design modifications to flare minimization systems and fugitive emission monitoring protocols. The US Coast Guard enforces vessel construction and crewing standards under 46 CFR subchapters. Stakeholders must monitor how evolving carbon intensity benchmarks for LNG exports reshape project financing terms and offtake contract structures.
Market Dynamics
The North America FLNG market is being reshaped by the collision of tightening EPA methane performance standards against the economic pull of stranded gas monetization along the US Gulf Coast. Industrial off-takers are rewriting contract structures to capture direct LNG supply, bypassing pipeline bottlenecks that constrain traditional delivery models.
Growth Catalysts
- Membrane containment systems:Higher cargo capacity and reduced hull weight are accelerating vessel specifications across newbuild orders. These systems enable mid-scale FLNG deployments that match fragmented reserve profiles.
- Industrial off-taker expansion:Gulf Coast petrochemical complexes are executing direct offtake agreements to secure feedstock supply independent of pipeline congestion. This bypass model reduces price volatility exposure.
- FERC export authorization framework:Streamlined interconnect permitting for floating liquefaction units is compressing project development timelines. Dual-jurisdiction coordination with BSEE is clarifying safety compliance pathways.
Market Restraints
- Specialized contractor scarcity:Cryogenic marine engineering capacity concentrates among a handful of firms qualified under US Coast Guard and BSEE dual jurisdiction. This bottleneck inflates EPC pricing and extends delivery schedules.
- High-alloy steel input costs:Nickel and molybdenum price volatility directly impacts containment system fabrication economics. Hull construction faces margin compression when commodity cycles spike.
- Onshore terminal substitution:Conventional land-based liquefaction retains cost advantages at scale for large reserve developments. Brownfield brownfield expansions at existing Gulf Coast sites compete for the same feedstock pools.
Strategic Opportunities
- Louisiana port zone clustering:Existing pipeline interconnect density at Cameron and Calcasieu Pass reduces stranded gas risk for floating deployments. Infrastructure reuse lowers breakeven thresholds.
- Inflation Reduction Act methane penalties:Clean energy tax credit eligibility is rewarding projects with verified low-carbon intensity. Carbon accounting transparency is becoming a financing differentiator.
- Small-scale modular liquefaction:Convergence of barge-mounted compression with shore-based power integration is opening mid-scale niches below traditional FLNG scale. This hybrid architecture matches marginal field economics.
Industry Challenges
- Cryogenic welding certification timelines:US Coast Guard qualification requirements for 9% nickel steel joining extend crew mobilization lead times. Skilled inspector availability constrains construction velocity.
- Flare minimization system integration:EPA methane regulations mandate closed-loop vapor recovery that complicates topside process design. Engineering change orders proliferate during detailed design phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America FLNG Market |
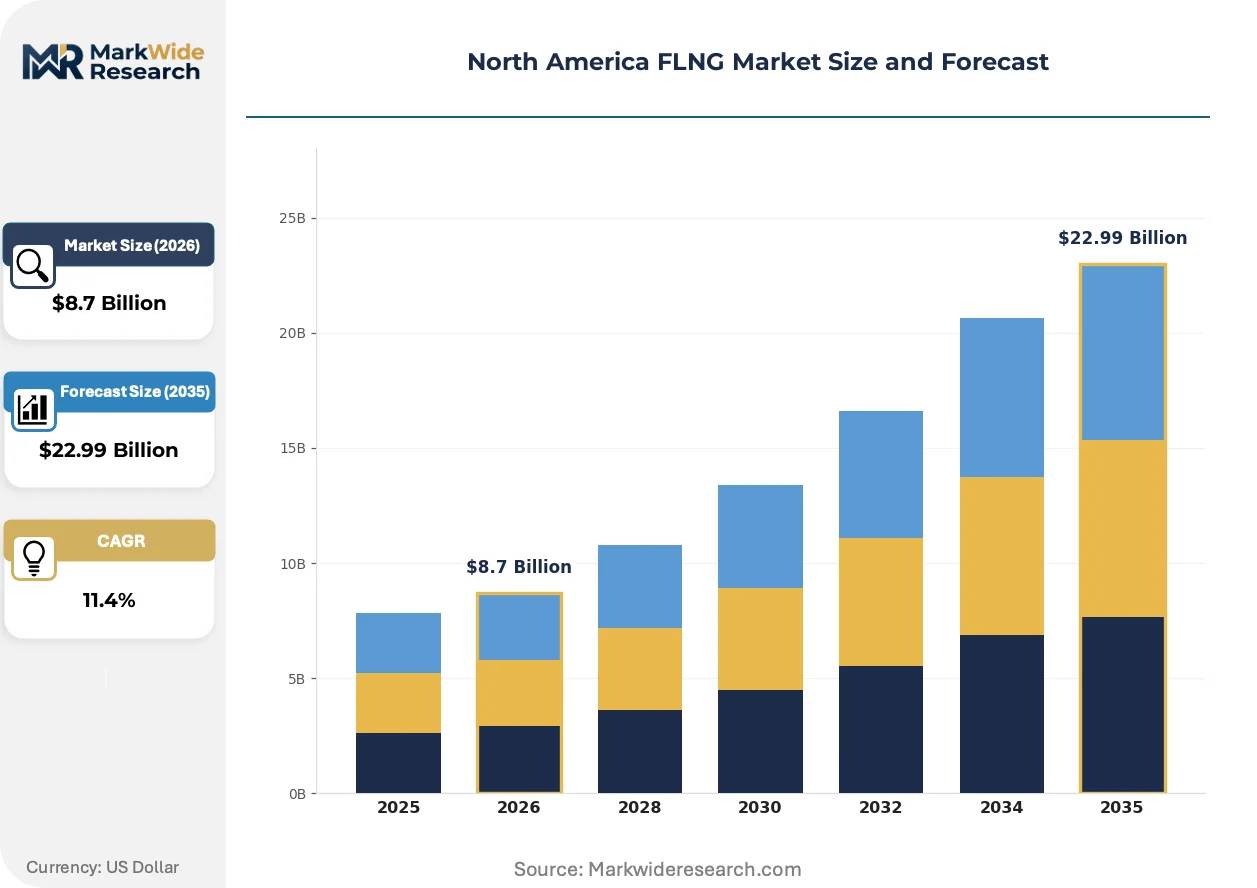
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane, Moss, SPB, Other End User: Utility, Industrial, Government, Commercial Operation Mode: Construction, Pipelines, Storage, Export Service Type: Engineering, Consultancy, Operations, Maintenance |
| Companies Covered | ExxonMobil, Shell, Chevron, Golar LNG, New Fortress Energy, Woodside Petroleum, Eni, Technip Energies, Black & Veatch Holding Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America FLNG Market Evolving Landscape
Technology trajectories in North American FLNG are converging on modular architectures that decouple liquefaction capacity from vessel scale. Regulatory pressure and buyer procurement evolution are simultaneously compressing project timelines and expanding performance verification requirements.
Membrane containment technology is overtaking Moss-type spherical tanks in newbuild specifications. Gulf Coast developers specify GTT Mark III and NO96 systems for their superior volumetric efficiency. Industrial off-takers with direct offtake contracts are driving this specification shift to maximize cargo flexibility per hull.
EPA methane performance standards under the Clean Air Act are forcing real-time emission monitoring integration into process control systems. FLNG operators must deploy optical gas imaging and continuous analyzer networks to demonstrate compliance. Texas and Louisiana projects face the steepest retrofit burden where legacy flare systems predominate.
Long-term tolling agreements are displacing merchant risk models as the dominant commercial structure. Petrochemical buyers with captive gas demand are underwriting project finance through take-or-pay commitments. This shift concentrates counterparty risk assessment on off-taker credit quality rather than reserve certification alone.
North America FLNG Market Segmentation
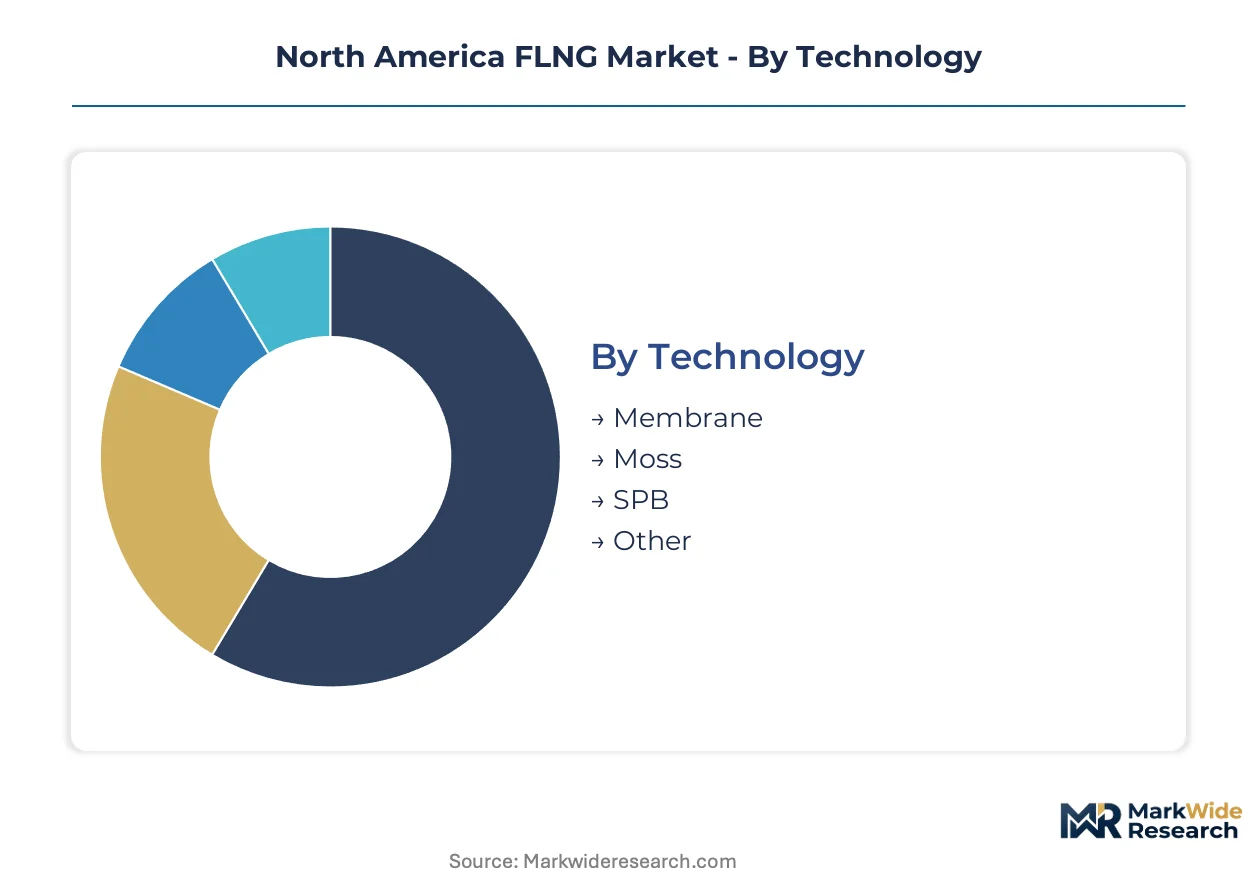
Technology selection dictates capital intensity and cargo economics for Gulf Coast developers weighing membrane against Moss-type configurations. End-user contracting structures determine revenue stability across utility baseload demand versus industrial spot exposure. Understanding segment interdependencies clarifies where engineering margins concentrate versus commodity-exposed operations.
Technology:
Buyers prioritize volumetric efficiency and hull steel tonnage when specifying containment systems for stranded gas monetization.
- Membrane:GTT Mark III and NO96 systems utilize corrugated stainless steel and polyurethane foam insulation to maximize cargo volume within hull constraints. Gulf Coast petrochemical off-takers favor this specification for its superior cubic meter yield per deadweight ton, directly lowering delivered LNG costs to Texas and Louisiana port terminals.
- Moss:Spherical aluminum tanks suspended in hull structures deliver proven cryogenic integrity for harsh weather deployments. Arctic-exposed Atlantic projects specify Moss systems despite 15-20% cargo volume penalties, trading efficiency for structural redundancy under BSEE safety mandates.
- SPB:Self-supporting prismatic tanks of aluminum or 9% nickel steel offer intermediate volumetric performance with simplified inspection protocols.
- Other:Emerging composite containment and hybrid membrane-spherical configurations address niche small-scale liquefaction requirements.
Membrane leads on scale; SPB gains share fastest in mid-scale modular deployments.
End User:
Contract duration and credit quality vary sharply across buyer categories, reshaping project finance underwriting criteria.
- Industrial:Petrochemical complexes along the Houston Ship Channel and Lake Charles execute direct offtake agreements to bypass pipeline congestion. These buyers accept merchant price exposure in exchange for supply security, concentrating counterparty risk assessment on balance sheet strength rather than rate-base regulation.
- Utility:Regulated gas distribution utilities in Texas and Louisiana seek long-term tolling contracts with FERC-export-authorized capacity. Their investment-grade ratings anchor non-recourse project debt, though load-following flexibility demands complicate liquefaction train sizing.
- Government:State energy security programs and municipal port authorities pursue strategic reserve capacity with sovereign guarantee backing.
- Commercial:Traders and aggregators exploit arbitrage between Henry Hub and JKM pricing, requiring rapid cargo turnaround and minimal destination restrictions.
Utility anchors financing capacity; Industrial climbs the fastest on contract volume.
Operation Mode:
Revenue recognition timing and capital deployment intensity diverge across the project lifecycle spectrum.
- Export:FOB cargo loading operations generate the highest revenue per throughput ton, with liquefaction tolling fees stacked onto shipping differentials. Cameron and Calcasieu Pass infrastructure density minimizes stranded gas risk for export-focused deployments.
- Storage:Seasonal injection and withdrawal services capture Henry Hub contango, though tankage yields compress against pipeline deliverability.
- Construction:EPC phase margins concentrate among US Coast Guard-qualified contractors for cryogenic marine fabrication.
- Pipelines:Interconnect and gathering system operations face regulated tariff ceilings under FERC jurisdiction.
Export leads on scale; Storage gains share fastest on seasonal volatility capture.
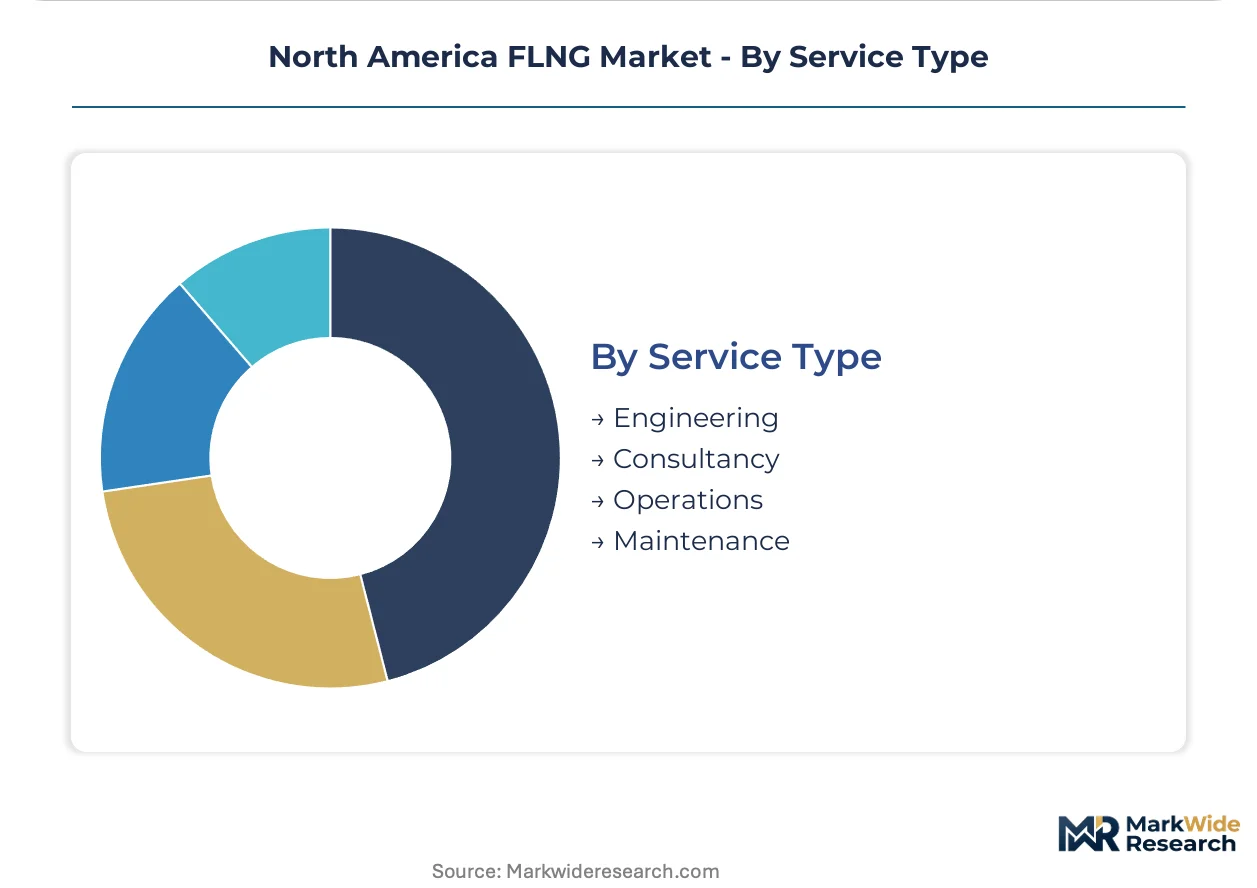
Service Type:
Capability scarcity and certification barriers determine margin retention across the value chain.
- Engineering:Front-end design and detailed engineering for cryogenic marine systems command premium pricing due to dual US Coast Guard and BSEE qualification requirements. FEED contractors with Prelude-class or Hilli Episeyo experience capture disproportionate market share.
- Operations:Liquefaction train commissioning and steady-state production management generate recurring revenue with long-term contract tenors.
- Consultancy:Regulatory navigation and carbon intensity verification services expand under EPA methane performance standards.
- Maintenance:Drydock and in-service inspection protocols face compressed margins against standardized class society schedules.
Engineering leads on scale; Consultancy expands most quickly on compliance complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cryogenic welding crews and marine liquefaction engineers concentrate along the US Gulf Coast, anchoring North America's FLNG talent base and project development velocity.
United States
Texas and Louisiana port zones drive deployment decisions through dense pipeline interconnects at Cameron and Calcasieu Pass. EPA methane performance standards under the Clean Air Act mandate closed-loop vapor recovery systems for all floating liquefaction units. Houston Ship Channel petrochemical complexes execute direct offtake agreements to bypass pipeline congestion.
Canada
British Columbia's stranded gas reserves and Pacific export positioning attract preliminary FLNG feasibility studies. The country's national energy regulator coordinates with marine safety authorities to clarify dual-jurisdiction compliance pathways. Vancouver-area engineering consultancies develop cold-climate containment specifications for potential Arctic deployments.
Mexico
Offshore gas discoveries in the Gulf of Mexico stimulate interest in floating liquefaction as an alternative to land-constrained Pacific terminals. The country's national hydrocarbons commission evaluates export authorization frameworks for private-sector floating projects. Tamaulipas port authorities assess infrastructure compatibility with mid-scale membrane containment systems.
North America FLNG Market Competitive Landscape
The competitive structure tilts toward integrated energy majors with captive upstream positions and specialized marine engineering contractors with dual-certification credentials. Player concentration splits between liquefaction technology licensors, vessel operators, and EPC consortia qualified under US Coast Guard and BSEE jurisdiction. Two archetypes dominate: Permian-anchored feedstock suppliers leveraging basin-scale gas positions, and conversion specialists repurposing existing LNG carriers for mid-scale deployments. Capacity expansion through modular train additions and strategic partnerships for cryogenic marine fabrication represent the primary competitive vectors.
Among integrated majors with Gulf Coast positioning, ExxonMobil and Shell exemplify the upstream-anchored archetype, while Golar LNG occupies a distinctive position as a conversion-focused vessel operator. ExxonMobil's Permian Basin gas production provides feedstock integration potential. Shell transfers Prelude-class engineering experience to North American project studies. Golar LNG demonstrates lower capital intensity through its Hilli Episeyo conversion model.
| Leading Market Players |
|---|
| ExxonMobil |
| Shell |
| Chevron |
| Golar LNG |
| New Fortress Energy |
| Woodside Petroleum |
| Eni |
| Technip Energies |
| Black & Veatch Holding Company |
| Others |
Value Network & Pricing Analysis
Captive upstream integration into Permian Basin feedstock supply anchors both procurement leverage and tolling fee negotiating power for Gulf Coast FLNG developers. This structural choice compresses breakeven thresholds while insulating project returns from Henry Hub volatility exposure.
Pricing Analysis
Bundled tolling agreements dominate commercial structures, stacking liquefaction fees onto FOB cargo pricing. Unbundled merchant models persist among trader off-takers seeking destination flexibility. Price differentiation centers on carbon intensity certification tiers under EPA methane performance standards and FERC export authorization status. Cost compression in engineering services intensifies as qualified EPC contractors compete for limited project slots. Industrial petrochemical buyers exhibit lowest price sensitivity due to captive feedstock demand, while commercial traders face acute margin pressure from JKM-Henry Hub spread compression.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Japanese shipyards for membrane containment system fabrication. France supplies GTT Mark III and NO96 technology licensing. Raw material dependencies center on nickel and molybdenum alloys for cryogenic steel, plus specialized polyurethane foam insulation. Tariff exposure on high-alloy steel imports threatens containment system cost structures. Distribution runs through Houston Ship Channel engineering consortia qualified under dual US Coast Guard and BSEE jurisdiction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
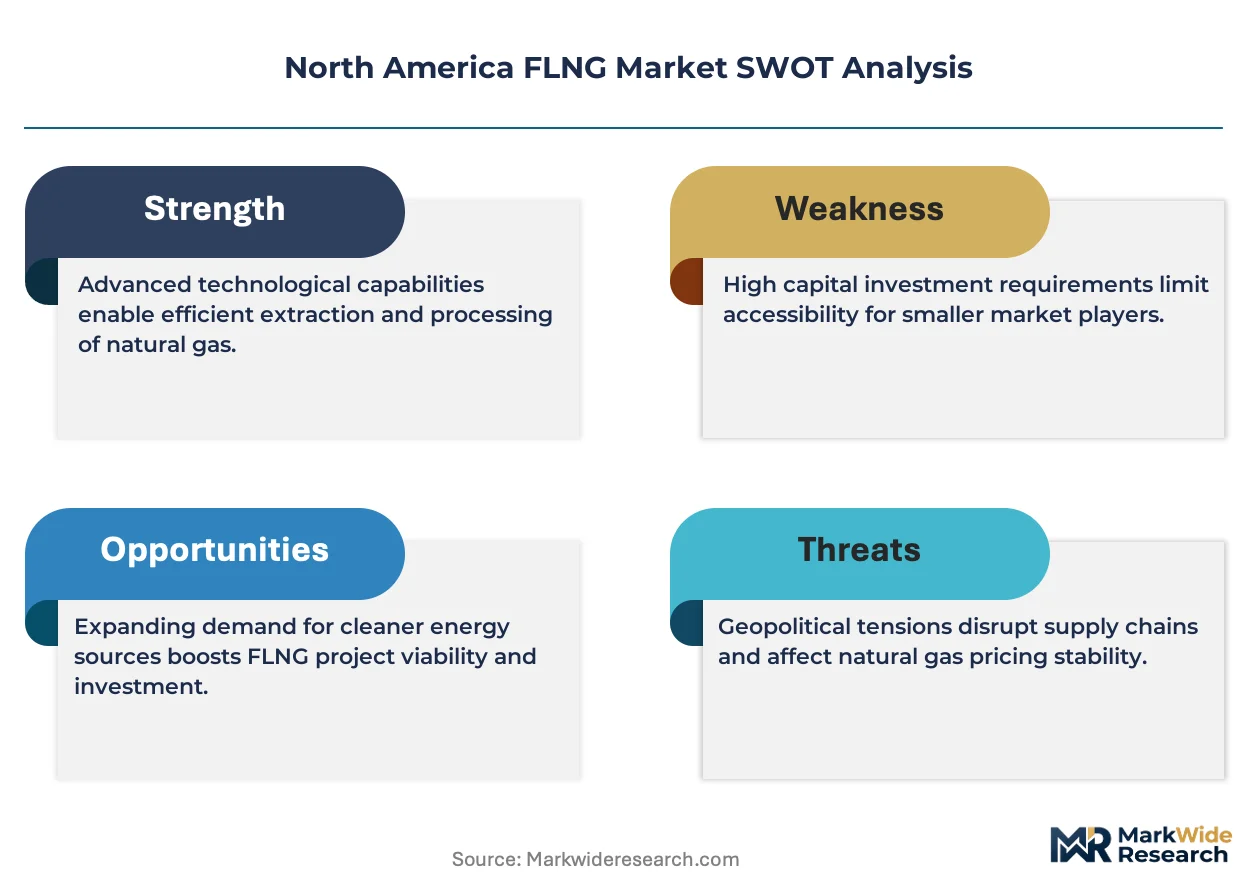
North America FLNG functions as a regulatory compounder where EPA methane performance standards and Inflation Reduction Act credit eligibility continuously reshape project economics. These frameworks reward verified low-carbon intensity with financing advantages.
For Market Incumbents: Cement feedstock integration through Permian Basin gathering system acquisitions to defend against stranded gas risk. Secure long-term tolling contracts with investment-grade industrial off-takers before competitor capacity additions at Cameron and Calcasieu Pass compress margin pools. Prioritize cryogenic welding crew certification investments to accelerate construction timelines.
For New Entrants and Emerging Players: Modular barge-mounted liquefaction technology offers a technology-first wedge into mid-scale deployments below traditional FLNG scale. Target Louisiana port zone clustering where existing pipeline interconnect density reduces infrastructure capital requirements. Pursue direct offtake partnerships with Houston Ship Channel petrochemical complexes seeking supply security.
For Investors and Strategic Acquirers: Roll-up economics work for engineering consultancies with dual US Coast Guard and BSEE qualification credentials because contractor scarcity inflates acquisition multiples. Long-term viability hinges on carbon intensity verification capability across the analysis window. Monitor EPA enforcement patterns on methane emissions as the inflection indicator for project financing availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Permian Basin Feedstock Integration | Captive gas supply anchors tolling fee negotiating power against Henry Hub volatility. |
| Membrane Containment Technology Licensing | GTT Mark III specifications maximize cargo yield per deadweight ton for Gulf Coast routes. |
| Cryogenic Marine Engineering Certification | Dual US Coast Guard and BSEE qualification commands premium EPC pricing. |
| Industrial Direct Offtake Agreements | Petrochemical buyers provide investment-grade counterparty risk for project finance. |
| EPA Methane Compliance Infrastructure | Closed-loop vapor recovery systems satisfy Clean Air Act performance standards. |
Research Methodology
Bottom-up industrial off-take modeling reconciled against top-down liquefaction capacity tracking forms the analytical core. Primary interviews with FLNG project developers, EPC contractors, petrochemical procurement directors, and FERC regulatory specialists combined with secondary validation from EIA production data, FERC export authorization filings, BSEE safety incident reports, and EPA emissions databases. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Input-output matrices map feedstock availability, liquefaction train specifications, and offtake contract structures to project revenue streams. Segmentation dimensions span containment technology type, end-user category, operation mode, and service type across the modeling period. CAGRs derive from capacity deployment schedules and tolling fee trajectories. Forecast inputs include Permian Basin production forecasts, nickel alloy price cycles, and EPA regulatory enforcement intensity.
The model holds under stable FERC export authorization timelines and consistent EPA methane enforcement; deviation in regulatory permitting delays or carbon intensity benchmark revisions would shift capacity deployment schedules. Forecasts reflect documented assumptions about industrial demand growth and contractor availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
China Oil and Gas Downstream Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
Europe LNG Bunkering Market
Offshore Oil and Gas
Global Mobile Offshore Drilling Units Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
Marine Mining Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market