
 Jumbo Kraft Tubes Market | 2026-2036
Jumbo Kraft Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Jumbo Kraft Tubes Market Foresight
North American paperboard mill capacity is consolidating around jumbo tube-grade kraft production. Sonoco Products Company leverages its integrated fiber supply network across the southeastern United States. Smurfit Kappa Group anchors European demand through its recycled paper tube operations in Iberia and the Baltics. Mondi Group differentiates via specialty coated paper formulations for pharmaceutical-grade tubes.
Jumbo kraft tubes are spiral-wound or convolute-wound cylindrical containers fabricated from multi-ply kraft paperboard, typically ranging from 6 inches to over 40 inches in diameter and engineered to axial crush loads exceeding 10,000 pounds for heavy-duty industrial winding and shipping applications. Plain tubes dominate volume shipments for textile and film cores where cost minimization governs procurement, while laminated tubes command margin premiums in cosmetics and pharmaceutical end uses where moisture barrier performance determines specification compliance. Custom tubes represent the fastest-growing product type as industrial buyers specify exact inner diameter tolerances and proprietary surface treatments for automated winding lines.
EPA industrial effluent guidelines constrain kraft pulping operations in the United States, raising recovered fiber utilization rates across tube manufacturers. EU REACH and F-Gas Regulation frameworks restrict certain coating chemistries used in laminated tube barriers, redirecting R&D toward bio-based moisture barriers. India's BIS packaging standards mandate minimum recycled content thresholds for paperboard containers sold into domestic industrial channels. Stakeholders must monitor evolving extended producer responsibility schemes and calibrate material certification strategies against buyer sustainability scorecards.
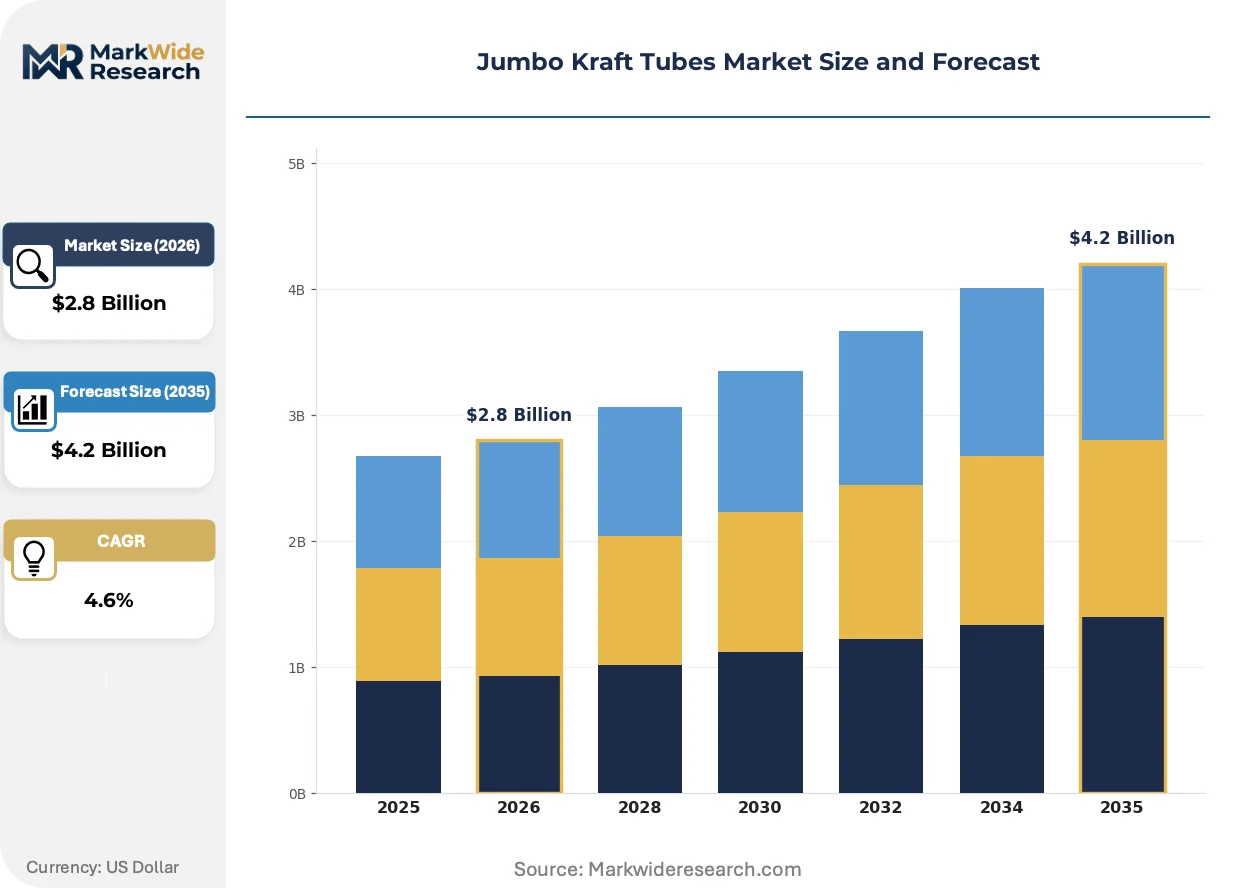
Market Dynamics
EU packaging waste regulations and FSC chain-of-custody certifications are restructuring material sourcing requirements across the Jumbo Kraft Tubes Market, forcing converters to requalify fiber suppliers and redirect procurement toward certified recycled streams.
Growth Catalysts
- Food Industry demand:Buyers are scaling orders for laminated and custom tube formats to replace rigid plastic packaging in dry goods and specialty food segments.
- REACH and F-Gas Regulation:These EU frameworks are accelerating R&D investment in bio-based moisture barriers, opening specification pathways for compliant tube producers.
- Paperboard converting capacity expansion:Germany, India, and Brazil are building domestic spiral-winding infrastructure, reducing import dependency for industrial end users.
Market Restraints
- Recovered fiber cost volatility:EPA industrial effluent guidelines constrain kraft pulping operations in the United States, elevating dependence on post-consumer fiber with price swings tied to municipal collection rates.
- Coating chemistry restrictions:EU REACH Annex XVII limitations on fluorinated compounds eliminate certain high-performance barrier options for pharmaceutical-grade tubes.
- Substitution by rigid plastics:Polypropylene cores retain cost advantages in moisture-critical textile winding applications where axial crush tolerances are moderate.
Strategic Opportunities
- Brazilian domestic market:Underpenetrated industrial packaging channels present white space for locally manufactured jumbo tubes serving film and nonwoven producers.
- Extended producer responsibility schemes:EU Green Deal implementation creates compliance-driven demand for certified recyclable tube formats with documented end-of-life pathways.
- Digital printing integration:Convergence of inkjet decoration technology with spiral-winding lines enables short-run custom branding for cosmetics and premium food segments.
Industry Challenges
- Chain-of-custody certification timelines:FSC and PEFC multi-site audits require 12-18 month implementation cycles, delaying qualification for EU-based brand owner supply chains.
- Automated winding line integration:Custom tube specifications for Industry 4.0 winding equipment demand sub-millimeter diameter tolerances that strain legacy spiral-winding assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jumbo Kraft Tubes Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain Tubes, Printed Tubes, Laminated Tubes, Custom Tubes Material: Kraft Paper, Recycled Paper, Coated Paper, Others End User: Food Industry, Cosmetics, Pharmaceuticals, Industrial Supplies Packaging Type: Rigid Packaging, Flexible Packaging, Eco-Friendly Packaging, Tube Packaging |
| Companies Covered | Sonoco Products Company, Smurfit Kappa Group, Mondi Group, DS Smith Plc, International Paper, Greif, Inc., Valk Industries Inc., Western Container Corporation, Ace Paper Tube, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jumbo Kraft Tubes Market Shifts & Advancements
Active developments across barrier technology, regulatory compliance architecture, and buyer procurement systems are compressing product development cycles and redefining competitive differentiation in tube manufacturing.
Bio-based moisture barriers derived from cellulose nanofibrils and plant-derived waxes are unifying performance and sustainability specifications previously served by synthetic coatings. Pharmaceutical and cosmetics packagers in Northern Europe are piloting these formulations at commercial scale. This unification is collapsing the traditional premium gap between laminated and plain tube categories.
REACH authorization procedures and the EU F-Gas Regulation are systematically removing per- and polyfluoroalkyl substances from approved coating chemistries. Tube laminators must reformulate barrier layers or sacrifice access to EU pharmaceutical and food-contact markets. German and Iberian converters are investing in plasma treatment and aqueous dispersion technologies to maintain specification compliance.
Consolidated buying desks at multinational film and textile producers are compressing supplier qualification cycles and demanding integrated logistics services. Direct mill-to-plant tube delivery programs are displacing distributor-stocked inventory models. This pattern is most pronounced in the southeastern United States and western Germany where winding operations cluster near converted paperboard mills.
Jumbo Kraft Tubes Market Segmentation
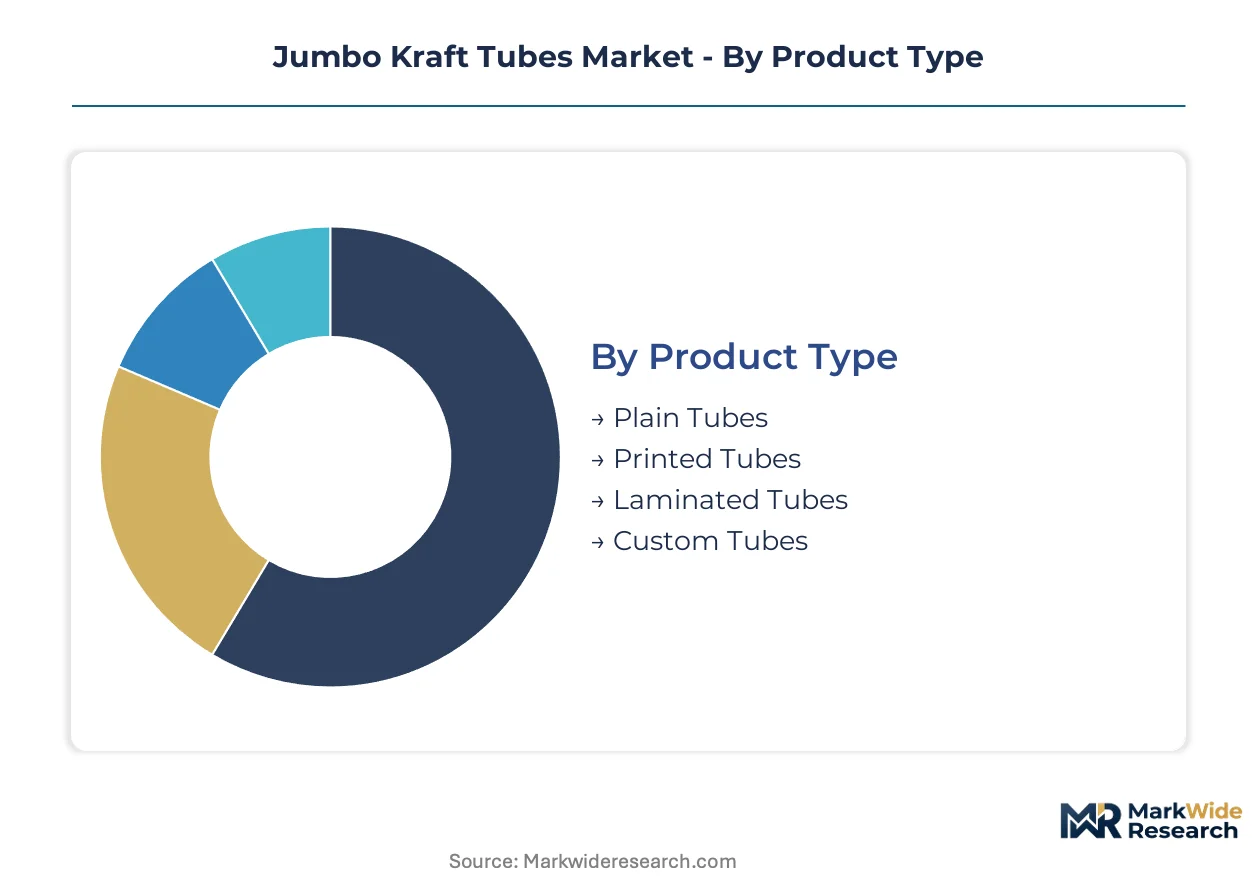
Tube specification diversity drives procurement complexity across industrial winding, food contact, and pharmaceutical barrier applications. Buyers segment requirements by structural performance, surface functionality, and compliance certification rather than commoditized diameter and wall thickness alone.
Product Type:
Standalone tube formats operate independently in end-use equipment, while embedded configurations integrate into automated winding lines with tight tolerance specifications.
- Plain Tubes:Unlaminated kraft paperboard cylinders serve textile cores and film winding where axial crush loads exceed 10,000 pounds but moisture exposure remains minimal. Demand concentrates in southeastern United States textile clusters where cost minimization governs procurement against polypropylene substitutes.
- Laminated Tubes:Multi-ply constructions with synthetic or bio-based moisture barriers protect hygroscopic contents in pharmaceutical and cosmetics applications. EU REACH and F-Gas Regulation compliance requirements are redirecting German and Iberian converter R&D toward cellulose nanofibril formulations.
- Printed Tubes:Direct surface decoration enables brand differentiation for premium food and cosmetics segments without secondary labeling operations.
- Custom Tubes:Exact inner diameter tolerances and proprietary surface treatments match Industry 4.0 winding equipment specifications. Sub-millimeter precision requirements strain legacy spiral-winding assets.
Volume placements concentrate in Plain Tubes; the faster expansion belongs to Custom Tubes.
Material:
Raw material selection stratifies across virgin fiber performance, recycled content mandates, and functional coating requirements.
- Kraft Paper:Virgin unbleached sulfate pulp delivers maximum axial crush strength for heavy-duty industrial winding cores. EPA industrial effluent guidelines constrain United States kraft pulping operations, elevating recovered fiber utilization rates.
- Recycled Paper:Post-consumer fiber streams meet India's BIS packaging standards minimum recycled content thresholds for domestic industrial channels. Price volatility tied to municipal collection rates constrains procurement planning.
- Coated Paper:Specialty barrier formulations serve pharmaceutical-grade tube specifications requiring moisture vapor transmission control.
- Others:Hybrid fiber blends and experimental agricultural residue pulps address emerging sustainability scorecard requirements.
Procurement volumes favor Recycled Paper; specification premiums attach to Coated Paper.
End User:
Customer type determines tolerance precision, barrier performance, and certification documentation intensity.
- Food Industry:Dry goods and specialty food segments are scaling orders for laminated and custom tube formats to replace rigid plastic packaging. FSC chain-of-custody certification documentation satisfies EU extended producer responsibility scheme compliance.
- Pharmaceuticals:Moisture barrier performance determines specification compliance for drug product protection. EU REACH Annex XVII limitations on fluorinated compounds eliminate certain high-performance barrier options.
- Cosmetics:Premium positioning demands integrated digital printing capabilities for short-run custom branding.
- Industrial Supplies:Film and nonwoven producers in Brazil present underpenetrated demand for locally manufactured jumbo tubes.
Industrial Supplies generates the highest shipment volumes; Food Industry climbs the fastest on plastic substitution momentum.
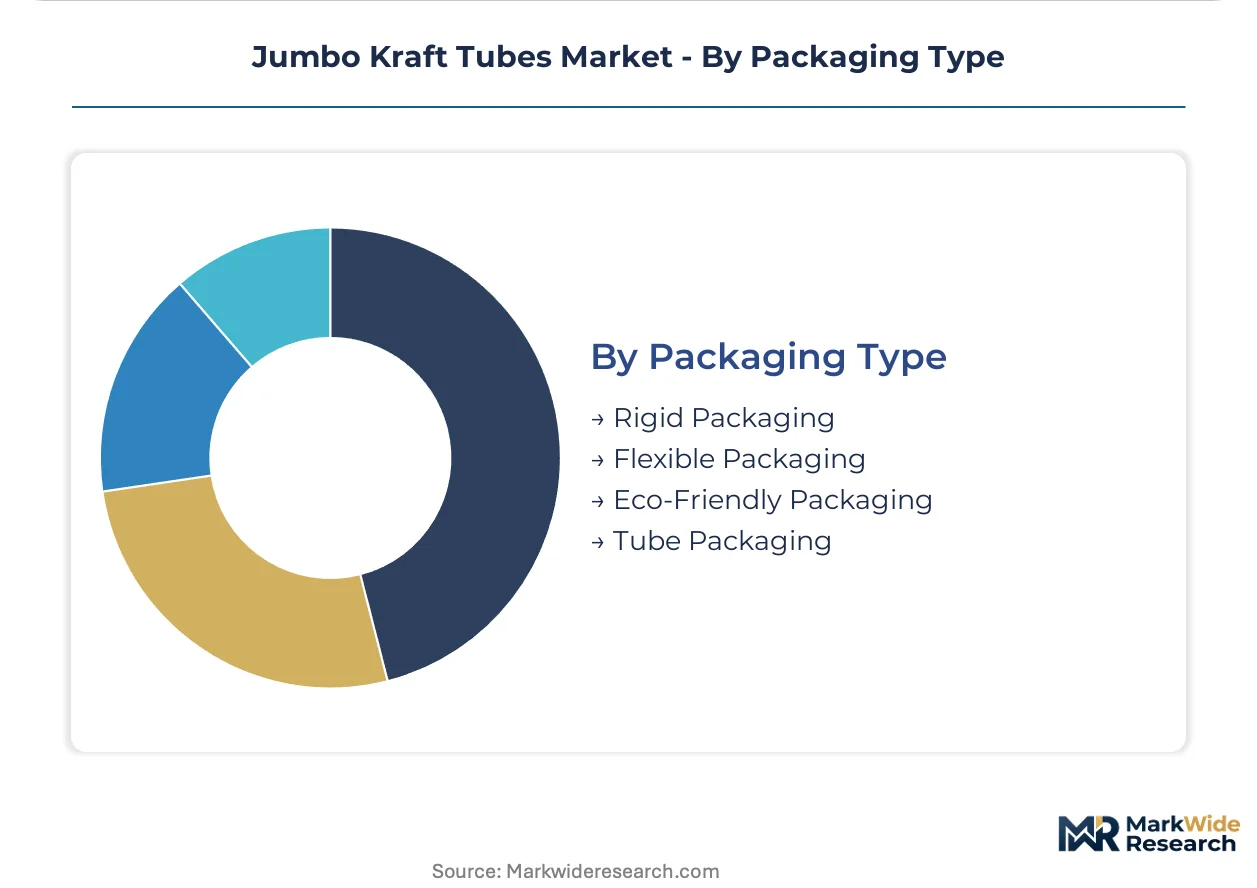
Packaging Type:
Format classification reflects structural rigidity, end-of-life pathway, and supply chain integration depth.
- Rigid Packaging:Spiral-wound and convolute-wound cylinders maintain dimensional stability under axial and radial loads for heavy-duty shipping applications.
- Eco-Friendly Packaging:Certified recyclable formats with documented end-of-life pathways capture EU Green Deal implementation compliance-driven demand.
- Flexible Packaging:Collapsible or semi-rigid constructions serve specialized logistics configurations.
- Tube Packaging:Dedicated winding and dispensing functionality distinguishes this format from general rigid containment.
Shipment concentration sits with Rigid Packaging; Eco-Friendly Packaging gains share fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recovered fiber availability and spiral-winding infrastructure concentration determine regional competitiveness across jumbo kraft tube supply chains. Germany, India, Brazil, and the United States anchor production capacity, while regulatory divergence on recycled content mandates and barrier chemistry approvals fragments procurement strategies.
Germany
Food Industry buyers in Bavaria and North Rhine-Westphalia are scaling laminated tube orders for dry goods packaging. EU REACH Annex XVII and the F-Gas Regulation are accelerating converter investment in cellulose nanofibril barrier R&D. The Hamburg industrial corridor hosts plasma treatment technology pilots serving pharmaceutical-grade tube specifications.
India
Domestic film and textile producers in Maharashtra and Gujarat are expanding orders for custom tube formats with sub-millimeter tolerances. BIS packaging standards mandate minimum recycled content thresholds for paperboard containers in industrial channels. The Tamil Nadu paperboard converting cluster is adding spiral-winding capacity to reduce import dependency.
Brazil
Underpenetrated film and nonwoven winding channels in São Paulo and Minas Gerais are driving demand for locally manufactured jumbo tubes. ANVISA pharmaceutical packaging regulations are elevating documentation requirements for moisture barrier performance. The Rio Grande do Sul industrial corridor is attracting greenfield paperboard mill investment.
United States
Southeastern textile clusters in Georgia and the Carolinas concentrate plain tube procurement for cost-sensitive film core applications. EPA industrial effluent guidelines constrain kraft pulping operations, elevating recovered fiber utilization rates. The Pacific Northwest maintains specialty coated paper capacity for pharmaceutical-grade tube exports.
United Kingdom
Cosmetics packagers in London and the Southeast are piloting digitally printed tube formats for premium short-run branding. Extended producer responsibility schemes under the EU Green Deal framework are redirecting procurement toward certified recyclable formats. The Midlands industrial belt hosts integrated logistics programs linking mills to automated winding lines.
Jumbo Kraft Tubes Market Competitive Landscape
Global majors compete with regional champions across fiber supply integration and certification depth. The vendor base stratifies between integrated paperboard producers with captive pulp supply and independent converters reliant on merchant fiber markets. Three archetypes dominate: integrated fiber-to-tube operators, specialty barrier laminators, and precision custom fabricators. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with players securing FSC chain-of-custody documentation and winding line integration capabilities.
Among North American integrated operators, Sonoco Products Company exemplifies the fiber-captive archetype through southeastern United States mill networks. Smurfit Kappa Group represents the European recycled paper tube specialist with Iberian and Baltic operations. Mondi Group occupies the specialty coated paper tier, anchoring pharmaceutical-grade barrier development. These three sit within distinct competitive vectors—fiber security, geographic density, and formulation differentiation—rather than direct product overlap.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Smurfit Kappa Group |
| Mondi Group |
| DS Smith Plc |
| International Paper |
| Greif, Inc. |
| Valk Industries Inc. |
| Western Container Corporation |
| Ace Paper Tube |
| Others |
Supply & Pricing Matrix
Recovered Old Corrugated Container (OCC) price indices from the US Southeast and German merchant markets cascade through jumbo kraft tube supply chains into three distinct procurement tiers. Buyers with captive fiber supply command margin stability against merchant-dependent converters exposed to municipal collection volatility. Laminated pharmaceutical-grade specifications capture premium positioning through REACH-compliant barrier investments, while plain textile cores compete on delivered cost against polypropylene substitutes.
Pricing Analysis
Logistics bundling separates mill-direct contract structures from distributor-stocked spot purchases. Three-tier pricing stratifies across FSC-certified laminated formats, standard recycled-content industrial grades, and economy plain tubes for cost-sensitive textile winding. Cost compression in plain tube segments intensifies as recovered fiber volatility strains merchant-dependent converters. Food Industry buyers demonstrate lowest price sensitivity, prioritizing moisture barrier documentation and chain-of-custody certification over unit economics.
Supply Chain Analysis
Kraft pulp supply rests on integrated southeastern US mills, Iberian recycled fiber networks, and emerging Tamil Nadu converting clusters. Virgin unbleached sulfate pulp, post-consumer OCC streams, and cellulose nanofibril barrier formulations constitute critical input dependencies. Single-source vulnerability concentrates in plasma treatment equipment for pharmaceutical-grade surface modification. Distribution runs through direct mill-to-plant programs displacing regional distributor inventories near Georgia textile corridors and Bavaria film winding clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
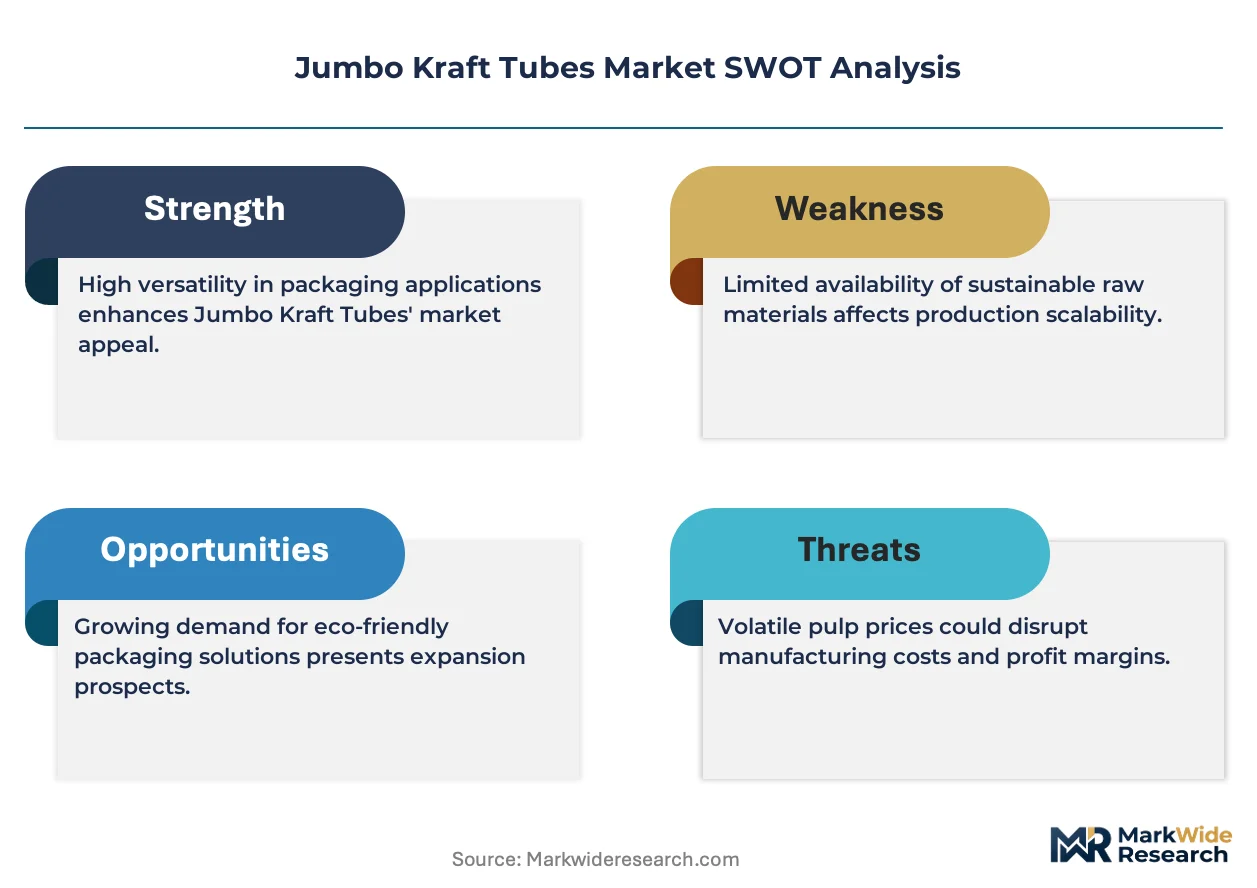
EU packaging waste regulations and FSC certification timelines are consolidating the Jumbo Kraft Tubes Market, eliminating merchant-fiber converters unable to absorb 12-18 month audit cycles. Scale advantages accrue to integrated operators with captive pulp supply and documented end-of-life pathways.
For Market Incumbents: Lock in fiber security through backward integration into southeastern US kraft pulping assets or long-term offtake agreements with Iberian recycled paperboard mills. Defend against polypropylene substitution in textile winding by embedding sub-millimeter tolerance capabilities into legacy spiral-winding lines. Prioritize REACH-compliant bio-based barrier R&D to maintain pharmaceutical specification access as fluorinated compound restrictions tighten. For New Entrants and Emerging Players: Begin with São Paulo film and nonwoven winding channels where domestic manufacturing gaps persist against imported tube supply. Target India's Maharashtra custom tube segment where BIS recycled content mandates disadvantage import-dependent distributors. Establish greenfield spiral-winding capacity with integrated digital printing for cosmetics short-run branding contracts. For Investors and Strategic Acquirers: The window for entry favors specialty barrier laminators with pharmaceutical-grade formulation pipelines and established EU regulatory compliance. Long-term viability hinges on consolidation of fragmented regional converters into multi-site certified networks. Watch FSC multi-site audit completion rates as the inflection signal for qualification access into EU-based brand owner supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulping | Captive fiber supply insulates margin stability from OCC price volatility in southeastern US markets. |
| Cellulose Nanofibril Barrier R&D | REACH-compliant formulations unlock pharmaceutical-grade specification access as fluorinated coatings phase out. |
| FSC Multi-Site Certification | Chain-of-custody documentation satisfies EU extended producer responsibility scheme compliance requirements. |
| Digital Printing Line Integration | Short-run custom branding capabilities capture premium cosmetics and specialty food segment contracts. |
| Direct Mill-to-Plant Logistics Programs | Integrated delivery displaces distributor inventory models near Georgia and Bavaria winding clusters. |
Research Methodology
Trade data from USITC and Eurostat, FSC certification registries, and EPA industrial effluent compliance filings formed the secondary backbone of this analysis. Primary interviews with paperboard mill procurement directors, spiral-winding plant managers, and pharmaceutical packaging specification engineers validated demand assumptions. Conversations with textile winding equipment OEMs and film producer buying desks informed tolerance and logistics requirements. Bottom-up capacity modeling across Germany, India, Brazil, and the United States was cross-checked against top-down demand aggregation by end-use segment.
Historical trendline analysis of recovered fiber price movements, spiral-winding capacity additions, and regulatory implementation timelines anchored the projection framework. Segmentation modeling spanned product type, material grade, end-user industry, and geographic production cluster dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution effects from polypropylene cores and plastic packaging displacement momentum. Industry-specific inputs included BIS packaging standard compliance thresholds, ANVISA pharmaceutical documentation requirements, and EU Green Deal extended producer responsibility scheme adoption rates.
Recovered fiber cost volatility, REACH Annex XVII barrier chemistry restrictions, and FSC audit timeline delays are the dominant revision risks to forecast assumptions. Regulatory acceleration or deceleration in EU packaging waste implementation would compress or extend competitive consolidation timelines. A small set of named triggers—OCC index movements, plasma treatment equipment lead times, and multi-site certification completion rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
Molded Fiber Trays Market
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
Europe Molded Pulp Packaging Market
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
Europe Molded Fiber Packaging Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Fibreglass Trays Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Europe Transfer Molded Pulp Packaging Market