
 Europe Transfer Molded Pulp Packaging Market | 2026-2036
Europe Transfer Molded Pulp Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Transfer Molded Pulp Packaging Market Analytics
Subscription-based packaging redesign services is consolidating how European converters monetize long-term customer relationships. Huhtamaki Oyj leverages its pan-European manufacturing footprint to anchor large-volume food service contracts. Brødrene Hartmann A/S dominates egg packaging while extending into industrial protective applications. James Cropper plc specializes in premium molded pulp using colored fibers and custom textures for luxury positioning.
Transfer molded pulp packaging forms three-dimensional fiber structures through heated mold pressing of aqueous pulp slurry, typically achieving wall thicknesses of 0.8 to 3.0 millimeters and edge radii under 2 millimeters for precise product nesting. The process employs vacuum-assisted dewatering and thermal bonding without synthetic adhesives, yielding compostable protective shells for fragile goods. Trays lead volume across the Europe transfer molded pulp packaging market due to standardized food service dimensions and automated filling compatibility. Food and beverage end users generate the deepest margin pools as brand owners fund premium fiber grades to meet plastic reduction pledges. Virgin pulp material commands price premiums in pharmaceutical and cosmetics segments where contamination thresholds remain stringent.
EMA packaging guidelines, EU Green Deal circular economy targets, and REACH chemical compliance frameworks collectively mandate fiber traceability and restrict per- and polyfluoroalkyl substance coatings in food contact materials. ECHA substance evaluation protocols now screen imported molded pulp for persistent organic pollutants, reshaping raw material sourcing decisions for converters serving pan-European brands. Stakeholders must monitor pending Packaging and Packaging Waste Regulation revisions that will recalibrate extended producer responsibility fees by material recyclability performance.
Market Dynamics
EU Green Deal mandates and F-Gas Regulation phase-outs are forcing converters to eliminate fluorinated coatings from food-contact molded pulp, triggering raw material substitution and capital redeployment across European manufacturing corridors.
Growth Catalysts
- EU Green Deal circular economy targets:Mandatory plastic reduction timelines in Germany, France, and the Netherlands accelerate fiber tray conversion in ready-meal and fresh produce categories.
- Trays:Standardized dimensions compatible with automated filling lines reduce switching costs for food service operators replacing expanded polystyrene.
- Pharmaceuticals:Virgin pulp demand rises as EMA packaging guidelines tighten contamination thresholds for secondary protective packaging.
Market Restraints
- Softwood pulp price volatility:Nordic pulp mill capacity constraints and energy cost spikes compress converter margins during peak demand windows.
- Barrier coating limitations:PFAS-free alternatives lack grease resistance parity, restricting adoption in high-fat food applications despite REACH restrictions.
- Capital intensity:Heated mold pressing equipment requires seven-figure euro outlays, concentrating production among established European converters.
Strategic Opportunities
- Industrial protective applications:Electronics and automotive sectors in Eastern Europe remain underpenetrated versus Western European food service saturation.
- Cosmetics premium positioning:France's luxury packaging corridor demands colored fiber and custom texture capabilities that command price premiums.
- REACH-compliant coating innovation:Bio-based barrier technologies eligible for ECHA green chemistry recognition open differentiated product lines.
Industry Challenges
- Tooling lead times:Precision mold fabrication for sub-2-millimeter edge radii extends new product development cycles beyond brand owner launch windows.
- Composting infrastructure gaps:Industrial composting facility availability varies across European member states, complicating end-of-life claims and consumer communication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Transfer Molded Pulp Packaging Market |
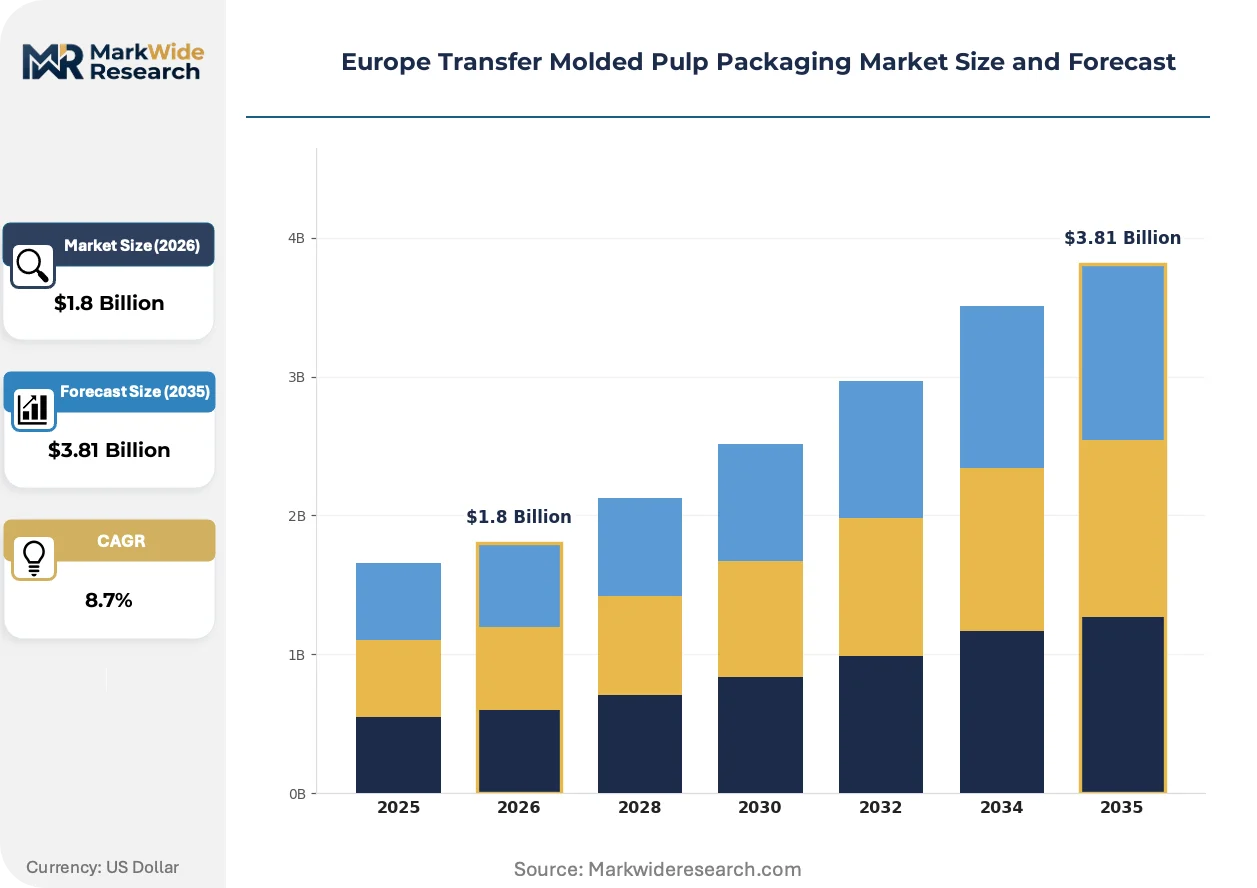
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Trays, Clamshells, Cups End User: Food & Beverage, Electronics, Cosmetics, Pharmaceuticals Material: Recycled Paper, Virgin Pulp, Composites, Biodegradable Plastics Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | James Cropper plc, KIEFEL GmbH, Brødrene Hartmann A/S, International Paper, Pulp-Tec Limited, Huhtamaki Oyj, PAPACKS Sales GmbH, Graphic Packaging International, LLC, Omni-Pac Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Transfer Molded Pulp Packaging Market Evolving Landscape
Barrier coating chemistry and mold precision engineering are converging to expand molded pulp from commodity egg cartons into performance-critical protective applications previously dominated by plastics and foams.
Precision thermoformed fiber molding is rewriting protective packaging economics. Wall thickness control down to 0.8 millimeters enables electronics manufacturers to specify molded pulp for component shipping trays. German automotive suppliers are qualifying these trays for precision parts logistics. The technology is compressing cost premiums versus expanded polypropylene to sub-15% at volume.
REACH substance evaluation protocols now screen imported molded pulp for persistent organic pollutants. ECHA enforcement actions against non-compliant Asian suppliers are reshaping raw material sourcing decisions. French and Dutch brand owners are accelerating fiber traceability certification to preempt supply disruption.
Subscription-based packaging redesign services are displacing transactional mold sales. European converters lock in multi-year relationships through continuous design iteration and volume commitment structures. This model concentrates in Germany's industrial packaging corridor where annual redesign cycles match automotive model year turnovers.
Europe Transfer Molded Pulp Packaging Market Segmentation
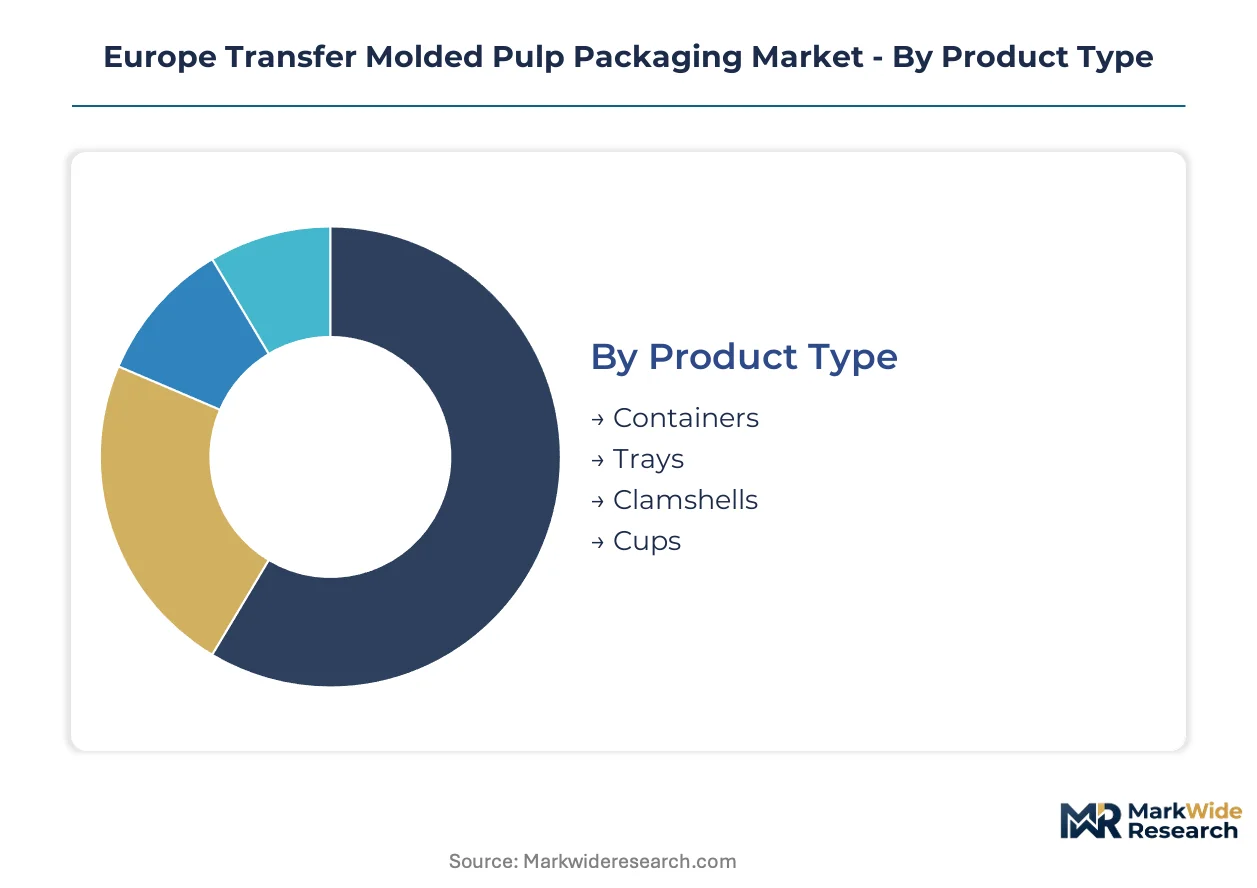
European converters engineer transfer molded pulp around precise dimensional tolerances and end-use contamination thresholds. Segmentation reveals how material purity, product geometry, and channel economics partition margin pools across Germany's industrial corridor and France's premium consumer sectors.
Product Type:
Heated mold pressing capacity concentrates among established European converters serving high-volume tray contracts, while precision thermoformed fiber equipment enables thinner-wall applications.
- Trays:Standardized dimensions compatible with automated filling lines dominate food service conversions from expanded polystyrene. German ready-meal producers and Dutch fresh produce distributors anchor volume demand as EU Green Deal plastic reduction timelines tighten.
- Containers:Three-dimensional fiber structures with 0.8 to 3.0 millimeter wall thickness protect fragile goods through vacuum-assisted dewatering and thermal bonding. Cosmetics brands in France specify these for luxury unboxing experiences without synthetic adhesives.
- Clamshells:Hinged fiber designs serve electronics and automotive component shipping in Eastern European manufacturing zones.
- Cups:Thin-wall fiber vessels compete in beverage service where barrier coating limitations restrict high-fat content applications.
Today's leader: Trays. Tomorrow's challenger: Containers.
End User:
Margin structures diverge sharply between commodity food service contracts and contamination-sensitive pharmaceutical specifications.
- Food & Beverage:Brand owners fund premium fiber grades to meet plastic reduction pledges across Germany, France, and the Netherlands. Automated filling compatibility and standardized dimensions reduce switching costs for operators replacing single-use plastic trays.
- Pharmaceuticals:EMA packaging guidelines tighten contamination thresholds for secondary protective packaging. Virgin pulp demand rises as traceability certification becomes mandatory under REACH substance evaluation protocols.
- Electronics:Precision thermoformed fiber molding enables 0.8-millimeter wall thickness for component shipping trays qualifying with German automotive suppliers.
- Cosmetics:France's luxury packaging corridor demands colored fiber and custom texture capabilities commanding price premiums.
Food & Beverage commands current volume. Pharmaceuticals offers the steepest expansion trajectory.
Material:
Raw material sourcing decisions reshape around ECHA enforcement actions and Nordic pulp mill capacity constraints.
- Virgin Pulp:Pharmaceutical and cosmetics segments pay contamination-threshold premiums. ECHA screening for persistent organic pollutants accelerates fiber traceability certification among French and Dutch brand owners.
- Recycled Paper:Standard food service trays leverage cost advantages where grease resistance requirements remain moderate. Softwood pulp price volatility and energy cost spikes compress converter margins during peak demand windows.
- Composites:Hybrid fiber formulations attempt barrier performance without PFAS coatings restricted under REACH.
- Biodegradable Plastics:Limited adoption where composting infrastructure gaps complicate end-of-life claims across European member states.
Virgin pulp dominates premium positioning. Recycled paper faces margin pressure from input cost volatility.
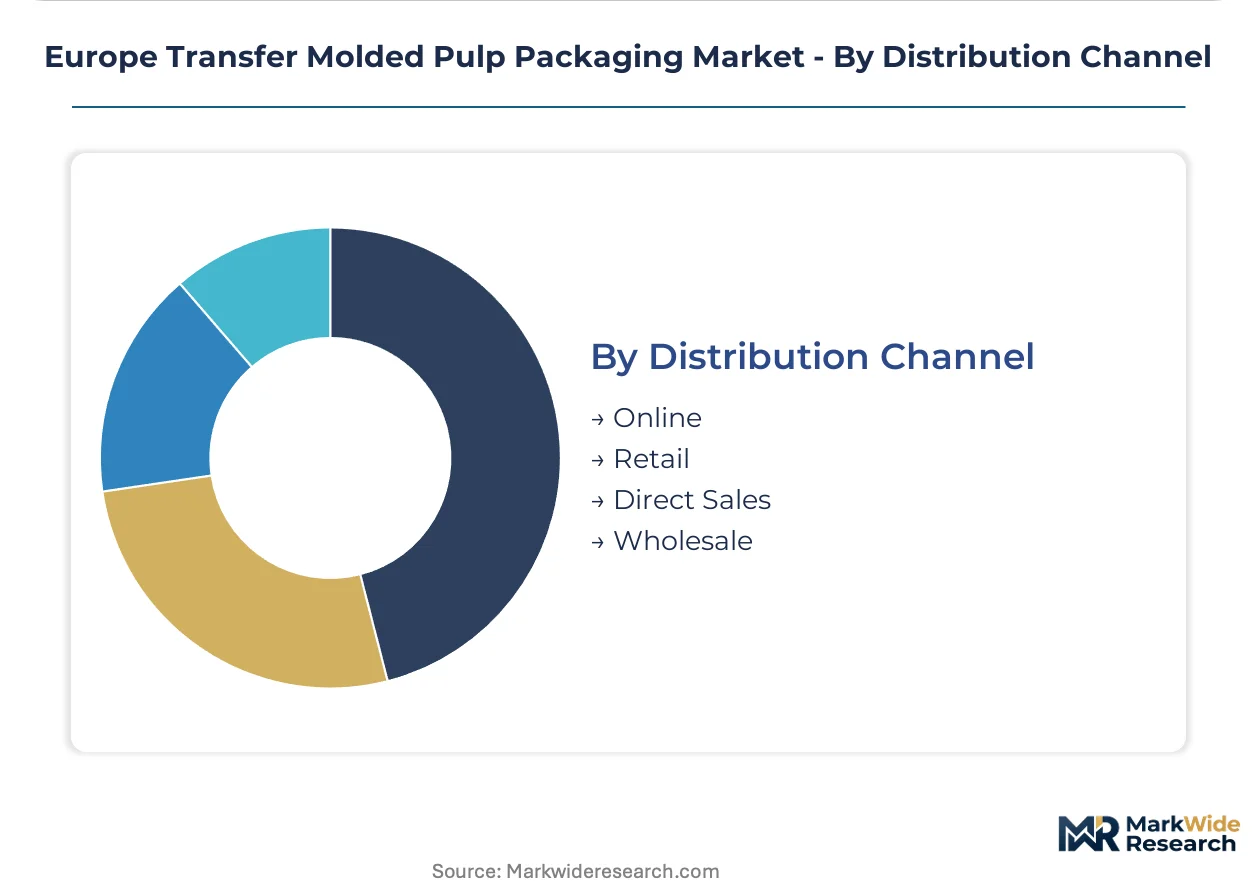
Distribution Channel:
Subscription-based packaging redesign services are displacing transactional mold sales through multi-year volume commitment structures.
- Direct Sales:European converters lock in automotive and electronics manufacturers through continuous design iteration matching model year turnovers. Germany's industrial packaging corridor concentrates these annual redesign cycles.
- Wholesale:Pan-European food service distributors aggregate fragmented ready-meal and fresh produce demand.
- Retail:Limited penetration for standardized molded pulp given customization requirements for premium positioning.
- Online:Emerging channel for sample and short-run orders where tooling lead times for precision molds extend beyond brand owner launch windows.
Direct Sales anchors relationship value. Wholesale captures fragmented volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany generates deeper volume pools than France, yet French converters command steeper price premiums through luxury positioning capabilities. This divergence shapes how transfer molded pulp packaging penetrates food service versus cosmetics end uses across the continent.
Germany
Ready-meal producers and automotive suppliers anchor tray demand in Germany's industrial packaging corridor. The EU Green Deal's plastic reduction timelines accelerate fiber conversion in fresh produce distribution. Bavaria's manufacturing clusters host precision thermoforming equipment serving component shipping contracts.
France
Cosmetics brands in France's luxury packaging corridor specify colored fibers and custom textures for premium unboxing experiences. REACH substance evaluation protocols screen imported molded pulp for persistent organic pollutants. The Île-de-France region concentrates design-intensive converter operations serving pan-European brand owners.
Netherlands
Dutch fresh produce distributors drive standardized tray adoption compatible with automated filling infrastructure. ECHA enforcement actions against non-compliant Asian suppliers reshape sourcing decisions among Rotterdam-based logistics operators. The Randstad area aggregates pan-European distribution hub demand.
United Kingdom
EMA packaging guidelines tighten contamination thresholds for pharmaceutical secondary packaging in the UK market. Virgin pulp traceability certification becomes mandatory under post-Brexit regulatory alignment pressures. The Midlands region hosts specialty converters serving medical device manufacturers.
Poland
Eastern European electronics and automotive sectors remain underpenetrated versus Western European food service saturation. F-Gas Regulation phase-outs create openings for fiber-based protective packaging in Warsaw manufacturing zones. Polish converters capture overflow capacity from German industrial corridor demand spikes.
Europe Transfer Molded Pulp Packaging Market Competitive Landscape
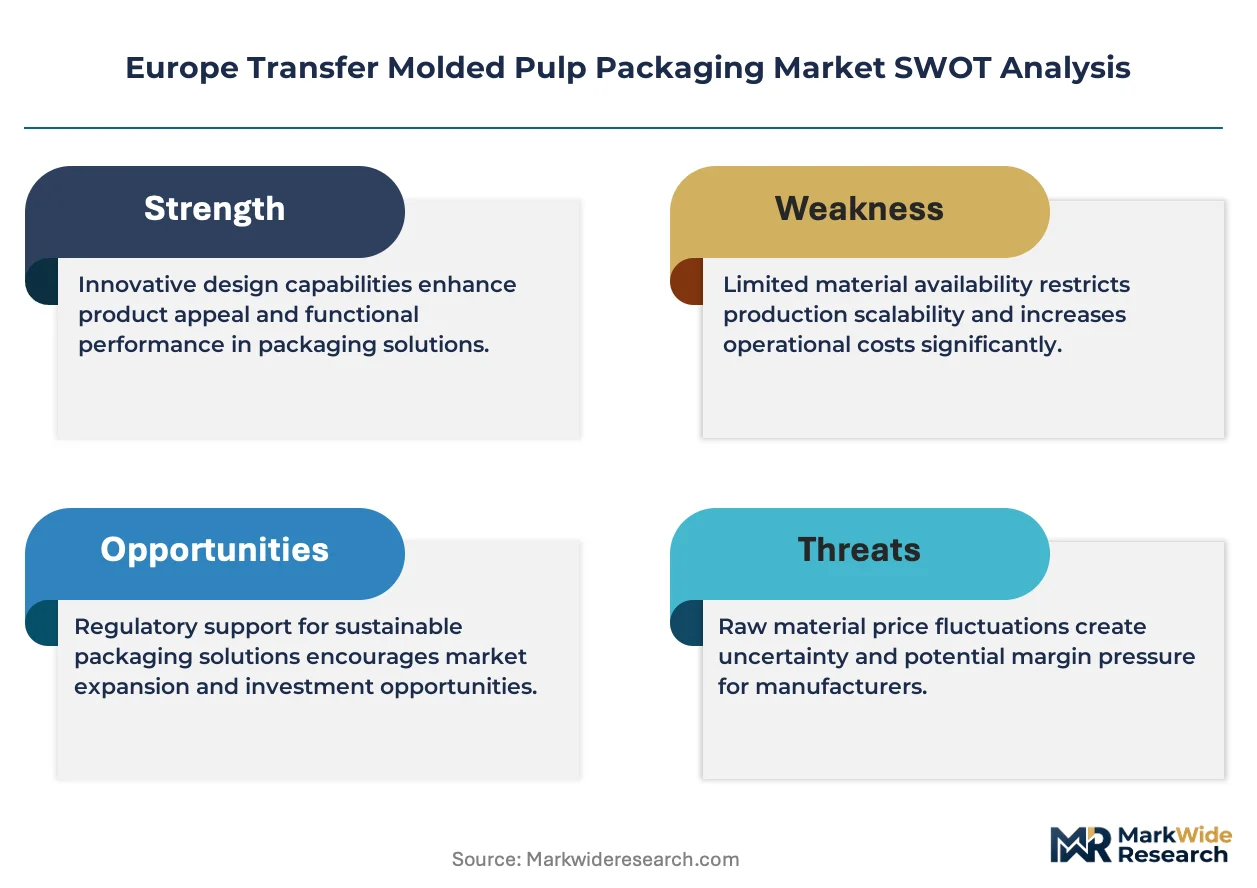
Branded specialists and contract manufacturers split share differently across segments, with food service consolidation contrasting industrial fragmentation. Three tiers emerge: pan-European volume leaders, national specialists with premium capabilities, and regional fabricators serving niche geometries. Strategic moves concentrate on capacity expansion in Eastern European manufacturing zones and subscription-based redesign services locking in multi-year automotive contracts.
Among Nordic-based converters, Brødrene Hartmann A/S exemplifies the egg packaging specialist archetype extending into industrial protective applications. Huhtamaki Oyj anchors the pan-European volume tier through manufacturing footprint scale. James Cropper plc occupies the premium positioning vector with colored fiber and custom texture capabilities serving French luxury cosmetics demand.
| Leading Market Players |
|---|
| James Cropper plc |
| KIEFEL GmbH |
| Brødrene Hartmann A/S |
| International Paper |
| Pulp-Tec Limited |
| Huhtamaki Oyj |
| PAPACKS Sales GmbH |
| Graphic Packaging International, LLC |
| Omni-Pac Group |
| Others |
Value Network & Pricing Analysis
EU Green Deal plastic reduction mandates in Germany and France are forcing food service operators to specify fiber-based alternatives, compelling converters to absorb softwood pulp volatility and recalibrate contract structures around long-term volume commitments rather than spot pricing.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors for standardized tray contracts. Three-tier pricing structure across premium, standard, and economy levels separates virgin pulp pharmaceutical specifications from recycled paper food service grades and composite industrial applications. Cost compression in recycled paper tiers is intensifying because Nordic energy spikes and pulp mill constraints feed directly into converter margins. Food service distributors exhibit highest price sensitivity, while cosmetics brands in France show lowest sensitivity due to unboxing experience premiums.
Supply Chain Analysis
Precision thermoforming equipment operators in Bavaria, Warsaw manufacturing zones, and the Randstad area face tightening technical workforce availability as mold engineering specialization concentrates among aging European workforces. Raw material sourcing draws from Nordic softwood pulp mills, recycled paper streams from Dutch distribution hubs, and bio-based barrier chemical suppliers in Germany. Single-source vulnerability runs through heated mold pressing equipment fabricators in Southern Germany. Distribution runs through direct sales relationships locking in automotive contracts and wholesale channels aggregating fragmented food service demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities between Western European regulatory stringency and Eastern European manufacturing cost structures define this market, with F-Gas Regulation enforcement gaps in Poland creating temporary cost advantages for fiber-based protective packaging.
For Market Incumbents: Deepen backward integration into virgin pulp traceability certification to preempt ECHA enforcement disruptions. Anchor capacity expansion in Warsaw manufacturing zones to capture overflow demand from Germany's industrial corridor while PFAS-free coating R&D investment defends margin position against barrier performance gaps in high-fat food applications. For New Entrants and Emerging Players: EU Green Deal circular economy targets in the Netherlands open a window for subscription-based packaging redesign services displacing transactional mold sales. Target Eastern European electronics and automotive component shipping where precision thermoformed fiber remains underpenetrated versus Western food service saturation. Lead with rapid prototyping capabilities compressing tooling lead times for sub-2-millimeter edge radii specifications. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier converters possessing colored fiber and custom texture capabilities serving French luxury cosmetics demand. Five-to-ten year viability hinges on REACH-compliant coating innovation eligibility for ECHA green chemistry recognition. Monitor PFAS-free barrier technology breakthroughs as the inflection signal triggering accelerated food service conversion and premium pricing capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Virgin Pulp Certification | ECHA screening protocols in France and Germany make traceability a supply prerequisite. |
| Capacity Expansion in Eastern European Manufacturing Zones | Polish and Czech locations capture German industrial corridor demand overflow at lower cost bases. |
| REACH-Compliant Coating R&D Investment | Bio-based barrier technologies unlock high-fat food applications currently restricted by PFAS limitations. |
| Subscription-Based Packaging Redesign Services | Multi-year volume commitments with automotive suppliers displace transactional mold sales in Bavaria. |
| Precision Thermoforming Equipment Deployment | 0.8-millimeter wall thickness capabilities qualify molded pulp for German automotive component logistics. |
Research Methodology
Multiple input streams — converter production data, pulp mill capacity disclosures, and brand owner procurement specifications — were reconciled through bottom-up and top-down triangulation. Primary interviews with packaging engineers at German automotive suppliers, sustainability officers at French cosmetics brands, procurement leads at Dutch fresh produce distributors, and regulatory affairs specialists at ECHA-screened converters were cross-validated against secondary sources including EU Green Deal implementation documents, REACH substance evaluation protocols, F-Gas Regulation phase-out schedules, and Nordic pulp mill energy cost filings.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include product geometry, material purity tier, end-use contamination sensitivity, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of fiber conversion rates against plastic reduction pledge timelines. Industry-specific forecast inputs incorporated EMA packaging guideline revision trajectories and precision thermoforming equipment deployment rates in Bavarian manufacturing clusters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction enforcement or Nordic pulp mill capacity disruptions. Forecasts reflect documented assumptions regarding EU Green Deal timeline adherence and composting infrastructure rollout consistency across member states. Material deviation in ECHA green chemistry recognition criteria or F-Gas Regulation phase-out acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Europe Molded Pulp Packaging Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
Global Molded Pulp Packaging Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
Fibreglass Trays Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Cup Market