
 Molded Fiber Packaging Market | 2026-2036
Molded Fiber Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Fiber Packaging Market Intelligence
Chinese molded fiber capacity is hardening around bagasse and bamboo pulp supply chains. Huhtamaki Oyj leverages its European thermoforming infrastructure to extend molded fiber capabilities across foodservice accounts. Stora Enso anchors Nordic demand through captive pulp integration and forest certification programs. Brødrene Hartmann A/S specializes in egg packaging automation while competing aggressively in industrial protective formats.
Molded fiber packaging consists of pressed pulp fibers—typically recycled paperboard, agricultural residues, or virgin wood pulp—formed under heat and pressure into dimensionally stable containers, trays, or protective shapes with defined wall thickness and moisture resistance ratings. The material serves primarily as a structural substitute for expanded polystyrene and rigid plastic in applications requiring impact absorption, stackability, and compostable end-of-life pathways. Trays dominate foodservice applications where grease resistance and freezer-to-oven performance determine specification tiers, while clamshells capture premium produce retail channels demanding optical clarity substitutes and venting precision. Protective packaging leads industrial growth as electronics manufacturers abandon plastic cushioning under extended producer responsibility frameworks.
EU packaging waste regulations and the F-Gas Regulation indirectly strengthen molded fiber competitiveness by raising compliance costs for synthetic alternatives, while FDA food contact substance notifications govern pulp chemistry and barrier coatings in the United States. China's GB standards for food packaging materials and dual carbon goals are redirecting domestic capacity toward agricultural fiber feedstocks. Stakeholders must monitor how cellulose nanofiber barrier technologies evolve against bioplastic film laminations in premium shelf-life applications.
Market Dynamics
Single-use plastic bans across multiple jurisdictions are compressing substitution timelines for foodservice operators, forcing rapid qualification of molded fiber alternatives in tray and clamshell formats previously dominated by polystyrene and PET structures.
Growth Catalysts
- State-level plastic bans:California, New York, and Washington have enacted prohibitions on expanded polystyrene food containers, creating immediate demand pull for molded fiber replacements in quick-service restaurant supply chains.
- F-Gas Regulation:The EU measure restricting hydrofluorocarbon use in foam production is elevating comparative cost competitiveness of pulp-based protective formats for temperature-sensitive electronics shipments.
- Bagasse supply chain maturation:Chinese processors are securing multi-year agricultural residue contracts with sugarcane mill operators, stabilizing fiber input costs for export-grade molded pulp production.
Market Restraints
- Barrier coating cost volatility:PLA and bio-PET film laminations required for high-moisture food applications carry price premiums that compress margins in contract foodservice accounts.
- Equipment supply concentration:Thermoforming and pressing machinery for high-tolerance industrial formats remains concentrated among German and Italian original equipment manufacturers, creating capex bottlenecks for new entrants.
- Performance ceiling in frozen distribution:Current cellulose fiber structures exhibit moisture weakening below minus twenty degrees Celsius, limiting penetration in deep-cold supply chains for seafood and ice cream.
Strategic Opportunities
- India foodservice underpenetration:Quick-service restaurant chains in Mumbai and Bangalore are initiating plastic-to-fiber transitions ahead of anticipated FSSAI packaging mandates, creating first-mover positioning windows.
- Cellulose nanofiber convergence:Integration of nanocellulose barriers with conventional molded fiber substrates promises grease resistance without petroleum-derived coatings in premium ready-meal segments.
- Extended producer responsibility frameworks:France's AGEC law and similar measures across the EU are assigning end-of-life cost accountability to brand owners, redirecting specification decisions toward compostable pulp formats.
Industry Challenges
- Automation engineering scarcity:Molded fiber production requires process engineers fluent in both pulp rheology and precision thermoforming, a skill intersection concentrated among Nordic and German technical specialists.
- FDA notification timelines:Food contact substance approvals for novel barrier chemistries routinely extend eighteen to twenty-four months, delaying product launches for US-market-focused manufacturers.
- Legacy plastics integration:Foodservice operators running hybrid packaging lines face changeover inefficiencies and contamination risks when alternating between synthetic and fiber-based formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Fiber Packaging Market |
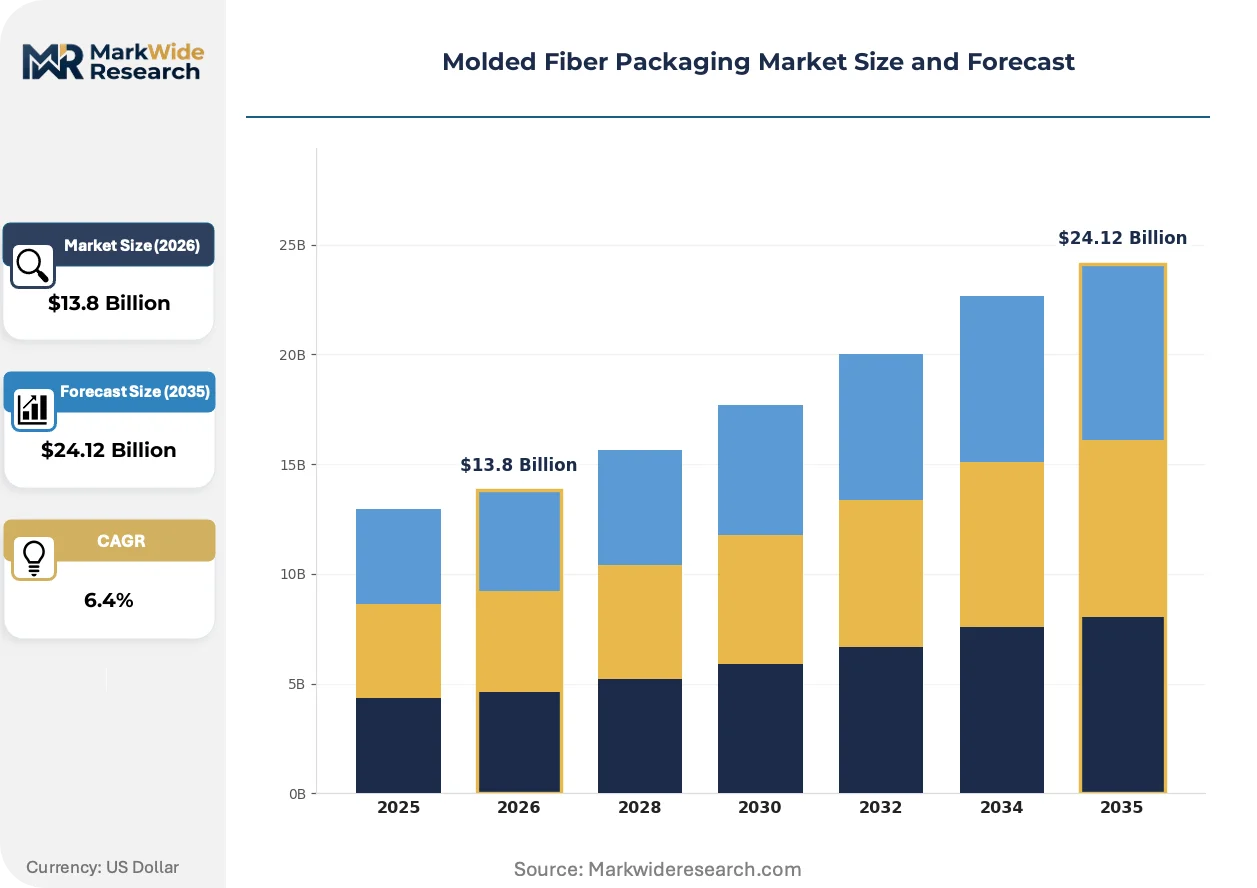
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trays, Clamshells, Containers, Inserts End User: Food & Beverage, Electronics, Personal Care, Pharmaceuticals Form: Rigid, Semi-Rigid, Flexible, Custom Application: Transit Packaging, Retail Packaging, Protective Packaging, Industrial Packaging |
| Companies Covered | Pactiv Evergreen Inc., Genpak LLC, Huhtamaki Oyj, Stora Enso, UFP Technologies Inc., Brødrene Hartmann A/S, CKF Inc., Amcor plc, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Fiber Packaging Market Strategic Shifts & Innovations
Barrier technology advancement and regulatory compression are restructuring competitive capability requirements, separating operators with in-house coating development from commodity tray producers.
Dry-molded fiber processing is electrifying capital allocation patterns across packaging boardrooms. The technology eliminates water-intensive slurry preparation, cutting energy consumption and wastewater treatment burdens. Electronics manufacturers in South Korea and Taiwan are accelerating qualification timelines for protective formats produced through this method. The process is electrifying investment prioritization, redirecting engineering resources from incremental thermoforming improvements toward waterless fiber platforms.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorochemical grease barriers from EU food contact applications. Industrial consequence includes forced reformulation of premium molded fiber trays for ready-meal and bakery segments. German and French converters are responding with accelerated testing of cellulose nanofiber and bio-wax alternatives, compressing typical eighteen-month qualification cycles to nine months.
Direct sourcing contracts between agricultural processors and molded fiber manufacturers are displacing spot-market pulp purchasing in cost-sensitive tray segments. Quick-service restaurant chains in the United States are consolidating supplier relationships to capture volume pricing and traceability documentation. This pattern is most visible in the Southeast, where bagasse supply agreements with Louisiana and Florida sugarcane operators are securing multi-year cost positions against recycled pulp volatility.
Molded Fiber Packaging Market Segmentation
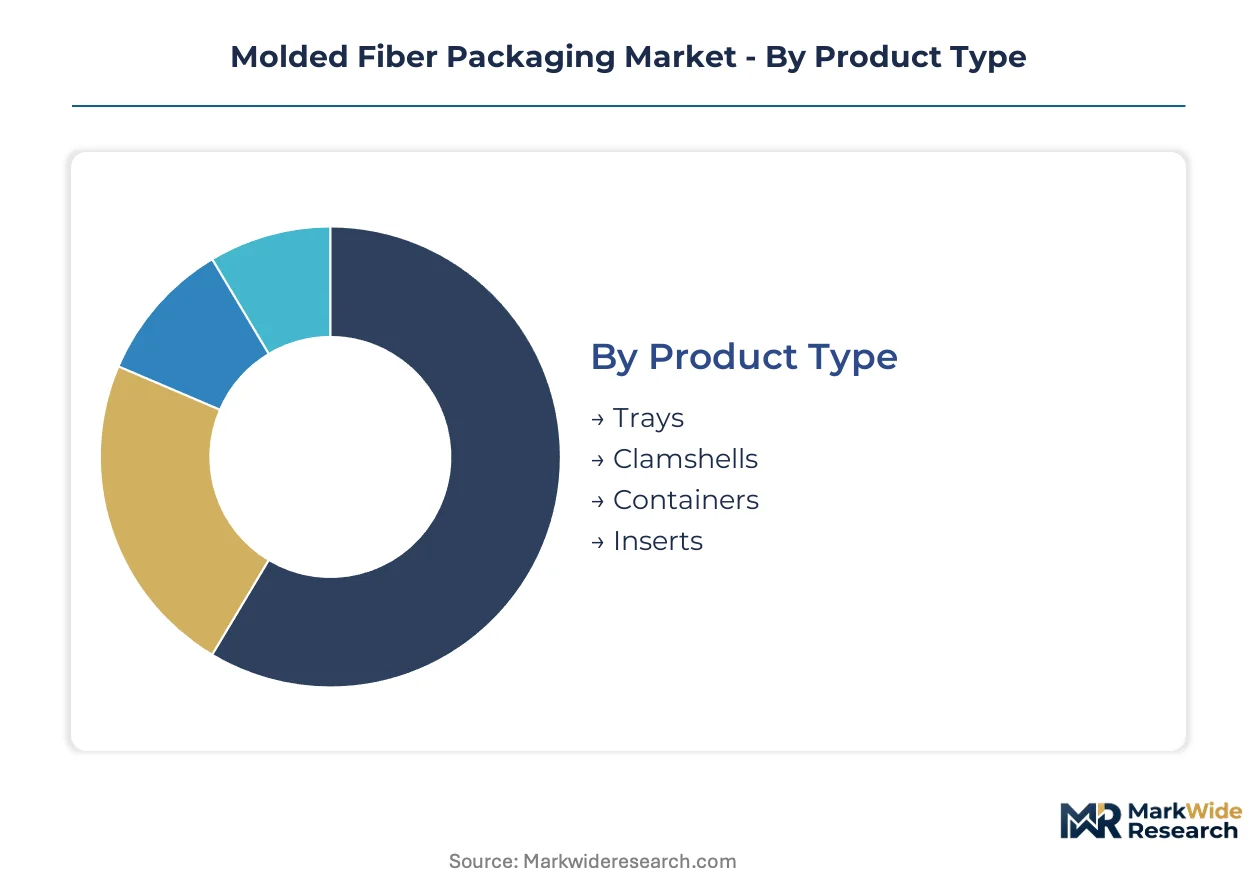
Molded fiber packaging segments diverge sharply in tooling requirements and barrier specifications. Foodservice operators demand grease-resistant coatings that pharmaceutical shippers rarely need. Electronics manufacturers prioritize dimensional tolerance that agricultural produce distributors dismiss.
Product Type:
Capital intensity peaks in formats requiring precision thermoforming dies and multi-cavity tooling.
- Trays:Pressed pulp structures with defined wall thickness and stacking lugs serve quick-service restaurant chains and ready-meal distributors. California's state-level polystyrene bans have compressed substitution timelines, forcing rapid qualification of fiber alternatives in freezer-to-oven specifications.
- Clamshells:Hinged-lid formats with integral locking tabs replicate rigid plastic functionality for premium produce retail. Venting precision and optical clarity substitutes determine specification tiers in channels previously dominated by PET structures.
- Containers:Deep-drawn formats with reinforced rims capture soup and prepared food applications.
- Inserts:Nestable protective shapes cushion electronics and glassware in transit.
Most installed capacity flows through Trays. Expansion is steepest in Clamshells.
End User:
Customer procurement patterns split between contract foodservice accounts with annual volume commitments and industrial protective formats purchased on project cycles.
- Food & Beverage:Quick-service restaurants, bakery chains, and meal-kit distributors specify molded fiber for grease resistance and compostable end-of-life pathways. FDA food contact substance notifications govern pulp chemistry and barrier coatings in this segment.
- Electronics:Smartphone and semiconductor manufacturers require high-tolerance protective formats with static-dissipative properties. South Korean and Taiwanese OEMs are accelerating qualification timelines for dry-molded fiber alternatives.
- Personal Care:Cosmetic and skincare brands specify molded fiber for unboxing experience and sustainability credentials.
- Pharmaceuticals:Temperature-sensitive biologics shippers adopt pulp-based cushioning under extended producer responsibility frameworks.
Food & Beverage commands the largest volume share. Electronics is climbing the fastest as EPR frameworks tighten.
Form:
Structural rigidity determines stacking height, compression strength, and automation compatibility on filling lines.
- Rigid:High-density pressed pulp with defined crush resistance serves automated palletization and retail display requirements. German automotive parts shippers specify these formats for engine component protection.
- Semi-Rigid:Moderate-density structures balance protection with nesting efficiency for egg and produce applications. European Union packaging waste regulations are accelerating material innovation in this specification tier.
- Flexible:Low-density molded pulp wraps and pads conform to irregular geometries.
- Custom:Engineered formats with part-specific cavities serve high-value industrial components.
Rigid formats absorb the majority of thermoforming investment. Custom formats are expanding most quickly in electronics protective applications.
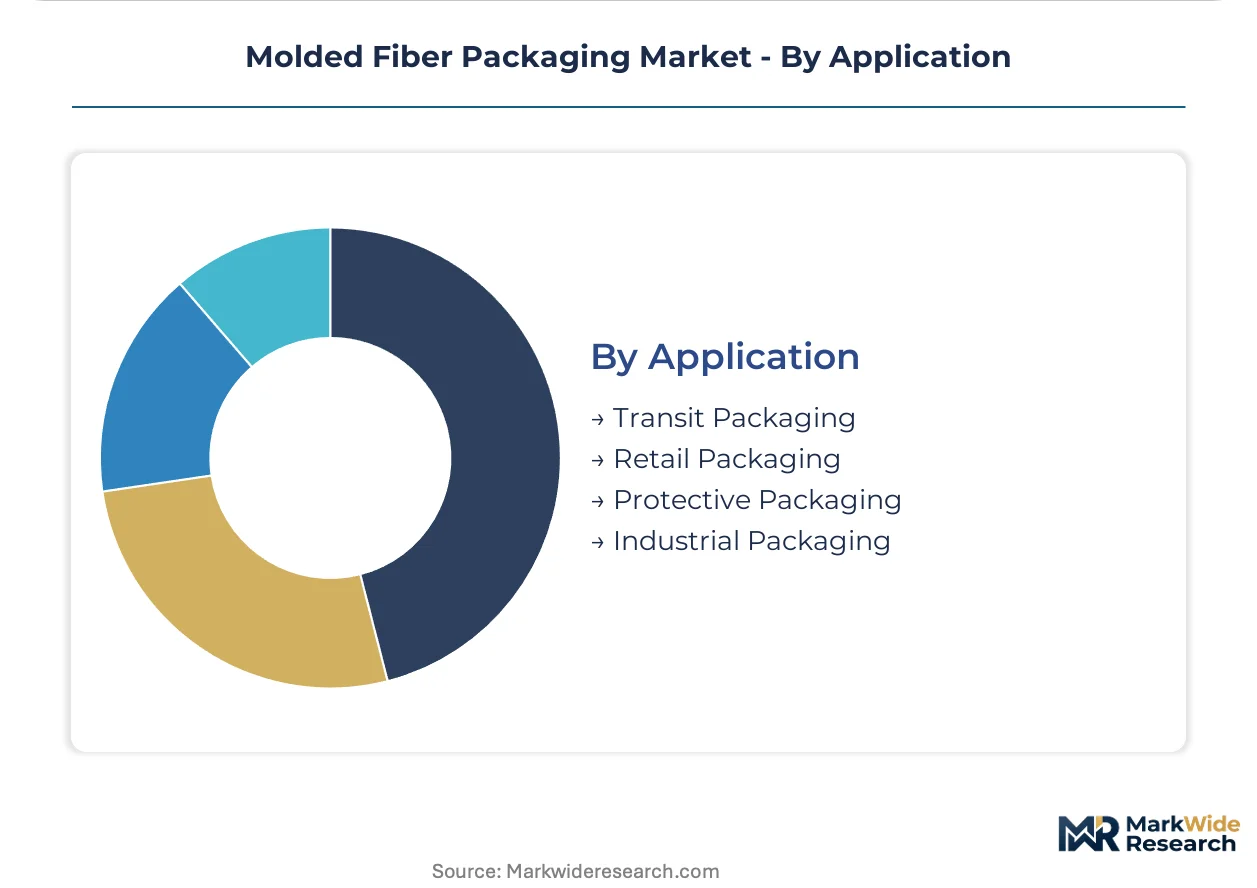
Application:
End-use performance requirements dictate fiber blend selection, coating chemistry, and moisture resistance ratings.
- Transit Packaging:Corrugated-compatible trays and corner posts protect goods through distribution networks. Bagasse supply chain maturation in China is stabilizing fiber input costs for export-grade production.
- Retail Packaging:Consumer-facing formats with print-ready surfaces serve club store and supermarket channels. Quick-service restaurant chains in the United States are consolidating supplier relationships to capture volume pricing.
- Protective Packaging:Engineered cushions and inserts absorb impact for fragile goods. REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorochemical barriers from EU food contact applications.
- Industrial Packaging:Heavy-duty formats for machinery and automotive components require high-tolerance pressing capabilities.
Transit Packaging channels the most tonnage. Protective Packaging is gaining share fastest as electronics manufacturers abandon plastic cushioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting molded fiber capacity toward jurisdictions with streamlined compliance pathways and abundant agricultural residue feedstocks.
United States
California, New York, and Washington state-level bans on expanded polystyrene food containers are forcing quick-service restaurant chains into rapid molded fiber qualification cycles. FDA food contact substance notifications govern pulp chemistry and barrier coatings for domestic foodservice applications. The Southeast corridor from Louisiana to Florida is securing multi-year bagasse supply agreements with sugarcane operators.
Germany
Automotive parts shippers in Baden-Württemberg and Bavaria specify high-tolerance rigid formats for engine component protection under extended producer responsibility frameworks. The F-Gas Regulation elevates pulp-based protective formats against synthetic foam alternatives. The industrial packaging corridor between Stuttgart and Munich concentrates thermoforming infrastructure for precision pressing capabilities.
China
Processors are hardening capacity around bagasse and bamboo pulp supply chains under GB standards for food packaging materials and dual carbon goals. The Yangtze River Delta and Pearl River Delta clusters are securing multi-year agricultural residue contracts with sugarcane mill operators. Export-grade production is stabilizing fiber input costs through direct sourcing arrangements.
India
Quick-service restaurant chains in Mumbai and Bangalore are initiating plastic-to-fiber transitions ahead of anticipated FSSAI packaging mandates. The country's national food safety regulator is expected to tighten packaging material standards. Maharashtra and Karnataka are emerging as first-mover positioning windows for contract foodservice accounts.
France
The AGEC law assigns end-of-life cost accountability to brand owners, redirecting specification decisions toward compostable pulp formats in ready-meal and bakery segments. REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorochemical grease barriers from food contact applications. The Île-de-France region is compressing typical qualification cycles through accelerated cellulose nanofiber testing.
Molded Fiber Packaging Market Key Industry Players
Nordic producers anchor one tier through captive pulp integration and forest certification programs; Asian specialists hold cost positions via agricultural residue supply chains and export-focused capacity. The vendor base splits between integrated pulp-to-package operators and independent converters purchasing market pulp. Three archetypes dominate: vertically integrated forest products groups, agricultural fiber specialists, and precision thermoforming engineering houses. Capacity expansion and barrier technology licensing represent the dominant competitive vectors.
Within the integrated forest products tier, Stora Enso and Huhtamaki Oyj exemplify Nordic operators leveraging in-house pulp supply and established thermoforming infrastructure. Brødrene Hartmann A/S occupies a specialist position with concentrated expertise in automated egg packaging formats while competing in industrial protective applications. These three entities represent distinct strategic postures: captive raw material security, European foodservice platform extension, and automation-driven segment specialization.
| Leading Market Players |
|---|
| Pactiv Evergreen Inc. |
| Genpak LLC |
| Huhtamaki Oyj |
| Stora Enso |
| UFP Technologies Inc. |
| Brødrene Hartmann A/S |
| CKF Inc. |
| Amcor plc |
| Sonoco Products Company |
| Others |
Cost & Logistics Intelligence
Quick-service restaurant procurement consolidation across California, New York, and Washington is compressing supplier margins through multi-year volume contracts that trade price certainty for market share capture in polystyrene-replacement timelines.
Pricing Analysis
Distributor margins in foodservice channels absorb the steepest compression as operators consolidate supplier relationships to secure traceability documentation and volume pricing. Pricing stratifies across premium, standard, and economy tiers based on barrier coating chemistry and freezer-to-oven performance certification. Cost compression in standard-grade trays is intensifying because bagasse supply agreements in Louisiana and Florida are stabilizing fiber input costs. Contract foodservice accounts exhibit highest price sensitivity, while pharmaceutical and electronics shippers prioritize dimensional tolerance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs and South Korean electronics manufacturers are forcing molders to qualify secondary pressing capacity across multiple jurisdictions. Fiber supply concentrates in China, Germany, and the United States, with pulp processing drawing from recycled paperboard, bagasse, and bamboo feedstocks. Single-source vulnerability persists in thermoforming machinery, where German and Italian OEMs control precision pressing equipment. Distribution runs through direct sourcing contracts between agricultural processors and molded fiber manufacturers, displacing spot-market pulp purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molded fiber packaging has entered a late-cycle quality phase where dry-molded fiber processing and cellulose nanofiber barrier specifications are separating premium suppliers from commodity tray producers.
For Market Incumbents: Anticipate margin erosion in standard-grade foodservice trays as Chinese processors with captive bagasse supply chains enter export markets. Defend position through backward integration into agricultural residue contracts in the US Southeast and accelerated FDA notification timelines for novel barrier chemistries. Certification investment in cellulose nanofiber coatings represents the critical lever for premium ready-meal segment retention. For New Entrants and Emerging Players: The premium-economy price gap in industrial protective formats offers white-space entry for precision thermoforming specialists. Target electronics protective applications in South Korea and Taiwan where dry-molded fiber qualification timelines are compressing. Pursue direct OEM engagement bypassing distributor layers, leveraging EPR framework compliance as the primary go-to-market wedge. For Investors and Strategic Acquirers: Integrated forest products groups are the most active acquirer in this space, seeking barrier technology licensing positions and regional thermoforming capacity. Long-term viability rests on coating chemistry differentiation rather than commodity pulp processing scale. Watch cellulose nanofiber barrier adoption rates in EU ready-meal segments as the inflection signal for premium tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Technology Licensing | Cellulose nanofiber coating patents separate premium suppliers from commodity producers in EU food contact applications. |
| Agricultural Residue Contracting | Multi-year bagasse agreements with Louisiana sugarcane operators secure cost positions against recycled pulp volatility. |
| Dry-Molded Fiber Capacity Buildout | Waterless processing platforms cut energy consumption and attract electronics manufacturers in South Korea and Taiwan. |
| Regulatory Pre-Qualification Investment | FDA food contact substance notification acceleration delays competitor entry by eighteen to twenty-four months in US markets. |
| EPR Framework Compliance Positioning | France's AGEC law redirects brand owner specifications toward compostable pulp formats with traceable end-of-life pathways. |
Research Approach
Multiple input streams — pulp mill operators, quick-service restaurant procurement directors, thermoforming equipment manufacturers, and barrier coating chemists — were reconciled against trade flow data from customs authorities and forest certification databases. Primary interviews with plant managers at molded fiber production facilities, category buyers at foodservice distributors, and technical R&D directors at coating suppliers were cross-validated with secondary sources including FDA food contact substance notifications, EU REACH restriction updates, and GB standards documentation. Bottom-up capacity assessments and top-down demand modeling were triangulated to produce volume and value estimates.
Historical shipment data from pulp processing associations were cross-referenced against panel input from packaging procurement executives to construct the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end-use vertical, structural rigidity tier, and regional regulatory cluster. CAGRs were derived from regression analysis of substitution timelines against state-level plastic ban implementation schedules and EPR framework adoption curves. Forecast inputs incorporated bagasse supply contract maturation patterns and cellulose nanofiber barrier qualification velocity.
Caveats apply where FDA notification delays, REACH restriction scope expansions, or frozen distribution performance breakthroughs could materially shift the outlook. Deviation in dual-carbon policy enforcement intensity in China would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
Molded Fiber Cup Market
Fiber-Based Packaging
Molded Fiber Containers Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Europe Transfer Molded Pulp Packaging Market
Fiber-Based Packaging
Global Molded Pulp Packaging Market
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
Global Molded Fiber Bowls Market
Fiber-Based Packaging
Europe Molded Fiber Packaging Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market